
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Laboratory Benchtop Automation Market Size 2024 | USD 1325 million |
| Laboratory Benchtop Automation Market, CAGR | 5.5% |
| Laboratory Benchtop Automation Market Size 2032 | USD 2033.45 million |
Market Overview:
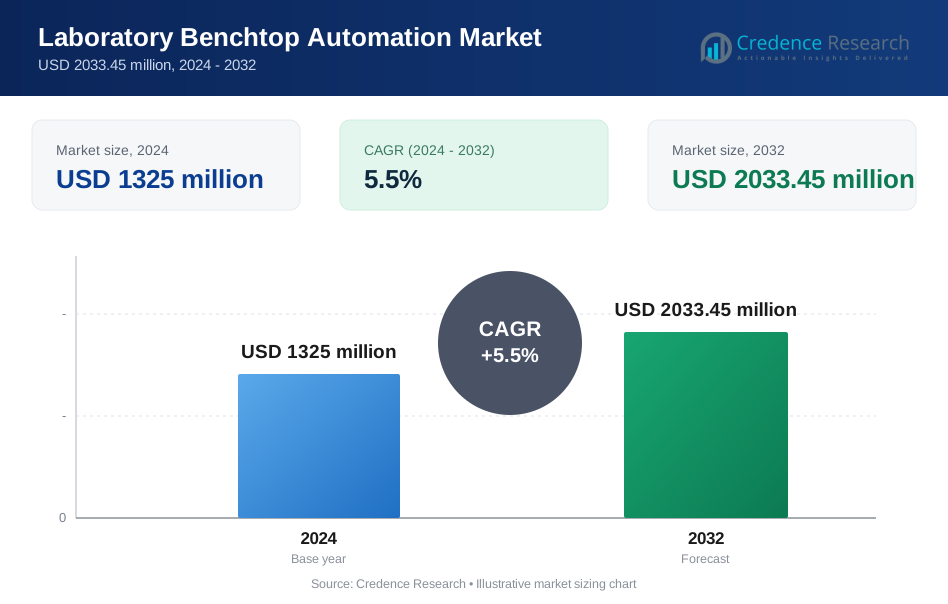
The Laboratory Benchtop Automation Market is projected to grow from USD 1325 million in 2024 to an estimated USD 2033.45 million by 2032, with a compound annual growth rate (CAGR) of 5.5% from 2024 to 2032.
Key drivers of the market include the increasing demand for high-throughput screening and testing in diagnostic labs and research centers, coupled with the growing emphasis on personalized medicine and drug discovery. The integration of artificial intelligence (AI) and machine learning (ML) into laboratory automation platforms enhances data accuracy, facilitates complex analyses, and optimizes operational efficiency. Additionally, advancements in miniaturization and modular designs are making benchtop automation solutions more accessible to small and medium-sized laboratories, broadening the market’s customer base. Regulatory mandates for precise testing protocols in pharmaceutical and clinical applications further underscore the importance of automated solutions in ensuring compliance and quality control.
Regionally, North America dominates the market, accounting for the largest share in 2024 due to its advanced healthcare infrastructure, robust research initiatives, and high adoption of cutting-edge technologies. Europe follows closely, driven by strong government support for research and development and a focus on laboratory modernization. The Asia-Pacific region is anticipated to witness the fastest growth, supported by rapid industrialization, increasing healthcare expenditure, and expanding biopharma activities in countries like China and India. Latin America and the Middle East & Africa are also showing steady progress, fueled by improving laboratory infrastructure and rising awareness about automation benefits. These regional dynamics highlight the global potential of laboratory benchtop automation to transform research and diagnostic workflows across diverse sectors.
Market Insights:
- The laboratory benchtop automation market is set to grow from USD 1325 million in 2024 to USD 2033.45 million by 2032, achieving a CAGR of 5.5%, driven by technological advancements and increasing demand for high-throughput screening.
- Adoption of benchtop automation is rising due to its ability to streamline workflows, enhance accuracy, and support complex tasks, particularly in personalized medicine and drug discovery.
- Integration of technologies like artificial intelligence, machine learning, and robotics is optimizing efficiency, enabling real-time data analysis, and reducing manual errors in laboratory operations.
- North America dominates the market due to its advanced healthcare infrastructure, strong research initiatives, and widespread use of modern automation solutions.
- Regulatory compliance requirements in pharmaceutical and clinical testing are accelerating the adoption of benchtop automation, ensuring consistent quality and adherence to industry standards.
- Asia-Pacific is experiencing rapid growth, driven by expanding healthcare infrastructure, rising biopharma activities, and growing demand for automation in countries such as China and India.
- High initial costs and ongoing maintenance expenses pose challenges, especially for smaller laboratories and those in emerging markets, limiting the pace of widespread adoption.
Market Drivers:
Rising Demand for Precision and Efficiency in Laboratory Operations
The increasing need for precision and efficiency in laboratory workflows is a primary driver of the laboratory benchtop automation market. Laboratories, particularly in the healthcare, biotechnology, and pharmaceutical industries, are under pressure to deliver accurate and reproducible results while managing high volumes of samples. Benchtop automation solutions address these demands by minimizing manual errors, streamlining processes, and enhancing overall productivity. For instance, Roche Diagnostics has implemented automated benchtop systems that have reduced manual errors and increased throughput. As laboratories face mounting challenges in managing complex testing procedures, the adoption of compact and efficient benchtop systems is accelerating.
Expansion of Personalized Medicine and Drug Discovery Efforts
The global focus on personalized medicine and the rapid pace of drug discovery initiatives are significantly boosting the market for laboratory benchtop automation. These applications require extensive testing, precise data analysis, and high-throughput screening, which are made feasible through automated benchtop systems. Innovations in genomics, proteomics, and metabolomics are further driving demand for advanced automation tools that can handle intricate workflows and large datasets. For example, Illumina's NextSeq 2000 system enables high-throughput sequencing, supporting personalized medicine initiatives by processing up to 1,200 gigabases of data per runhttps. lableaders.roche.com/global/en/articles/laboratory-quality-efficiency-best-practices.html. Automation is becoming a critical enabler in achieving faster turnaround times and cost efficiency in research and development, fueling its widespread adoption.
Integration of Advanced Technologies in Laboratory Equipment
The integration of advanced technologies, such as artificial intelligence, machine learning, and robotics, is transforming the laboratory benchtop automation landscape. These technologies enhance the capabilities of automation systems by enabling predictive maintenance, data-driven decision-making, and seamless handling of complex laboratory tasks. For instance, Thermo Fisher Scientific has integrated AI and machine learning into its benchtop automation systems, resulting in improvement in predictive maintenance and reduction in downtime. Modular and miniaturized designs are also contributing to market growth, as they allow laboratories of varying sizes to adopt automation without significant space or infrastructure constraints. The ongoing innovation in automation platforms ensures continual improvements in accuracy, reliability, and ease of use.
Regulatory Mandates and Quality Assurance Requirements
Stringent regulatory requirements and the growing emphasis on quality assurance in pharmaceutical and clinical testing are driving the adoption of laboratory benchtop automation. Regulatory bodies mandate accurate and traceable testing protocols to ensure the safety and efficacy of drugs and medical devices. Automated systems help laboratories meet these standards by providing consistent performance, reliable data documentation, and reduced risk of compliance breaches. For example, the Clinical Laboratory Improvement Amendments (CLIA) require laboratories to follow stringent quality standards, and automated systems from companies like Beckman Coulter help ensure compliance by providing accurate and traceable results. As regulations become more complex, laboratories are increasingly relying on automation to maintain operational integrity and ensure adherence to industry guidelines.
Market Trends:
Increasing Adoption of Modular Automation Solutions
The laboratory benchtop automation market is witnessing a shift toward modular automation systems that offer flexibility and scalability. Laboratories are increasingly opting for modular platforms that can be customized to meet specific workflow requirements without significant infrastructure changes. These systems allow users to integrate various functionalities, such as liquid handling, sample preparation, and data analysis, into a single compact unit. For instance, Thermo Fisher Scientific offers modular automation solutions that can be tailored to specific laboratory needs, enhancing efficiency and adaptability. This trend is particularly prominent among small and medium-sized laboratories that require efficient yet adaptable solutions to accommodate evolving testing needs.
Growth of AI and Data-Driven Automation
The integration of artificial intelligence (AI) and data analytics is emerging as a transformative trend in the laboratory benchtop automation market. AI-driven automation systems can analyze vast datasets, identify patterns, and optimize workflows to enhance operational efficiency. These systems are also equipped with predictive analytics capabilities, enabling laboratories to anticipate equipment maintenance needs and minimize downtime. For example, Eularis uses AI-driven analytics to optimize laboratory workflows, resulting in improvement in predictive maintenance and reduction in downtime. This convergence of AI with automation is particularly valuable in high-throughput laboratories, where rapid and accurate decision-making is essential for maintaining productivity.
Rising Emphasis on Lab Digitalization and Connectivity
The digital transformation of laboratories is driving demand for automation solutions that can seamlessly integrate with laboratory information management systems (LIMS) and other digital platforms. Laboratories are increasingly prioritizing connectivity and interoperability to achieve end-to-end digital workflows. Benchtop automation systems equipped with IoT-enabled features and cloud-based data management are becoming a standard choice. For instance, Agilent Technologies provides IoT-enabled benchtop automation systems that enhance data traceability and facilitate remote monitoring. This trend is enhancing data traceability, facilitating remote monitoring, and enabling real-time collaboration among research teams, further advancing the automation ecosystem.
Expansion of Applications in Non-Traditional Laboratories
While the healthcare and pharmaceutical sectors remain dominant users of laboratory benchtop automation, non-traditional applications are gaining momentum. Industries such as food and beverage testing, environmental analysis, and forensic science are increasingly adopting automation to enhance accuracy and throughput. These sectors are leveraging automation for tasks such as microbiological testing, chemical analysis, and quality assurance. For example, Bio Molecular Systems offers automated solutions for microbiological testing and chemical analysis, significantly improving accuracy and throughput in non-traditional laboratory settings. The diversification of automation applications is opening new revenue streams for market players, driving the growth and innovation of benchtop solutions tailored to various industries.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs
One of the primary restraints in the laboratory benchtop automation market is the significant initial investment required for purchasing and implementing automated systems. The cost of advanced benchtop equipment, coupled with expenses related to installation, training, and integration with existing laboratory workflows, can be prohibitive for small and medium-sized laboratories. Additionally, regular maintenance and the need for skilled technicians to operate and troubleshoot these systems further add to the financial burden. This economic barrier restricts widespread adoption, particularly in resource-constrained settings and emerging markets.
Limited Adaptability to Diverse Laboratory Needs
Laboratories often operate with unique workflows and varying requirements, which can pose challenges for standardized benchtop automation systems. Many automation solutions are designed for specific applications or sample types, limiting their flexibility to adapt to diverse testing protocols. This lack of adaptability can result in inefficiencies or underutilization of automation equipment, particularly in multidisciplinary research environments. Consequently, laboratories may hesitate to invest in systems that lack the versatility to address their evolving needs.
Integration Challenges with Legacy Systems
The integration of new benchtop automation systems with existing laboratory infrastructure can be a complex process. Laboratories with legacy equipment often face compatibility issues, requiring additional investments in software updates or hardware modifications. These integration challenges can delay implementation timelines and disrupt laboratory operations. Furthermore, the lack of standardized protocols across automation platforms exacerbates interoperability issues, creating further hurdles for laboratories aiming to achieve seamless workflows.
Workforce Training and Resistance to Change
The successful adoption of benchtop automation relies on a well-trained workforce capable of operating and maintaining these systems effectively. However, many laboratories face a shortage of skilled personnel with the expertise to manage automated workflows. Additionally, resistance to change from laboratory staff accustomed to traditional methods can slow the transition to automation. Addressing these human resource challenges requires investment in comprehensive training programs and change management strategies, which may further strain laboratory budgets and resources.
Market Opportunities:
The laboratory benchtop automation market presents significant opportunities driven by the growing demand for efficiency, precision, and scalability in laboratory workflows. With the increasing complexity of research and diagnostic processes, laboratories across sectors such as pharmaceuticals, biotechnology, and clinical diagnostics are seeking automation solutions to enhance productivity and reduce human error. The adoption of artificial intelligence (AI) and machine learning (ML) in benchtop automation systems is transforming data analysis, enabling predictive insights and real-time decision-making. These advancements create avenues for manufacturers to develop innovative systems tailored to specific laboratory needs, such as high-throughput screening or molecular diagnostics.
Emerging markets, particularly in Asia-Pacific and Latin America, offer lucrative growth prospects as governments and private entities invest in upgrading healthcare and research infrastructure. The rising prevalence of chronic diseases and the expanding pharmaceutical and biopharmaceutical sectors in these regions are fueling demand for automated laboratory solutions. Additionally, the increasing focus on personalized medicine and next-generation sequencing technologies underscores the need for advanced benchtop automation systems capable of handling complex workflows. Manufacturers can capitalize on these opportunities by offering cost-effective, user-friendly solutions and collaborating with academic and research institutions to expand their market reach. This strategic alignment with evolving laboratory requirements positions the market for sustained growth in the coming years.
Market Segmentation Analysis:
The Laboratory Benchtop Automation Market is categorized by product type, end use, and region, offering diverse solutions to streamline laboratory workflows and enhance precision in research and diagnostics.
By product type, the market encompasses automated liquid handling and dispensing benchtop equipment, sample storage and handling equipment, robotics systems, and system accessories. Automated liquid handling and dispensing equipment lead the segment due to their critical role in improving accuracy and reducing manual errors. Robotics systems are gaining traction for their ability to optimize repetitive tasks, while system accessories complement core automation tools, enhancing overall laboratory efficiency.
By end use, the market serves research and development institutes, pharmaceutical industries, hospitals and diagnostic centers, and other specialized laboratories. Pharmaceutical industries dominate this segment, driven by increasing demand for high-throughput screening and drug discovery applications. Hospitals and diagnostic centers are adopting automation to improve diagnostic accuracy and manage growing workloads, while research institutes focus on integrating these technologies to support complex studies.
Segmentation:
By Product Type:
- Automated Liquid Handling & Dispensing Benchtop Equipment
- Sample Storage and Handling Equipment
- Robotics Systems
- System Accessories
By End Use:
- Research & Development Institutes
- Pharmaceutical Industries
- Hospitals & Diagnostic Centres
- Other End Use
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The laboratory benchtop automation market exhibits strong regional dynamics, with varying growth trajectories across key global markets. North America dominates the market, holding the largest share of approximately 35% in 2024. This leadership is attributed to the region’s robust healthcare infrastructure, significant investments in research and development, and the high adoption rate of advanced laboratory technologies. The presence of prominent pharmaceutical and biotechnology companies further bolsters the demand for benchtop automation systems, as these organizations seek to enhance productivity and efficiency in drug discovery and development. Additionally, favorable regulatory frameworks and government funding for research initiatives support sustained market growth in the region.
Europe follows closely, accounting for around 28% of the market share in 2024. The region’s strong emphasis on precision diagnostics and the rising prevalence of chronic diseases drive the adoption of benchtop automation solutions in clinical laboratories. Countries such as Germany, the UK, and France are at the forefront of this growth, benefiting from well-established healthcare systems and substantial investments in laboratory automation. Furthermore, stringent regulatory standards for laboratory processes in the European Union underscore the importance of automated systems for compliance and accuracy.
The Asia-Pacific region is poised to witness the fastest growth, with a compound annual growth rate (CAGR) exceeding the global average during the forecast period. This rapid expansion is driven by increasing healthcare expenditure, rising demand for advanced diagnostic tools, and the growth of the pharmaceutical and biotechnology sectors in countries such as China, India, and Japan. Government initiatives to strengthen research infrastructure and the growing emphasis on personalized medicine further accelerate market adoption in this region, which accounted for approximately 20% of the market share in 2024.
Latin America and the Middle East & Africa collectively account for the remaining market share, with steady growth prospects fueled by improving healthcare infrastructure and rising investments in research and diagnostics. Brazil and South Africa are key contributors within these regions, leveraging initiatives to modernize laboratory processes and expand access to advanced diagnostic solutions. While challenges such as economic instability and limited access to technology persist in some areas, increasing awarene
Key Player Analysis:
- ABBOTT
- Agilent Technologies
- Beckmann Coulter Inc.
- Biotek Instruments
- Danaher Corporation
- Eppendorf
- Logos Biosystems Inc.
- PerkinElmer
- QIAGEN
- Siemens Healthcare
- Thermo Fisher Scientific
Competitive Analysis:
The laboratory benchtop automation market is characterized by intense competition, driven by the presence of established players and emerging innovators striving to capture market share. Key players, including Thermo Fisher Scientific, PerkinElmer Inc., Agilent Technologies, and Tecan Group, dominate the market with their comprehensive product portfolios, global reach, and continuous investments in research and development. These companies leverage advanced technologies, such as artificial intelligence and robotics, to enhance the efficiency and precision of their automation solutions, catering to diverse laboratory needs. Emerging players are focusing on niche segments and offering cost-effective solutions to gain traction, particularly in price-sensitive markets. The competitive landscape is further influenced by strategic collaborations, mergers, and acquisitions, enabling companies to expand their technological capabilities and geographic footprint. For example, PerkinElmer launched the BioQule NGS System, an automated benchtop solution for next-generation sequencing library preparation, which has been well-received in the market. While competition fosters innovation, maintaining differentiation and addressing regional regulatory complexities remain critical challenges for market participants aiming to secure long-term success.
Recent Developments:
- In August 2024, Abbott entered a global partnership with Medtronic to develop an integrated continuous glucose monitoring system based on Abbott's FreeStyle Libre technology.
- In July 2024, Agilent Technologies announced the acquisition of BIOVECTRA for $925 million, expanding their CDMO capabilities in biologics and pharmaceutical manufacturing.
- In October 2024, BioPorto and Beckman Coulter formed a global distribution partnership for Acute Kidney Injury NGAL Tests, with initial distribution in Europe followed by US expansion pending FDA approval.
- In July 2024, Danaher Corporation announced the launch of two new Clinical Laboratory Innovation Centers - one in Newcastle, UK (opening July 2024) and another in the United States (opening late 2024).
- In July 2024, Thermo Fisher Scientific completed its acquisition of Olink Holding for approximately $3.1 billion, integrating Olink into their Life Sciences Solutions segment9.
- In May 2023, Calibre Scientific acquired Eppendorf's micro manipulation product portfolio, including TransferMan, InjectMan, CellTram, and related products
Market Concentration & Characteristics:
The laboratory benchtop automation market exhibits a moderate to high level of market concentration, with a few dominant players holding a significant share. Key companies such as Thermo Fisher Scientific, PerkinElmer Inc., Agilent Technologies, and Tecan Group leverage their technological expertise, strong global presence, and established customer base to maintain a competitive edge. These leaders drive innovation, offering advanced automation solutions tailored to the evolving needs of laboratories across industries. The market is characterized by rapid technological advancements, with features like artificial intelligence, machine learning, and robotics becoming integral to benchtop automation systems. Customization and modularity in equipment design are prominent trends, enabling laboratories to enhance operational efficiency and adapt to diverse workflows. While established players dominate in developed regions, emerging markets provide growth opportunities for smaller and regional companies, driven by the increasing demand for cost-effective and compact automation solutions. This dynamic underscores the sector’s competitive yet innovation-driven nature.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type and By End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The laboratory benchtop automation market is poised for significant growth, driven by increasing demand for high-throughput analysis and precision in laboratory workflows.
- Integration of artificial intelligence and machine learning will enhance automation systems, enabling predictive maintenance and data-driven decision-making.
- Miniaturization and modular designs will gain traction, addressing space constraints in laboratories and fostering flexibility in system configurations.
- Expansion in biotechnology and pharmaceutical industries will boost adoption, particularly in research and drug discovery applications.
- Growing emphasis on reducing human error and improving reproducibility in experiments will accelerate the shift toward automated benchtop solutions.
- Emerging markets in Asia-Pacific and Latin America will present growth opportunities, supported by increasing investments in healthcare and research infrastructure.
- Advancements in cloud-based solutions will enable real-time monitoring and remote operation of automated systems, enhancing operational efficiency.
- Rising adoption in clinical diagnostics, particularly for COVID-19-related testing and beyond, will drive market expansion.
- The development of cost-effective solutions tailored for small and mid-sized laboratories will broaden the market base.
- Collaborative efforts among industry players, academic institutions, and government bodies will foster innovation and accelerate the adoption of advanced automation technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the laboratory benchtop automation market?
What are the key drivers of market growth?
Which region dominates the market?
What industries benefit most from benchtop automation?
What is a key challenge for this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Laboratory Benchtop Automation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Laboratory Benchtop Automation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1325 million → 2032: USD 2033.45 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Laboratory Benchtop Automation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Laboratory Benchtop Automation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Laboratory Benchtop Automation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Laboratory Benchtop Automation Market Drivers
- 3.3 Laboratory Benchtop Automation Market Restraints & Challenges
- 3.4 Laboratory Benchtop Automation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Laboratory Benchtop Automation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Laboratory Benchtop Automation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Laboratory Benchtop Automation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Laboratory Benchtop Automation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Laboratory Benchtop Automation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Laboratory Benchtop Automation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Laboratory Benchtop Automation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Laboratory Benchtop Automation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Laboratory Benchtop Automation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Laboratory Benchtop Automation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Laboratory Benchtop Automation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Laboratory Benchtop Automation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Laboratory Benchtop Automation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Laboratory Benchtop Automation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Laboratory Benchtop Automation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Laboratory Benchtop Automation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Laboratory Benchtop Automation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Laboratory Benchtop Automation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Laboratory Benchtop Automation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
