
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Latin America Data Center Renovation Market Size 2024 | USD 985.88 million |
| Latin America Data Center Renovation Market, CAGR | 12.05% |
| Latin America Data Center Renovation Market Size 2032 | USD 2,449.78 million |
Market Overview
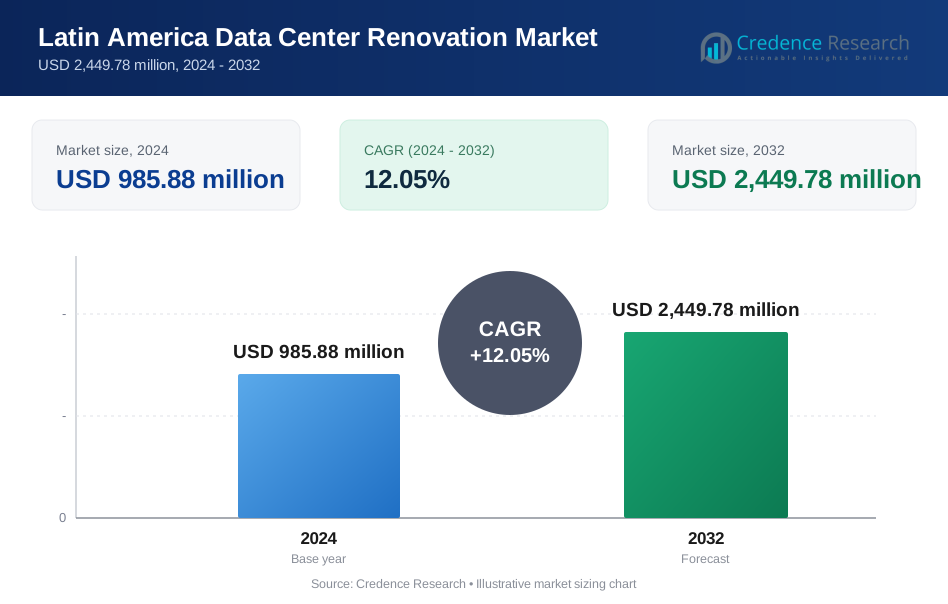
Latin America Data Center Renovation market size was valued at USD 985.88 million in 2024 and is anticipated to reach USD 2,449.78 million by 2032, at a CAGR of 12.05% during the forecast period (2024-2032).
The Latin America Data Center Renovation Market is experiencing significant growth due to increasing demand for modernized IT infrastructure, rising adoption of cloud computing, and the need for energy-efficient data centers. Businesses are investing in renovation projects to enhance operational efficiency, reduce downtime, and comply with stringent regulatory standards. The growing focus on sustainability and the integration of advanced cooling systems, modular designs, and automation technologies are further driving market expansion. Additionally, the rapid digital transformation across industries, coupled with the expansion of hyperscale data centers, is fueling demand for infrastructure upgrades. Key trends include the adoption of AI-driven monitoring solutions, edge computing advancements, and retrofitting of legacy systems with high-density storage and networking solutions. Moreover, increasing investments from global cloud service providers and data center operators are accelerating modernization efforts, positioning Latin America as a strategic hub for digital infrastructure expansion. These factors collectively drive the market’s strong growth trajectory.
Latin America's data center renovation market is driven by increasing digital transformation initiatives across key economies, including Brazil, Argentina, Chile, Colombia, and Peru. Brazil leads the region in data center modernization efforts, fueled by a growing demand for cloud services and government incentives for energy-efficient infrastructure. Argentina and Chile are also witnessing increased renovation activities, driven by expanding IT sectors and the rising adoption of edge computing. Colombia and Peru are focusing on upgrading aging facilities to meet evolving data security and operational efficiency standards. Several global and regional players are actively investing in the market, including Schneider Electric, Cisco Systems, Dell Technologies, Johnson Controls, Honeywell, Microsoft, Siemens, and IBM. These companies are introducing innovative solutions, such as advanced cooling systems and AI-driven energy management tools, to enhance data center efficiency. Their strategic expansions, partnerships, and technological advancements continue to shape the competitive landscape of Latin America's data center renovation industry.
Market Insights
- The Latin America Data Center Renovation market was valued at USD 985.88 million in 2024 and is projected to reach USD 2,449.78 million by 2032, growing at a CAGR of 12.05% from 2024 to 2032.
- Increasing demand for energy-efficient and sustainable data center solutions is driving renovation activities across the region.
- Rising adoption of cloud computing and digital transformation initiatives is fueling modernization efforts in key economies like Brazil and Argentina.
- Integration of AI-driven cooling and power management systems is emerging as a key trend in data center renovations.
- Leading companies, including Schneider Electric, Cisco Systems, and Dell Technologies, are expanding their presence through partnerships and technological advancements.
- High costs and operational disruptions during renovation pose challenges to market growth.
- Brazil dominates the market, followed by Argentina and Chile, with growing investments in data center infrastructure to support rising digital connectivity demands.
Market Drivers
Rising Demand for Energy-Efficient and Sustainable Data Centers
The increasing focus on sustainability and energy efficiency is a major driver of the Latin America Data Center Renovation Market. Companies are actively seeking solutions to reduce power consumption and carbon footprints while improving operational efficiency. Data centers consume significant amounts of electricity, and rising energy costs are compelling businesses to adopt eco-friendly practices such as advanced cooling technologies, liquid cooling systems, and renewable energy integration. Additionally, regulatory bodies in Latin America are introducing stringent environmental policies, encouraging data center operators to upgrade existing facilities to meet compliance requirements. The transition to green data centers not only helps in cost reduction but also enhances brand reputation by aligning with corporate sustainability goals. For instance, a Chilean mining company reduced its operating costs and carbon footprint by deploying uninterruptible power supply units with lithium-ion batteries. This growing emphasis on energy-efficient infrastructure is accelerating the demand for data center renovations across the region.
Increasing Adoption of Cloud Computing and Digital Transformation
The rapid expansion of cloud computing and digital transformation initiatives is significantly fueling the need for data center renovations in Latin America. Businesses across industries, including banking, healthcare, and e-commerce, are shifting to cloud-based solutions, driving the demand for modernized data center infrastructure that supports high-speed processing, storage, and security. As enterprises migrate to hybrid and multi-cloud environments, existing data centers require upgrades to accommodate increasing workloads and ensure seamless connectivity. For instance, Brazil's "Digital Government Strategy" focuses on improving citizen services and enhancing data security through cloud solutions. Additionally, governments in the region are investing in digitalization efforts, further pushing the need for data center modernization. The growing reliance on cloud services has also led to an increase in data traffic, necessitating enhanced network infrastructure and storage capabilities. These factors collectively contribute to the rising investments in data center renovation projects.
Growing Investments from Hyperscale and Colocation Data Center Providers
Latin America is witnessing significant investments from global hyperscale and colocation data center providers, further driving the market for data center renovations. Major cloud service providers such as AWS, Microsoft Azure, and Google Cloud are expanding their presence in the region, leading to increased demand for infrastructure upgrades and facility expansions. Existing data centers are being modernized to meet the evolving requirements of hyperscale computing, which includes higher power density, improved cooling systems, and enhanced security measures. Additionally, colocation providers are upgrading their facilities to offer better scalability and reliability to enterprise customers. These investments are transforming Latin America into a key digital infrastructure hub, fostering growth in the data center renovation market.
Technological Advancements and Adoption of AI-Driven Solutions
The integration of AI-driven solutions and automation technologies is revolutionizing the Latin America Data Center Renovation Market. Businesses are leveraging AI for predictive maintenance, real-time monitoring, and energy optimization, ensuring improved operational efficiency and reduced downtime. The adoption of intelligent power management systems, automated security protocols, and smart cooling technologies is becoming increasingly prevalent in renovated data centers. Additionally, advancements in edge computing are prompting companies to upgrade their infrastructure to support decentralized data processing, reducing latency and enhancing performance. These technological innovations are not only improving the efficiency of existing data centers but also making them more resilient to future demands, further driving market growth.
Market Trends
Increasing Adoption of Modular and Scalable Data Center Designs
The Latin America Data Center Renovation Market is witnessing a growing shift towards modular and scalable designs to enhance flexibility and operational efficiency. For instance, Scala Data Centers has decided to invest in more than 30 data centers spread across the under-construction, planned, and announced stages. Businesses are increasingly investing in modular infrastructure that allows for rapid expansion and easy upgrades without significant disruptions. These prefabricated modular solutions enable data centers to adapt to evolving technological requirements, ensuring future-proof operations. Additionally, the scalability of these designs supports growing data processing demands, making them an attractive choice for enterprises and cloud service providers. As organizations prioritize cost-effective renovation strategies, modular solutions are becoming a preferred choice for optimizing space utilization and improving energy efficiency in existing data centers.
Integration of Advanced Cooling and Energy-Efficient Technologies
Energy efficiency remains a key focus in data center renovation, driving the adoption of advanced cooling solutions and energy-efficient technologies across Latin America. Companies are increasingly implementing liquid cooling, immersion cooling, and AI-driven climate control systems to enhance thermal management while reducing power consumption. The rising electricity costs and stringent environmental regulations are pushing operators to adopt green energy solutions, such as solar and wind power, to achieve sustainability goals. Additionally, data centers are incorporating smart energy management systems that optimize power usage and improve overall efficiency. These advancements are transforming existing facilities into more environmentally friendly and cost-effective operations, making energy efficiency a central trend in data center renovations.
Rise of Edge Computing and Decentralized Data Infrastructure
The increasing demand for low-latency computing is driving the expansion of edge computing infrastructure, leading to significant upgrades in existing data centers. Latin America is experiencing a surge in IoT adoption, 5G deployment, and digital transformation initiatives, necessitating localized data processing to reduce network congestion and improve real-time analytics. As a result, data center operators are modernizing legacy systems to support edge computing capabilities, ensuring faster data access and enhanced security. This trend is particularly prominent in industries such as telecommunications, healthcare, and smart cities, where real-time data processing is crucial. The shift towards decentralized data infrastructure is reshaping renovation strategies, with a focus on distributed computing and high-performance storage solutions.
Enhanced Security and AI-Powered Automation in Renovation Strategies
With the increasing volume of data being processed and stored, cybersecurity has become a top priority in data center renovation projects. Organizations are upgrading their security infrastructure by integrating AI-driven threat detection, biometric access controls, and automated monitoring systems to prevent cyberattacks and unauthorized access. Additionally, AI-powered automation is streamlining maintenance, optimizing workloads, and improving overall operational resilience. Predictive analytics and self-healing systems are being deployed to reduce downtime and enhance efficiency. As businesses prioritize data security and operational continuity, the implementation of AI and automation-driven solutions is becoming a fundamental aspect of data center renovation efforts across Latin America.
Market Challenges Analysis
High Capital Investment and Cost Constraints
One of the primary challenges in the Latin America Data Center Renovation Market is the high capital investment required for modernization projects. Upgrading existing infrastructure involves substantial costs related to advanced cooling systems, energy-efficient power solutions, and security enhancements. Many enterprises, especially small and medium-sized businesses, struggle to allocate sufficient budgets for large-scale renovations, leading to delays or partial upgrades. Additionally, fluctuating economic conditions and currency depreciation in some Latin American countries further strain investment capabilities. For example, in Eldorado do Sul, Brazil, new legislation was approved to authorize the development of Scala AI City, with an initial investment of $500 million to spur economic recovery following 2024 floods. Businesses often face challenges in securing funding for these upgrades, limiting the pace of data center modernization. Despite the long-term benefits of improved efficiency and reduced operational costs, the significant upfront investment remains a critical barrier to widespread adoption of renovation initiatives.
Infrastructure Limitations and Regulatory Compliance
Aging infrastructure and regulatory challenges pose significant hurdles to data center renovation across Latin America. Many existing data centers operate with outdated power and cooling systems, requiring complex retrofitting processes that can be both time-consuming and disruptive. In addition, regulatory compliance requirements related to energy consumption, data security, and environmental impact add further complexity to renovation projects. Different countries in the region have varying regulations, making it challenging for multinational companies to standardize their renovation strategies. Moreover, the lack of skilled professionals and technical expertise in data center operations further complicates the modernization process. Addressing these infrastructure and regulatory challenges requires strategic planning, increased investments in workforce development, and collaboration between industry stakeholders and government bodies to create a more supportive framework for data center upgrades.
Market Opportunities
The Latin America Data Center Renovation Market presents significant opportunities driven by the region's accelerating digital transformation and increasing demand for cloud computing solutions. As businesses and government agencies expand their reliance on data-driven technologies, the need for modernized and efficient data center infrastructure is growing. The rapid adoption of AI, IoT, and big data analytics is further pushing organizations to upgrade their existing facilities to support high-performance computing and real-time data processing. Additionally, the growing presence of global cloud service providers in Latin America is creating demand for scalable and energy-efficient data centers. Companies that invest in innovative renovation strategies, such as modular infrastructure and advanced cooling technologies, can capitalize on this growing market while addressing the region’s sustainability concerns.
Another key opportunity lies in the expansion of edge computing and colocation services, as enterprises seek to enhance data processing capabilities closer to end users. The deployment of 5G networks and the increasing penetration of IoT devices are driving the need for decentralized data centers with lower latency and higher efficiency. This shift creates opportunities for infrastructure upgrades that support localized data processing, security enhancements, and AI-driven automation. Furthermore, government initiatives aimed at improving digital connectivity and smart city developments are fostering investments in data center modernization projects. Companies that offer tailored renovation solutions, integrating automation, security, and energy-efficient designs, can gain a competitive advantage in this evolving market. As the demand for reliable and sustainable data infrastructure continues to grow, businesses that prioritize modernization efforts will be well-positioned to capitalize on the expanding opportunities in Latin America’s data center renovation sector.
Market Segmentation Analysis:
By Renovation Type:
The Latin America Data Center Renovation Market is segmented into mechanical, electrical, and infrastructure renovations, each addressing specific operational challenges. Mechanical renovations focus on upgrading cooling systems, airflow management, and HVAC infrastructure to enhance thermal efficiency and reduce energy consumption. With increasing environmental regulations and the need for sustainable operations, businesses are investing in liquid cooling solutions, precision air conditioning, and advanced ventilation systems. Electrical renovations primarily involve modernizing power distribution, backup generators, and uninterruptible power supply (UPS) systems to ensure stable and uninterrupted operations. The rising adoption of high-density computing and AI-driven workloads is driving the need for upgraded electrical infrastructure that supports increased power demands. Infrastructure renovations encompass the physical expansion and redesign of data center layouts, integrating modular architectures, improved cabling systems, and seismic reinforcement to enhance durability and scalability. As enterprises seek to improve operational efficiency and future-proof their facilities, investments in infrastructure upgrades continue to rise, further driving market growth across Latin America.
By Renovation Goal:
Data center renovation projects in Latin America are primarily driven by goals such as improved energy efficiency, increased capacity and density, and modernization. Improved energy efficiency remains a key focus, with organizations adopting advanced cooling technologies, energy-efficient servers, and smart power management systems to reduce operational costs and meet sustainability targets. Additionally, regulatory mandates promoting green energy adoption are encouraging companies to integrate renewable energy sources into their facilities. Increased capacity and density renovations aim to optimize data center space, supporting high-performance computing and edge processing needs. With rising demand for cloud computing and AI applications, businesses are upgrading to high-density racks, efficient power distribution, and scalable architectures. Modernization and upgrading initiatives focus on enhancing security, automation, and overall performance, ensuring that legacy data centers can support next-generation digital infrastructure. As digital transformation accelerates, enterprises are prioritizing these renovation goals to remain competitive in an increasingly data-driven economy.
Segments:
Based on Renovation Type:
- Mechanical Renovation
- Electrical Renovation
- Infrastructure Renovation
Based on Renovation Goal:
- Improved Energy Efficiency
- Increased Capacity and Density
- Modernization and Upgrading
Based on Component:
- Cooling Systems
- Power Systems
- Racks and Enclosures
- Security Systems
Based on Age:
- 0-5 Years
- 6-10 Years
- 11-15 Years
- 16-20 Years
- Over 20 Years
Based on the Geography:
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
Regional Analysis
Brazil
Brazil holds the largest share in the Latin America Data Center Renovation Market, accounting for approximately 35% of the total market in 2024. The country’s strong market presence is driven by the rapid expansion of cloud computing, increasing investments from global technology firms, and growing digitalization across industries. Brazil is home to major data centers operated by companies such as Microsoft, Google, and AWS, leading to continuous infrastructure upgrades and modernization efforts. The demand for energy-efficient solutions and regulatory requirements promoting sustainable data center operations further contribute to the market’s growth. Additionally, the increasing adoption of AI, IoT, and big data analytics is pushing enterprises to renovate existing facilities, ensuring better efficiency and scalability. As businesses prioritize security and performance, investments in electrical and mechanical renovations are rising, making Brazil a key hub for data center development in Latin America.
Argentina
Argentina holds a market share of approximately 18%, reflecting steady growth in the data center renovation sector. The country’s expanding IT infrastructure and rising adoption of cloud computing services are key drivers of market expansion. Government initiatives promoting digital transformation and data sovereignty are encouraging investments in local data centers, driving the need for mechanical and infrastructure renovations. Additionally, the increasing adoption of colocation services among enterprises and financial institutions is fueling the demand for improved capacity and efficiency. Argentina’s data centers are focusing on sustainability, leading to the integration of renewable energy sources such as wind and solar power. Furthermore, the growing penetration of edge computing and 5G technology is prompting companies to upgrade their existing facilities, enhancing connectivity and reducing latency. With global and regional players investing in modernization efforts, Argentina is poised for further growth in the data center renovation market.
Chile
Chile accounts for approximately 12% of the Latin America Data Center Renovation Market, with a strong focus on energy-efficient infrastructure and digital transformation. The country has positioned itself as a strategic location for data center investments due to its stable economy, favorable business environment, and increasing use of renewable energy sources. Chile is actively promoting green data center renovations, making significant investments in sustainable cooling technologies and alternative energy solutions to reduce operational costs and environmental impact. Additionally, the deployment of submarine fiber optic cables is strengthening the country’s position as a digital hub in South America, leading to increased demand for high-performance data centers. As businesses seek to modernize IT infrastructure and improve security measures, investments in automation and AI-driven monitoring systems are rising, positioning Chile as a key growth market for data center renovations.
Colombia
Colombia holds a market share of approximately 10%, driven by increasing investments in cloud computing, fintech, and digital government initiatives. The country is witnessing rising demand for modernized and scalable data center infrastructure, with both local and international firms upgrading their existing facilities. The government’s focus on improving digital connectivity and cybersecurity regulations is further encouraging businesses to invest in mechanical and infrastructure renovations. Additionally, Colombia’s growing e-commerce and banking sectors are fueling the need for advanced data center solutions that ensure high performance, security, and reliability. With companies emphasizing cost-effective and energy-efficient renovation strategies, the demand for smart cooling technologies and AI-based automation is increasing. As Colombia continues to strengthen its digital economy, the data center renovation market is expected to see sustained growth, making it a promising region for infrastructure modernization.
Key Player Analysis
- Schneider Electric
- Cisco Systems
- Dell Technologies
- Johnson Controls
- Honeywell
- Microsoft
- Siemens
- Emerson Electric
- Hewlett Packard Enterprise
- IBM
- Vertiv
- Legrand
- Eaton
- ABB
Competitive Analysis
The competitive landscape of the Latin America Data Center Renovation market is characterized by the presence of key players such as Schneider Electric, Cisco Systems, Dell Technologies, Johnson Controls, Honeywell, Microsoft, Siemens, Emerson Electric, Hewlett Packard Enterprise, IBM, Google, Vertiv, Legrand, Eaton, and ABB. These companies are focusing on technological advancements, strategic partnerships, and acquisitions to strengthen their market position. These firms are emphasizing energy-efficient power and cooling solutions, addressing the rising demand for sustainable data centers. For example, Scala Data Centers and Serena announced a renewable energy supply agreement in Latin America, expanding Scala's renewable energy portfolio and providing wind power for hyperscale data centers. Additionally, there is a strong push towards network and infrastructure modernization, integrating AI-driven automation and cloud-based solutions to enhance operational efficiency. Many companies are investing in smart building technologies and energy management systems, ensuring minimal downtime during renovations while improving overall sustainability. Expanding footprints in key markets such as Brazil and Argentina is a priority, with firms leveraging joint ventures and localized services to strengthen their presence. Despite strong competition, high initial costs and operational disruptions associated with data center renovations remain significant challenges. To mitigate these issues, leading market players are focusing on modular solutions and scalable renovation strategies, ensuring seamless upgrades and long-term efficiency improvements.
Recent Developments
- In December 2024, Microsoft announced the completion of construction on three Azure availability zones in Saudi Arabia, with availability expected in 2026. These zones are part of Microsoft's ongoing investments in the Kingdom, focusing on providing highly secure and globally trusted cloud services to governments and key industries.
- In October 2024, Johnson Controls announced its participation in Data Centre World Asia 2024, where it will showcase its integrated solutions for smarter, safer, and more resilient data center operations. The company aims to highlight its commitment to sustainable infrastructure and advanced technology.
- In October 2024, Dell's founder and CEO, Michael Dell, predicted that data center capacity will need to increase by 100 times over the next 10 years due to the rising demand for AI services.
- In June 2024, Schneider Electric opened a new 105,000-square-foot integration facility in Red Oak, Texas, designed to build pre-engineered and prefabricated IT infrastructure to meet the growing demand for data centers in the U.S. This facility will accelerate the production of integrated modular data center solutions, reducing production costs and expediting delivery.
- In May 2024, Dell Technologies unveiled enhancements to its Dell AI Factory, combining its XE 9680 with direct liquid cooling to support AI workloads. The company also introduced new storage capabilities with PowerStore 4.0, offering greater efficiency and better speeds.
Market Concentration & Characteristics
The Latin America Data Center Renovation market exhibits a moderately concentrated landscape, with a mix of global enterprises and regional firms driving market growth. Larger players dominate through extensive service portfolios, advanced technological capabilities, and strategic alliances, while smaller firms focus on niche offerings and localized expertise. The market is characterized by increasing demand for energy-efficient renovations, modernization of legacy infrastructure, and integration of AI and automation for enhanced operational efficiency. Companies are prioritizing sustainability initiatives, leading to the adoption of advanced cooling systems, modular designs, and smart power management solutions. Additionally, regulatory frameworks promoting reduced energy consumption are shaping market strategies. While competition remains strong, high capital investment and operational disruptions during renovation projects act as barriers for new entrants. However, the growing reliance on cloud computing, edge data centers, and hybrid IT environments is expected to create significant opportunities, driving further innovation and service expansion in the industry.
Report Coverage
The research report offers an in-depth analysis based on Renovation Type, Renovation Goal, Component, Age and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Latin America Data Center Renovation market is projected to experience significant growth, driven by increasing digital transformation initiatives.
- Rising adoption of cloud computing and edge data centers will fuel demand for modernized infrastructure.
- Companies will focus on energy-efficient solutions to align with sustainability goals and regulatory requirements.
- Integration of AI and automation will enhance operational efficiency and reduce maintenance costs.
- Hybrid IT environments will gain traction, leading to increased investments in scalable and modular renovation solutions.
- Security enhancements will remain a priority, with advanced monitoring systems and cybersecurity measures being implemented.
- Market players will expand their service portfolios to include predictive maintenance and remote management solutions.
- Government initiatives supporting data localization and energy conservation will influence renovation strategies.
- High initial investment costs may continue to challenge smaller firms, driving partnerships and acquisitions.
- Continuous technological advancements will shape the competitive landscape, encouraging innovation and service differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Data Center Renovation market?
What factors are driving the growth of the Latin America Data Center Renovation market?
What are some challenges faced by the Latin America Data Center Renovation market?
Who are the major players in the Latin America Data Center Renovation market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Latin America Data Center Renovation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Latin America Data Center Renovation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 985.88 million → 2032: USD 2,449.78 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Latin America Data Center Renovation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Latin America Data Center Renovation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Latin America Data Center Renovation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Latin America Data Center Renovation Market Drivers
- 3.3 Latin America Data Center Renovation Market Restraints & Challenges
- 3.4 Latin America Data Center Renovation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Latin America Data Center Renovation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Latin America Data Center Renovation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Latin America Data Center Renovation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Latin America Data Center Renovation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Latin America Data Center Renovation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Latin America Data Center Renovation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Latin America Data Center Renovation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Latin America Data Center Renovation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Latin America Data Center Renovation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Latin America Data Center Renovation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Latin America Data Center Renovation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Latin America Data Center Renovation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Latin America Data Center Renovation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Latin America Data Center Renovation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Latin America Data Center Renovation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Latin America Data Center Renovation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Latin America Data Center Renovation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Latin America Data Center Renovation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Latin America Data Center Renovation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
