
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lawn Mowers Market Size 2024 | USD 34,212.40 million |
| Lawn Mowers Market, CAGR | 6.44% |
| Lawn Mowers Market Size 2032 | USD 56,047.39 million |
Market Overview:
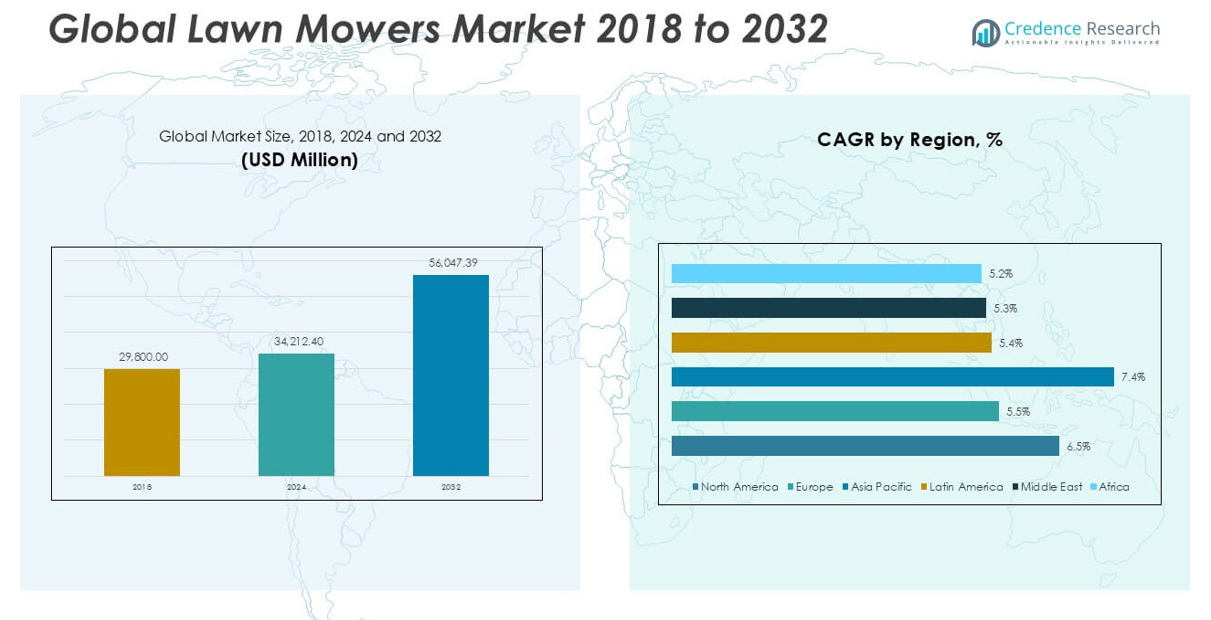
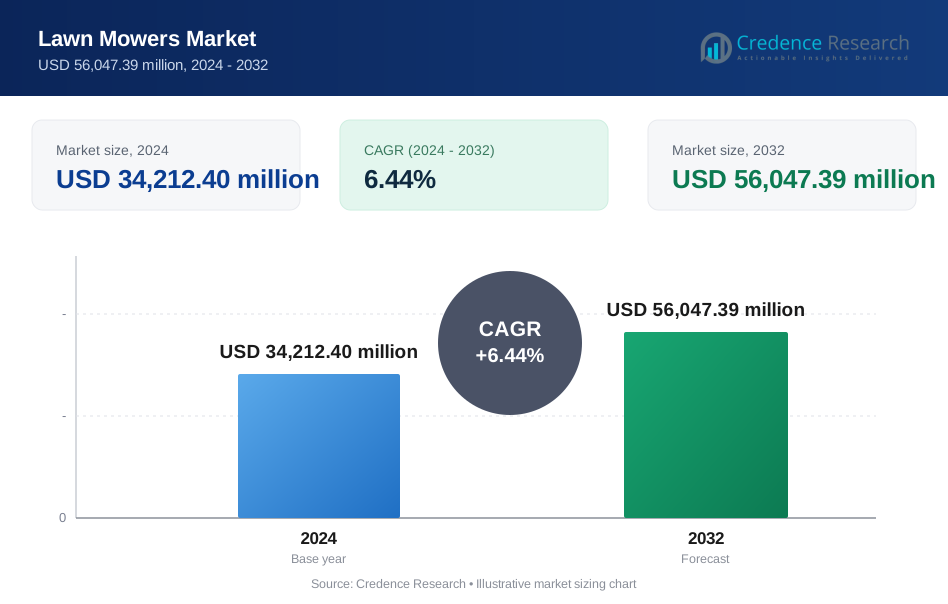
The Lawn Mowers market size was valued at USD 29,800.00 million in 2018, reached USD 34,212.40 million in 2024, and is anticipated to reach USD 56,047.39 million by 2032, at a CAGR of 6.44% during the forecast period.
The Lawn Mowers market is dominated by leading players such as Deere & Company, Husqvarna Group, The Toro Company, Briggs & Stratton, Robert Bosch GmbH, American Honda Motor Co., Inc., Ariens Company, MTD Products, Robomow Friendly House, Falcon Garden Tools, and Fiskars. These companies focus on product innovation, battery technology, and the expansion of robotic and electric mower offerings to strengthen their global position. North America leads the Lawn Mowers market, holding a 34.8% share in 2024, driven by high consumer demand for advanced lawn care equipment and widespread adoption of smart, eco-friendly mowing solutions. Europe and Asia Pacific follow, supported by increasing environmental awareness and growing residential landscaping activities.
Market Insights
- The Lawn Mowers market was valued at USD 29,800.00 million in 2018, reached USD 34,212.40 million in 2024, and is projected to reach USD 56,047.39 million by 2032, growing at a CAGR of 6.44% during the forecast period.
- Rising demand for home gardening, landscaping, and DIY lawn maintenance is driving market growth, with walk-behind lawn mowers holding over 45% segment share in 2024 due to their ease of use and affordability.
- The market is witnessing strong trends in the adoption of robotic lawn mowers and battery-powered models, supported by technological advancements like GPS, smart sensors, and remote control features.
- The competitive landscape is marked by leading players such as Deere & Company, Husqvarna Group, and The Toro Company, who are focusing on electric product portfolios, though high initial costs and battery limitations remain key restraints.
- North America leads the market with a 34.8% share in 2024, followed by Asia Pacific at 30.0% and Europe at 23.5%, with Asia Pacific showing the fastest growth at a 7.4% CAGR.
Market Segmentation Analysis:
By Type:
In the Lawn Mowers market, the Walk-behind Lawn Mowers segment holds the dominant share, accounting for over 45% of the market in 2024. These mowers are widely preferred due to their affordability, ease of use, and suitability for small to medium-sized lawns. Increasing residential development and the growing popularity of DIY lawn care practices are key drivers fueling this segment’s growth. Furthermore, advancements in ergonomic designs and lightweight models continue to attract a broad consumer base, enhancing the market position of walk-behind mowers over riding and robotic variants.
- For instance, in 2021, Honda launched the HRN216VKA walk-behind lawn mower equipped with a GCV170 engine delivering 166cc displacement and 4.8 horsepower, offering significant power with an easy-start system specifically targeted at home users.
By Offering
Within the Lawn Mowers market by offering, Hardware dominates with a significant market share exceeding 70% in 2024, driven by the continuous demand for key components such as ultrasonic sensors, motors, and batteries. Among these, batteries are the leading sub-segment, driven by the rising consumer preference for battery-powered, eco-friendly lawn mowers that offer quiet operation and reduced emissions. The push for sustainability and increasing adoption of electric propulsion further support the demand for advanced battery technologies, positioning hardware as the core revenue generator in this segment.
- For instance, Husqvarna’s Automower 435X AWD is powered by a Li-Ion battery pack of 5.2 Ah capacity that supports 70-minute continuous operation with a charging time of 30 minutes, demonstrating significant advancements in hardware efficiency and performance.
By Propulsion Type
The Electric Lawn Mowers segment leads the propulsion type category, capturing more than 60% of the market share in 2024. This growth is primarily driven by the increasing consumer shift towards environmentally friendly alternatives that reduce noise and carbon emissions. Rising fuel prices and stringent environmental regulations further accelerate the adoption of electric mowers over ICE-powered units. Additionally, advancements in battery capacity and charging efficiency contribute to the dominance of this segment, making electric lawn mowers a preferred choice for both residential and commercial applications.
Market Overview
Rising Demand for Home Gardening and Landscaping
The growing consumer inclination towards home gardening and aesthetically appealing outdoor spaces significantly drives the demand for lawn mowers. Urbanization and increasing disposable income are encouraging homeowners to invest in regular lawn maintenance and landscaping equipment. Additionally, the expanding trend of DIY gardening activities, especially in residential areas, accelerates the purchase of walk-behind and robotic lawn mowers. This shift enhances market growth by creating sustained demand across both developed and developing regions.
- For instance, The Toro Company reported a 25% increase in residential mower sales volume in 2021, attributed to rising DIY gardening activities and increased home improvement spending during the pandemic period.
Technological Advancements in Lawn Mowers
Continuous innovation in lawn mower technology, particularly the integration of battery-powered systems, smart sensors, and autonomous navigation, is propelling market growth. Robotic lawn mowers with features such as GPS tracking, self-charging, and remote operation via smartphones offer users greater convenience and efficiency. These technological advancements attract both residential and commercial consumers seeking cost-effective and time-saving lawn care solutions, boosting the adoption of advanced lawn mowing equipment globally.
- For instance, Husqvarna’s Automower 450X can autonomously cover lawn areas up to 5,000 square meters, navigate slopes of up to 24° (45% incline), and is equipped with GPS-assisted navigation for optimized mowing patterns.
Increasing Environmental Awareness and Regulations
Growing awareness regarding environmental sustainability and stringent emission regulations are accelerating the shift from internal combustion engine (ICE) mowers to electric and battery-powered alternatives. Governments and regulatory bodies across various regions promote the use of eco-friendly equipment, driving consumer preference for quieter, energy-efficient lawn mowers with low carbon footprints. This regulatory push is encouraging manufacturers to focus on greener technologies, creating significant growth opportunities in the electric lawn mower segment.
Key Trends & Opportunities
Surge in Adoption of Robotic Lawn Mowers
The increasing adoption of robotic lawn mowers presents a key growth opportunity for market players. These mowers offer automated lawn maintenance with minimal human intervention, which appeals to busy homeowners and large commercial property managers. Features like programmable schedules, rain sensors, and safety mechanisms are enhancing product appeal. The convenience and time efficiency provided by robotic mowers are driving rapid acceptance, particularly in Europe and North America.
- For instance, the Robomow RS630 can autonomously maintain lawns up to 3,200 square meters and is integrated with Bluetooth and GSM modules for remote control and real-time status updates via mobile applications.
Expansion of Online Sales Channels
The expansion of online sales platforms is emerging as a strong trend in the lawn mowers market. E-commerce channels offer consumers access to a wide variety of models, competitive pricing, and convenient delivery options. Online product reviews and detailed specifications help buyers make informed decisions. This shift is particularly notable among younger, tech-savvy consumers who prefer digital shopping experiences, creating new revenue streams for manufacturers and retailers globally.
- For instance, Amazon reported that robotic lawn mowers, including models from Husqvarna and Worx, saw a 45% year-on-year sales increase in 2021 through its e-commerce platform, highlighting the shift toward online purchasing preferences.
Key Challenges
High Initial Cost of Advanced Lawn Mowers
The premium pricing associated with robotic and high-performance battery-powered lawn mowers poses a significant challenge, especially in price-sensitive markets. Although these models offer long-term operational savings, the high upfront investment can deter residential users and small businesses. This cost barrier limits the widespread adoption of technologically advanced mowers in developing regions, where traditional walk-behind and ICE-powered models still dominate due to affordability.
Limited Battery Life and Charging Constraints
Despite advancements, battery-powered lawn mowers still face limitations related to battery life and charging infrastructure. Longer charging times and restricted run-time can hinder productivity, particularly for users with large lawn areas or commercial landscaping operations. These limitations may lead consumers to prefer conventional fuel-based mowers that offer longer uninterrupted operation, posing a challenge to the growth of electric and robotic lawn mower segments.
Seasonal Demand Fluctuations
Lawn mower sales are highly seasonal, with peak demand concentrated during the spring and summer months. This cyclical buying pattern creates inventory management and revenue forecasting challenges for manufacturers and retailers. In regions with prolonged winters or unpredictable weather patterns, the short mowing season can significantly impact annual sales volumes and profitability, posing a structural challenge to market stability.
Regional Analysis
North America
North America held the largest share in the Lawn Mowers market, accounting for 34.8% in 2024, with a market size of USD 11,913.61 million, up from USD 10,489.60 million in 2018. The region is projected to reach USD 19,619.67 million by 2032, expanding at a CAGR of 6.5%. The strong market presence is driven by high adoption of advanced lawn care equipment, growing demand for home gardening, and the popularity of robotic mowers. Technological advancements and the presence of key manufacturers further contribute to the region's continued market dominance.
Europe
Europe accounted for 23.5% of the Lawn Mowers market in 2024, with the market size increasing from USD 7,301.00 million in 2018 to USD 8,032.14 million in 2024. It is anticipated to reach USD 12,261.64 million by 2032, growing at a CAGR of 5.5%. The region benefits from strong demand for robotic and battery-powered lawn mowers, driven by increasing environmental regulations and consumer preference for low-noise, eco-friendly equipment. The rise in residential landscaping and government initiatives supporting green spaces continue to fuel market expansion in Europe.
Asia Pacific
Asia Pacific captured 30.0% of the Lawn Mowers market share in 2024, growing from USD 8,612.20 million in 2018 to USD 10,258.44 million in 2024. The market is forecast to reach USD 18,154.80 million by 2032, expanding at the highest CAGR of 7.4%. Rapid urbanization, rising disposable incomes, and increasing interest in personal landscaping drive the regional market growth. Additionally, the growing middle-class population and expanding e-commerce networks are significantly boosting lawn mower sales across key countries, particularly in China, India, and Japan.
Latin America
Latin America accounted for 5.1% of the Lawn Mowers market in 2024, with the market size rising from USD 1,525.76 million in 2018 to USD 1,730.80 million in 2024. The market is projected to reach USD 2,610.13 million by 2032, growing at a CAGR of 5.4%. Increasing urban green spaces, growing residential construction, and the gradual adoption of electric lawn mowers support market growth. However, compared to North America and Europe, the market in Latin America is still developing, with cost sensitivity and limited product penetration restraining faster expansion.
Middle East
The Middle East contributed 3.5% to the Lawn Mowers market in 2024, increasing from USD 1,102.60 million in 2018 to USD 1,183.53 million in 2024. The market is expected to reach USD 1,770.73 million by 2032, at a CAGR of 5.3%. Growing landscaping activities in residential and commercial sectors, particularly in the UAE and Saudi Arabia, are driving demand. Government initiatives to enhance urban greenery and the adoption of advanced garden equipment further support market development. However, the region’s dry climate limits natural lawn growth, slightly constraining broader market potential.
Africa
Africa represented 3.2% of the Lawn Mowers market in 2024, with the market growing from USD 768.84 million in 2018 to USD 1,093.87 million in 2024. It is anticipated to reach USD 1,630.42 million by 2032, expanding at a CAGR of 5.2%. The market is driven by increasing urbanization, the expansion of residential housing, and gradual adoption of modern landscaping equipment. While market growth remains moderate due to economic constraints and limited product availability, rising awareness of garden aesthetics and growing disposable income are expected to support future demand in the region.Top of FormBottom of For
Market Segmentations:
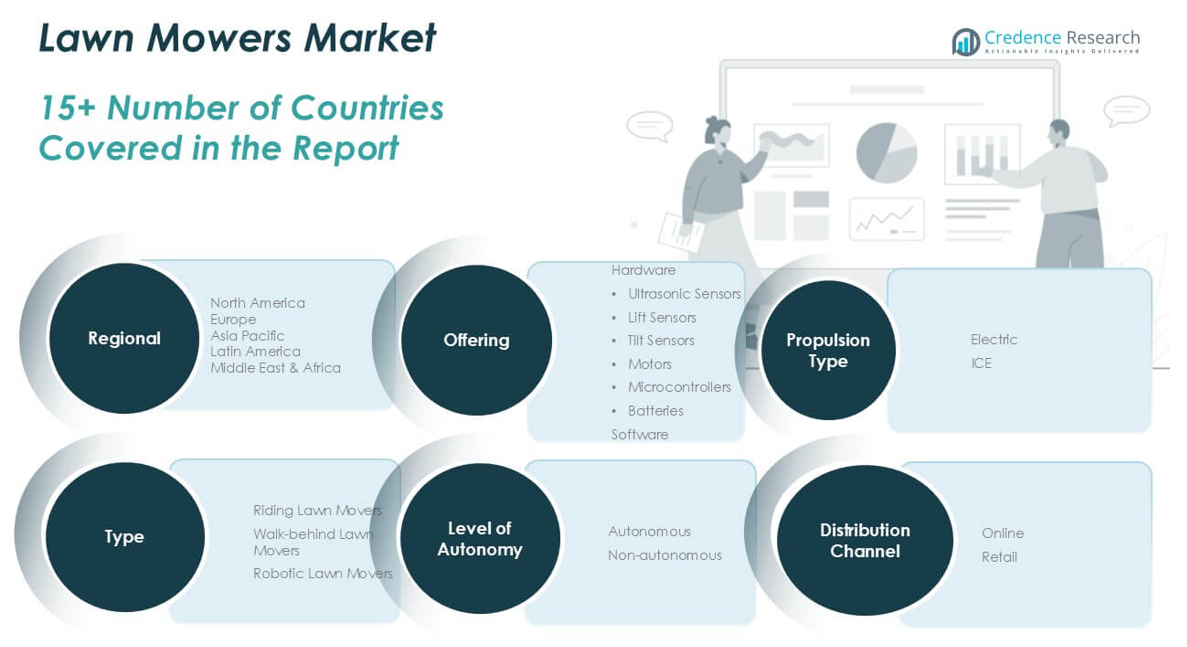
By Type
- Riding Lawn Mowers
- Walk-behind Lawn Mowers
- Robotic Lawn Mowers
By Offering
- Hardware
- Ultrasonic Sensors
- Lift Sensors
- Tilt Sensors
- Motors
- Microcontrollers
- Batteries
- Software
By Propulsion Type
- Electric
- ICE (Internal Combustion Engine)
By Level of Autonomy
- Autonomous
- Non-autonomous
By Distribution Channel
- Online
- Retail
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Lawn Mowers market is highly competitive, with key players focusing on product innovation, technological advancements, and strategic partnerships to strengthen their market presence. Major companies such as Deere & Company, Husqvarna Group, The Toro Company, Briggs & Stratton, and Robert Bosch GmbH dominate the landscape by offering a wide range of lawn care solutions tailored to residential, commercial, and professional users. These players consistently invest in research and development to introduce electric, battery-powered, and robotic mowers with advanced features like GPS navigation and remote operation. The market also witnesses growing participation from regional and emerging manufacturers, particularly in Asia Pacific, who offer cost-effective alternatives to attract price-sensitive consumers. Companies are increasingly leveraging online distribution channels to expand their reach and improve customer engagement. Additionally, mergers, acquisitions, and collaborations are common strategies aimed at enhancing technological capabilities and expanding product portfolios, driving competitive intensity in the global lawn mowers market.
Key Player Analysis
- American Honda Motor Co., Inc.
- Ariens Company
- Briggs & Stratton
- Deere & Company
- Falcon Garden Tools
- Fiskars
- Husqvarna Group
- MTD Products
- Robert Bosch GmbH
- Robomow Friendly House
- The Toro Company
Recent Developments
- In February 2025, Husqvarna has introduced three new robot lawn mowers, none of which need boundary wires. In addition to the Automower 305E NERA and 405XE NERA models that are designed for smaller yards, there's also an improved version of the all-wheel-drive robot mower for difficult terrain, the Automower 435X AWD NERA..
- In February 2025, Eufy, a brand under Anker Innovations, has launched two new robotic lawn mowers-the Eufy Robot Lawn Mower E15 and E18-offering exclusive pre-sale access to current users in North America via the Eufy app until February 28. The products will be available for full retail sale on eufy.com and Amazon in April. Known for its smart home devices, Eufy is expanding into the lawn care market, aiming to bring the same innovation and convenience seen in its vacuums and security systems. The new mowers feature Eufy’s Vision Full-Self Driving (V-FSD 1.0) technology, enabling them to detect and avoid obstacles, identify lawn edges, and follow paths precisely. This move reinforces Eufy’s commitment to simplifying home maintenance through advanced automation.
- In January 2025, Husqvarna, a global leader in outdoor power products and robotics, announces two new robotic lawn mowers for commercial use. The new Automower® 535 AWD EPOS and Automower® 580L EPOS further Husqvarna's commitment to providing autonomous solutions and revolutionizing turf management for golf courses, sports fields, and facility maintenance.
- In January 2025, John Deere launched its latest innovation a fully electric, battery-powered autonomous zero-turn, stand-on mower. Featuring a 60-inch rear-discharge deck, the mower can operate both autonomously and manually with an operator. It includes integrated batteries, off-board charging options, and significantly reduces noise and emissions. Equipped with multiple cameras, GPS antennas, and wheel odometry, it ensures accurate navigation and object detection. Deere developed the mower by adapting its agricultural technology and collaborating with landscaping professionals to meet commercial needs.
- In October 2024: Briggs & Stratton licensed the Snapper brand to Daye North America, with a 60V line entering mass retail by spring 2025.
Market Concentration & Characteristics
The Lawn Mowers Market is moderately concentrated, with a few large global players holding significant market shares alongside several regional and niche manufacturers. It features a balanced mix of established brands and emerging companies competing on product innovation, price, and distribution. The market is driven by steady demand from both residential and commercial sectors, supported by growing consumer interest in automated and battery-powered equipment. It is characterized by seasonal sales patterns, strong demand for product durability, and increasing focus on eco-friendly designs. Companies differentiate through technological advancements, customer service, and multi-channel retail strategies, including a rapid shift toward online sales platforms.
Report Coverage
The research report offers an in-depth analysis based on Type, Offering, Propulsion Type, Level of Autonomy, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for electric and battery-powered lawn mowers is expected to grow significantly due to increasing environmental awareness and emission regulations.
- Robotic lawn mowers will gain rapid adoption, driven by rising consumer preference for automation and time-saving solutions.
- The growth of residential construction and urban green spaces will continue to boost lawn mower sales worldwide.
- Manufacturers will focus on developing lightweight, energy-efficient, and user-friendly lawn mowers to meet evolving consumer needs.
- Online sales channels will expand further, offering consumers greater product variety, price comparison, and purchasing convenience.
- Increasing disposable incomes in emerging economies will create new growth opportunities for mid-range and premium lawn mowers.
- Seasonal demand fluctuations will continue to pose inventory and revenue management challenges for market players.
- Battery life improvements and faster charging technologies will become key focus areas for product development.
- The competitive landscape will intensify as regional players introduce cost-effective models to capture price-sensitive markets.
- Integration of smart features like GPS tracking and remote control will become more common in new lawn mower models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Automation
Continuous innovation in battery technology, smart sensors, and autonomous navigation is making lawn mowers more efficient and user-friendly. The integration of features like GPS tracking and remote operation is driving adoption among both residential and commercial users seeking convenience and time savings.
Shift Toward Eco-friendly and Electric Models
Increasing environmental awareness and stricter emission regulations are accelerating the transition from internal combustion engine mowers to electric and battery-powered alternatives. Consumers and governments alike are prioritizing low-noise, low-emission equipment, boosting demand for electric lawn mowers.
Growth in Home Gardening and Landscaping
Urbanization and rising disposable incomes are encouraging homeowners to invest in lawn care and landscaping equipment. The trend toward DIY gardening and the desire for aesthetically pleasing outdoor spaces are fueling steady demand for walk-behind and robotic lawn mowers.
Expansion of Online Sales Channels
The proliferation of e-commerce platforms is making it easier for consumers to access a wide variety of lawn mower models, compare prices, and benefit from convenient delivery. This shift is particularly appealing to tech-savvy buyers and is expanding the market’s reach, especially in emerging economies.
Rising Adoption of Robotic Lawn Mowers
Busy lifestyles and the appeal of automated solutions are driving rapid growth in the robotic lawn mower segment. Features such as programmable schedules, rain sensors, and safety mechanisms are increasing the attractiveness of these products, especially in Europe and North America.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Lawn Mowers Market?
What are the key segments within the Lawn Mowers Market?
What are some challenges faced by the Lawn Mowers Market
Who are the major players in the Lawn Mowers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Riding Lawn Mowers
- 1.2.2 Walk-behind Lawn Mowers
- 1.2.3 Robotic Lawn Mowers
- 1.3 By Offering
- 1.3.1 Hardware
- 1.3.2 Software
- 1.4 By Propulsion Type
- 1.4.1 Electric
- 1.4.2 ICE (Internal Combustion Engine)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 34,212.40 million → 2032: USD 56,047.39 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lawn Mowers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lawn Mowers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lawn Mowers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lawn Mowers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lawn Mowers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lawn Mowers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lawn Mowers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lawn Mowers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 34,212.40 million → 2032: USD 56,047.39 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lawn Mowers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Riding Lawn Mowers
- 12.3.7.2 Walk-behind Lawn Mowers
- 12.3.7.3 Robotic Lawn Mowers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Offering - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Propulsion Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric
- 12.5.7.2 ICE (Internal Combustion Engine)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lawn Mowers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Lawn Mowers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Lawn Mowers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Deere & Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Husqvarna Group
- 17.4 The Toro Company
- 17.5 Briggs & Stratton
- 17.6 Robert Bosch GmbH
- 17.7 American Honda Motor Co., Inc.
- 17.8 Ariens Company
- 17.9 MTD Products
- 17.10 Robomow Friendly House
- 17.11 Fiskars
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

