
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Lawn Mower Market Size 2024 | USD 17,469 Million |
| Electric Lawn Mower Market, CAGR | 5.7% |
| Electric Lawn Mower Market Size 2032 | USD 27,218.73 Million |
Market Overview:
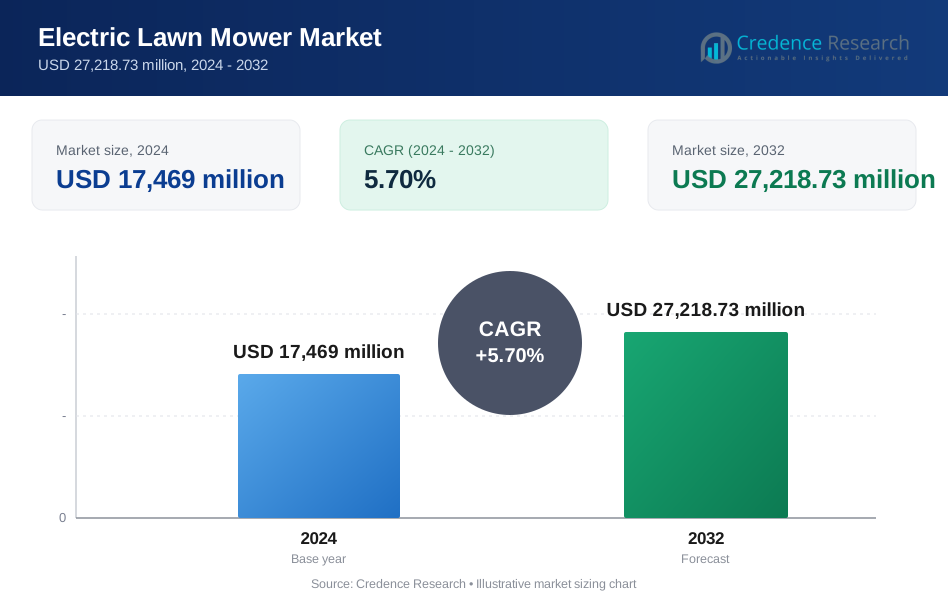
The Electric Lawn Mower Market is projected to grow from USD 17,469 million in 2024 to USD 27,218.73 million by 2032, with a compound annual growth rate (CAGR) of 5.7%.
The electric lawn mower market is being driven by growing consumer demand for eco-friendly, energy-efficient, and low-maintenance lawn care solutions. Increasing awareness about the environmental impact of traditional gasoline-powered mowers, coupled with the shift towards sustainable living, has accelerated the adoption of electric mowers. Additionally, advancements in battery technology, offering longer run times and faster charging, have enhanced the performance of electric mowers, making them more appealing to homeowners and commercial users. The rise in smart and robotic lawn mowers, equipped with GPS mapping, automation, and cloud-based route storage, is also gaining traction due to their convenience and efficiency. Furthermore, government incentives promoting the use of electric equipment and stricter emissions regulations are contributing to the market's growth. The trend of smart home integration and increasing popularity of DIY lawn care is expected to further propel the electric lawn mower market in the coming years.
The electric lawn mower market is experiencing significant growth across various regions, with North America leading the charge, accounting for the largest market share in 2024 due to strong demand in the U.S. and Canada. Europe follows closely with substantial adoption, driven by eco-conscious consumers and government regulations, holding around 30% of the market share. The Asia Pacific region is rapidly growing, driven by urbanization and rising disposable incomes, expected to capture approximately 20% of the market. The Rest of the World, including Latin America, the Middle East, and Africa, is witnessing gradual growth with a market share of 10-15%. Key players such as Husqvarna Group, Deere & Company, Briggs & Stratton, Honda Motor Co., Ltd., and others are strategically targeting these regions to expand their presence and cater to diverse consumer demands.
Market Insights:
- The electric lawn mower market is projected to grow from USD 17,469 million in 2024 to USD 27,218.73 million by 2032, with a CAGR of 5.7%.
- Increasing consumer demand for eco-friendly, energy-efficient, and low-maintenance lawn care solutions is driving market growth.
- Advancements in battery technology are improving performance, offering longer run times and faster charging.
- The rise in smart and robotic lawn mowers, equipped with GPS mapping, automation, and cloud-based features, is gaining momentum.
- Government incentives and regulations are boosting the adoption of electric mowers, promoting cleaner, sustainable alternatives to gasoline-powered mowers.
- North America is expected to hold the largest market share in 2024, driven by strong demand in the U.S. and Canada, with a market share of around 38%.
- Europe, Asia Pacific, and the Rest of the World are seeing increased adoption, with Europe at 30%, Asia Pacific at 20%, and the Rest of the World at 10-15% in 2024.
Market Drivers:
Growing Environmental Awareness:
One of the key drivers of the electric lawn mower market is the increasing environmental awareness among consumers. Traditional gasoline-powered mowers are known to emit harmful gases, contributing to air pollution and climate change. As consumers become more conscious of their carbon footprint, they are seeking eco-friendly alternatives. Electric lawn mowers, which produce zero emissions, are gaining popularity as they align with the growing trend toward sustainable living and eco-friendly practices. For instance, Greenworks offers a range of cordless electric mowers designed to provide emission-free lawn care solutions, appealing to environmentally conscious consumers.
Technological Advancements:
Advancements in battery technology have significantly boosted the performance of electric lawn mowers. Innovations such as longer battery life, faster charging times, and lightweight designs have made these mowers more efficient and practical for everyday use. For instance, EGO Power+ has developed lithium-ion battery-powered mowers with fast-charging capabilities and extended run times, enabling users to manage larger lawns with ease. The development of high-capacity lithium-ion batteries continues to enhance the durability and operational time of electric mowers, making them increasingly reliable and cost-effective.
Government Incentives and Regulations:
Government policies promoting sustainability and reducing emissions are contributing to the growth of the electric lawn mower market. Many regions offer incentives and rebates to consumers who switch to electric-powered equipment, making electric mowers more financially appealing. For instance, California has introduced regulations that ban the sale of gas-powered lawn equipment by 2024, further accelerating the shift toward electric mowers. Additionally, stricter emissions regulations are pushing manufacturers to develop and market cleaner, greener alternatives to gasoline-powered mowers.
Rise in Smart and Robotic Mowers:
The increasing demand for smart and robotic lawn mowers is another significant driver of the market. These mowers are equipped with advanced features such as GPS mapping, cloud-based route storage, and automated navigation, offering convenience and efficiency for both residential and commercial users. For instance, Husqvarna’s Automower series includes robotic mowers with GPS-assisted navigation and remote control via smartphone apps, delivering precision and ease for homeowners. The growing trend of smart home integration is also influencing the market, driving demand for these advanced systems.
Market Trends:
Increasing Demand for Cordless Electric Mowers:
A prominent trend in the electric lawn mower market is the rising demand for cordless models. Consumers are increasingly favoring cordless electric mowers due to their convenience and ease of use. These mowers offer greater mobility and eliminate the hassle of dealing with power cords, which makes them more versatile and ideal for medium to large-sized lawns. For instance, Ryobi offers cordless electric lawn mowers equipped with high-capacity lithium-ion batteries that provide extended run times, enabling users to mow large lawns effortlessly. As battery technology continues to improve, the range and power of cordless mowers are expanding, further contributing to their growing popularity.
Integration of Smart Technologies:
Another key trend is the integration of smart technologies into electric lawn mowers. Manufacturers are incorporating advanced features like GPS navigation, automated mowing schedules, and smartphone connectivity into their products. These innovations allow for enhanced efficiency and ease of operation, making lawn care more convenient for users. For instance, the Worx Landroid robotic mower connects to a smartphone app, allowing users to customize mowing schedules and receive real-time updates for a seamless experience. As consumers become more accustomed to smart home technologies, the demand for electric mowers with IoT capabilities is expected to rise.
Robotic Lawn Mowers Gaining Popularity:
The market for robotic electric lawn mowers is experiencing significant growth. These mowers can autonomously mow lawns, navigate around obstacles, and return to their charging stations without user intervention. Robotic mowers are particularly appealing to busy homeowners or commercial property managers seeking time-saving solutions. For instance, Husqvarna’s Automower series offers robotic mowers with advanced obstacle detection and self-charging features, delivering hands-free, efficient lawn care solutions. The increasing demand for hands-free, efficient solutions is propelling the popularity of robotic mowers, a trend that is expected to continue as technology improves.
Emphasis on Sustainable and Eco-friendly Solutions:
Sustainability remains a key trend influencing the electric lawn mower market. With a growing focus on reducing carbon footprints and minimizing environmental impact, more consumers are opting for electric mowers over traditional gasoline-powered models. The zero-emission feature of electric mowers aligns with the rising global emphasis on sustainability. For instance, Greenworks offers a wide range of zero-emission lawn mowers that operate on renewable energy-compatible charging systems, providing environmentally friendly solutions for homeowners. This trend is reinforced by government incentives and stricter environmental regulations, making electric mowers an attractive choice for environmentally conscious consumers.
Market Challenges Analysis:
High Initial Cost:
One of the primary challenges facing the electric lawn mower market is the high initial cost compared to traditional gasoline-powered mowers. Although electric mowers offer long-term savings on fuel and maintenance, the initial investment required for high-quality models-especially those with advanced features such as smart technologies, robotic capabilities, and larger battery capacities-can be a significant deterrent for consumers. While the total cost of ownership is lower over time, due to savings on fuel and the reduced need for servicing, the higher upfront price remains a major obstacle, especially in price-sensitive regions. This issue is most prominent in emerging markets, where affordability plays a critical role in purchasing decisions. Additionally, some consumers may perceive electric mowers as a premium product, leading them to hesitate when considering the switch from more affordable, traditional gasoline-powered alternatives. The market's ability to overcome this barrier will depend on further innovations in battery technology, production processes, and cost-reduction strategies, which could make electric mowers more accessible to a wider consumer base.
Limited Battery Life and Charging Time:
Another significant challenge in the electric lawn mower market is the limited battery life and relatively long charging times that affect some models. Despite advancements in battery technology, electric mowers still often fall short in terms of operational time compared to traditional gasoline-powered mowers, which can operate for extended periods without requiring a break. For users with large lawns or commercial properties, this can be a major drawback, as the mower may need to be recharged before the task is completed, leading to delays and interruptions in mowing. While lithium-ion batteries have improved in terms of energy density and efficiency, they still may not provide sufficient runtime for larger areas without requiring frequent recharging. Furthermore, although fast-charging technology is progressing, many electric mowers still take several hours to fully charge, which can be an inconvenience for users with tight schedules or large areas to maintain. Manufacturers must continue to focus on improving battery life and reducing charging times to meet the demands of both residential and commercial users.
Market Opportunities:
The electric lawn mower market presents significant growth opportunities driven by an increasing consumer preference for eco-friendly and sustainable solutions. As environmental concerns rise globally, more consumers are moving away from gasoline-powered mowers due to their harmful emissions and negative impact on air quality. The zero-emission nature of electric mowers positions them as an attractive alternative, particularly in markets with stringent environmental regulations. Additionally, government incentives and subsidies designed to promote green technologies are creating favorable conditions for the adoption of electric lawn mowers. As governments continue to push for cleaner, more sustainable solutions, consumers are likely to respond positively, further expanding the market. Manufacturers can capitalize on this opportunity by offering electric mowers that are cost-competitive and meet consumer expectations for efficiency, durability, and low maintenance.
Furthermore, the rise in smart home technologies offers substantial opportunities for innovation in the electric lawn mower market. Consumers are increasingly looking for convenient, automated solutions for lawn care, and the integration of features like GPS mapping, robotic navigation, and smartphone connectivity aligns perfectly with these demands. Robotic electric lawn mowers, which require minimal human intervention, are gaining popularity for their ability to autonomously manage lawn maintenance. As technology improves, electric mowers with advanced capabilities, such as automated scheduling and weather adaptation, are expected to become more mainstream. This trend, along with the growing interest in smart home ecosystems, creates significant opportunities for manufacturers to develop and market electric lawn mowers with enhanced automation and connectivity features, appealing to both residential and commercial consumers seeking efficient, hassle-free solutions.
Market Segmentation Analysis:
By Product Type
The electric lawn mower market is segmented by product type into push mowers, self-propelled mowers, and robotic mowers. Push mowers are ideal for smaller residential lawns, while self-propelled models cater to medium-sized lawns, offering convenience and ease of use. Robotic mowers, which are fully automated, are gaining traction for their hands-free operation, particularly in larger properties or commercial spaces, offering a high level of convenience.
By Cord Type
The market is further segmented based on cord type into corded and cordless electric mowers. Corded models are typically more affordable and provide consistent power, but they limit mobility due to the need for a power source. Cordless mowers, however, offer greater freedom of movement and are increasingly popular, especially as battery technology improves, providing longer runtimes.
By End User
The electric lawn mower market also caters to different end users, including residential, commercial, and industrial segments. Residential users seek electric mowers for their eco-friendliness, quiet operation, and convenience in maintaining smaller lawns. Commercial and industrial users prefer these mowers for their efficiency, sustainability, and ability to handle larger, more complex lawn care needs, particularly in the landscaping industry.
Segments:
Based on Product Type
- Ride-On
- Walk-behind
Based on Cord Type
- Corded
- Cordless
Based on End-user
- Residential
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
In 2024, North America is expected to hold the largest market share of the electric lawn mower market, with a significant portion of the global demand coming from the United States and Canada. The region is driven by a growing preference for environmentally friendly lawn care solutions, fueled by rising awareness of the environmental impacts of gasoline-powered equipment. Government incentives and stringent regulations aimed at reducing emissions further support the adoption of electric mowers in residential and commercial sectors. The widespread use of smart home technologies and automation also contributes to the rising popularity of robotic mowers. North America is expected to maintain a substantial share of the market in 2024, with the region likely accounting for 38% of the global market.
Europe
Europe is projected to be a strong market for electric lawn mowers, contributing a significant share to the overall global market in 2024, estimated at 30%. The region’s increasing focus on sustainability and green technologies is a major driving force behind the adoption of electric mowers. European countries like Germany, the UK, and France are leading the way in embracing eco-friendly alternatives for lawn maintenance, supported by government policies, environmental regulations, and consumer demand for low-emission products. Furthermore, the trend toward urbanization and smaller residential lawns has increased the demand for electric mowers, including robotic and cordless models. The European market benefits from a well-established market for smart and automated lawn care systems.
Asia Pacific
The Asia Pacific region is poised for rapid growth in the electric lawn mower market, with an anticipated market share of 20% in 2024. This growth is driven by rising disposable incomes, increasing urbanization, and growing environmental consciousness in countries like Japan, South Korea, and China. Additionally, the shift toward more sustainable and cost-effective lawn care solutions is contributing to the growing demand for electric mowers. The development of smart city infrastructure and the rising popularity of robotic lawn mowers further support the market's expansion. As more consumers in urban areas adopt electric mowers for residential and small-scale commercial use, the Asia Pacific market is expected to experience robust growth over the next few years.
Rest of the World In regions outside of the major markets such as Latin America, the Middle East, and Africa, the electric lawn mower market is still in the early stages of adoption. However, with an estimated market share of 15% in 2024, these areas are expected to see gradual growth. The increasing awareness of environmental issues, along with the rising middle-class population, will support market growth in these regions. The demand for electric mowers will be particularly strong in urban areas, where space and convenience drive the preference for smaller, more efficient lawn care solutions.
Key Player Analysis:
- Husqvarna Group
- Deere & Company
- Briggs & Stratton
- Robert Bosch GmbH
- RYOBI
- STIGA
- Honda Motor Co., Ltd.
- D&D Motor Systems Inc
- The Toro Company
- AriensCo
- Black+Decker
- Emak S.p.A.
Competitive Analysis:
The electric lawn mower market is highly competitive, with leading players such as Husqvarna Group, Deere & Company, Briggs & Stratton, Robert Bosch GmbH, RYOBI, STIGA, Honda Motor Co., Ltd., D&D Motor Systems Inc, The Toro Company, AriensCo, Black+Decker, and Emak S.p.A. dominating the landscape. These companies are continually innovating to capture market share, focusing on technological advancements such as longer battery life, improved charging times, and smart capabilities like GPS mapping and robotic navigation. For instance, Briggs & Stratton offers electric mowers with high-efficiency motors that reduce energy consumption while maintaining powerful performance. Moreover, strategic collaborations, acquisitions, and partnerships are common strategies to enhance product offerings and expand global reach. As consumer demand for eco-friendly solutions and automation grows, these companies are adjusting their product lines to cater to residential, commercial, and industrial sectors, intensifying competition in the rapidly expanding electric lawn mower market.
Recent Developments:
- In February 2023, Deere & Company introduced its first electric lawn mower, featuring a 3.2 kWh lithium-ion battery (with a maximum capacity of 3.56 kWh). This mower is capable of covering up to two acres on a single charge.
- In October 2023, Honda revealed its first battery-powered electric zero-turn riding (ZTR) mower, the Honda Autonomous Work Mower (AWM) prototype. Designed to boost worksite efficiency, this all-electric mower incorporates GPS-guided mapping and cloud-based route storage, making it an ideal solution for landscaping large properties.
- In March 2024, Segway, a leader in personal transportation and robotics, launched the highly anticipated Navimow I Series robotic lawn mower. This innovation represents a significant leap forward in automated lawn maintenance, offering unparalleled convenience, efficiency, and precision in lawn care.
- In 2023, Solis Tractors divulged new series of agricultural tractors and lawn mowers and promise to deliver cutting-edge technology, and high productivity for farming communities by emphasizing sustainability.
Market Concentration & Characteristics:
The electric lawn mower market exhibits moderate concentration, with a mix of well-established global players and emerging regional companies driving competition. Key market leaders, such as Husqvarna Group, Deere & Company, Honda Motor Co., Ltd., and The Toro Company, dominate the landscape, leveraging their established brand recognition, technological expertise, and extensive distribution networks. However, the market also includes smaller players and startups, particularly those focused on robotic and smart mowers, contributing to a diverse competitive environment. The characteristics of this market include rapid technological advancements, particularly in battery efficiency, automation, and smart features. Consumer demand is shifting toward eco-friendly and low-maintenance solutions, pushing manufacturers to innovate and offer sustainable, energy-efficient products. Additionally, market players are increasingly focusing on product differentiation, such as enhanced connectivity and automation features, to cater to evolving consumer preferences, while navigating pricing pressures and regulatory frameworks aimed at reducing emissions and promoting sustainability.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Cord Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for electric lawn mowers will continue to grow as consumers increasingly prioritize eco-friendly and sustainable solutions.
- Technological advancements in battery efficiency and charging times will improve the overall performance and convenience of electric mowers.
- The adoption of robotic lawn mowers will rise, driven by their automation, smart capabilities, and reduced need for human intervention.
- The integration of smart home technologies will further enhance the appeal of electric mowers, offering seamless connectivity and automated scheduling.
- Government incentives and stricter emissions regulations will create favorable conditions for the adoption of electric lawn mowers.
- Urbanization and the trend towards smaller lawns will drive demand for compact and easy-to-use electric lawn mowers.
- The commercial sector, particularly landscaping businesses, will increasingly turn to electric mowers to meet sustainability goals and reduce operational costs.
- The rise of DIY lawn care will contribute to greater interest in electric mowers, as consumers seek more efficient and user-friendly options.
- Global expansion in emerging markets will drive the adoption of electric mowers as consumer awareness of environmental impacts rises.
- Competition among manufacturers will intensify, leading to more innovative, cost-effective, and high-performance electric lawn mowers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Environmental Awareness
Consumers are increasingly aware of the environmental impact of gasoline-powered mowers, leading to a shift toward electric alternatives that produce zero emissions and support sustainable living.
Advancements in Battery Technology
Improvements in lithium-ion batteries have resulted in longer run times, faster charging, and lighter designs, making electric lawn mowers more practical and appealing for both residential and commercial users.
Government Incentives and Emissions Regulations
Policies such as rebates for electric equipment and bans on gas-powered mowers in certain regions are accelerating the adoption of electric lawn mowers by making them more financially attractive and necessary for compliance.
Rise of Smart and Robotic Mowers
The integration of automation, GPS mapping, and smart home connectivity in electric mowers is driving demand, as consumers and businesses seek convenient, efficient, and hands-free lawn care solutions.
Urbanization and DIY Lawn Care Trends
Increasing urbanization and the popularity of do-it-yourself lawn care are boosting demand for compact, easy-to-use electric mowers, especially in regions with smaller lawns and limited outdoor space.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Lawn Mower Market?
What factors are driving the growth of the Electric Lawn Mower Market?
What are the key segments within the Electric Lawn Mower Market?
What are some challenges faced by the Electric Lawn Mower Market?
Who are the major players in the Electric Lawn Mower Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Cord Type
- 1.3.1 Corded
- 1.3.2 Cordless
- 1.4 By Product Type
- 1.4.1 Ride-On
- 1.4.2 Walk-behind
- 1.4.3 Robotic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,469 million → 2032: USD 27,218.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Lawn Mower Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Lawn Mower Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Lawn Mower Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Lawn Mower Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Lawn Mower Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Lawn Mower Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Lawn Mower Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Lawn Mower Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,469 million → 2032: USD 27,218.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Lawn Mower Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Cord Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Corded
- 12.4.7.2 Cordless
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ride-On
- 12.5.7.2 Walk-behind
- 12.5.7.3 Robotic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Lawn Mower End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electric Lawn Mower Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electric Lawn Mower Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electric Lawn Mower Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Husqvarna Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Deere & Company
- 18.4 Briggs & Stratton
- 18.5 Robert Bosch GmbH
- 18.6 RYOBI
- 18.7 STIGA
- 18.8 Honda Motor Co., Ltd.
- 18.9 The Toro Company
- 18.10 AriensCo
- 18.11 Black+Decker
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

