
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Metalized Barrier Films Market Size 2024 | USD 2301.5 million |
| Metalized Barrier Films Market, CAGR | 3% |
| Metalized Barrier Films Market Size 2032 | USD 2915.47 million |
Market Overview:
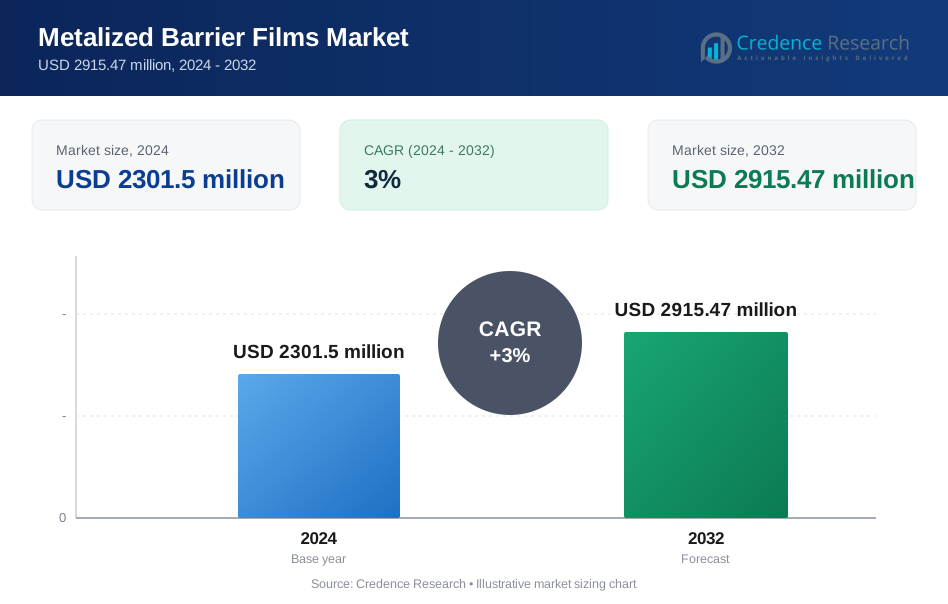
The Metalized Barrier Films Market is projected to grow from USD 2301.5 million in 2024 to an estimated USD 2915.47 million by 2032, with a compound annual growth rate (CAGR) of 3% from 2024 to 2032.
Key drivers of the metalized barrier films market include the increasing demand for packaging solutions that offer enhanced protection against moisture, oxygen, and light. These films are widely used in food and beverage packaging, pharmaceuticals, and electronics due to their superior barrier properties that extend the shelf life of products. As consumer demand for longer-lasting, fresh, and safe products continues to grow, metalized films are becoming a preferred choice for manufacturers. Additionally, the shift towards more sustainable packaging options is driving the development of eco-friendly metalized barrier films that are recyclable and reduce the environmental footprint of packaging. Technological advancements in film production processes are also contributing to market growth, allowing manufacturers to create thinner, more cost-effective, and high-performance barrier films. The ability to integrate metalized films with advanced coatings and laminates is expanding their applications across a variety of industries, including personal care, healthcare, and automotive sectors.
Regionally, North America and Europe are significant markets for metalized barrier films due to the presence of well-established industries and the high demand for innovative packaging solutions. In Asia Pacific, the growing consumer goods industry and rapid urbanization in countries like China and India are driving the adoption of metalized films. Furthermore, increasing investments in packaging infrastructure and consumer demand for premium products are expected to further fuel the market in the region. The Middle East and Latin America are also emerging as key markets, driven by the expansion of retail and foodservice industries.
Market Drivers:
Increasing Demand for Packaging Solutions with Enhanced Barrier Properties:
Consumer demand for packaging solutions that offer better protection against moisture, light, and oxygen is growing, particularly in sectors like food and beverages, pharmaceuticals, and electronics. Metalized barrier films are ideal for these applications because they provide superior shelf-life extension by protecting products from environmental factors that can degrade quality. For instance, The Food and Agriculture Organization (FAO) reports that about 1.3 billion tons of food are wasted every year globally, with packaging failures playing a significant role in food spoilage. Metalized barrier films are crucial in reducing food wastage by offering better protection compared to conventional packaging materials. In the U.S., the food packaging market is projected to grow by 3.6% annually over the next decade, with increasing demand for materials that preserve food quality for longer periods (source: U.S. Department of Agriculture, USDA). Additionally, in the pharmaceutical industry, the global market for blister packaging-a segment where metalized films are widely used-is expected to grow from USD 13 billion in 2021 to USD 22 billion by 2030, driven by the need for packaging that ensures drug safety, integrity, and shelf life (source: Global Data Healthcare).
Shifting Consumer Preferences for Sustainable Packaging Solutions:
Sustainability has become a major driver in packaging innovation, as consumers and governments push for more eco-friendly solutions. Consumers are increasingly concerned about the environmental impact of plastic packaging, and there is a growing preference for recyclable, biodegradable, or less resource-intensive alternatives. For instance, The United Nations Environment Programme (UNEP) projects that global plastic waste could increase by 40% by 2030 unless significant changes are made. As a result, companies are investing in more sustainable packaging solutions. Metalized films are evolving to meet these demands by being made recyclable or using eco-friendly materials. For example, Amcor, a global leader in packaging, has pledged to make 100% of its packaging recyclable or reusable by 2025, with a focus on developing more sustainable film solutions. In Europe, the European Union's Circular Economy Action Plan introduced in 2020 has set ambitious targets, such as ensuring that all packaging in the EU will be recyclable or reusable by 2030. As part of this push, companies are investing in developing sustainable packaging alternatives, including metalized barrier films made from recyclable materials (source: European Commission).
Technological Advancements in Film Production:
Technological advancements in film production are another key factor driving the growth of the metalized barrier films market. These innovations enable manufacturers to create films that are thinner, stronger, and more cost-effective, without compromising on performance. For instance, the National Institute of Standards and Technology (NIST) reports that advancements in nano-coating technologies are allowing manufacturers to produce high-performance metalized films with better barrier properties at a lower cost. A report indicates that the global smart packaging market, which includes metalized films integrated with technologies such as RFID tags and sensors, is expected to grow at 6.2% from 2021 to 2026. This technological progress has opened up new opportunities for metalized films in various industries, including pharmaceuticals, where smart packaging is used for anti-counterfeiting and temperature monitoring. In addition, Dow Chemicals has developed a technology that improves the durability and barrier properties of metalized films used in food packaging. Their innovation has led to a significant reduction in packaging material waste, with estimates suggesting a 20% reduction in film thickness while maintaining high barrier protection (source: Dow Chemicals).
Growing Demand in Emerging Markets:
Emerging markets in regions such as Asia-Pacific, Latin America, and the Middle East are significant drivers of growth in the metalized barrier films market. Urbanization, rising disposable incomes, and a growing middle class are leading to increased demand for packaged goods, especially in developing economies like China, India, and Brazil. For instance, China, as the largest consumer of packaging materials in Asia, saw an increase in food packaging demand by over 5% annually in 2020, driven by urbanization and growing consumer preferences for convenience foods. Similarly, India’s packaged food market is expected to grow by 17% annually from 2020 to 2025, as urbanization and a growing working population increase demand for ready-to-eat and shelf-stable food products (source: India Brand Equity Foundation). In Latin America, particularly in Brazil, the growing retail and foodservice industries are further fueling the demand for advanced packaging solutions. According to a World Bank report, Brazil’s retail sector is projected to grow by 4.5% annually from 2020 to 2025, which will drive the need for packaging materials like metalized barrier films to meet the increasing demand for packaged and processed food products.
Market Trends:
Rise of Sustainable Packaging Solutions:
Sustainability is becoming a core focus in the packaging industry, driven by growing consumer and regulatory demand for environmentally responsible materials. The packaging sector, including the use of metalized barrier films, is undergoing a transformation to meet these demands. Companies are increasingly focused on developing eco-friendly metalized films that are recyclable, reusable, and made from renewable resources. For instance, Amcor, a global packaging leader, has committed to using 100% recyclable or reusable packaging by 2025. This commitment extends to their work with metalized barrier films, where the company is developing films that are compatible with existing recycling systems to reduce environmental impact. Amcor's efforts align with the European Union's Circular Economy Action Plan, which mandates that all packaging in the EU must be recyclable by 2030. Such trends are encouraging manufacturers to adopt sustainable materials that not only meet regulatory standards but also appeal to the growing segment of environmentally-conscious consumers. Additionally, according to a United Nations Environment Programme (UNEP) report, global plastic packaging waste is expected to increase by 40% by 2030 unless substantial changes are made. As a result, there is increasing pressure on companies to develop sustainable alternatives to traditional plastic packaging, and metalized barrier films are a promising solution due to their high performance and recyclability potential.
Integration of Smart Packaging Technologies:
The growing demand for smarter, more functional packaging is a significant trend shaping the metalized barrier films market. Smart packaging incorporates technologies such as sensors, RFID tags, and QR codes to enhance the functionality of packaging beyond its traditional role of protecting products. These innovations are helping businesses provide more value to consumers while improving supply chain efficiency and product safety. For instance, the World Bank reports that the global smart packaging market is projected to grow rapidly in the coming years. Smart packaging, including metalized films with embedded sensors or anti-tampering features, is gaining traction in industries such as pharmaceuticals and food and beverages. This technology not only extends product shelf life but also allows real-time tracking and monitoring of conditions such as temperature and humidity, which is particularly important for perishable goods. A major player in this space, Dow Chemical, has been working on integrating these advanced technologies into metalized films for packaging. Dow’s work in developing intelligent packaging solutions has led to innovations where metalized films are paired with sensors that detect product freshness or alert consumers to potential spoilage, enhancing both consumer safety and convenience. These innovations reflect a growing trend of packaging becoming more interactive and functional, offering consumers added value beyond the product itself.
Market Challenge Analysis:
Sustainability and Environmental Concerns:
One of the primary challenges facing the metalized barrier films market is the growing demand for sustainable packaging solutions. As environmental awareness rises globally, both consumers and governments are increasingly focused on reducing plastic waste and improving recycling rates. Metalized films, particularly those made with aluminum, can be difficult to recycle due to the mixed-material layers that make up the film. This presents a significant hurdle for companies looking to align with stricter regulatory requirements and consumer expectations for eco-friendly products. For example, the European Union’s Circular Economy Action Plan, which aims to ensure that all packaging in the EU market is recyclable by 2030, poses a challenge for metalized film manufacturers, who must develop new materials or technologies to make their products more sustainable. Companies that fail to adapt to these sustainability demands may face reputational damage, increased regulatory scrutiny, or even a decline in market share as consumers shift toward greener alternatives. The difficulty in recycling metalized films also extends to the packaging supply chain, where recycling infrastructure in many regions is still underdeveloped or inefficient. Despite the push for innovation in recyclable packaging solutions, such as biodegradable films or films made from renewable materials, the current recycling systems are not fully equipped to handle complex materials like metalized films. The lack of effective end-of-life solutions for these products contributes to environmental concerns, making it crucial for manufacturers to invest in R&D and new technologies. Developing metalized films that are fully recyclable or made from eco-friendly materials without sacrificing performance and barrier properties remains a significant challenge. Until more sustainable alternatives become widely available and viable, metalized films may face continued pressure from both regulators and environmentally-conscious consumers.
Cost and Performance Balance:
Another significant challenge for the metalized barrier films market is balancing cost with performance. Metalized films offer excellent barrier properties, making them highly effective for applications in food packaging, pharmaceuticals, and electronics. However, the production of these films can be expensive, especially when advanced technologies such as vacuum metalizing or sputtering are used. These processes, while providing superior quality, can drive up production costs, which in turn increases the overall price of the final product. As a result, manufacturers are under constant pressure to innovate and reduce production costs without compromising the effectiveness of the films. In particular, the food and beverage industry, where cost efficiency is crucial, may look for alternative, more affordable packaging solutions that offer similar protection but at a lower price point. Moreover, fluctuations in the prices of raw materials, such as aluminum and petroleum-based plastics, can significantly impact production costs for metalized films. The volatile nature of these materials’ pricing makes it difficult for manufacturers to maintain consistent margins, particularly when trying to offer competitively priced products in a market that demands both high performance and low cost. This creates a delicate balancing act for companies that must ensure their films meet stringent performance standards-such as maintaining freshness, durability, and product integrity-while remaining cost-effective. As global supply chains continue to face disruptions and the cost of raw materials increases, this challenge is expected to become even more pronounced, pushing manufacturers to explore new materials, production methods, and business models to mitigate cost-related pressures.
Market Segmentation Analysis:
By Type:
The metalized barrier films market can be segmented based on the type of materials used in their production. These include aluminum-based, PET (Polyethylene Terephthalate) based, and other specialty films. Aluminum-based metalized films are widely used due to their superior barrier properties, especially in applications where light and oxygen protection is critical, such as in food packaging and pharmaceuticals. PET-based metalized films are increasingly gaining popularity, offering an excellent balance of barrier performance, mechanical strength, and flexibility. These films are used in a variety of packaging applications, particularly in the food and beverage industry. Other specialty films, including those made from biodegradable materials, are seeing increasing adoption due to growing consumer demand for sustainable packaging solutions.
By Technology:
The metalized barrier films market is also segmented based on the technology used in the production process. Common technologies include vacuum metalizing, sputtering, and chemical vapor deposition (CVD). Vacuum metalizing is the most widely used technique, as it is cost-effective and produces films with strong barrier properties. Sputtering is gaining traction in certain high-tech applications due to its ability to produce uniform coatings on a variety of substrates. Chemical vapor deposition (CVD) is a more advanced process that creates films with enhanced durability and flexibility, suitable for high-end applications such as electronics and medical packaging.
By End-User:
The metalized barrier films market serves a wide range of end-users, including food and beverage, pharmaceuticals, personal care, electronics, and others. The food and beverage industry is the largest consumer of metalized barrier films, driven by the need for longer shelf life and better product protection. The pharmaceutical sector also represents a significant segment due to the increasing demand for tamper-evident packaging and protection of sensitive medications from environmental factors. Personal care and cosmetics packaging is another growing application, where metalized films are used to enhance the aesthetic appeal and provide protection against moisture. The electronics industry is adopting metalized films for packaging components that need to be shielded from moisture and static. Other industries, including automotive and consumer goods, also contribute to the growing demand for metalized films, driven by their unique combination of protective and functional properties.
Segmentation:
Based on Product Type:
- Aluminum-based Metalized Films
- PET-based Metalized Films
- Other Specialty Metalized Films
Based on Technology:
- Vacuum Metalizing
- Sputtering
- Chemical Vapor Deposition (CVD)
Based on End-User:
- Food and Beverage
- Pharmaceuticals
- Personal Care and Cosmetics
- Electronics
- Other Industries (Automotive, Consumer Goods, etc.)
Based on Region:
-
- North America
- United States
- Canada
- Europe
- United Kingdom
- Germany
- France
- Asia-Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Mexico
- Middle East & Africa
- South Africa
- United Arab Emirates
- North America
Regional Analysis:
North America
North America holds a significant share of the global metalized barrier films market, contributing approximately 30% of the market share. The region’s demand for metalized films is primarily driven by the food and beverage, pharmaceutical, and personal care industries, which require high-performance packaging solutions. The United States, as the largest market in North America, plays a key role in this growth due to its well-established industries and high consumption of packaged food and pharmaceutical products. The demand for premium packaging in food, where metalized films provide enhanced shelf life and protection, is particularly strong. Furthermore, the growing focus on sustainable packaging solutions in the region is pushing companies to develop recyclable or biodegradable versions of metalized films, responding to environmental concerns and regulatory pressures. The U.S. Food and Drug Administration (FDA) and other regulatory bodies in North America have stringent packaging standards, especially for pharmaceuticals and food products. This has led to increased use of metalized barrier films that meet these standards for tamper-evidence and product integrity. In addition, the rising preference for e-commerce in North America has driven the demand for packaging that ensures product protection during transport. This shift toward more premium packaging materials for online retail has created new opportunities for metalized films. However, North America’s market growth is also challenged by the high production costs associated with metalized films, which could limit their adoption in cost-sensitive applications.
Europe
Europe accounts for around 28% of the global metalized barrier films market share, with significant contributions from countries like Germany, France, the United Kingdom, and Italy. The region’s demand for metalized films is influenced by both consumer preferences for high-quality packaging and strict environmental regulations. Europe is at the forefront of the sustainability movement, with the European Union's Circular Economy Action Plan aiming to make all packaging in the region recyclable or reusable by 2030. This regulatory push has encouraged metalized film manufacturers to innovate, creating films that are more sustainable without compromising performance. The demand for recyclable metalized films is growing as both governments and consumers push for greener packaging solutions. In the food and beverage industry, metalized films are used extensively due to their ability to extend shelf life while protecting products from oxygen, moisture, and light. The pharmaceutical sector in Europe also demands metalized barrier films for packaging sensitive products such as medicines, vaccines, and medical devices. Furthermore, the personal care and cosmetics industry, where packaging aesthetics and product protection are critical, continues to be a strong consumer of metalized films in Europe. Despite the challenges of balancing sustainability with performance, manufacturers are heavily investing in R&D to produce eco-friendly metalized films that meet both regulatory standards and market demands. The increasing adoption of flexible packaging in Europe also drives the growth of the metalized films market, as these films are well-suited for flexible packaging solutions.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the global metalized barrier films market, contributing around 35% of the market share. The region’s rapid industrialization, growing middle class, and rising demand for packaged goods are major factors driving this growth. Countries such as China, India, Japan, and South Korea are witnessing significant demand for metalized films, particularly in the food and beverage sector, where the need for extended shelf life and product protection is paramount. The growing urban population in Asia-Pacific is leading to an increase in demand for packaged, processed, and ready-to-eat foods, further fueling the need for metalized barrier films. China, as the largest consumer of packaging materials in Asia, is seeing rapid adoption of metalized films for food packaging, electronics, and pharmaceuticals. The country’s expanding middle class and increasing disposable incomes are driving the demand for premium packaged products. Similarly, India’s expanding retail and e-commerce sectors are boosting the need for protective packaging solutions, creating opportunities for metalized films. Additionally, the pharmaceutical and healthcare industries in countries like Japan and South Korea are also significant contributors to the market, as metalized films are used to package medications and medical devices that require protection from moisture and air. The demand for sustainable packaging solutions in Asia-Pacific is growing, with governments in countries like Japan and South Korea setting ambitious recycling and waste management targets. However, the region also faces challenges related to the availability of recycling infrastructure, which may hinder the widespread adoption of fully recyclable metalized films. Despite these challenges, Asia-Pacific is expected to continue its strong growth trajectory, driven by the increasing consumption of packaged goods and the rise of urbanization and disposable income in the region.
Key Player Analysis:
- Uflex Ltd.
- Polyplex Corporation Ltd.
- DUNMORE Corporation Ltd.
- Jindal Poly Films Ltd.
- Bemis Company Inc.
- Amcor Ltd.
- Mondi Group plc
- Henkel AG & Co. KGaA
- SRF Limited
- Forum Packaging
- Cosmo Films Ltd.
- Toray Plastics (America), Inc
Competitive Analysis:
The metalized barrier films market is highly competitive, with several global and regional players vying for market share. Key industry leaders include Amcor, Dow Chemical, Berry Global, and Mondi Group, all of which offer a wide range of packaging solutions, including metalized films, for industries such as food and beverage, pharmaceuticals, and personal care. These companies focus heavily on innovation, sustainable packaging, and meeting regulatory requirements, particularly in response to growing consumer and government demands for eco-friendly materials. Amcor, for example, has committed to making all of its packaging recyclable or reusable by 2025, while Mondi has introduced recyclable metalized films to address sustainability concerns. In addition to product innovation, these companies are expanding their geographical presence, particularly in emerging markets like Asia-Pacific, where rising demand for packaged goods is driving growth. Smaller regional players also compete by focusing on niche markets or offering specialized products, such as biodegradable or lower-cost metalized films. However, the competitive landscape is also shaped by the increasing pressure to reduce production costs while maintaining the performance of metalized films. This has led to greater emphasis on cost-efficient manufacturing techniques, such as vacuum metalizing and sputtering, which help reduce production expenses without compromising quality. Additionally, as regulatory frameworks tighten, especially in Europe and North America, companies must continuously adapt to meet sustainability and recycling targets, further intensifying competition in the market. The competitive dynamics are likely to remain focused on innovation, cost management, and sustainable practices.
Recent Developments:
- In February 2024, UFlex showcased a range of innovative products, including the "Nutri" series from Flexure SF for food packaging, pharma, and hygiene applications. The company also presented barrier films such as B-INM-M, C-CPM-ML-M, CPP metalized film, and C-CBP-WG CPP film.
- In October 2023, Australian brand Madura Tea adopted Koehler NexPlus Seal Pure MOB 72 gsm flexible paper packaging. Gundlach Packaging Group and Koehler Paper, both German suppliers, provided the test materials following promising results.
- In May 2023, UFlex introduced several new products in Q4 FY23, including a metalized high-barrier tear polyester film for packaging applications, with a focus on research-driven innovation and sustainability.
Market Concentration & Characteristics:
The metalized barrier films market exhibits moderate concentration, with a mix of global giants and regional players. A few key players, such as Amcor, Berry Global, Mondi Group, and Sealed Air, dominate the market, accounting for a significant share due to their broad product offerings, extensive distribution networks, and continuous innovation in sustainable packaging solutions. These large companies invest heavily in R&D to enhance film performance and develop eco-friendly alternatives, such as recyclable and biodegradable metalized films, in response to increasing environmental concerns. At the same time, smaller players and regional manufacturers contribute to the market by focusing on specialized applications or catering to local industries. For instance, companies in Asia-Pacific may tailor their metalized films to meet the specific needs of fast-growing sectors like food packaging and e-commerce. The market is characterized by a high level of product differentiation, as companies strive to provide innovative solutions that address the unique needs of different industries, including food and beverage, pharmaceuticals, and electronics. The demand for higher barrier properties, extended shelf life, and tamper-evidence in packaging continues to drive innovation in metalized films. Additionally, as sustainability becomes a key consumer and regulatory priority, the development of recyclable and environmentally friendly metalized films is gaining importance. Despite the competitive pressure from new entrants and smaller players, the market remains consolidated around a few dominant firms with significant resources and global reach, allowing them to influence pricing, standards, and innovation trends across the industry.
Report Coverage:
This report provides a comprehensive analysis of the metalized barrier films market, covering key aspects such as market trends, drivers, challenges, segmentation, regional dynamics, and competitive landscape. It explores the market's growth across different types of metalized films, including aluminum-based, PET-based, and specialty films, as well as the technologies used in their production, such as vacuum metalizing, sputtering, and chemical vapor deposition (CVD). The report delves into the end-user industries driving demand, particularly in food and beverage packaging, pharmaceuticals, personal care, and electronics. It also analyzes the geographical dynamics of the market, with a detailed focus on North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, highlighting regional market share, growth potential, and the impact of regulatory policies and sustainability efforts. Furthermore, the report provides an in-depth competitive analysis, profiling key market players like Amcor, Dow Chemical, Mondi Group, and Berry Global, among others. It examines their strategies, market positioning, and innovations, as well as the ongoing challenges related to sustainability and production costs. The report also offers a forward-looking perspective on market opportunities, emerging trends in smart packaging and eco-friendly materials, and the evolving demand for advanced barrier properties. By addressing these critical factors, the report aims to provide valuable insights for manufacturers, investors, and stakeholders to make informed decisions in the rapidly evolving metalized barrier films market.
Future Outlook:
- The demand for metalized barrier films will continue to rise due to their superior protection against moisture, light, and oxygen, essential for extending product shelf life.
- Sustainability will remain a key driver, with companies focusing on creating recyclable and eco-friendly metalized films in response to environmental concerns and regulatory pressures.
- Technological advancements will enhance the performance and versatility of metalized films, making them thinner, lighter, and more cost-effective without compromising quality.
- The growth of the e-commerce sector will increase demand for durable, protective packaging solutions, further driving the adoption of metalized barrier films.
- The food and beverage industry will continue to be a dominant consumer of metalized films, particularly as consumer demand for fresh, shelf-stable products increases.
- The pharmaceutical sector will also see growing usage of metalized films due to their ability to provide tamper-evident packaging and protect sensitive drugs from environmental factors.
- Integration of smart technologies into metalized films, such as RFID tags and sensors, will make packaging more functional and interactive.
- The Asia-Pacific region will lead global demand, driven by rapid urbanization, population growth, and rising middle-class disposable income.
- Regulatory changes, such as stricter packaging waste management laws, will push companies to adopt more sustainable materials.
- Investment in R&D will accelerate, leading to innovations that meet both performance and environmental sustainability goals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Enhanced Barrier Packaging
Metalized barrier films offer superior protection against moisture, oxygen, and light, which is critical for extending the shelf life of food, beverages, and pharmaceuticals. This drives adoption in industries where product integrity and freshness are essential.
Shift Toward Sustainable Packaging
Growing consumer and regulatory pressure for eco-friendly packaging is pushing manufacturers to develop recyclable and biodegradable metalized films. Companies are investing in sustainable solutions to meet environmental targets and appeal to environmentally conscious consumers.
Technological Advancements in Film Production
Innovations such as nano-coating, advanced vacuum metalizing, and thinner film production are enabling manufacturers to deliver high-performance, cost-effective barrier films. These advancements expand application possibilities and improve the cost-to-performance ratio.
Growth in Emerging Markets and E-commerce
Rapid urbanization, rising disposable incomes, and the expansion of e-commerce in Asia-Pacific, Latin America, and the Middle East are increasing demand for packaged goods. This, in turn, fuels the need for advanced protective packaging like metalized barrier films.
Integration of Smart Packaging Features
The adoption of smart packaging technologies, such as RFID tags and sensors embedded in metalized films, is enhancing product safety, traceability, and consumer engagement, particularly in food and pharmaceutical applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Metalized Barrier Films Market?
What are the key drivers for the growth of the Metalized Barrier Films Market?
Which industries use metalized barrier films the most?
How are technological advancements affecting the Metalized Barrier Films Market?
Which regions are driving growth in the Metalized Barrier Films Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Food and Beverage
- 1.2.2 Pharmaceuticals
- 1.2.3 Personal Care and Cosmetics
- 1.2.4 Electronics
- 1.2.5 Other Industries (Automotive, Consumer Goods, etc.)
- 1.3 By Technology
- 1.3.1 Vacuum Metalizing
- 1.3.2 Sputtering
- 1.3.3 Chemical Vapor Deposition (CVD)
- 1.4 By Product Type
- 1.4.1 Aluminum-based Metalized Films
- 1.4.2 PET-based Metalized Films
- 1.4.3 Other Specialty Metalized Films
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2301.5 million → 2032: USD 2915.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Metalized Barrier Films Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Metalized Barrier Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Metalized Barrier Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Metalized Barrier Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Metalized Barrier Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Metalized Barrier Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Metalized Barrier Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Metalized Barrier Films Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2301.5 million → 2032: USD 2915.47 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Metalized Barrier Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food and Beverage
- 12.3.7.2 Pharmaceuticals
- 12.3.7.3 Personal Care and Cosmetics
- 12.3.7.4 Electronics
- 12.3.7.5 Other Industries (Automotive, Consumer Goods, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Vacuum Metalizing
- 12.4.7.2 Sputtering
- 12.4.7.3 Chemical Vapor Deposition (CVD)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aluminum-based Metalized Films
- 12.5.7.2 PET-based Metalized Films
- 12.5.7.3 Other Specialty Metalized Films
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Metalized Barrier Films End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Metalized Barrier Films Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Metalized Barrier Films Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Metalized Barrier Films Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mondi Group plc
- 18.4 Uflex Ltd.
- 18.5 Polyplex Corporation Ltd.
- 18.6 Jindal Poly Films Ltd.
- 18.7 Bemis Company Inc.
- 18.8 Cosmo Films Ltd.
- 18.9 Toray Plastics (America), Inc
- 18.10 Berry Global Inc.
- 18.11 SRF Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

