
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Mexico Stem Cell Contract Manufacturing Market Size 2024 | USD 50.93 Million |
| Mexico Stem Cell Contract Manufacturing Market, CAGR | 10.51% |
| Mexico Stem Cell Contract Manufacturing Market Size 2032 | USD 113.27 Million |
Market Overview:
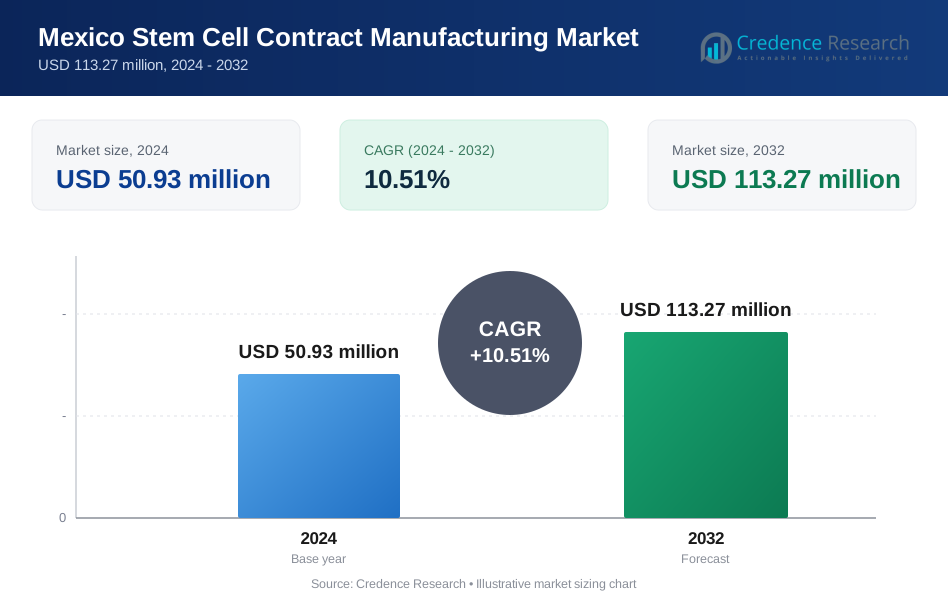
The Mexico Stem Cell Contract Manufacturing Market is projected to grow from USD 50.93 million in 2024 to an estimated USD 113.27 million by 2032, with a compound annual growth rate (CAGR) of 10.51% from 2024 to 2032.
Several factors are driving the growth of the stem cell contract manufacturing market in Mexico. Firstly, the rising prevalence of chronic diseases such as diabetes, cardiovascular disorders, and neurological conditions has heightened the need for innovative therapeutic solutions, including stem cell-based therapies. Additionally, advancements in stem cell research and manufacturing technologies have facilitated the development of scalable and efficient production processes, reducing costs and increasing accessibility. Mexico’s strategic location, cost-effective manufacturing capabilities, and skilled workforce have further attracted investments from international pharmaceutical and biotechnology companies seeking to outsource their manufacturing operations.Government initiatives and regulatory frameworks supporting the biotechnology and life sciences sectors have also played a crucial role in market development. Regulatory bodies in Mexico, such as COFEPRIS (Federal Commission for Protection Against Sanitary Risks), have implemented guidelines to streamline the approval processes for cell-based therapies and manufacturing practices, fostering confidence among investors and stakeholders. Furthermore, collaborations between academic institutions, research organizations, and industry players have created a robust ecosystem for innovation, further driving market growth.
Mexico’s central and northern regions are emerging as key hubs for stem cell contract manufacturing due to the presence of established research institutions and manufacturing facilities. Cities such as Monterrey, Guadalajara, and Mexico City are particularly notable for their advanced infrastructure and concentration of biotechnology firms. These regions benefit from proximity to the United States, which allows companies to leverage cross-border trade agreements, such as the USMCA (United States-Mexico-Canada Agreement), to access broader markets and expand their customer base. The northern states of Mexico, including Baja California, are also gaining traction as strategic locations for contract manufacturing facilities. Their geographical proximity to California, a global biotechnology hub, facilitates knowledge transfer and collaboration with leading players in the industry. Additionally, the coastal regions provide logistical advantages for importing raw materials and exporting finished products to international markets.
Market Insights:
- The Mexico stem cell contract manufacturing market is set to grow significantly, driven by a strong CAGR of 10.51% from 2024 to 2032, reflecting the increasing demand for scalable therapeutic solutions.
- Rising incidences of chronic diseases, such as diabetes and neurodegenerative disorders, are fueling the need for stem cell-based therapies, creating a robust demand for contract manufacturing services.
- Advances in manufacturing technologies, such as bioreactors and automated systems, are enhancing efficiency and reducing production costs, making Mexico a competitive hub for stem cell manufacturing.
- Strategic geographic proximity to the U.S. and inclusion in trade agreements like the USMCA offer manufacturers seamless access to global markets and opportunities for cross-border collaboration.
- Government support through COFEPRIS regulations and policies has streamlined therapy approval processes, attracting investments from international biopharmaceutical companies.
- Northern regions like Baja California and central hubs such as Mexico City and Guadalajara dominate the market due to their infrastructure, proximity to key markets, and thriving biotech ecosystems.
- Despite its growth potential, the market faces challenges, including high technology costs, limited local expertise, and competition from established global hubs, requiring strategic investments and collaborations to overcome these hurdles.
Market Drivers:
Increasing Prevalence of Chronic Diseases
The rising burden of chronic diseases such as diabetes, cardiovascular disorders, and neurodegenerative conditions is a significant driver of the Mexico stem cell contract manufacturing market. With a growing aging population and a higher incidence of these conditions, the demand for innovative therapeutic solutions like stem cell-based treatments has surged. For instance, according to the International Diabetes Federation (IDF), approximately 14.1 million adults in Mexico were living with diabetes in 2022, accounting for nearly 17% of the adult population. Stem cells offer promising regenerative capabilities that can address unmet medical needs, making them a key focus area for biopharmaceutical companies. This growing demand for stem cell therapies has created a robust need for scalable and efficient manufacturing services, positioning Mexico as a preferred location for contract manufacturing.
Advancements in Stem Cell Research and Technology
Continuous advancements in stem cell research and manufacturing technologies are another critical driver of the market. Innovations in cell culture systems, bioreactors, and cryopreservation techniques have significantly improved the scalability, quality, and cost-efficiency of stem cell production. For instance, advancements in bioreactor technology have enabled the production of larger quantities of stem cells with consistent quality. Additionally, the development of induced pluripotent stem cells (iPSCs) and human embryonic stem cells (hESCs) has expanded the scope of therapeutic applications. Mexico's growing investment in biotechnology infrastructure and its ability to adopt these advanced technologies make it an attractive destination for global players seeking to outsource their manufacturing operations.
Strategic Geographic Location and Cost Efficiency
Mexico’s strategic location, close to the United States and other Latin American markets, is a major advantage for the stem cell contract manufacturing industry. The country’s inclusion in trade agreements like the USMCA provides manufacturers with access to larger markets, enabling easier cross-border trade and collaboration. Additionally, Mexico offers cost-efficient manufacturing solutions, including lower labor and operational costs compared to other regions, without compromising on quality. This cost advantage has drawn international biopharmaceutical companies to invest in and partner with local manufacturers, further driving market growth. For instance, a report by ProMéxico highlighted that the country's manufacturing costs are lower than those in the United States
Supportive Government Policies and Collaborations
The Mexican government has played a pivotal role in fostering the growth of the stem cell manufacturing market through supportive policies and regulatory frameworks. COFEPRIS has implemented guidelines to streamline the approval processes for stem cell therapies, ensuring safety and compliance while reducing time to market. Additionally, collaborations between academic institutions, research organizations, and industry players have created a dynamic ecosystem that encourages innovation and knowledge sharing. For instance, the National Autonomous University of Mexico (UNAM) collaborates with various biotech firms to advance stem cell research and applications. These partnerships have not only advanced stem cell research but also strengthened Mexico’s capabilities in large-scale manufacturing, making the country a hub for stem cell contract manufacturing in the region.
Market Trends:
Rising Adoption of Automation in Stem Cell Manufacturing
The Mexico stem cell contract manufacturing market is witnessing a significant trend toward automation and advanced biomanufacturing processes. Companies are increasingly integrating automated systems to enhance efficiency, reduce human error, and improve scalability in stem cell production. For instance, Terumo Blood and Cell Technologies has expanded its offerings in Mexico, implementing automated manufacturing platforms to support cell and gene therapy developers. Technologies like automated cell culture systems and bioreactors are being adopted to meet the growing demand for high-quality, reproducible stem cell products. These advancements have not only streamlined production processes but also contributed to cost optimization, making Mexico a competitive location for international players seeking to outsource stem cell manufacturing.
Increasing Focus on Personalized Medicine
Personalized medicine has emerged as a key trend, driving the demand for autologous stem cell therapies. As the healthcare sector moves toward patient-specific treatments, contract manufacturers in Mexico are developing capabilities to produce small-batch, customized stem cell therapies. For instance, the Immunotherapy Regenerative Medicine Clinic in Puerto Vallarta offers personalized stem cell treatments tailored to individual patient needs. This trend is supported by the growing prevalence of chronic diseases and advancements in cell therapy research. The development of induced pluripotent stem cells (iPSCs) is playing a pivotal role in enabling personalized medicine, as they allow the generation of patient-specific cell lines for targeted therapies.
Expansion of Collaborative Ecosystems
Collaborations between academia, research institutions, and industry players are shaping the future of stem cell contract manufacturing in Mexico. These partnerships are fostering innovation by pooling resources, expertise, and funding to develop new manufacturing techniques and therapeutic applications. For instance, research organizations in Mexico City and Monterrey are working closely with biopharmaceutical companies to bridge the gap between early-stage research and large-scale manufacturing. Such collaborations are not only driving innovation but also attracting foreign investments, further strengthening the country’s position in the global market.
Growing Preference for Allogeneic Stem Cell Therapies
Allogeneic stem cell therapies are gaining traction in Mexico due to their scalability, lower production costs, and broader applicability compared to autologous therapies. Contract manufacturers are increasingly focusing on the development of standardized allogeneic stem cell products to cater to the rising demand. For instance, Stem Cell Therapy Mexico uses allogeneic mesenchymal stem cells obtained through a cryopreservation process that ensures high viability at the time of transplantation. This trend is particularly prominent in treating chronic conditions like cardiovascular and neurological disorders, where off-the-shelf solutions are more practical. Moreover, advancements in storage and transport technologies for stem cell products are enabling greater adoption of allogeneic therapies, enhancing their accessibility in domestic and international markets.
Market Challenges Analysis:
Regulatory Complexity
The stem cell contract manufacturing market in Mexico faces challenges associated with navigating complex and evolving regulatory frameworks. While COFEPRIS has made efforts to streamline approval processes, discrepancies in regulatory alignment with international standards may pose difficulties for companies seeking global market access. These regulatory complexities can delay product launches and increase compliance costs, especially for smaller manufacturers with limited resources.
High Costs of Advanced Technologies
The adoption of cutting-edge manufacturing technologies, such as automation and bioreactors for scalable stem cell production, requires significant upfront investment. Smaller and mid-sized firms may struggle to allocate sufficient funds for infrastructure upgrades, limiting their ability to compete with larger players. Furthermore, the high costs associated with research and development in stem cell technologies act as a barrier to entry for new players.
Limited Local Expertise
Although Mexico has a skilled workforce, the market faces a shortage of specialized expertise in advanced stem cell manufacturing and bioprocessing. This gap can hinder the adoption of complex technologies and reduce efficiency in production processes. Companies often need to rely on international collaborations or training programs, which can be time-consuming and costly.
Global Competition
Mexico's market also faces competition from established stem cell manufacturing hubs in regions such as North America, Europe, and Asia. These regions often have more advanced infrastructure, established networks, and larger pools of funding, making it challenging for Mexican firms to attract global clients and retain market share.
Ethical Concerns and Public Perception Ethical debates surrounding the use of certain types of stem cells, such as embryonic stem cells, could limit public acceptance and investor interest in specific segments of the market. These concerns may require firms to focus on transparent practices and rigorous ethical compliance.
Market Opportunities:
The Mexico stem cell contract manufacturing market presents significant opportunities driven by the increasing global demand for regenerative medicine and advanced cell-based therapies. Mexico’s cost-effective manufacturing capabilities, skilled workforce, and strategic proximity to the United States make it an attractive destination for international biopharmaceutical companies seeking to outsource stem cell production. The growing prevalence of chronic diseases such as diabetes, cardiovascular disorders, and neurodegenerative conditions has heightened the demand for stem cell therapies, fueling the need for scalable and efficient manufacturing solutions. Additionally, Mexico’s participation in trade agreements like the USMCA enhances access to global markets, providing manufacturers with opportunities to expand their customer base and establish a strong presence in the Americas.
Government initiatives and regulatory support, particularly through COFEPRIS, further strengthen Mexico’s appeal as a hub for stem cell manufacturing. Streamlined approval processes and incentives for innovation encourage investments in state-of-the-art facilities and research collaborations. Emerging technological advancements, such as automation in biomanufacturing and the development of novel stem cell sources like iPSCs, open doors for innovation and cost optimization. Furthermore, the increasing collaboration between academic institutions, research organizations, and industry players fosters a robust ecosystem for innovation. With continued advancements in stem cell research and manufacturing technologies, Mexico is well-positioned to attract new entrants and solidify its role as a key player in the global stem cell contract manufacturing industry. The combination of strategic advantages and rising demand creates immense potential for growth and innovation in this market.
Market Segmentation Analysis:
The Mexico stem cell contract manufacturing market is segmented based on the scale of operation, size of contract manufacturers, source of stem cells, type of stem cells, and end-user, each playing a distinct role in shaping the market's dynamics.
By Scale of Operation, the market is divided into commercial, clinical, and preclinical operations. The commercial segment holds the largest share due to the growing demand for large-scale production of stem cell therapies. Clinical and preclinical operations are driven by increasing research and clinical trials in regenerative medicine.
By Size of Contract Manufacturer, the market is categorized into large/very large, mid-sized, and small-sized manufacturers. Large manufacturers dominate the market due to their advanced infrastructure and ability to meet global regulatory standards, while mid-sized and small-sized firms cater to niche and local demands.
By Source of Stem Cells, the market is segmented into allogenic and autologous stem cells. Allogenic stem cells account for a significant share, owing to their scalability and cost-effectiveness, while autologous stem cells are preferred for personalized therapies.
By Type of Stem Cells, adult stem cells (ASCs) lead the market due to their established use and regulatory acceptance. Human embryonic stem cells (HESCs) and induced pluripotent stem cells (iPSCs) contribute to innovative research and advanced therapeutic applications.
By End-user, biopharmaceutical companies dominate the market due to their focus on developing and commercializing therapies. Research institutes and other stakeholders contribute significantly through academic studies and pilot-scale production.
Segmentation:
By Scale of Operation
- Commercial
- Clinical
- Preclinical
By Size of Contract Manufacturer
- Large/Very Large
- Mid-sized
- Small-sized
By Source of Stem Cells
- Allogenic
- Autologous
By Type of Stem Cells
- Adult Stem Cells (ASCs)
- Human Embryonic Stem Cells (HESCs)
- Induced Pluripotent Stem Cells (iPSCs)
By End-user
- Biopharmaceutical companies
- Research Institutes
- Others
Regional Analysis:
The Mexico stem cell contract manufacturing market is regionally segmented into key areas, including central Mexico, northern Mexico, and other emerging regions. Each region contributes uniquely to the market’s growth, with specific infrastructure, geographical, and economic advantages shaping its market share and strategic importance.
Central Mexico
Central Mexico, including cities like Mexico City and Guadalajara, accounts for a significant portion of the market, holding an estimated 40% market share. This region benefits from its advanced research infrastructure, proximity to academic institutions, and a concentration of biotechnology firms. Mexico City, as the economic and administrative hub, serves as a center for research collaborations and regulatory oversight. Guadalajara, known for its robust technological ecosystem, attracts investments for innovation and large-scale manufacturing capabilities. Central Mexico's established infrastructure and skilled workforce position it as a leader in stem cell contract manufacturing.
Northern Mexico
Northern Mexico, encompassing cities such as Monterrey and states like Baja California, holds an estimated 35% market share. The region's proximity to the United States provides logistical advantages and opportunities for cross-border collaborations under the USMCA agreement. Monterrey, with its well-developed industrial base and research institutions, has become a strategic hub for biotechnology manufacturing. Baja California, located near California’s biotech hub, offers seamless access to cutting-edge research and expertise, fostering innovation and partnership opportunities. Northern Mexico also benefits from established transportation networks, enabling efficient export and import operations.
Other Regions
Emerging regions in southern and eastern Mexico account for approximately 25% market share. These areas are gradually gaining attention due to government efforts to promote biotechnology and healthcare development. While they currently lack the established infrastructure seen in central and northern regions, ongoing investments in research and development, coupled with incentives for private-sector participation, are driving growth.
Key Player Analysis:
- Lonza Group
- WuXi AppTec
- Boehringer Ingelheim
- Catalent Inc.
- FUJIFILM Diosynth Biotechnologies
- Samsung Biologics
- Thermo Fisher Scientific Inc.
- Cytovance Biologics
- Cytiva
Competitive Analysis:
The Mexico stem cell contract manufacturing market is characterized by moderate competition, with a mix of domestic and international players vying for market share. Established global biotechnology and pharmaceutical companies leverage Mexico’s cost-efficient manufacturing capabilities and skilled workforce to expand their operations. Local firms also contribute significantly by providing specialized services and fostering collaborations with academic institutions and research organizations. For example, Cryo-Cell International collaborates with Mexican research institutions to advance stem cell research and applications. Key competitive strategies include investments in advanced manufacturing technologies, partnerships for research and development, and adherence to regulatory compliance standards set by COFEPRIS. Proximity to the United States and access to Latin American markets give firms a strategic advantage, particularly under trade agreements like the USMCA. While the market offers growth opportunities, players face challenges such as the need for consistent regulatory compliance, high technology costs, and competition from established global hubs. Companies that focus on innovation, cost optimization, and strategic partnerships are better positioned to succeed.
Recent Developments:
- In October 2023, Lonza announced the introduction of a new filling line specifically designed for the commercial supply of Antibody-Drug Conjugates (ADCs) for a dedicated customer. This state-of-the-art cGMP filling line, located at Lonza’s Stein (CH) site, is equipped to handle and fill bioconjugates for commercial distribution.
- In May 2024, WuXi AppTec, Inc. announced its expansion by opening its new R&D and manufacturing facility in Singapore. This new facility provides API R&D and manufacturing services for peptides, small molecules, complex synthetic conjugates, & oligonucleotides
- In May 2024, Boehringer Ingelheim announced an agreement with Quallent Pharmaceuticals, a private label pharmaceutical distributor, to manufacture and supply its adalimumab biosimilar, adalimumab-adbm, for the US market. This collaboration aims to expand patient access to essential biologic medicines
Market Concentration & Characteristics:
The Mexico stem cell contract manufacturing market exhibits a moderately fragmented structure, with a mix of domestic players and international companies leveraging the country’s strategic advantages. Leading firms focus on establishing state-of-the-art manufacturing facilities in key regions like Monterrey, Guadalajara, and Mexico City, benefiting from advanced infrastructure and a skilled workforce. The market is characterized by a strong emphasis on cost-efficient production, scalability, and adherence to regulatory standards set by COFEPRIS. Growing demand for personalized and regenerative medicine has prompted companies to invest in innovative manufacturing technologies and strategic collaborations with research institutions. While competition is intensifying, the market's evolving regulatory environment and regional advantages provide opportunities for smaller players to gain traction. The presence of cross-border trade agreements, like the USMCA, further strengthens Mexico’s position as a regional hub for stem cell contract manufacturing, appealing to global stakeholders.
Report Coverage:
The research report offers an in-depth analysis based on By Scale of Operation, By Size of Contract Manufacturer, By Source of Stem Cells, By Type of Stem Cells and By End-user.It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is anticipated to experience significant growth, more than doubling in size over the forecast period, driven by a strong compound annual growth rate (CAGR).
- Increasing demand for regenerative therapies will fuel investments in advanced stem cell research and production technologies.
- Mexico's cost-efficient manufacturing and skilled labor will continue to attract global biotech and pharmaceutical firms seeking outsourcing opportunities.
- Proximity to the U.S. market will strengthen cross-border collaborations, enhancing trade and innovation.
- Government support, including streamlined regulatory frameworks by COFEPRIS, will ensure market stability and investor confidence.
- Collaboration between academic institutions and industry players will accelerate research and technological advancements.
- Northern regions like Baja California and central hubs like Monterrey and Guadalajara will dominate due to infrastructure and geographic advantages.
- Growing interest in personalized medicine will expand applications of stem cell therapies across various therapeutic areas.
- Challenges such as regulatory harmonization and the high cost of advanced technologies may spur innovation in cost-effective solutions.
- Mexico’s position as a strategic location for Latin American and global markets will solidify its role as a key player in the stem cell manufacturing industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Mexico stem cell contract manufacturing market?
What factors are driving the market growth?
Which regions in Mexico are key hubs for stem cell manufacturing?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mexico Stem Cell Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mexico Stem Cell Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 50.93 million → 2032: USD 113.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mexico Stem Cell Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mexico Stem Cell Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mexico Stem Cell Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mexico Stem Cell Contract Manufacturing Market Drivers
- 3.3 Mexico Stem Cell Contract Manufacturing Market Restraints & Challenges
- 3.4 Mexico Stem Cell Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mexico Stem Cell Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mexico Stem Cell Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mexico Stem Cell Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mexico Stem Cell Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mexico Stem Cell Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mexico Stem Cell Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mexico Stem Cell Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mexico Stem Cell Contract Manufacturing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mexico Stem Cell Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mexico Stem Cell Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mexico Stem Cell Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mexico Stem Cell Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mexico Stem Cell Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mexico Stem Cell Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mexico Stem Cell Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mexico Stem Cell Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mexico Stem Cell Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mexico Stem Cell Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mexico Stem Cell Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
