
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Middle East Toy Market Size 2024 | USD 14,202.85 Million |
| Middle East Toy Market, CAGR | 3.16% |
| Middle East Toy Market Size 2032 | USD 18,213.36 Million |
Market Overview
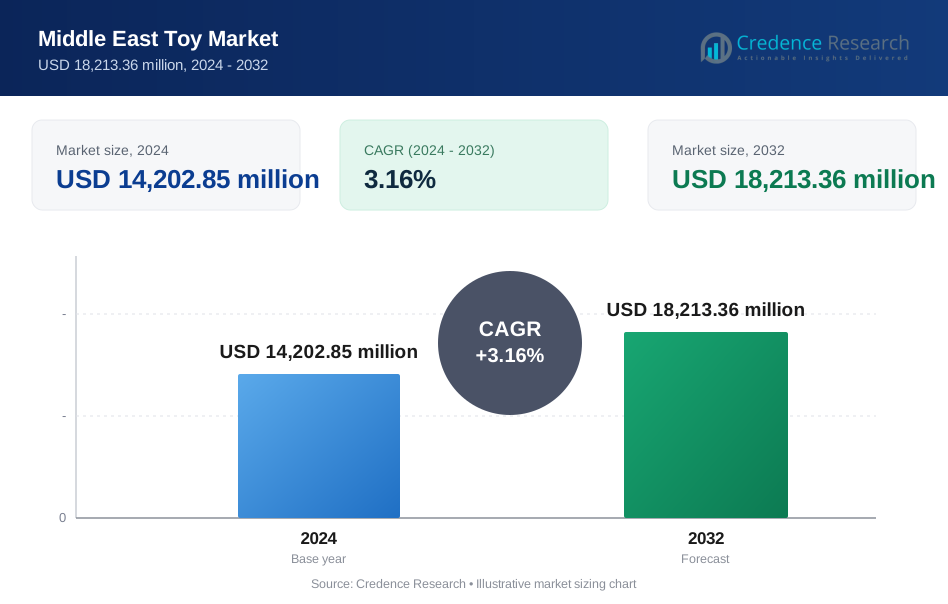
Middle East Toy Market size was valued at USD 14,202.85 million in 2024 and is anticipated to reach USD 18,213.36 million by 2032, at a CAGR of 3.16% during the forecast period (2024-2032). The Middle East toy market is experiencing significant growth driven by increasing disposable income, a young and expanding population, and a growing middle class. With a shift toward premium and educational toys, there is a rising demand for innovative and interactive products. The region's increasing digital adoption is also fueling interest in tech-based toys and smart gadgets, catering to tech-savvy children. Additionally, the popularity of licensed toys and collaborations with entertainment franchises contributes to market expansion. E-commerce platforms are becoming key distribution channels, further enhancing accessibility. Cultural and regional preferences, such as a focus on safety, sustainability, and Islamic values, are influencing product development. With the region's diverse demographics and evolving consumer trends, manufacturers are adjusting their strategies to meet the demand for both traditional and modern toy offerings, leading to a dynamic and competitive market landscape. The Middle East toy market is shaped by diverse geographical factors, including economic conditions, cultural preferences, and technological advancements. The Gulf countries, particularly the UAE and Saudi Arabia, dominate due to their strong retail infrastructure and high consumer spending. Meanwhile, Israel’s market thrives on innovation and STEM-based toys, while Turkey and Iran contribute through local manufacturing and affordable toy options. The region’s growing e-commerce sector has also significantly influenced distribution channels, making international brands more accessible. Key players in the market include Bandai Namco Holdings, VTech Holdings Limited, Mattel’s Fisher-Price, Playmates Toys, and TOMY Company, Ltd. These companies cater to a wide range of consumer demands, from educational and tech-driven toys to traditional and culturally relevant products. Additionally, increasing collaborations between global brands and local distributors have expanded market reach, further fueling the toy industry’s growth in the Middle East.Market Insights
- The Middle East toy market was valued at USD 14,202.85 million in 2024 and is expected to reach USD 18,213.36 million by 2032, growing at a CAGR of 3.16%.
- Increasing disposable income and a rising young population are key drivers fueling the demand for toys across the region.
- The growing preference for STEM-based, educational, and tech-driven toys is shaping market trends, especially in urban areas.
- E-commerce expansion and digital retailing are transforming toy distribution, making international brands more accessible.
- Strict government regulations and cultural restrictions on certain toy categories pose challenges to market growth.
- Saudi Arabia and the UAE dominate the market due to strong purchasing power, while Turkey and Iran contribute through local manufacturing.
- Leading players such as Bandai Namco, Mattel’s Fisher-Price, VTech, Playmates Toys, and TOMY Ltd. compete through innovation and product diversification.
Report Scope
This report segments the Middle East Market as follows: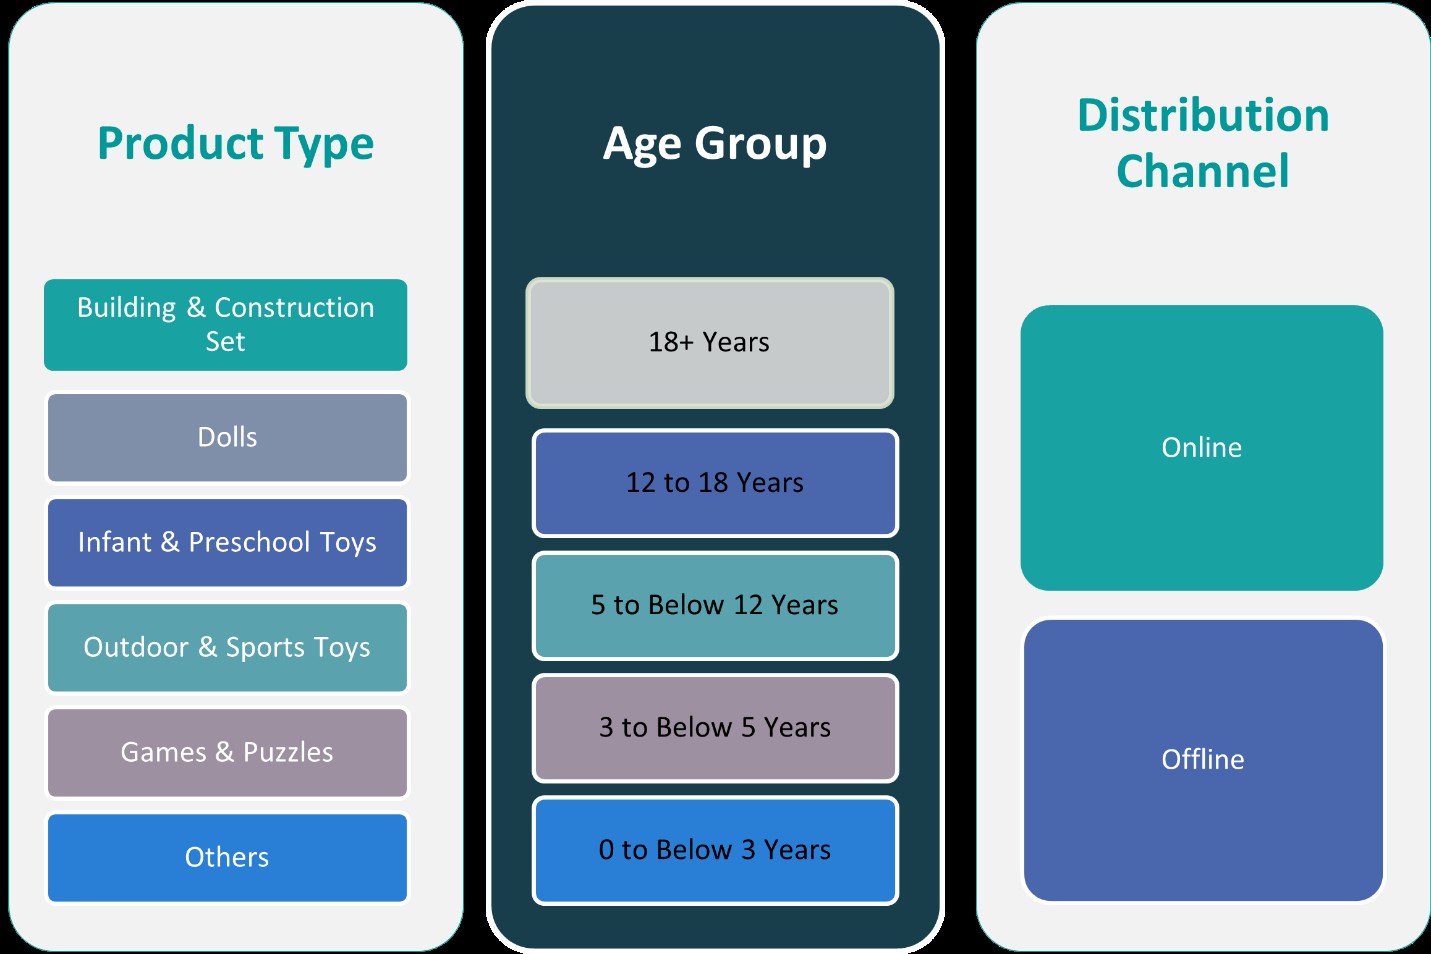
Market Drivers
Growing Disposable Income and Expanding Middle-Class Population The Middle East toy market is witnessing substantial growth, primarily driven by rising disposable income and an expanding middle-class population. For instance, government initiatives like Saudi Vision 2030 and the UAE's National Agenda have focused on economic diversification, leading to increased household incomes. This financial stability encourages the purchase of premium and branded toys, including educational and tech-driven options that enhance children's learning experiences. Additionally, an increase in dual-income households has further boosted consumer spending on toys, reinforcing the market’s steady expansion. Cultural Preferences, Safety Regulations, and Sustainability Trends Cultural values and regulatory standards significantly shape the Middle East toy market. For instance, modesty-focused dolls and culturally appropriate educational games align with Islamic values, as highlighted in reports by the Islamic Development Bank. Stringent safety regulations ensure that imported and locally manufactured toys meet high-quality standards, further influencing consumer purchasing decisions. Additionally, the global push for sustainability is making an impact, with eco-friendly and biodegradable toys gaining popularity. As governments and brands commit to environmental initiatives, the demand for sustainable toy options is expected to rise, contributing to a more responsible and conscious market landscape. Rising Demand for Educational and Tech-Enabled Toys Parents and educators in the Middle East are placing greater emphasis on cognitive and skill development, leading to a surge in demand for educational toys. Products that promote STEM (Science, Technology, Engineering, and Mathematics) learning, such as robotics kits, coding games, and interactive puzzles, are gaining traction. The integration of technology, including AI-powered toys, augmented reality games, and smart learning devices, is also fueling market growth. As digital literacy becomes a priority in the region, tech-enabled toys are expected to play a crucial role in shaping children's early learning experiences. Influence of E-Commerce and Digital Transformation The rapid adoption of e-commerce platforms is transforming toy distribution across the Middle East. Consumers increasingly prefer online shopping due to its convenience, diverse product offerings, and competitive pricing. Major online retailers and marketplaces, such as Amazon, Noon, and regional specialty toy stores, are expanding their reach and offering exclusive deals. Social media and digital marketing also play a vital role in influencing consumer preferences, with parents and children engaging with brands through targeted advertisements and influencer recommendations. This digital shift enhances accessibility and fuels market growth by reaching a broader audience.Market Trends
Growing Popularity of Licensed and Branded Toys The Middle East toy market is witnessing a surge in demand for licensed and branded toys, driven by the strong influence of global entertainment franchises. Popular characters from movies, TV shows, and video games, such as those from Disney, Marvel, and Pokémon, continue to dominate the market. Parents and children are increasingly drawn to collectible action figures, themed playsets, and merchandise that reflect their favorite characters. This trend is further fueled by streaming services and digital media, which have broadened access to international content, strengthening brand loyalty and increasing the demand for character-based toys. Shift Toward Educational and STEM-Based Toys Educational toys are gaining prominence as parents prioritize cognitive development and hands-on learning experiences for their children. For instance, government programs like the UAE's "Future Skills" initiative have encouraged the adoption of STEM-based toys, such as robotics kits and coding games, in schools. Schools and educational institutions are also integrating such toys into their curricula to promote creativity and problem-solving skills. The increasing awareness of the benefits of early childhood education is further driving this trend, encouraging manufacturers to develop more interactive and tech-driven learning toys. Expansion of E-Commerce and Omnichannel Retailing The rapid growth of e-commerce is reshaping the toy retail landscape in the Middle East. Online shopping platforms like Amazon, Noon, and regional toy retailers are offering a wider selection of products, competitive pricing, and convenient delivery options. The rise of omnichannel retailing, where brands integrate online and offline experiences, is also gaining momentum. Many retailers are leveraging digital strategies, such as augmented reality (AR) previews, virtual try-before-you-buy options, and targeted online promotions, to enhance customer engagement. This shift toward digital commerce is making toys more accessible to a broader audience across the region. Increasing Demand for Sustainable and Eco-Friendly Toys Sustainability is becoming a key focus in the Middle East toy market, with consumers showing a growing preference for eco-friendly and biodegradable products. For instance, government initiatives like the UAE's "Green Economy for Sustainable Development" encourage the production of toys made from recycled materials and plant-based plastics. Leading toy manufacturers are responding by launching sustainable product lines and adopting greener packaging solutions. Government initiatives promoting environmental consciousness and corporate social responsibility (CSR) efforts by brands are further driving this trend, making sustainability a crucial factor in toy purchasing decisions.Market Challenges Analysis
Stringent Regulations and Compliance Requirements The Middle East toy market faces significant challenges due to stringent safety regulations and compliance requirements. For instance, the Gulf Cooperation Council (GCC) enforces the "Gulf Conformity Mark" (G-mark), which ensures that all toys meet strict health, safety, and environmental standards. Compliance with international certifications, such as EN71 and ASTM, adds complexity for manufacturers and distributors. Additionally, cultural sensitivities influence product design and marketing, requiring brands to tailor their offerings to align with regional values. Navigating these regulatory frameworks increases operational costs and can pose barriers for new market entrants, limiting product diversity and innovation. High Dependency on Imports and Supply Chain Disruptions A major challenge in the Middle East toy industry is its heavy reliance on imports, with a large percentage of toys sourced from international markets such as China, the U.S., and Europe. This dependency makes the market vulnerable to global supply chain disruptions, fluctuating freight costs, and currency exchange rate volatility. Events such as trade restrictions, shipping delays, and geopolitical tensions can lead to higher import costs, impacting pricing strategies and product availability. Additionally, localized production remains limited, restricting opportunities for regional manufacturers to compete on a larger scale. These factors contribute to market instability and create challenges in maintaining consistent inventory levels.Market Opportunities
The Middle East toy market presents significant growth opportunities driven by increasing demand for innovative and culturally relevant products. With a young and expanding population, there is a rising preference for educational, STEM-based, and tech-enabled toys that enhance cognitive development and interactive learning. Parents and educators are actively seeking high-quality toys that align with early childhood education initiatives, creating a strong market for products that integrate artificial intelligence, robotics, and augmented reality. Additionally, the growing influence of global entertainment franchises and the popularity of licensed merchandise open avenues for collaborations between toy manufacturers and media companies, further driving sales and brand engagement. E-commerce and digital transformation are reshaping consumer purchasing behavior, offering lucrative opportunities for online retailers and direct-to-consumer brands. The region’s increasing internet penetration and mobile commerce adoption enable toy companies to reach a broader audience through digital platforms, social media marketing, and influencer-driven promotions. Furthermore, the rising emphasis on sustainability presents an opportunity for brands to introduce eco-friendly and biodegradable toys, catering to environmentally conscious consumers. As governments in the Middle East continue to support economic diversification and local manufacturing, there is potential for regional production growth, reducing reliance on imports and fostering a competitive domestic toy industry.Market Segmentation Analysis:
By Product Type: The Middle East toy market is categorized into several key product segments, including building & construction sets, dolls, infant & preschool toys, outdoor & sports toys, and games & puzzles. Building & construction sets are witnessing strong demand due to their role in fostering creativity and problem-solving skills, particularly among young children and preteens. Dolls remain a staple in the market, with a growing preference for culturally diverse and themed dolls that align with regional values. The infant & preschool toy segment continues to expand, driven by increasing parental focus on early childhood development and sensory learning. Outdoor & sports toys are gaining traction as governments and schools promote active lifestyles to combat rising childhood obesity rates. Meanwhile, the games & puzzles segment is experiencing steady growth, fueled by the rising popularity of educational and strategy-based games that encourage cognitive development. These diverse product segments cater to a broad consumer base, ensuring sustained market expansion and innovation. By Age Group: The Middle East toy market is also segmented based on age groups, ranging from infants to adults. The 0 to below 3 years segment is dominated by sensory and developmental toys that support motor skills and early learning. Toys for the 3 to below 5 years age group focus on interactive and imaginative play, including dolls, building sets, and preschool learning toys. The 5 to below 12 years segment holds a significant market share, driven by demand for STEM-based educational toys, action figures, and outdoor play equipment. The 12 to 18 years category is evolving, with teenagers showing a strong preference for digital gaming, collectibles, and tech-enhanced toys such as drones and robotics. The 18+ years segment, though smaller, is expanding with the rise of adult collectors, board games, and high-end model kits. Each age group presents unique opportunities for manufacturers to tailor their offerings, ensuring sustained consumer interest and market growth.Segments:
Based on Product Type:- Building & Construction Set
- Dolls
- Infant & Preschool Toys
- Outdoor & Sports Toys
- Games & Puzzles
- 18+ Years
- 12 to 18 Years
- 5 to Below 12 Years
- 3 to Below 5 Years
- 0 to Below 3 Years
- Online
- Offline
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
Regional Analysis
United Arab Emirates (UAE) The United Arab Emirates (UAE) holds a substantial share of the market, accounting for approximately 20% of the region’s total toy sales. The country’s high disposable income, strong retail infrastructure, and increasing demand for premium and educational toys drive market growth. The UAE benefits from a mix of international and local brands, with a preference for interactive, technology-driven toys. Additionally, the e-commerce sector has seen rapid growth, further fueling toy sales across different demographics. Saudi Arabia (KSA) Saudi Arabia (KSA) represents the largest share in the Middle East toy market, commanding around 30% of the total market. The country’s strong purchasing power, coupled with a large young population, makes it a key player in the industry. Government initiatives to enhance entertainment and recreational activities have boosted toy sales, especially in segments like educational and outdoor toys. The growing influence of Western brands and the increasing penetration of online retail platforms further strengthen the toy market in KSA. Additionally, cultural preferences shape product demand, with a rising interest in traditional and Islamic-themed toys. Israel Israel holds an estimated 10% market share in the Middle East toy sector. The country is known for its advanced technology sector, which translates into a high demand for innovative and STEM-based toys. Israeli consumers prioritize quality and educational value, driving sales of robotic kits, coding games, and science-related playsets. The presence of strong domestic toy manufacturers, alongside well-established international brands, ensures a competitive and diverse market. The robust e-commerce infrastructure also plays a significant role in expanding the reach of toy products to different consumer segments. Turkey and Iran Turkey and Iran, along with the rest of the Middle East, collectively hold the remaining 40% of the market. Turkey has a well-developed manufacturing industry, supplying toys both domestically and for export. The country’s toy market is driven by affordability and diversity, with a mix of traditional and modern toys. Iran, despite economic sanctions, maintains a steady demand for locally produced toys, with an emphasis on educational and culturally relevant products. Other Middle Eastern countries, including Kuwait, Qatar, and Egypt, contribute to market growth through increasing consumer spending and the expansion of international toy brands.Key Player Analysis
- Bandai Namco Holdings
- VTech Holdings Limited
- Mattel's Fisher-Price
- Playmates Toys
- TOMY Company, Ltd
Competitive Analysis
The Middle East toy market is highly competitive, with global and regional players vying for market share through innovation, product diversification, and strategic partnerships. Bandai Namco, Mattel’s Fisher-Price, VTech Holdings Limited, Playmates Toys, and TOMY Company, Ltd. are among the key players driving market growth. These companies focus on expanding their product portfolios to cater to the evolving preferences of Middle Eastern consumers, who increasingly demand educational, interactive, and culturally relevant toys. Companies focus on diversifying their product lines, incorporating educational and interactive elements to cater to evolving consumer preferences. The increasing demand for technology-driven toys, such as STEM-based and AI-integrated products, has intensified competition, pushing brands to develop engaging and interactive offerings. Licensing partnerships with popular entertainment franchises play a crucial role in market differentiation, driving sales through character-based and collectible toys. Additionally, the rise of e-commerce has transformed the competitive landscape, allowing direct-to-consumer sales and reducing dependency on brick-and-mortar stores. Brands are leveraging online platforms to expand their reach and enhance customer engagement. Despite significant opportunities, challenges such as cultural sensitivities, government regulations, and counterfeit products create hurdles for companies. To overcome these barriers, market players are collaborating with local distributors and aligning their product offerings with regional values. With rising consumer spending on premium and educational toys, competition is expected to intensify further. Companies continue to prioritize product innovation, digital marketing strategies, and localized offerings to maintain their market position and sustain long-term growth in the Middle East toy industry.Recent Developments
- In March 2025, the LEGO Group launched a wide range of new sets, including LEGO Architecture, LEGO Art, and LEGO Formula 1, with over 40 sets released on March 1st, including the Trevi Fountain and several Formula 1 Speed Champions sets.
- In March 2025, MGA Entertainment's Little Tikes brand announced a partnership with BBC Studios to launch a line of Bluey-inspired toys, including the Bluey Grannies Car Coupe, Bluey Bushland Adventures Splash Pad, Bluey Beach Day Sand Box, and Bluey Beach Water Table.
- In March 2025, the LEGO Group announced a new multi-year partnership with The Pokémon Company International to bring LEGO Pokémon sets starting in 2026.
- In March 2025, Spin Master announced the renewal of its global master toy licensee agreement with DreamWorks Animation for Gabby's Dollhouse.
- In March 2025, Hasbro participated in the North American International Toy Fair, showcasing new products and collaborations, including a PLAY-DOH Barbie line and Marvel's Iron Man toys.
- In March 2025, Mattel renewed its multi-year global licensing agreement with Disney for Toy Story, planning new products for the franchise's 30th anniversary and Toy Story 5.
Market Concentration & Characteristics
The Middle East toy market exhibits a moderate to high market concentration, with a mix of international brands and regional manufacturers competing for dominance. Leading global players maintain a strong foothold, leveraging brand recognition, licensing agreements, and advanced product innovation to capture consumer interest. The market is characterized by diverse product offerings, ranging from traditional toys to high-tech, STEM-based, and interactive play products. Increasing disposable income and a growing young population drive demand, particularly in urban centers where parents prioritize educational and entertainment value. E-commerce expansion has further reshaped market dynamics, allowing smaller players to compete through digital platforms and direct-to-consumer sales. However, regulatory constraints, cultural considerations, and counterfeit products pose challenges to market expansion. Companies continuously adapt by aligning product portfolios with regional preferences, fostering partnerships with local distributors, and investing in marketing strategies that resonate with Middle Eastern consumers, ensuring sustained growth in the industry.Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The Middle East toy market will continue to grow, driven by rising disposable income and a young population.
- Demand for educational, STEM-based, and interactive toys will increase as parents prioritize learning-focused play.
- E-commerce and digital retail platforms will play a crucial role in expanding market reach and accessibility.
- Licensing agreements with global entertainment franchises will strengthen brand positioning and sales.
- Local toy manufacturing will grow, reducing dependence on imports and offering region-specific products.
- Cultural preferences and regulatory frameworks will influence product development and market entry strategies.
- The popularity of AI-powered and tech-integrated toys will rise, aligning with global innovation trends.
- Counterfeit products and unregulated toy imports will remain key challenges for market players.
- Companies will invest more in sustainable and eco-friendly toys to meet evolving consumer preferences.
- Strategic partnerships between international brands and regional distributors will drive competitive advantage and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Disposable Income and Expanding Middle-Class Population
Economic diversification initiatives and rising household incomes in countries like Saudi Arabia and the UAE are enabling families to spend more on premium, branded, and educational toys, fueling overall market growth.
Rising Demand for Educational and Tech-Enabled Toys
Parents and educators are increasingly prioritizing cognitive and skill development, driving demand for STEM-based, interactive, and tech-integrated toys such as robotics kits, coding games, and smart learning devices.
Expansion of E-Commerce and Digital Retailing
The rapid adoption of online shopping platforms and omnichannel retail strategies is making toys more accessible, allowing international brands to reach a broader audience and offering consumers greater convenience and product variety.
Cultural Preferences, Safety Regulations, and Sustainability Trends
Cultural values, strict safety standards, and a growing focus on sustainability are shaping product development, with demand rising for culturally appropriate, safe, and eco-friendly toys that align with regional values and regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Middle East Toy Market?
What factors are driving the growth of the Middle East Toy Market?
What are the key segments within the Middle East Toy Market?
What are some challenges faced by the Middle East Toy Market?
Who are the major players in the Middle East Toy Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 0 to Below 3 Years
- 1.2.2 3 to Below 5 Years
- 1.2.3 5 to Below 12 Years
- 1.2.4 12 to 18 Years
- 1.2.5 18+ Years
- 1.3 By Product Type
- 1.3.1 Building & Construction Set
- 1.3.2 Dolls
- 1.3.3 Infant & Preschool Toys
- 1.3.4 Outdoor & Sports Toys
- 1.3.5 Games & Puzzles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,202.85 million → 2032: USD 18,213.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East Toy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East Toy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East Toy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East Toy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East Toy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East Toy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East Toy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East Toy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,202.85 million → 2032: USD 18,213.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East Toy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 0 to Below 3 Years
- 12.3.7.2 3 to Below 5 Years
- 12.3.7.3 5 to Below 12 Years
- 12.3.7.4 12 to 18 Years
- 12.3.7.5 18+ Years
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Building & Construction Set
- 12.4.7.2 Dolls
- 12.4.7.3 Infant & Preschool Toys
- 12.4.7.4 Outdoor & Sports Toys
- 12.4.7.5 Games & Puzzles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East Toy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Middle East Toy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Middle East Toy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bandai Namco Holdings
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 VTech Holdings Limited
- 17.4 Mattel's Fisher-Price
- 17.5 Playmates Toys
- 17.6 TOMY Company, Ltd
- 17.7 LEGO Group
- 17.8 Hasbro
- 17.9 Spin Master
- 17.10 MGA Entertainment
- 17.11 Simba Dickie Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

