
Market Overview
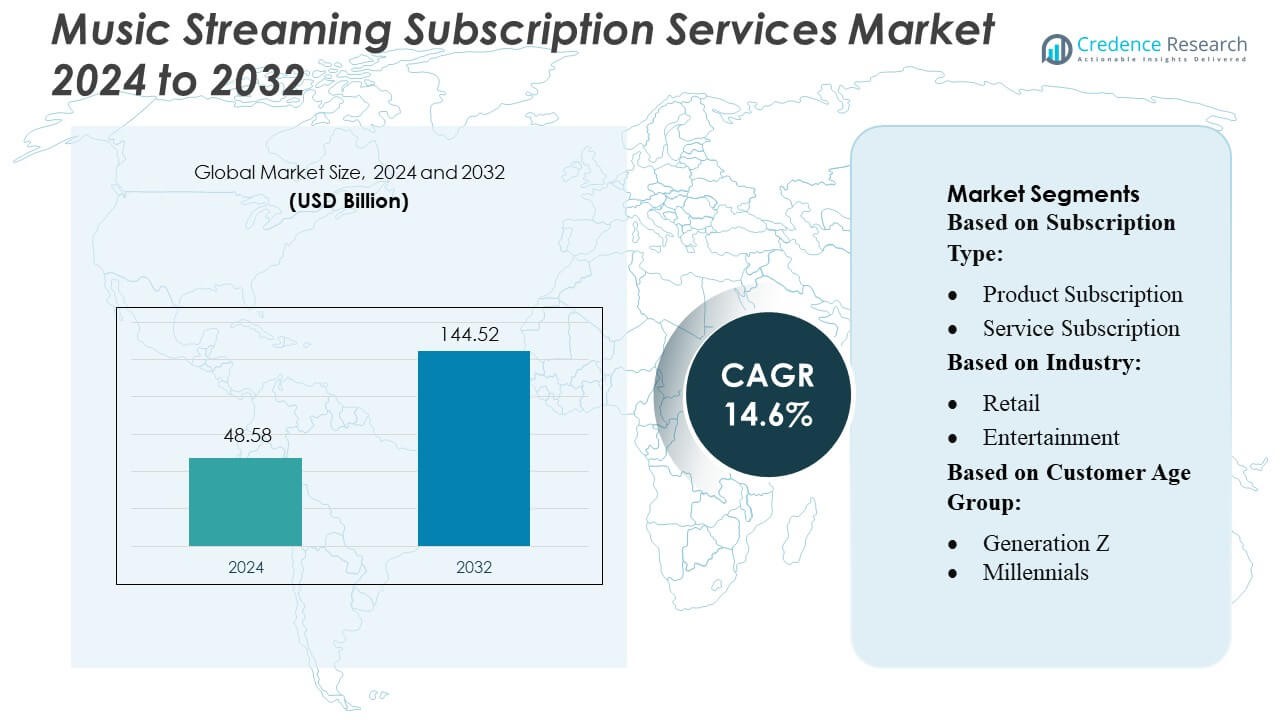
Music Streaming Subscription Services Market size was valued USD 48.58 billion in 2024 and is anticipated to reach USD 144.52 billion by 2032, at a CAGR of 14.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Music Streaming Subscription Services Market Size 2024 | USD 48.58 Billion |
| Music Streaming Subscription Services Market, CAGR | 14.6% |
| Music Streaming Subscription Services Market Size 2032 | USD 144.52 Billion |
The global music streaming subscription services market remains highly competitive as leading platforms aggressively innovate and expand their offerings. Major services invest in exclusive content, algorithm-driven personalization, and high-fidelity audio across devices, aiming to attract and retain paying subscribers. Regional players and emerging-market platforms increasingly challenge incumbents by offering localized content, flexible pricing, and mobile-first experiences tailored to younger audiences. Meanwhile, the dominant region continues to be North America, which accounts for roughly 37% of global market share, driven by high subscription penetration, strong internet infrastructure, and widespread adoption of premium and bundled streaming plans.
Market Insights
- The Music Streaming Subscription Services Market was valued at USD 48.58 billion in 2024 and is projected to reach USD 144.52 billion by 2032, registering a 14.6% CAGR, driven by rising adoption of premium, ad-free listening and expanding digital ecosystems.
- Growing demand for exclusive content, AI-powered personalization, and high-fidelity audio continues to drive market growth, with the premium subscription segment contributing the largest share of overall revenue.
- Trends such as podcast integration, social listening features, and mobile-first consumption in emerging markets strengthen platform engagement and broaden user bases.
- Competition intensifies as global and regional players expand localized content, flexible pricing, and device-agnostic streaming experiences, challenging traditional segment leaders.
- North America leads the market with a 37% share, supported by strong digital infrastructure, while Asia-Pacific emerges as the fastest-growing region due to rising smartphone penetration and youth-driven demand.
Market Segmentation Analysis:
By Subscription Type
Product Subscription dominates the music streaming subscription market, holding the largest share due to strong demand for bundled premium features such as offline access, ad-free streaming, and high-resolution audio. Service Subscription also grows steadily as platforms integrate AI-powered recommendations and multi-device syncing. Digital Subscription gains traction among users seeking flexible, app-based music access without long-term commitments, while Membership Subscription expands through ecosystem-based offerings that combine music, video, and cloud storage benefits. The dominance of Product Subscription is driven by higher perceived value and strong adoption among frequent streamers.
- For instance, Tidal supports lossless playback up to 24-bit/192 kHz across its premium tier. Service Subscription grows steadily with platforms enhancing AI-driven recommendations and device integration.
By Industry
Entertainment remains the dominant industry segment, accounting for the largest share as streaming platforms partner with record labels, production houses, and gaming companies to enhance content diversity and exclusivity. Retail increasingly leverages music subscriptions for in-store ambience optimization, while Food and Beverage outlets adopt curated playlists to enhance customer engagement. Health and Wellness emerges as a fast-growing segment with rising usage of mood-based and therapy-focused music collections. The Entertainment segment’s leadership is driven by high consumption volumes, rapid digital integration, and wide content licensing networks.
- For instance, SoundCloud supports a mix of free and paid memberships: its “Pro” subscription tier offers unlimited uploads (as opposed to the 1-hour or 2-hour upload caps on free/basic accounts).
By Customer Age Group
Millennials lead the market, holding the largest share due to high adoption of paid streaming plans, multi-device usage, and preference for curated and algorithmic playlists. Generation Z follows closely, driven by affordability options, social media-integrated music discovery, and strong engagement with short-form audio-visual platforms. Generation X maintains steady demand, especially for premium plans with family-sharing options, while Baby Boomers show growing interest in simplified user interfaces and classic-genre libraries. Millennials dominate primarily because of sustained digital spending habits and continuous engagement with both mainstream and niche music content.
Key Growth Drivers
- Expansion of Personalized and Algorithmic Recommendations The market grows as platforms invest in advanced AI-driven recommendation engines that improve content discovery and user retention. Services analyze listening behavior, mood patterns, and contextual data to deliver hyper-personalized playlists that enhance engagement. This capability boosts subscription upgrades and reduces churn, particularly among younger demographics seeking curated, real-time music experiences. As algorithms become more precise, platforms strengthen customer loyalty and differentiate themselves in a competitive landscape, driving sustained subscriber growth across global markets.
- For instance, Amazon, customers using Alexa+ explored music three times more than with the earlier Alexa, and those who requested recommendations listened to nearly 70% more music.
- Rising Adoption of Multi-Device and Cross-Platform Streaming Growing consumer demand for seamless access across smartphones, smart speakers, smart TVs, and wearables significantly drives subscription adoption. Music streaming services optimize interoperability, allowing users to switch devices without interrupting playback. This technological convenience increases daily usage time and encourages households to adopt family plans. The expansion of connected ecosystems-combined with high-speed internet availability-further reinforces the shift toward subscription-based audio consumption, enabling platforms to offer richer features and enhance user satisfaction.
- For instance, iHeartRadio reports having more than 188 million registered users. The service is available on over 500 platforms and supports more than 2,000 distinct types of connected devices, enabling listeners to begin playback on one device and continue it on another without interruption.
- Increasing Demand for Ad-Free and High-Fidelity Streaming The rising preference for premium, ad-free music listening experiences accelerates subscription growth. Consumers show strong willingness to pay for enhanced audio quality, such as HD, Ultra HD, and lossless formats, along with offline playback capabilities. As more users invest in high-end headphones and home audio systems, the value proposition of high-fidelity streaming strengthens. This shift pushes platforms to expand premium tiers, integrate immersive formats like spatial audio, and improve sound engineering, thereby driving higher revenue per subscriber.
Key Trends & Opportunities
- Growth of Social Listening and Collaborative Features A major trend emerges as platforms integrate real-time social listening, group sessions, and playlist collaboration features. These tools enable users to co-create content, share music experiences, and engage across social networks. The rise of creator-driven audio formats and shareable content generates new monetization opportunities. Services that leverage social integration enhance user stickiness, attract younger demographics, and transform streaming from a solo to a community-driven experience, unlocking long-term engagement potential.
- For instance, Deezer’s “Shaker” feature (launched in November 2023) enables users to form a collaborative playlist group with up to 14 people, even if some members don’t have a Deezer account.
- Expansion into Podcasts and Audio-Based Services Music streaming platforms increasingly diversify into podcasts, live audio sessions, and exclusive talk shows, creating significant revenue and engagement opportunities. Original podcast content and exclusive licensing deals strengthen platform differentiation while expanding listening time beyond music. This trend supports cross-selling strategies, increases subscription value, and attracts new user segments. As audiences adopt audio for learning, entertainment, and wellness, platforms gain opportunities to become comprehensive audio hubs.
- For instance, Spotify's official investor relations and newsroom information, the platform offers over 100 million tracks, nearly 7 million podcast titles, and 350,000 audiobooks for individual purchase (or access via monthly listening hours for Premium subscribers).
- Integration of AI-Generated and Immersive Audio Experiences Platforms explore AI-generated soundscapes, personalized mixes, and adaptive listening experiences as emerging opportunities. Immersive formats like Dolby Atmos and spatial audio enhance user satisfaction and provide premium upgrade pathways. AI-assisted creation tools enable users to craft customized audio environments, expanding engagement and opening new content verticals. These advancements offer differentiation and support the transition toward more interactive, experience-driven streaming services.
Key Challenges
- High Licensing Costs and Content Acquisition Pressures The market faces rising operational costs due to expensive licensing agreements with music labels, artists, and publishers. Ensuring access to diverse and exclusive content requires substantial investment, placing financial pressure on streaming platforms-especially emerging and regional players. As licensor negotiations become more complex and demand for fair artist compensation grows, platforms struggle to balance profitability with competitive pricing, limiting their ability to innovate or expand aggressively.
- Intense Competition and Subscriber Retention Issues The industry experiences strong competition from global streaming giants, regional services, and alternative entertainment formats such as short-form video and social media platforms. With similar content libraries across competitors, differentiation becomes challenging, leading to frequent price-based competition. Users often switch platforms due to promotional discounts, content preferences, or bundled service offerings. Maintaining long-term retention requires continuous investment in personalization, exclusive content, and value-added features, making sustained growth more difficult.
Regional Analysis
North America
North America holds the largest share of the music streaming subscription services market, accounting for around 38%. The region benefits from mature digital ecosystems, high smartphone adoption, and strong demand for premium, ad-free streaming. Users show consistent willingness to pay for enhanced audio quality and exclusive content. The presence of major global platforms strengthens market leadership, supported by widespread use of smart speakers and connected home devices. Growth continues steadily as personalized recommendations, podcast integration, and bundled subscription offerings increase user engagement and retention.
Europe
Europe represents approximately 27% of the global market, driven by strong digital infrastructure and high acceptance of subscription-based audio services. The region benefits from diverse language preferences, robust licensing frameworks, and rising demand for high-fidelity streaming. Consumers increasingly shift from free to paid tiers due to better sound quality and wider content libraries. Local and international platforms both maintain strong presence, supported by steady adoption across Western and Northern Europe. Although growth is moderate, Europe remains a stable and significant contributor to global revenue.
Asia-Pacific
Asia-Pacific holds nearly 28% of the market and remains the fastest-growing region. Expanding smartphone usage, affordable mobile data plans, and large youth populations fuel rapid adoption of music streaming services. Local-language content and mobile-first subscription models make streaming accessible across urban and rural areas. Countries like India, China, and Indonesia drive significant user growth due to strong digital engagement and rising disposable incomes. As platforms integrate more regional content and flexible pricing, Asia-Pacific continues to offer substantial long-term growth potential.
Latin America
Latin America accounts for around 6% of the global market but shows strong year-on-year growth. Rising internet penetration, wider availability of low-cost mobile plans, and increasing interest in regional music genres support subscription adoption. Countries such as Brazil and Mexico lead consumption, driven by young digital-native populations. Local playlists and culturally relevant content help platforms increase user engagement. Although its market share is smaller compared to other regions, Latin America remains a high-growth region with expanding opportunities for premium subscription offerings.
Middle East & Africa
The Middle East & Africa region holds roughly 5% of the market and is in an early but fast-growing stage. Growth is supported by rising smartphone ownership, urbanization, and greater availability of digital payment methods. Telecom partnerships offering bundled subscriptions help expand user bases. Increasing demand for local-language music also boosts streaming adoption. While subscription rates are lower than in mature markets, the region offers strong long-term potential as digital access improves and more consumers shift from traditional media to streaming platforms.
Market Segmentations:
By Subscription Type:
- Product Subscription
- Service Subscription
By Industry:
- Retail
- Entertainment
By Customer Age Group:
- Generation Z
- Millennials
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the music streaming subscription services market features leading players such as Tidal, SoundCloud Global Limited & Co. KG, Amazon.com, Inc. (Amazon Music), iHeartMedia, Inc., Deezer SA, Tencent Music Entertainment Group, Spotify AB, YouTube Music, Pandora Media, Inc., and Apple, Inc. (Apple Music). The music streaming subscription services market continues to intensify as platforms invest heavily in personalization technologies, exclusive content partnerships, and improved audio quality to strengthen user engagement. Companies focus on expanding premium tiers, offering high-fidelity and spatial audio formats, and integrating podcasts, live sessions, and creator-driven content to broaden their appeal. Cross-platform accessibility, smart-device compatibility, and bundled subscription ecosystems have become key differentiators, enabling services to retain subscribers in a crowded market. Regional platforms compete effectively through localized catalogues and flexible pricing, while global providers leverage large libraries and advanced recommendation systems. Overall, rising consumer expectations for seamless, high-quality listening experiences drive continuous innovation and strategic expansion across the industry.
Key Player Analysis
- Tidal
- SoundCloud Global Limited & Co. KG
- com, Inc. (Amazon Music)
- iHeartMedia, Inc.
- Deezer SA
- Tencent Music Entertainment Group
- Spotify AB
- YouTube Music
- Pandora Media, Inc.
- Apple, Inc. (Apple Music)
Recent Developments
- In May 2025, Naver Corp. is considering adding Spotify to its shopping membership to compete with Coupang, following a previous partnership with Netflix. This move would expand Naver's global content partnerships to attract more users to its services.
- In February 2025, Spotify launched "Mi Primer Escenario" in Argentina, a new music contest aimed at supporting emerging artists by giving them a chance to perform at the Quilmes Rock festival. The competition allows up-and-coming Argentine musicians to showcase their talent and connect with listeners, with the grand prize being a performance slot at the festival alongside established artists.
- In December 2024, Apple Music added three new live global radio stations-Apple Música Uno, Apple Music Club, and Apple Music Chill-to its existing lineup of Apple Music 1, Hits, and Country. These stations offer exclusive content and are available for free without a subscription.
- In September 2024, YouTube and Shopee launched a new online shopping service in Indonesia that allows users to buy products directly from YouTube videos, with plans to expand to other Southeast Asian countries. This move is a response to increasing competition from rivals like TikTok, which has also strengthened its e-commerce presence in the region.
Report Coverage
The research report offers an in-depth analysis based on Subscription Type, Industry, Customer Age Group and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as more users shift from ad-supported listening to premium, subscription-based models.
- Platforms will invest further in AI-driven personalization to enhance discovery and improve user retention.
- High-fidelity, lossless, and spatial audio formats will gain wider adoption across premium tiers.
- Podcasts, audiobooks, and live audio sessions will strengthen platform diversification and engagement.
- Local-language content will grow significantly as services target regional audiences more effectively.
- Cross-platform integration with smart devices and connected ecosystems will increase subscription value.
- Creator-focused tools and fan-engagement features will open new monetization opportunities.
- Telecom partnerships and bundled services will support subscriber growth in emerging markets.
- Social listening, shared playlists, and collaborative features will enhance community-based streaming.
- Continuous competition will drive innovation in pricing models, exclusive content, and user experience enhancements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Personalized and Algorithmic Recommendations
Advanced AI-driven recommendation engines analyze user behavior and preferences to deliver hyper-personalized playlists, increasing engagement and reducing churn. This capability is especially effective in attracting and retaining younger demographics who value curated, real-time music experiences.
Rising Adoption of Multi-Device and Cross-Platform Streaming
Consumers increasingly expect seamless music access across smartphones, smart speakers, TVs, and wearables. Platforms that optimize interoperability and device-agnostic streaming see higher daily usage and greater uptake of family and bundled subscription plans.
Increasing Demand for Ad-Free and High-Fidelity Streaming
A growing segment of users is willing to pay for premium, ad-free listening and superior audio quality, such as HD, Ultra HD, and lossless formats. This trend drives the expansion of premium tiers and increases average revenue per subscriber.
Growth of Social Listening and Collaborative Features
Integration of real-time social listening, group sessions, and collaborative playlists transforms streaming into a community-driven experience. These features boost user stickiness, attract younger audiences, and open new monetization opportunities.
Expansion into Podcasts and Audio-Based Services
Platforms are diversifying into podcasts, live audio, and exclusive talk shows, extending listening time and increasing subscription value. This broadens user bases and supports cross-selling, making services more comprehensive audio hubs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Music Streaming Subscription Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Music Streaming Subscription Services Market projected to grow between 2025 and 2032?
Which Music Streaming Subscription Services Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Music Streaming Subscription Services Market?
Who are the leading companies in the Music Streaming Subscription Services Market?
Which region commanded the largest share of the Music Streaming Subscription Services Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 Entertainment
- 1.2.2 Retail
- 1.2.3 Food and Beverage
- 1.2.4 Health and Wellness
- 1.3 By Subscription Type
- 1.3.1 Product Subscription
- 1.3.2 Service Subscription
- 1.3.3 Digital Subscription
- 1.3.4 Membership Subscription
- 1.4 By Customer Age Group
- 1.4.1 Generation Z
- 1.4.2 Millennials
- 1.4.3 Generation X
- 1.4.4 Baby Boomers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 48.58 billion → 2032: USD 144.52 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Music Streaming Subscription Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Music Streaming Subscription Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Music Streaming Subscription Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Music Streaming Subscription Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Music Streaming Subscription Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Music Streaming Subscription Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Music Streaming Subscription Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Music Streaming Subscription Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 48.58 billion → 2032: USD 144.52 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Music Streaming Subscription Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Entertainment
- 12.3.6.2 Retail
- 12.3.6.3 Food and Beverage
- 12.3.6.4 Health and Wellness
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Subscription Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Product Subscription
- 12.4.6.2 Service Subscription
- 12.4.6.3 Digital Subscription
- 12.4.6.4 Membership Subscription
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Customer Age Group - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Generation Z
- 12.5.6.2 Millennials
- 12.5.6.3 Generation X
- 12.5.6.4 Baby Boomers
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Music Streaming Subscription Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Music Streaming Subscription Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Music Streaming Subscription Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Music Streaming Subscription Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Spotify AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Apple, Inc. (Apple Music)
- 18.4 Amazon.com, Inc. (Amazon Music)
- 18.5 YouTube Music
- 18.6 Deezer SA
- 18.7 Tencent Music Entertainment Group
- 18.8 Tidal
- 18.9 SoundCloud Global Limited & Co. KG
- 18.10 Pandora Media, Inc.
- 18.11 iHeartMedia, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

