
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Nonalcoholic Steatohepatitis Drugs Pipeline Market Size 2024 | USD 272.25 million |
| Nonalcoholic Steatohepatitis Drugs Pipeline Market, CAGR | 33.5% |
| Nonalcoholic Steatohepatitis Drugs Pipeline Market Size 2032 | USD 2746.74 million |
Market Overview:
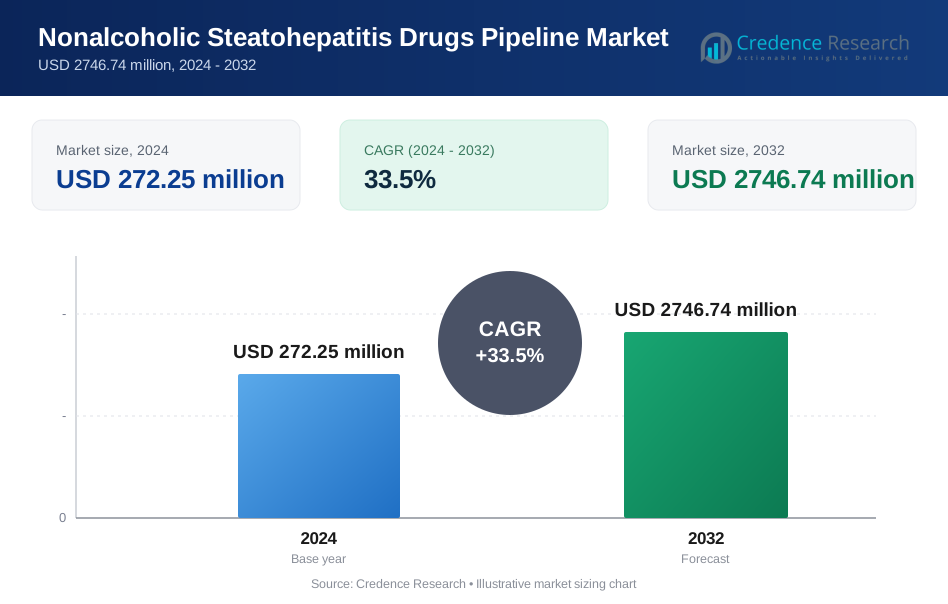
The Nonalcoholic Steatohepatitis Drugs Pipeline Market is projected to grow from USD 272.25 million in 2024 to an estimated USD 2746.74 million by 2032, with a compound annual growth rate (CAGR) of 33.5% from 2024 to 2032.
The primary drivers of the NASH drugs pipeline market include the growing burden of lifestyle-related diseases and the urgent need for effective treatments for this progressive liver condition. Sedentary lifestyles, unhealthy diets, and the global rise in metabolic syndrome have significantly increased the prevalence of NASH. Pharmaceutical companies are intensifying their R&D efforts, focusing on therapies targeting inflammation, fibrosis, and metabolic dysfunction. Key advancements in non-invasive diagnostics, such as elastography and MRI-based biomarkers, are facilitating more efficient clinical trials and accelerating drug development. Additionally, regulatory incentives, including fast-track designations and orphan drug approvals, are encouraging investment and innovation in the NASH drugs pipeline.
North America leads the market, accounting for the largest share due to a high prevalence of NASH, advanced R&D capabilities, and significant funding for drug development. The United States is a hub for innovation, driven by leading pharmaceutical companies and supportive regulatory frameworks. Europe follows closely, supported by strong collaborations between research institutions and pharmaceutical firms. The Asia-Pacific region is emerging as the fastest-growing market, fueled by increasing healthcare investments, a rising prevalence of metabolic disorders, and expanding clinical trial networks in countries like China, India, and Japan. Emerging markets in Latin America and the Middle East & Africa are also gaining momentum, driven by growing disease awareness, improving healthcare infrastructure, and government-backed research initiatives.
Market Insights:
- The market is projected to grow at a robust CAGR of 33.5% from USD 272.25 million in 2024 to USD 2746.74 million by 2032, driven by the unmet need for effective NASH treatments.
- Increasing prevalence of lifestyle-related diseases, such as obesity and type 2 diabetes, is fueling demand for innovative therapies targeting inflammation, fibrosis, and metabolic dysfunction.
- Advancements in non-invasive diagnostics, such as MRI-based biomarkers and elastography, are enhancing clinical trial efficiency and accelerating drug development.
- North America leads the market with a 40% share, driven by advanced R&D infrastructure, significant funding, and supportive regulatory frameworks in the United States.
- Europe holds 30% of the market, supported by strong research collaborations, personalized medicine initiatives, and adherence to stringent regulatory standards.
- Asia-Pacific is the fastest-growing region, capturing 20% of the market, fueled by rising healthcare investments, cost-effective trials, and large patient populations in countries like China and India.
- Emerging markets in Latin America and the Middle East & Africa, comprising 10% of the market, offer untapped opportunities through improving healthcare infrastructure and government-backed initiatives.
Market Drivers:
Rising Prevalence of Lifestyle-Related Diseases:
The increasing prevalence of lifestyle-related diseases such as obesity, type 2 diabetes, and metabolic syndrome is a significant driver of the Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market. These conditions are closely linked to the development of NASH, a progressive liver disease characterized by inflammation and fibrosis. Sedentary lifestyles and unhealthy diets are further exacerbating the global burden of NASH. With the disease affecting millions worldwide and no FDA-approved therapies currently available, the demand for effective treatment options is higher than ever. For instance, a study by Novo Nordisk highlighted that approximately 55% of patients with type 2 diabetes have non-alcoholic fatty liver disease (NAFLD), which can progress to NASH. This pressing need is prompting pharmaceutical and biotech companies to accelerate drug development efforts, focusing on novel therapies targeting the underlying mechanisms of NASH.
Advancements in Diagnostics and Biomarkers:
Technological advancements in non-invasive diagnostics and biomarkers are driving innovation in the NASH drugs pipeline. Traditional diagnostic methods like liver biopsies are invasive and resource-intensive, creating a demand for alternative solutions. Technologies such as transient elastography, magnetic resonance elastography (MRE), and MRI-based proton density fat fraction (MRI-PDFF) are revolutionizing NASH diagnosis and monitoring. These tools not only improve patient stratification but also enhance the efficiency of clinical trials by providing precise data on disease progression and treatment response. Such advancements are enabling pharmaceutical companies to design better-targeted and more effective therapies, ultimately accelerating drug approval processes.
Intensified Research and Development Activities:
The pharmaceutical industry is witnessing a surge in R&D activities aimed at addressing the unmet clinical needs of NASH patients. Companies are focusing on developing a range of therapies, including single-agent treatments and combination drugs, to target the disease’s complex pathophysiology. These efforts include therapies designed to reduce liver inflammation, reverse fibrosis, and address metabolic dysfunction. Strategic collaborations between pharmaceutical companies, academic institutions, and contract research organizations (CROs) are playing a pivotal role in advancing clinical trials. Increased funding from both private and public sectors further underscores the industry’s commitment to finding effective solutions for NASH.
Regulatory Support and Incentives:
Regulatory agencies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) are providing robust support to facilitate the development of NASH therapies. Programs like fast-track designations, orphan drug designations, and breakthrough therapy approvals are significantly accelerating the drug development pipeline. These incentives not only reduce the time to market but also encourage pharmaceutical companies to invest in innovative approaches. The proactive stance of regulatory bodies in addressing the growing NASH burden has created a favorable environment for drug developers, ensuring sustained market growth and continuous innovation in the pipeline.
Market Trends:
Focus on Combination Therapies:
One of the emerging trends in the Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market is the increasing emphasis on combination therapies. Given the multifaceted nature of NASH, which involves metabolic dysfunction, inflammation, and fibrosis, single-agent therapies often struggle to deliver comprehensive efficacy. Combination therapies aim to target multiple pathways simultaneously, providing a more holistic approach to disease management. Pharmaceutical companies are leveraging preclinical and clinical data to identify synergistic drug combinations that can improve patient outcomes. This trend is expected to reshape the therapeutic landscape for NASH, offering better results for a disease with limited treatment options.
Integration of Artificial Intelligence in Drug Development:
The integration of artificial intelligence (AI) and machine learning in drug development is revolutionizing the NASH pipeline. AI is being used to accelerate drug discovery processes, identify novel therapeutic targets, and optimize clinical trial designs. By analyzing vast datasets, AI-driven platforms are enabling researchers to uncover previously unexplored mechanisms of action and predict drug efficacy more accurately. Furthermore, AI applications in patient stratification are improving trial success rates by identifying the most suitable candidates for specific therapies. For instance, companies like Gilead Sciences are utilizing AI to enhance their clinical trial designs and improve patient outcomes. This technological advancement is not only reducing costs and timelines but also enhancing the precision of NASH drug development efforts.
Expansion of Clinical Trials in Emerging Markets:
The expansion of clinical trials into emerging markets is another significant trend in the NASH drugs pipeline. Regions such as Asia-Pacific, Latin America, and the Middle East are witnessing a rise in NASH prevalence due to increasing rates of obesity and diabetes. These markets offer pharmaceutical companies access to large, diverse patient populations and cost-effective clinical trial environments. Countries like China, India, and Brazil are rapidly upgrading their clinical research infrastructure, attracting sponsors looking to conduct late-stage trials. The involvement of contract research organizations (CROs) with localized expertise is further facilitating this trend, enabling global companies to tap into untapped opportunities.
Personalized Medicine and Biomarker-Based Approaches:
Personalized medicine is gaining momentum in the NASH drugs pipeline, driven by advancements in biomarker research. As understanding of the heterogeneity in NASH patients deepens, drug developers are focusing on tailoring treatments based on individual patient profiles. Biomarker-based approaches are helping researchers identify specific subgroups of patients who are more likely to respond to particular therapies. For instance, a study by the American Association for the Study of Liver Diseases (AASLD) highlighted the use of specific biomarkers to predict patient response to NASH therapies. This precision-driven trend not only enhances treatment efficacy but also reduces the risk of adverse effects, making clinical trials more efficient. Personalized approaches are expected to become a cornerstone of NASH drug development, aligning with the broader industry shift toward targeted therapeutics.
Market Challenges Analysis:
High Costs and Lengthy Drug Development Timelines:
One of the significant restraints in the Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market is the high cost and lengthy timelines associated with drug development. The complex pathophysiology of NASH requires extensive preclinical studies and multi-phase clinical trials, which demand significant financial investment and time. Clinical trials for NASH often span years due to the slow progression of the disease and the need to evaluate long-term therapeutic effects on fibrosis and inflammation. For instance, a report by the Tufts Center for the Study of Drug Development estimated that the average cost of bringing a new drug to market is approximately $2.6 billion. These prolonged timelines increase the overall cost of development and pose a financial burden on pharmaceutical companies, particularly smaller biotech firms with limited resources.
Challenges in Patient Recruitment and Retention:
Recruiting and retaining suitable patients for NASH clinical trials remains a persistent challenge. NASH is often asymptomatic in its early stages, leading to late diagnosis and a smaller pool of eligible trial participants. Strict inclusion criteria, such as specific fibrosis stages, further narrow the recruitment window. Retaining patients throughout the trial duration is equally difficult, as studies typically require invasive procedures like liver biopsies, which deter participation. These challenges delay trial completion and increase operational costs, hindering the progress of the drugs pipeline.
Limited Availability of Validated Biomarkers:
While advancements in biomarkers have improved the diagnosis and monitoring of NASH, the lack of universally validated biomarkers for predicting therapeutic outcomes remains a critical challenge. Current non-invasive tools, such as MRI-based biomarkers and elastography, are useful but not definitive for assessing all aspects of disease progression and treatment response. This limitation complicates trial design and increases reliance on invasive methods like biopsies, slowing the pace of drug development and raising the risk of trial failures.
Regulatory and Market Access Barriers:
Navigating the regulatory landscape for NASH drug approval poses another challenge. Differing requirements across regions create complexities for multinational trials, leading to delays in regulatory submissions and market entry. Additionally, the absence of approved NASH therapies means companies face uncertainties in pricing and reimbursement strategies, which can impact market access and commercialization potential. Addressing these barriers requires collaborative efforts between regulatory bodies and pharmaceutical companies to streamline approval processes and establish clear market access pathways.
Market Opportunities:
The Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market presents a significant growth opportunity due to the rising global prevalence of NASH, driven by increasing obesity, type 2 diabetes, and metabolic syndrome. With no FDA-approved therapies currently available, the unmet medical need in this area is substantial, positioning the market as a lucrative space for pharmaceutical and biotech companies. The development of innovative therapies targeting inflammation, fibrosis, and metabolic dysfunction offers the potential to transform disease management. Additionally, advancements in non-invasive diagnostic technologies and biomarker-based approaches are facilitating more efficient clinical trials, enabling faster drug development and regulatory approval. This has spurred substantial R&D investment from both established players and emerging biotech firms, signaling robust growth potential.
Emerging markets such as Asia-Pacific, Latin America, and the Middle East & Africa offer untapped opportunities due to their rising prevalence of NASH, improving healthcare infrastructure, and growing participation in clinical research. These regions provide cost-effective environments for conducting clinical trials and accessing large, diverse patient populations. Regulatory incentives, including fast-track and orphan drug designations, further enhance the market’s appeal, encouraging pharmaceutical companies to accelerate innovation. As awareness of NASH continues to grow, and the demand for effective therapies intensifies, the pipeline for NASH drugs is expected to expand significantly, driving transformative advancements in treatment and addressing a critical unmet global need.
Market Segmentation Analysis:
The Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market is segmented based on drug development phases, drug candidates, molecules, route of administration, and mechanisms of action, reflecting the diversity and complexity of this growing field.
By Phases, the pipeline spans pre-clinical and discovery stage candidates, early-stage products (Phase I), mid-stage products (Phase II), and late-stage products (Phase III). Late-stage products dominate the market, as Phase III trials focus on confirming efficacy and safety on a large scale to secure regulatory approval. Early- and mid-stage products show significant potential, driven by growing investments in novel therapies targeting fibrosis, inflammation, and metabolic dysfunction.
By Drugs, the market includes a diverse range of candidates, such as Resmetirom (MGL-3196), Tirzepatide, Lanifibranor, Saroglitazar Magnesium, and MSDC-0602K, among others. These drugs, leveraging varied mechanisms of action, are at different stages of development, highlighting the focus on innovative approaches to address the unmet needs of NASH treatment.
By Molecules, the market is divided into small molecules, biologics, and oligonucleotides. Small molecules dominate due to their cost-effectiveness and oral bioavailability, while biologics and oligonucleotides are emerging as promising alternatives for precision-driven therapies.
By Route of Administration, oral formulations lead due to convenience and patient compliance, followed by subcutaneous methods, which are gaining traction for targeted delivery of biologics and peptides.
By Mechanism of Action, therapies are categorized into receptor agonists, enzyme inhibitors, protein and peptide inhibitors, and receptor antagonists, each offering a unique approach to targeting disease pathways. This segmentation underscores the comprehensive efforts in developing multifaceted treatments for NASH.
Segmentation:
By Phases:
- Pre-clinical and Discovery stage candidates
- Early-stage product (Phase I)
- Mid-stage products (Phase II)
- Late-stage products (Phase III)
By Drugs:
- Saroglitazar Magnesium
- VK-1430
- GMA-107
- Resmetirom (MGL-3196)
- MSDC-0602K
- ION-224
- HTD 1801
- JKB-121
- EDP-305
- TERN-101
- EYP001
- SNP-610
- SNP-630
- Lanifibranor
- Firsocostat
- Tirzepatide
- Others
By Molecules:
- Small Molecules
- Biologics
- Oligonucleotides
By Route of Administration:
- Oral
- Subcutaneous
- Others
By Mechanism of Action:
- Receptor Agonist
- Enzyme Inhibitor
- Protein & Peptide Inhibitor
- Receptor Antagonist
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market demonstrates varied growth across regions, with North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa contributing to its dynamics. Each region’s market share reflects its prevalence of NASH, clinical research capabilities, and regulatory frameworks.
North America holds the largest market share, accounting for approximately 40% of the global market. The United States is a key driver in this region, supported by its high prevalence of obesity and type 2 diabetes, which are major risk factors for NASH. The region benefits from advanced research and development (R&D) infrastructure, robust funding for clinical trials, and the presence of leading pharmaceutical companies. Supportive regulatory initiatives, such as fast-track and orphan drug designations by the U.S. FDA, further stimulate drug development activities. Canada also contributes significantly, leveraging its strong healthcare system and growing focus on metabolic disease research.
Europe accounts for about 30% of the market, driven by strong collaborations between academic institutions, pharmaceutical firms, and research organizations. Countries such as Germany, the UK, and France lead the region, supported by well-established clinical trial networks and government initiatives promoting innovation in NASH therapies. Europe’s focus on personalized medicine and the increasing use of biomarker-based approaches further enhance its position in the market. The region’s adherence to stringent regulatory standards ensures high-quality drug development, attracting global players to conduct trials here.
Asia-Pacific is the fastest-growing region, capturing approximately 20% of the market. The rise in urbanization, sedentary lifestyles, and dietary changes has significantly increased the prevalence of NASH in countries like China, India, and Japan. These nations are rapidly improving their clinical research infrastructure and healthcare systems, making them attractive destinations for conducting clinical trials. The cost-effectiveness of trials in Asia-Pacific, coupled with large patient populations, offers pharmaceutical companies a strategic advantage. Government investments in healthcare and growing partnerships with contract research organizations (CROs) are further driving market expansion in this region.
Latin America and the Middle East & Africa together account for the remaining 10% of the market. Brazil and Mexico are key players in Latin America, with increasing awareness of NASH and improving healthcare infrastructure supporting market growth. In the Middle East & Africa, countries like the UAE and Saudi Arabia are focusing on healthcare modernization and research collaborations to address the growing burden of metabolic diseases, creating niche opportunities for NASH drug development.
Key Player Analysis:
- AbbVie (Allergan (Tobira Therapeutics Inc.)
- Akero Therapeutics, Inc.
- AstraZeneca
- Axcella Therapeutics
- Boehringer Ingelheim International
- Boston Pharmaceuticals
- Bristol Myers Squibb Co.
- Cirius Therapeutics
- Galmed Pharmaceuticals
- Gilead Sciences
- Gmax Biopharm
- GmbH
- GSK plc.
- Hepion Pharmaceuticals
- HighTide Therapeutics Inc.
- Histogen, Inc. (Conatuspharma.com)
- Intercept Pharmaceuticals Inc.
- Inventiva
- Ionis Pharmaceuticals, Inc. (Akcea Therapeutics)
- Kowa Group (Kowa Company, Ltd.)
- Madrigal Pharmaceuticals
- Melinta Therapeutics LLC
- Merck & Co., Inc.
- NGM Biopharmaceuticals
- Novartis AG
- Novo Nordisk A/S
- Biosciences
- SINEW PHARMA INC.
Competitive Analysis:
The Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market is highly competitive, driven by the urgent need for effective treatments and the absence of approved therapies. Major pharmaceutical companies such as Pfizer Inc., Gilead Sciences Inc., Novo Nordisk A/S, Intercept Pharmaceuticals, and Madrigal Pharmaceuticals dominate the landscape with extensive investments in research and development. These market leaders focus on developing therapies targeting key disease mechanisms, including fibrosis, inflammation, and metabolic dysfunction. Emerging biotech firms are also making significant contributions by pursuing innovative approaches, such as combination therapies and biomarker-driven treatment strategies. Strategic collaborations between pharmaceutical companies, academic institutions, and contract research organizations (CROs) are further advancing drug development. Competitive differentiation is driven by advancements in clinical trial efficiency, integration of non-invasive diagnostic tools, and regulatory incentives such as fast-track and orphan drug designations. As the pipeline continues to grow, innovation and strategic partnerships will remain critical for gaining market advantage.
Recent Developments:
- In January 2024, Boehringer Ingelheim entered a $2 billion collaboration with Suzhou Ribo Life Science and Ribocure Pharmaceuticals to develop siRNA-based NASH treatments, leveraging Boehringer’s pharmaceutical expertise and Ribo’s RNA technology platform.
- In March 2024, Madrigal Pharmaceuticals secured FDA approval for Rezdiffra (resmetirom), the first-ever approved treatment for NASH. Targeting adults with moderate to advanced fibrosis, the drug is priced at $47,400 annually and will be promoted by a specialized sales team engaging 5,000–7,000 specialists.
- In October 2024, Inventiva announced positive results from the LEGEND Phase 2 trial, combining lanifibranor with empagliflozin, representing a novel dual-mechanism approach to NASH treatment.
- In 2024, Boehringer Ingelheim and Zealand Pharma reported encouraging Phase II results for survodutide, a dual glucagon and GLP-1 agonist, showing significant improvements in NASH parameters and positioning as a potential breakthrough therapy.
Market Concentration & Characteristics:
The Nonalcoholic Steatohepatitis (NASH) Drugs Pipeline Market exhibits moderate concentration, with a mix of leading pharmaceutical companies and emerging biotechnology firms driving innovation. Prominent players such as Gilead Sciences Inc., Pfizer Inc., Novo Nordisk A/S, Intercept Pharmaceuticals, and Madrigal Pharmaceuticals hold significant market shares due to their robust R&D capabilities and advanced clinical pipelines. These companies are focused on developing targeted therapies addressing fibrosis, inflammation, and metabolic dysfunction-the key mechanisms underlying NASH. The market is characterized by its dynamic and innovation-driven nature, with increasing emphasis on combination therapies and biomarker-based approaches to enhance treatment efficacy. Regulatory incentives, including fast-track designations and orphan drug approvals, encourage investment and accelerate drug development timelines. Additionally, the growing adoption of non-invasive diagnostic tools and expanding clinical trial activities in emerging markets reflect the market’s adaptability and potential for global expansion. Collaboration and innovation remain pivotal for success in this competitive landscape
Report Coverage:
The research report offers an in-depth analysis based on By Phases, By Drugs, By Molecules, By Route of Administration and By Mechanism of Action. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is projected to grow significantly, driven by rising global prevalence of obesity, type 2 diabetes, and metabolic syndrome.
- Advancements in combination therapies will address the multifaceted nature of NASH, improving treatment outcomes.
- Biomarker-driven approaches will enhance patient stratification, leading to more efficient and targeted clinical trials.
- Regulatory incentives such as fast-track and orphan drug designations will continue to accelerate drug approval timelines.
- Emerging markets, particularly in Asia-Pacific and Latin America, will provide cost-effective opportunities for clinical trials and drug development.
- Integration of artificial intelligence and machine learning in drug discovery will optimize development processes and reduce timelines.
- Expansion of non-invasive diagnostics, such as elastography and MRI-based biomarkers, will improve disease monitoring and trial outcomes.
- Strategic partnerships between pharmaceutical companies, academic institutions, and CROs will drive innovation and collaboration.
- Increasing investment in personalized medicine will pave the way for precision-driven NASH therapies.
- Rising healthcare infrastructure and awareness in underserved regions will create new opportunities for market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Lifestyle-Related Diseases
The increasing rates of obesity, type 2 diabetes, and metabolic syndrome globally are directly contributing to the growing incidence of NASH, creating a large patient pool in urgent need of effective therapies and driving demand for pipeline drugs.
Advancements in Non-Invasive Diagnostics
Innovations such as MRI-based biomarkers and elastography are making it easier to diagnose and monitor NASH, improving patient recruitment and retention in clinical trials and accelerating the pace of drug development.
Intensified R&D and Strategic Collaborations
Pharmaceutical companies are ramping up research and forming partnerships with academic institutions and CROs to develop novel therapies targeting inflammation, fibrosis, and metabolic dysfunction, expanding the pipeline and increasing the likelihood of successful drug approvals.
Regulatory Incentives and Fast-Track Approvals
Supportive regulatory frameworks, including fast-track and orphan drug designations from agencies like the FDA and EMA, are reducing development timelines and encouraging investment in innovative NASH therapies.
Expansion of Clinical Trials in Emerging Markets
Growing healthcare infrastructure and large, diverse patient populations in Asia-Pacific, Latin America, and the Middle East & Africa are attracting clinical trial activity, providing cost-effective environments and accelerating global drug development efforts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the NASH drugs pipeline market?
What is driving the growth of the NASH drugs pipeline market?
Which region leads the NASH drugs pipeline market?
What challenges does the NASH drugs pipeline market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Phase
- 1.2.1 Pre-clinical and Discovery
- 1.2.2 Phase I (Early-stage)
- 1.2.3 Phase II (Mid-stage)
- 1.2.4 Phase III (Late-stage)
- 1.3 By Molecule Type
- 1.3.1 Small Molecules
- 1.3.2 Biologics
- 1.3.3 Oligonucleotides
- 1.4 By Mechanism of Action
- 1.4.1 Receptor Agonist
- 1.4.2 Enzyme Inhibitor
- 1.4.3 Protein & Peptide Inhibitor
- 1.4.4 Receptor Antagonist
- 1.4.5 Others
- 1.5 By Route of Administration
- 1.5.1 Oral
- 1.5.2 Subcutaneous
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 272.25 million → 2032: USD 2746.74 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Nonalcoholic Steatohepatitis Drugs Pipeline Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 272.25 million → 2032: USD 2746.74 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Phase - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pre-clinical and Discovery
- 12.3.7.2 Phase I (Early-stage)
- 12.3.7.3 Phase II (Mid-stage)
- 12.3.7.4 Phase III (Late-stage)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Molecule Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small Molecules
- 12.4.7.2 Biologics
- 12.4.7.3 Oligonucleotides
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mechanism of Action - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Receptor Agonist
- 12.5.7.2 Enzyme Inhibitor
- 12.5.7.3 Protein & Peptide Inhibitor
- 12.5.7.4 Receptor Antagonist
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oral
- 12.6.7.2 Subcutaneous
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Nonalcoholic Steatohepatitis Drugs Pipeline Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Nonalcoholic Steatohepatitis Drugs Pipeline Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Nonalcoholic Steatohepatitis Drugs Pipeline Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Gilead Sciences
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Madrigal Pharmaceuticals
- 17.4 Novo Nordisk A/S
- 17.5 Intercept Pharmaceuticals
- 17.6 Pfizer Inc.
- 17.7 Boehringer Ingelheim
- 17.8 Inventiva
- 17.9 AstraZeneca
- 17.10 Akero Therapeutics
- 17.11 Bristol Myers Squibb
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

