
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Pressure Sensor Market Size 2024 | USD 6,679.45 million |
| North America Pressure Sensor Market, CAGR | 4.24% |
| North America Pressure Sensor Market Size 2032 | USD 9,313.94 million |
Market Overview
The North America Pressure Sensor Market is projected to grow from USD 6,679.45 million in 2024 to an estimated USD 9,313.94 million by 2032, with a compound annual growth rate (CAGR) of 4.24% from 2025 to 2032. The market growth is driven by increasing demand for pressure sensors in various sectors such as automotive, healthcare, industrial, and consumer electronics.
Key market drivers include the rising demand for smart devices and automation, which require accurate and reliable pressure measurement. Additionally, the growing need for enhanced safety features in vehicles and equipment, along with the need for precise monitoring in healthcare applications, is fueling market growth. Trends such as the integration of IoT (Internet of Things) in pressure sensing technologies and advancements in wireless sensor networks are further boosting the market. As the industrial sector focuses on efficiency and safety, the demand for pressure sensors continues to rise, highlighting the importance of innovation and technological developments in sensor technologies.
Geographically, North America holds a significant share of the global pressure sensor market, driven by the presence of key players and strong industrial sectors in the region. The United States and Canada are major contributors to the market's growth, with key players such as Honeywell International Inc., Emerson Electric Co., and Bosch Group driving technological advancements and market development. These companies are focusing on enhancing sensor performance and expanding their product portfolios to meet growing consumer and industrial demands.
Market Insights
- The North America Pressure Sensor Market is expected to grow from USD 6,679.45 million in 2024 to USD 9,313.94 million by 2032, with a CAGR of 4.24% from 2025 to 2032.
- Increased adoption of automation technologies across industries like automotive, healthcare, and manufacturing is driving the demand for precise pressure measurement solutions.
- The integration of IoT in pressure sensors is enhancing real-time monitoring, predictive maintenance, and operational efficiency across multiple sectors.
- The high initial cost of advanced pressure sensors, especially those incorporating IoT or wireless technology, may limit adoption in cost-sensitive sectors.
- Technical challenges related to sensor calibration and integration with existing systems can pose barriers for smooth implementation in some industries.
- North America, especially the U.S. and Canada, holds a significant share of the market due to strong industrial sectors and the presence of leading sensor manufacturers like Honeywell and Emerson Electric.
- Mexico is seeing rising demand for pressure sensors, particularly in automotive manufacturing and industrial sectors, further contributing to regional market growth.
Market Drivers
Healthcare Sector Advancements and Demand for Medical Devices
The healthcare sector's increasing reliance on advanced medical devices is another significant driver of the North American pressure sensor market. Pressure sensors are widely used in various medical applications, such as monitoring blood pressure, respiratory conditions, and critical care management. In particular, devices such as ventilators, infusion pumps, and blood pressure monitors all rely on accurate pressure measurement to function properly. As the healthcare industry increasingly embraces precision medicine and patient monitoring, the need for high-performance, reliable pressure sensors is growing. The COVID-19 pandemic also heightened the demand for medical devices such as ventilators, which utilize pressure sensors for monitoring air pressure and controlling oxygen levels. Additionally, wearable medical devices, which monitor physiological parameters in real-time, are incorporating pressure sensors to offer patients continuous health monitoring. The ongoing innovation in healthcare technologies and the increasing focus on personalized and remote healthcare services are likely to further increase the demand for advanced pressure sensors in North America.
Growth in the Oil and Gas Industry and Need for Pressure Management
The oil and gas sector in North America has historically been a key driver of the pressure sensor market. Pressure sensors are essential in oil and gas exploration, production, and refining processes, where accurate pressure readings are necessary to ensure safe and efficient operations. In upstream operations, pressure sensors are used to monitor drilling systems, oil rigs, and wellhead systems, ensuring that pressure levels stay within safe parameters to prevent equipment failures and accidents. Similarly, in downstream operations, pressure sensors help regulate the pressure in pipelines, refining units, and storage tanks, ensuring the efficient transportation and storage of crude oil and natural gas. As the demand for energy increases and as more unconventional oil and gas reserves are explored in North America, the need for highly reliable pressure sensors continues to rise. Furthermore, with the industry's increasing focus on safety, efficiency, and reducing environmental risks, pressure sensors are essential for real-time monitoring of critical parameters in various systems, contributing to the growth of the market.
Increasing Demand for Automation and Industry 4.0 Integration
The push for automation and the adoption of Industry 4.0 technologies across various sectors is one of the major drivers of the North America Pressure Sensor Market. As industries such as manufacturing, automotive, and oil & gas seek to improve operational efficiency, automation technologies are becoming essential. Pressure sensors play a critical role in the monitoring and control of automated systems, ensuring optimal performance and safety. In automated manufacturing processes, pressure sensors are used to monitor and regulate the pressure within machinery, preventing system failures and increasing uptime. Furthermore, the growing trend of smart factories-integrating robotics, IoT, and AI technologies-requires highly accurate and reliable pressure sensors to monitor various parameters. These advanced systems depend on sensors to provide real-time data and maintain optimal conditions, contributing to improved product quality and cost reduction. The transition towards digitalization and connected technologies within industries is fueling the demand for pressure sensors that can integrate seamlessly into these systems.For instance, BMW Group is leading the Industry 4.0 revolution, harnessing virtual reality and advanced robotics to set new benchmarks for efficiency and innovation in automotive manufacturing. Additionally, West Liberty Foods implemented a connected worker platform, enabling real-time machine data analytics and full visibility into shop floor operations, resulting in significant improvements in resource utilization and operational availability.
Expansion of the Automotive Industry and Need for Safety Features
The North American automotive industry is another key driver for the growth of the pressure sensor market. As vehicles become more advanced with the inclusion of electric, hybrid, and autonomous technologies, the need for precise pressure measurement has increased. In modern vehicles, pressure sensors are used in a variety of applications, such as tire pressure monitoring systems (TPMS), engine management systems, and fuel systems. Pressure sensors ensure proper operation of critical components by providing accurate readings on the vehicle's performance, ensuring safety, and optimizing fuel efficiency. Moreover, with rising consumer demand for enhanced safety features in vehicles, pressure sensors are integral to technologies such as airbags, hydraulic brakes, and electronic stability control systems, all of which require accurate pressure readings to function effectively. The continued growth of electric vehicles (EVs) and autonomous vehicles (AVs) in North America, along with a heightened focus on vehicle safety, will further drive the demand for pressure sensors in the automotive sector.In the automotive sector, pressure sensors are crucial components in tire pressure monitoring systems, engine management systems, and safety features like airbags and electronic stability control. These sensors provide real-time data on various parameters, ensuring optimal performance, safety, and fuel efficiency in modern vehicles.
Market Trends
Adoption of Smart Pressure Sensors in Industrial Automation
The increasing demand for smarter manufacturing systems is contributing to the rapid adoption of smart pressure sensors in the North American industrial automation sector. These smart sensors not only measure pressure but also have integrated capabilities for self-calibration, self-diagnostics, and predictive maintenance. This trend is especially important in industries like oil and gas, automotive, and manufacturing, where high reliability and system uptime are critical. Smart pressure sensors enable real-time monitoring and analysis of pressure levels in industrial processes, contributing to improved system performance, energy efficiency, and safety. They provide more accurate and detailed data, allowing for the early detection of potential issues before they escalate into costly equipment failures. The ability to integrate these smart sensors into existing Industrial Internet of Things (IIoT) ecosystems is further driving their adoption. By connecting smart pressure sensors to a network of other intelligent devices, companies can create highly efficient, interconnected systems that facilitate data exchange, process optimization, and seamless automation. The trend of adopting smart pressure sensors in industrial applications is helping companies improve operational efficiency, reduce downtime, and optimize maintenance strategies, making it one of the key trends shaping the market.
Environmental and Safety Regulations Driving Market Growth
Another important trend influencing the North America Pressure Sensor Market is the growing emphasis on environmental and safety regulations. As industries face increasing pressure to comply with stricter environmental and safety standards, the demand for pressure sensors that can ensure regulatory compliance is on the rise. In sectors such as oil and gas, chemical processing, and manufacturing, pressure sensors play a vital role in monitoring and controlling environmental parameters, such as gas and liquid pressures, which are essential for maintaining safe and efficient operations. In addition, sensors are crucial for detecting leaks, preventing hazardous spills, and ensuring the integrity of critical infrastructure. For example, in the oil and gas industry, pressure sensors are used to monitor the pressure levels in pipelines and drilling systems to prevent accidents that could result in environmental disasters. In response to growing concerns about climate change and workplace safety, businesses are increasingly investing in advanced pressure sensors that help them stay compliant with environmental regulations and avoid costly penalties. This trend is particularly prominent in North America, where stringent regulations such as those set by the Environmental Protection Agency (EPA) and Occupational Safety and Health Administration (OSHA) are pushing industries to adopt more sophisticated monitoring systems. As companies look to minimize their environmental footprint and ensure the safety of their operations, the role of pressure sensors will continue to be integral, driving sustained growth in the market.
Integration of IoT and Wireless Pressure Sensors
One of the most prominent trends in the North America Pressure Sensor Market is the integration of Internet of Things (IoT) capabilities with pressure sensors. IoT-enabled pressure sensors are revolutionizing various industries by allowing real-time, remote monitoring and data collection. These sensors are equipped with wireless communication technologies such as Bluetooth, Wi-Fi, or Zigbee, enabling them to transmit data to centralized systems or cloud-based platforms for analysis and monitoring. The growing demand for connected devices across sectors like industrial automation, automotive, and healthcare is driving this trend. For instance, the XDB316 Series Ceramic Pressure Sensors are specifically designed for the IoT industry, making them suitable for widespread applications in manufacturing and automation. These sensors can achieve remote monitoring, data analysis, and intelligent decision-making, improving operational efficiency and safety. In industrial applications, IoT-based pressure sensors help monitor equipment performance and detect anomalies in real-time, allowing for predictive maintenance and reducing downtime. In automotive applications, XIDIBEI tire pressure sensors provide accurate readings in real-time, helping to improve safety and reduce the risk of accidents. Similarly, in healthcare, IoT-enabled pressure sensors are becoming essential for remote patient monitoring, enhancing patient care and treatment outcomes. This trend reflects the increasing need for smarter and more efficient solutions in various sectors, where data-driven decision-making is becoming a priority.
Miniaturization of Pressure Sensors for Consumer Electronics and Wearables
Miniaturization of pressure sensors is another key trend shaping the North American market. As consumer electronics and wearable devices become more advanced, there is a growing need for smaller, more compact sensors that offer high accuracy while taking up minimal space. Pressure sensors are now being integrated into a wide array of consumer devices, from smartphones and smartwatches to fitness trackers and health-monitoring gadgets. These sensors are used to measure various parameters, such as altitude, barometric pressure, or even body temperature changes. The trend toward miniaturization is being driven by advancements in sensor technologies and materials, allowing manufacturers to create smaller, lighter, and more efficient sensors without compromising on performance. This is particularly evident in the healthcare sector, where miniature pressure sensors with an overall size of less than 2 mm × 2 mm or a pressure sensitive diaphragm area of less than 1 mm × 1 mm are being used for accurate blood pressure measurement in blood vessels with an inner diameter from 200 to 1000 μm. The DPS368, a robust and waterproofed barometric pressure sensor, is ideal for smartwatches, wearables, and smartphones, offering features like fitness tracking, step counting, fall detection, and navigation. With the increasing demand for health-conscious consumers seeking real-time health monitoring, the miniaturization trend is expected to continue to accelerate in North America, supporting market growth in consumer electronics and wearable devices.
Market Challenges
Technical Challenges in Integration and Calibration
Another significant challenge in the North America Pressure Sensor Market is the technical complexity involved in the integration and calibration of pressure sensors, particularly in highly automated or connected systems. As pressure sensors are increasingly integrated into IoT-based platforms and industrial automation systems, ensuring compatibility and proper calibration becomes more complicated. The pressure sensors must seamlessly interface with other system components, requiring sophisticated integration techniques. Furthermore, ensuring accurate and reliable performance across a wide range of operating conditions-such as temperature fluctuations, harsh environments, and varying pressure levels-adds to the complexity. Calibration processes for pressure sensors also require highly specialized equipment and procedures to ensure accuracy and reliability, particularly in critical applications like healthcare or aerospace. Any miscalibration or integration issues can lead to system malfunctions, safety risks, and costly operational downtimes. Overcoming these technical challenges requires continuous innovation in sensor design, testing protocols, and support systems to ensure seamless operation within interconnected systems, posing an ongoing challenge for manufacturers and end-users alike.
High Costs of Advanced Sensor Technologies
One of the key challenges faced by the North America Pressure Sensor Market is the high cost associated with advanced sensor technologies. While the demand for precision, reliability, and advanced features in pressure sensors continues to grow, the development and production of sensors that meet these standards require significant investments in research, development, and high-quality manufacturing processes. Advanced pressure sensors, particularly those used in specialized applications such as aerospace, automotive, and healthcare, often come with higher price tags due to their complex designs and the materials used.For instance, the development of micro-electromechanical systems (MEMS) and other cutting-edge sensor technologies has led to the creation of compact, lightweight, and highly sensitive pressure sensors. These advancements enhance performance and enable integration into various systems, such as aircraft components. However, they also lead to increased manufacturing costs due to intricate processes, specialized materials, and precise quality control requirements. Additionally, the integration of IoT capabilities and wireless communication in pressure sensors further increases costs, as these features require sophisticated hardware and software components.For many small and medium-sized enterprises (SMEs), the high initial investment required for these advanced sensors may present a barrier to adoption. This pricing challenge could potentially limit the widespread adoption of cutting-edge pressure sensors in price-sensitive industries, hindering market growth in the region.
Market Opportunities
Growth in Industrial Automation and Smart Manufacturing
The growing adoption of industrial automation and the increasing focus on smart manufacturing present a significant opportunity for the North America Pressure Sensor Market. As industries across sectors such as automotive, oil and gas, and manufacturing push toward digital transformation, the demand for pressure sensors capable of integrating with Internet of Things (IoT) platforms and advanced automation systems continues to rise. Pressure sensors play a crucial role in monitoring critical parameters, improving system reliability, and optimizing production processes in automated environments. With the ongoing expansion of Industry 4.0, smart factories, and predictive maintenance strategies, the need for precise, real-time data from pressure sensors is more important than ever. This trend provides a lucrative opportunity for manufacturers to develop innovative, smart, and IoT-enabled pressure sensor solutions that cater to the increasing demand for automation and process optimization across industries.
Expansion in Healthcare and Wearable Devices
Another significant market opportunity for pressure sensors in North America lies in the healthcare and wearable device sectors. With the increasing demand for health monitoring devices, wearables, and remote patient monitoring solutions, pressure sensors are becoming integral components of medical devices such as blood pressure monitors, ventilators, and fitness trackers. As consumers and healthcare providers focus more on real-time health monitoring and preventive care, there is an expanding market for advanced pressure sensors that offer high accuracy and reliability. Furthermore, with the growing trend of personalized healthcare and telemedicine, the need for compact, efficient, and non-invasive pressure sensors in wearable devices and home healthcare applications offers substantial growth potential in this sector.
Market Segmentation Analysis
By Application:
Pressure sensors in the automotive sector are used in tire pressure monitoring systems (TPMS), engine management, and fuel systems. The increasing adoption of electric and autonomous vehicles is fueling the demand for advanced pressure sensors in this sector.Pressure sensors in healthcare applications are widely used in devices like blood pressure monitors, ventilators, and infusion pumps. The growing demand for remote patient monitoring and the rise of wearable health devices are driving market growth in this segment.Pressure sensors are critical in ensuring the safe and efficient operation of automated systems in manufacturing. They help monitor pressure levels in hydraulic and pneumatic systems, enabling predictive maintenance and enhancing productivity in industrial environments.In the energy sector, pressure sensors are crucial for monitoring pressure levels in oil and gas pipelines, power plants, and renewable energy systems. The increasing focus on safety and efficiency in energy generation and distribution drives demand in this segment.Pressure sensors are increasingly used in consumer electronics such as smartphones, smartwatches, and fitness trackers. These sensors monitor parameters like altitude, barometric pressure, and internal device pressures, supporting the growing trend of wearable and connected devices.Aerospace applications require high-performance pressure sensors for monitoring cabin pressure, fuel systems, and hydraulic systems. The aerospace sector's strict safety and reliability standards are driving the demand for advanced pressure sensor technologies.In the oil and gas industry, pressure sensors are used in drilling systems, wellheads, and pipelines to ensure the safe and efficient transport and extraction of oil and gas. With the need to meet stringent safety and environmental regulations, this segment continues to see robust growth.
By Pressure Range:
Low Pressure (Up to 10 bar) sensors are commonly used in applications such as HVAC systems, automotive, and consumer electronics. These sensors help monitor the pressure in systems where low-pressure levels are critical for safe and efficient operation.Medium Pressure (10 bar – 100 bar) sensors are widely used in industrial manufacturing, automotive, and energy sectors, where they provide a balance between performance and cost. These sensors are essential for applications such as fuel systems, hydraulic systems, and pressure monitoring in compressors.High Pressure (Above 100 bar) sensors are critical for industries such as aerospace, oil and gas, and energy, where they measure extreme pressures in drilling systems, engines, and hydraulic systems. Their ability to withstand high-pressure environments makes them essential for these high-stakes applications.
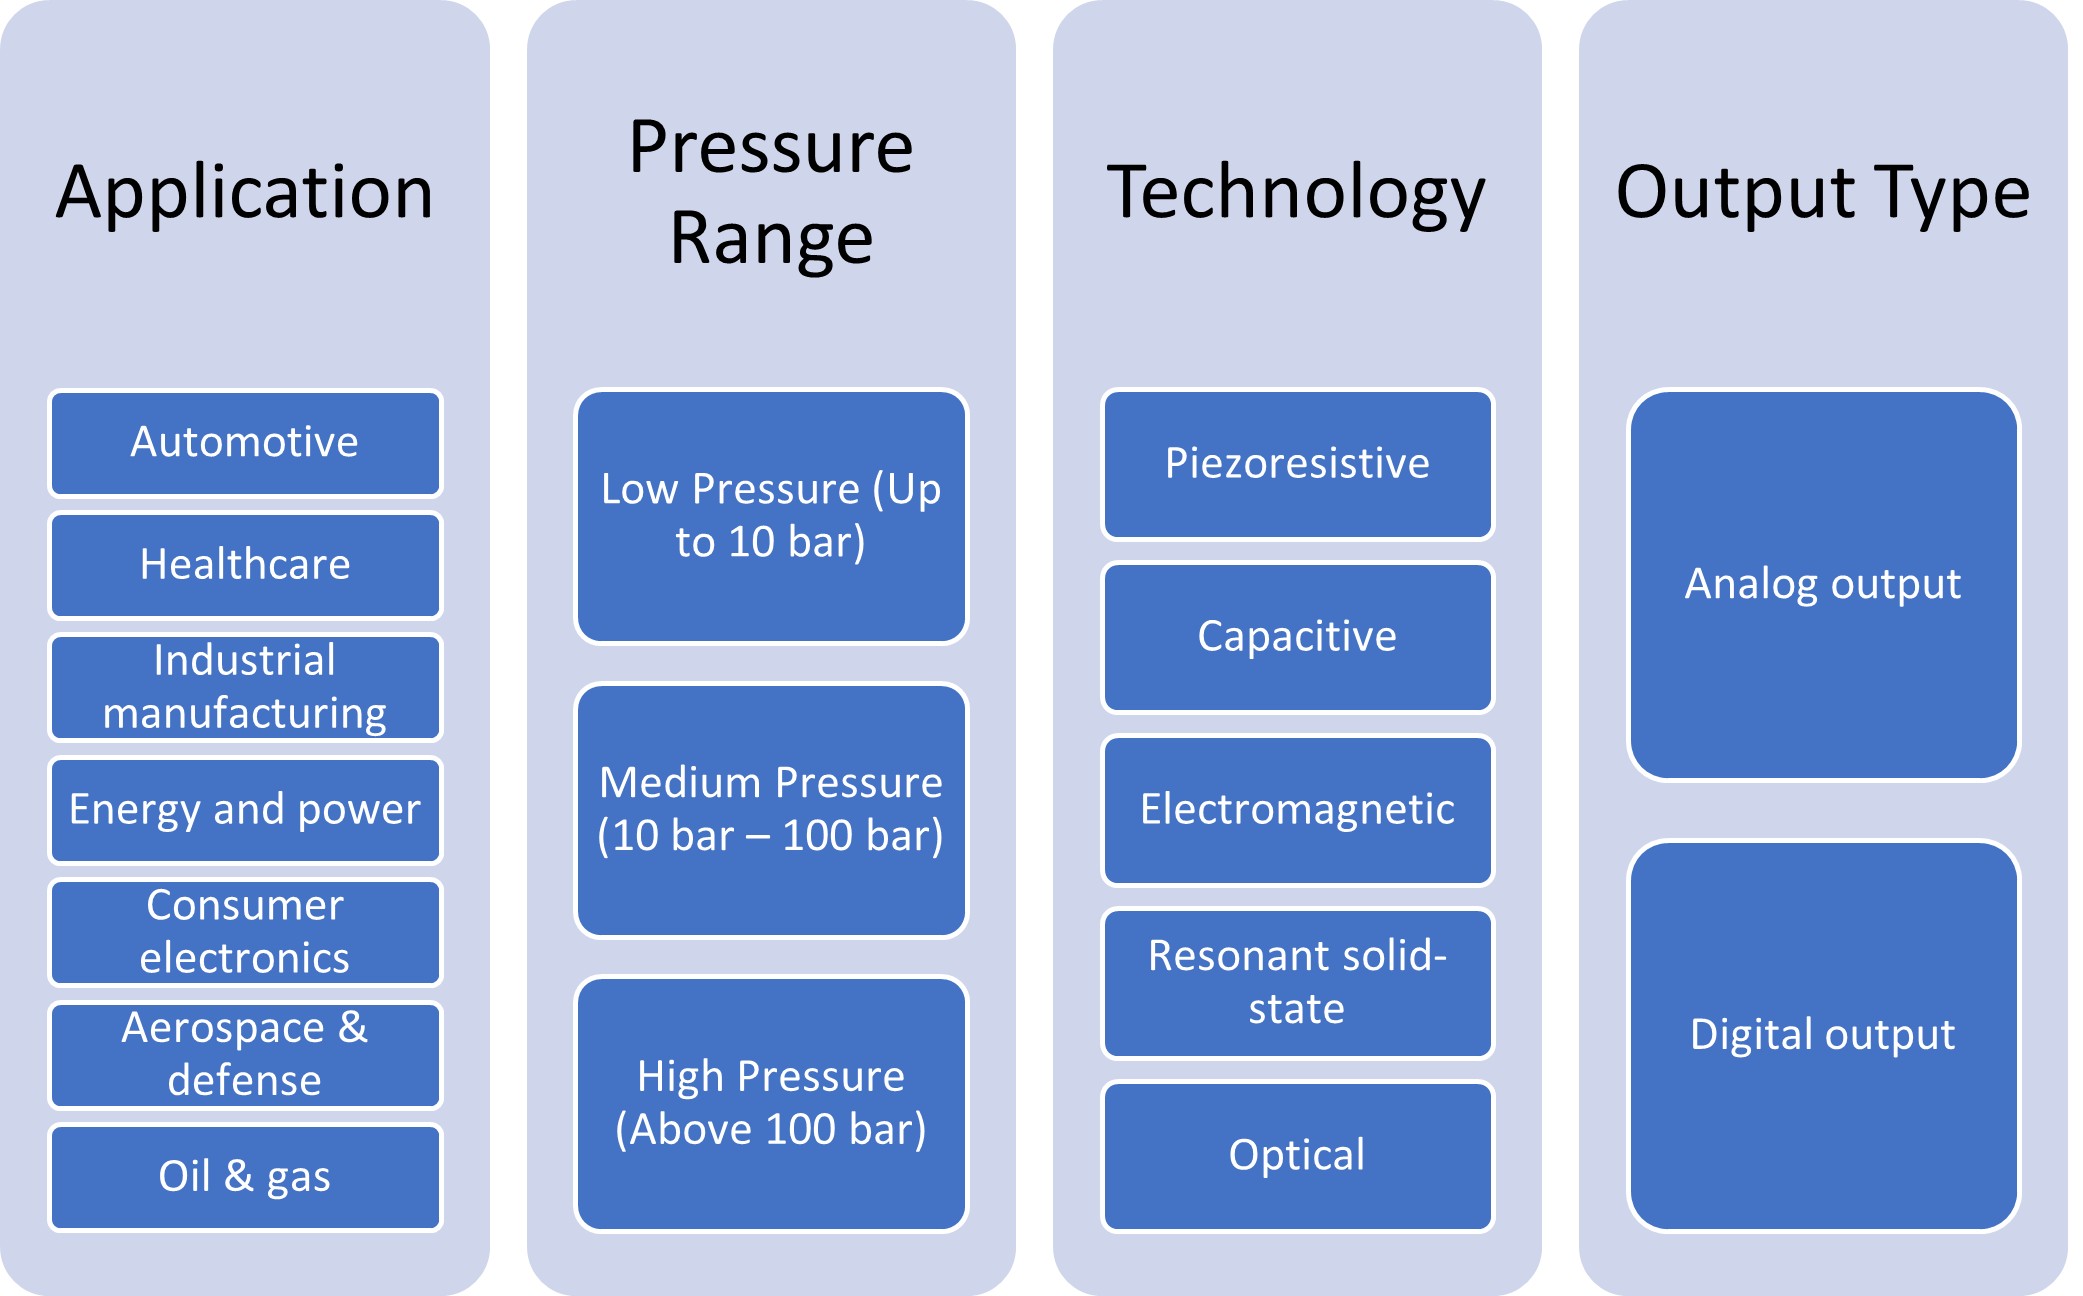
Segments
Based on Application
- Automotive
- Healthcare
- Industrial manufacturing
- Energy and power
- Consumer electronics
- Aerospace & defenseOil & gas
Based on pressure Range
- Low Pressure (Up to 10 bar)
- Medium Pressure (10 bar – 100 bar)
- High Pressure (Above 100 bar)
Based on Technology
- Piezoresistive
- Capacitivem
- Electromagnetic
- Resonant solid-state
- Optical
Based on Output Type
- Analog output
- Digital output
Based on Region
- United States
- Canada
Regional Analysis
United States (70%)
The United States dominates the North America Pressure Sensor Market, accounting for approximately 70% of the regional market share. The country’s vast industrial base, coupled with its leadership in automotive, aerospace, healthcare, and consumer electronics, significantly influences the demand for pressure sensors. The United States is at the forefront of the Industry 4.0 revolution, which is driving the need for smart, IoT-enabled sensors across various sectors. The automotive industry, in particular, is one of the major consumers of pressure sensors, especially with the rise of electric and autonomous vehicles. The healthcare sector, too, continues to expand, with the increasing demand for advanced medical devices that require precise pressure measurements, such as blood pressure monitors and ventilators. Additionally, industries like oil and gas, energy, and manufacturing are leveraging pressure sensors for safety, efficiency, and regulatory compliance, contributing to the market's growth.
Canada (25%)
Canada holds approximately 25% of the North America Pressure Sensor Market. While smaller than the U.S. market, Canada is a key player due to its strong presence in the oil & gas, energy, and manufacturing sectors. The country’s rich natural resources and growing focus on environmental sustainability drive the demand for pressure sensors in energy production, including oil extraction, refining, and renewable energy systems. Moreover, the industrial automation sector in Canada is expanding, with the growing need for high-precision sensors in manufacturing processes. The healthcare sector is also witnessing growth, with a focus on remote patient monitoring and medical diagnostics, driving further demand for pressure sensors.
Key players
- Ashcroft, Inc.
- Advance Electrical & Automation
- Nexon Meters Inc.
- Stellar Technology
- Setra Systems
Competitive Analysis
The North America Pressure Sensor Market is highly competitive, with key players such as Ashcroft, Inc., Advance Electrical & Automation, Nexon Meters Inc., Stellar Technology, and Setra Systems leading the industry. These companies differentiate themselves through innovative product offerings, strategic partnerships, and technological advancements. Ashcroft, Inc. stands out with its extensive product portfolio and strong financial performance, leveraging decades of expertise in pressure measurement solutions. Companies like Advance Electrical & Automation and Nexon Meters Inc. focus on providing customized sensor solutions for industrial and automation applications, ensuring their products meet the specific needs of their clients. Stellar Technology emphasizes high-precision sensors for critical applications such as aerospace and defense. Meanwhile, Setra Systems is recognized for its innovative approach in the healthcare sector, offering highly accurate pressure sensors for medical devices. Overall, these companies continue to drive market growth through research, development, and an ability to adapt to the rapidly changing technological landscape.
Recent Developments
- In March 2025, Honeywell International Inc launched the TruStability NSC Series pressure sensors, offering uncompensated and unamplified options for customers to perform their own calibration while benefiting from industry-leading stability, accuracy, and repeatability.
- In August 2024, Bosch Sensortec introduced the BMP581 barometric pressure sensor, utilizing capacitive technology instead of piezoresistive, resulting in 85% lower current consumption (1.3 µA), 80% reduced noise (0.08 Pa), and 33% improved temperature coefficient offset (± 0.5 Pa/K).
- In July 2024, Analog Devices Inc. released the MAX40109 low-power precision sensor interface SoC for pressure sensor applications, featuring a high-precision programmable analog front-end and digital signal processing capabilities.
- In November 2023, IFM Electronic released a series of wireless pressure sensors designed specifically for remote monitoring in oil and gas applications.
Market Concentration and Characteristics
The North America Pressure Sensor Market exhibits a moderate to high level of market concentration, with a few key players holding significant shares while several smaller players contribute to niche applications. The market is characterized by technological innovation, with companies focusing on advancements in sensor accuracy, miniaturization, and IoT integration. Major players, such as Honeywell International Inc., Emerson Electric Co., and Bosch Group, dominate the market by offering a diverse range of pressure sensor solutions across various industries, including automotive, healthcare, industrial manufacturing, and energy. The market is also marked by intense competition in terms of product differentiation, where companies differentiate through specialized features like wireless capabilities, smart sensors, and high durability for harsh environments. With increasing demand for automation, predictive maintenance, and smart manufacturing, market dynamics are continually evolving, with both established players and new entrants driving innovation and market growth.
Report Coverage
The research report offers an in-depth analysis based on Application, Pressure Range, Technology, Output Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing adoption of automation in manufacturing and industrial sectors will significantly drive the demand for pressure sensors. Automation technologies rely on real-time data, and pressure sensors are critical in monitoring and controlling industrial processes.
- The growth of the electric vehicle (EV) market in North America will increase the need for advanced pressure sensors in applications such as battery management systems and tire pressure monitoring. EVs require precise pressure monitoring to enhance performance and safety.
- As IoT technologies continue to expand across industries, the demand for connected pressure sensors will grow. These sensors will enable real-time monitoring and data analytics for improved operational efficiency and predictive maintenance.
- The North American push toward renewable energy sources, such as wind and solar power, will create new opportunities for pressure sensors in monitoring energy production and distribution systems. These sensors will play a crucial role in ensuring the efficiency and safety of renewable energy technologies.
- The healthcare sector’s reliance on medical devices for patient monitoring will drive the need for accurate and reliable pressure sensors. Medical applications like ventilators, infusion pumps, and blood pressure monitors are expected to boost market growth.
- Ongoing advancements in sensor miniaturization will enable the development of compact, high-performance sensors. These smaller sensors will find applications in consumer electronics, wearables, and medical devices, creating new market opportunities.
- New sensor technologies, such as optical and resonant solid-state sensors, will continue to emerge, offering enhanced accuracy and reliability. These innovations will cater to high-demand industries like aerospace, automotive, and energy.
- The increasing trend of smart sensors that provide not only pressure measurement but also self-diagnostics and self-calibration will drive market growth. These smart sensors are essential for the evolving needs of industries requiring autonomous and efficient systems.
- The oil and gas industry’s heightened focus on safety, environmental regulations, and efficiency will lead to greater adoption of pressure sensors. These sensors are essential for monitoring critical parameters in drilling systems, pipelines, and refining processes.
- The growing trend of connected consumer electronics, such as smartwatches, fitness trackers, and smartphones, will create new opportunities for pressure sensors. These sensors will monitor barometric pressure, altitude, and other parameters in these devices.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Healthcare Sector Advancements and Demand for Medical Devices
The increasing reliance on advanced medical devices in North America, such as ventilators, infusion pumps, and wearable health monitors, is driving demand for high-precision pressure sensors. The need for accurate and reliable pressure measurement in patient monitoring and critical care is fueling market growth in the healthcare segment.
Growth in the Oil and Gas Industry and Need for Pressure Management
Pressure sensors are essential for safe and efficient operations in oil and gas exploration, production, and refining. As North America continues to expand its energy sector and focus on safety and environmental compliance, the demand for robust pressure sensors in drilling systems, pipelines, and storage facilities is rising.
Increasing Demand for Automation and Industry 4.0 Integration
The adoption of automation and Industry 4.0 technologies across manufacturing, automotive, and industrial sectors is boosting the need for pressure sensors that enable real-time monitoring, predictive maintenance, and process optimization. Smart factories and connected systems depend on accurate pressure data to ensure operational efficiency and safety.
Expansion of the Automotive Industry and Need for Safety Features
Modern vehicles, including electric and autonomous models, require advanced pressure sensors for applications such as tire pressure monitoring, engine management, and safety systems like airbags and stability control. The push for enhanced vehicle safety and performance is a key driver in the automotive sector.
Integration of IoT and Wireless Pressure Sensors
The trend toward IoT-enabled and wireless pressure sensors is enabling remote monitoring, data analytics, and predictive maintenance across industries. This integration supports operational efficiency and real-time decision-making, further accelerating the adoption of advanced pressure sensors in North America.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the North America Pressure Sensor Market in 2023 and 2032?
What factors are driving the growth of the North America Pressure Sensor Market?
How are advancements in sensor technology contributing to market expansion?
Which industries are the largest consumers of pressure sensors in North America?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Piezoresistive
- 1.2.2 Capacitive
- 1.2.3 Electromagnetic
- 1.2.4 Resonant Solid-State
- 1.2.5 Optical
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Healthcare
- 1.3.3 Industrial Manufacturing
- 1.3.4 Energy and Power
- 1.3.5 Consumer Electronics
- 1.3.6 Aerospace & Defense
- 1.3.7 Oil & Gas
- 1.4 By Output Type
- 1.4.1 Analog Output
- 1.4.2 Digital Output
- 1.5 By Pressure Range
- 1.5.1 Low Pressure (Up to 10 bar)
- 1.5.2 Medium Pressure (10 bar – 100 bar)
- 1.5.3 High Pressure (Above 100 bar)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,679.45 million → 2024: USD 6,679.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Pressure Sensor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Pressure Sensor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2024
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2024
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Pressure Sensor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2024
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Pressure Sensor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Pressure Sensor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Pressure Sensor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 North America Pressure Sensor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Pressure Sensor Market Outlook, 2024-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,679.45 million → 2024: USD 6,679.45 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 Volume Forecast to 2024
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Pressure Sensor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2024
- 12.3.4 Volume Forecast, 2024-2024
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Piezoresistive
- 12.3.7.2 Capacitive
- 12.3.7.3 Electromagnetic
- 12.3.7.4 Resonant Solid-State
- 12.3.7.5 Optical
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2024
- 12.4.4 Volume Forecast, 2024-2024
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Healthcare
- 12.4.7.3 Industrial Manufacturing
- 12.4.7.4 Energy and Power
- 12.4.7.5 Consumer Electronics
- 12.4.7.6 Aerospace & Defense
- 12.4.7.7 Oil & Gas
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Output Type - Market Size and Forecast, 2024-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2024
- 12.5.4 Volume Forecast, 2024-2024
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Analog Output
- 12.5.7.2 Digital Output
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Pressure Range - Market Size and Forecast, 2024-2024
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2024
- 12.6.4 Volume Forecast, 2024-2024
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Low Pressure (Up to 10 bar)
- 12.6.7.2 Medium Pressure (10 bar – 100 bar)
- 12.6.7.3 High Pressure (Above 100 bar)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North America Pressure Sensor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Pressure Sensor Geographic Market Outlook, 2024-2024
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2024
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Pressure Sensor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2024
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Pressure Sensor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2024
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Emerson Electric Co.
- 18.4 Bosch Group
- 18.5 Ashcroft, Inc.
- 18.6 Setra Systems
- 18.7 Stellar Technology
- 18.8 Analog Devices Inc.
- 18.9 IFM Electronic
- 18.10 Nexon Meters Inc.
- 18.11 Advance Electrical & Automation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

