
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| NVOCC Aggregator MarketSize 2024 | USD 11325.11 million |
| NVOCC Aggregator Market, CAGR | 13.5% |
| NVOCC Aggregator Market Size 2032 | USD 31189.5 million |
Market Overview:
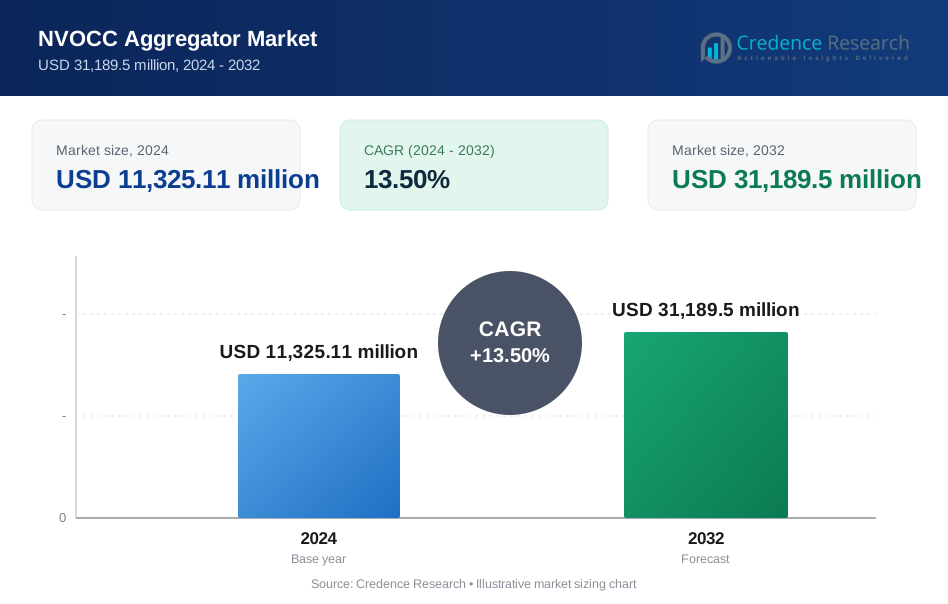
NVOCC Aggregator Market size was valued at USD 11325.11 million in 2024 and is anticipated to reach USD 31189.5 million by 2032, at a CAGR of 13.5% during the forecast period (2024-2032).
The market is propelled by the rise in cross-border e-commerce, demand for end-to-end supply chain visibility, and the adoption of cloud-based platforms that enhance cargo tracking, booking, and document management. The fragmented nature of ocean freight logistics encourages the use of NVOCC aggregators to streamline operations, reduce reliance on traditional freight forwarders, and improve turnaround time. The integration of AI, IoT, and blockchain technologies into aggregator platforms also fosters transparency and real-time data sharing, enabling better coordination between shippers, carriers, and consignees. The ability to access dynamic pricing tools and route optimization modules gives users a competitive edge. Aggregators also play a strategic role in helping customers meet compliance requirements and environmental standards across jurisdictions.
Asia Pacific leads with major transshipment hubs in Singapore, China, and India, supporting robust container volumes and manufacturing exports. North America benefits from advanced transportation management systems, IoT-enabled cargo tracking, and strategic alliances with e-commerce platforms that enhance fulfillment efficiency. Europe leverages modern port infrastructure, multimodal connectivity, and harmonized customs procedures to expedite cross-border shipping. Latin America strengthens its freight corridors through targeted port upgrades and regional trade agreements, while the Middle East & Africa capitalize on strategic shipping lanes and smart-port initiatives to drive platform uptake. Aggregators across all regions leverage local agent networks, multi-port connectivity, and compliance expertise to deliver seamless, cost-effective logistics solutions that meet evolving sustainability and regulatory requirements.
Market Insights:
- The NVOCC Aggregator Market reached USD 11,325.11 million in 2024 and will grow to USD 31,189.5 million by 2032 at a 5% CAGR.
- Rapid cross-border e-commerce expansion drives demand for bulk consolidation and competitive freight rates.
- Shippers demand end-to-end visibility, prompting adoption of centralized tracking and secure document management.
- Cloud-based platforms streamline booking workflows, automate rate comparisons, and accelerate deployment.
- Ocean freight fragmentation encourages reliance on aggregators to optimize container utilization and reduce forwarder dependency.
- Integrating AI analytics, IoT sensors, and blockchain strengthens transparency, real-time data sharing, and risk management.
- Asia Pacific leads market share with hubs in Singapore, China, and India, followed by North America, Europe, Latin America, and Middle East & Africa.
Market Drivers:
Surge in Cross-Border E-commerce Volume Drives Market Demand:
Cross-border e-commerce platforms have expanded rapidly, prompting logistics providers to seek consolidated freight solutions. The NVOCC Aggregator Market caters to small and medium shippers by offering bulk purchasing power. It consolidates shipments and secures competitive rates from multiple carriers. Aggregators reduce manual coordination among partners and streamline booking processes. It delivers reliable transit schedules and transparent pricing to end users. Investors recognize this trend and increase funding for aggregator platforms.
Rising Demand for End-to-End Supply Chain Transparency and Visibility:
Shippers require greater supply chain transparency due to complex trade lanes. The NVOCC Aggregator Market responds with centralized tracking systems. It delivers real-time updates on container location across inland and ocean segments. Customers gain actionable insights that improve scheduling and inventory planning. It minimizes delays through proactive alerts and secure document exchange. Shippers leverage this capability to meet global compliance standards. Investors favor platforms that provide comprehensive analytics to stakeholders.
- For instance, Sourcemap provides blockchain-based supply chain mapping solutions that allow companies to trace their supply chains down to the origin of raw materials, helping ensure compliance with due diligence requirements and responsible sourcing practices.
Adoption of Cloud-Based Freight Management Platforms and Online Booking Systems:
Cloud-based freight management platforms gain traction among logistics providers. The NVOCC Aggregator Market benefits from scalable infrastructure and rapid deployment. It supports seamless integration with carrier systems and third-party logistics applications. Users access secure portals for rate comparison and online booking confirmations. It reduces IT overhead and accelerates time-to-market for new service offerings. Companies value this digital model for predictable operating costs and enhanced agility. Platforms that integrate with ERP and IoT sensors command a competitive edge.
- For instance, Softlink Global’s Logi-Sys platform is a comprehensive cloud-based logistics management solution that integrates logistics, finance, and operational functions, providing real-time shipment visibility and advanced analytics for freight forwarders and logistics service providers.
Emphasis on Sustainable and Cost-Efficient Logistics Partnerships:
Environmental regulations and cost pressures motivate shippers to optimize logistics strategies. The NVOCC Aggregator Market enables partnerships that consolidate cargo and lower emissions. It secures volume-based discounts that reduce freight unit costs. Aggregators negotiate voyage options that carriers publish with favorable carbon metrics. It monitors sustainability performance and supports ESG reporting requirements. Shippers benefit from combined shipments that minimize empty container repositioning. Investors view these platforms favorably for long-term cost savings and environmental impact.
Market Trends:
Expansion of Cloud-Based Freight Ecosystems Strengthens Platform Capabilities:
The expansion of cloud-based freight ecosystems improves scalability and reduces IT overhead. The NVOCC Aggregator Market leverages these ecosystems to offer dynamic rate comparisons. It enhances user access through web portals and mobile applications that provide instant booking confirmations. Integration with carrier booking engines and transportation management systems streamlines data exchange. It consolidates disparate shipment records into a unified dashboard. Freight operators rely on automated alerts to adjust schedules quickly. It provides cargo visibility across multimodal legs and inland networks.
- For instance, CTSI-Global leverages Cleo Integration Cloud to unify data from multiple logistics partners, providing clients with operational dashboards, real-time analytics, and enhanced supply chain visibility.
Adoption of AI-Driven Analytics Enhances Decision Making and Risk Management:
The adoption of AI-driven analytics transforms cargo routing and demand forecasting. The NVOCC Aggregator Market harnesses predictive models to allocate capacity accurately. It analyzes historical shipment records to reduce dwell times and prevent port bottlenecks. Aggregators simulate scenarios that strengthen negotiation of carrier rates. It tracks carrier performance metrics and guides alliance development. Freight professionals apply real-time alerts to mitigate delays from weather or congestion. It drives data-driven decisions that refine supply chain processes.
- For instance, Maersk utilizes AI to optimize shipping routes and reduce fuel consumption by analyzing weather and ocean data.
Market Challenges Analysis:
Complexity of Carrier Contracts and Volatile Rate Environment:
Carriers update rate structures frequently, which complicates contract management for aggregators. The NVOCC Aggregator Market depends on stable contracts to secure favorable rates. Aggregators negotiate with multiple carriers, and inconsistent terms hamper predictable pricing. It must allocate resources to monitor contract amendments in various trade lanes. Discrepancies in fuel surcharges and currency adjustment factors can erode margins. It struggles to maintain end-user trust when sudden rate changes impact shipment costs. This scenario discourages shippers from committing to long-term volume agreements.
- For instance, CargoSphere’s SUDS technology has enabled logistics providers to efficiently process and manage complex carrier contracts, improving management control and internal accountability while streamlining the handling of contract amendments.
Challenges in System Integration and Data Standardization Across Multiple Platforms:
Integration of legacy systems with modern aggregator platforms demands significant IT investment. The NVOCC Aggregator Market must manage data from carriers, ports, and customs authorities. It needs uniform data formats to deliver clear shipment status reports. Disparate EDI protocols and API standards create gaps in real-time visibility. It must reconcile carrier feeds, manually check field mappings, and correct mismatches. Inconsistent terminology for container types and free time rules leads to errors. It may face booking delays when teams address conflicting information.
Market Opportunities:
Growth Potential in SME-Focused Freight Consolidation:
Rising demand from small and medium shippers drives new use cases for bulk booking. The NVOCC Aggregator Market can package multiple small shipments into single containers. It negotiates competitive rates that individual shippers cannot secure independently. It streamlines documentation workflows and reduces administrative burdens for SMEs. Partnerships with local agent networks extend service coverage. It improves delivery predictability and builds trust among emerging exporters. New marketing channels can raise awareness among underserved businesses.
Opportunity through Integration of Trade Finance and Regulatory Compliance Solutions:
Trade finance platforms can integrate directly into aggregator portals to support letter of credit issuance. The NVOCC Aggregator Market stands to benefit from offering embedded financing options. It enhances customer loyalty by shortening payment cycles for high-volume clients. It monitors shipment compliance data and automates customs filing processes. Automated compliance reduces risk of fines and delays at destination ports. It promotes collaboration between financial institutions, carriers, and shippers. Such integrations create differentiated value and open new revenue streams.
Market Segmentation Analysis:
By Customer Type
The NVOCC Aggregator Market divides by customer type into enterprise shippers, small and medium enterprises, and e-commerce retailers. Enterprise shippers leverage bulk contracts for high-volume routes and demand integrated visibility tools. SMEs seek cost-effective freight consolidation that reduces administrative burden. Retailers pursue aggregator solutions to handle seasonal volume surges and reduce lead time. It offers tiered service plans that align with each customer profile and meet specific budget and operational requirements.
By Service Offering
By service offering, the NVOCC Aggregator Market segments include rate negotiation, documentation management, cargo consolidation, and value-added visibility platforms. Rate negotiation tools secure competitive tariffs across multiple carriers. Documentation management workflows streamline bill of lading issuance and compliance filings. Cargo consolidation services enhance container utilization and lower per-unit costs. Visibility platforms deliver unified dashboards that display real-time shipment status. It supports API integrations that connect with carrier systems and customer portals.
By Technology Adoption
The NVOCC Aggregator Market segments technology adoption into cloud-native platforms, AI-driven analytics, IoT-enabled tracking, and blockchain-powered documentation. Cloud platforms provide scalability and rapid deployment across global operations. AI analytics deliver predictive insights that optimize route planning and capacity allocation. IoT tracking sensors record container conditions and location throughout transit. Blockchain documentation maintains tamper-proof records for secure trade compliance. It promotes innovation to meet evolving logistics demands.
Segmentations:
By Customer Type
- Enterprise Shippers
- Small and Medium Enterprises (SMEs)
- E-commerce Retailers
By Service Offering
- Rate Negotiation
- Documentation Management
- Cargo Consolidation
- Visibility Platforms
By Technology Adoption
- Cloud-Native Platforms
- AI-Driven Analytics
- IoT-Enabled Tracking
- Blockchain Documentation
By Cargo Type
- Full Container Load (FCL)
- Less than Container Load (LCL)
- Breakbulk
- Special Cargo
By Pricing Model
- Spot Rates
- Contract Rates
- Dynamic Pricing
- Subscription-Based
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Strategic Leadership of Asia Pacific through Major Transshipment Hubs
Asia Pacific region holds 38% share of the NVOCC Aggregator Market. It benefits from major ports such as Singapore and Shanghai that handle high container volumes. It leverages extensive feeder networks linking secondary ports and inland distribution centers. Government investments in port modernization increase adoption of aggregator platforms. NVOCC aggregators integrate with regional digital corridors to improve booking accuracy and cargo visibility. Shippers rely on bulk consolidation to lower freight costs and streamline customs compliance.
Robust Infrastructure and Technology Adoption in North America
North America region holds 27% share of the NVOCC Aggregator Market. It capitalizes on advanced transportation management systems integrated with aggregator portals. Secure APIs enable real-time rate benchmarking and container tracking across networks. EDI protocol standardization reduces manual data entry and accelerates document processing. Collaborations between carriers and aggregators optimize lane performance and reduce empty repositioning. Shippers benefit from consistent transit schedules and enhanced supply chain resilience.
Emerging Growth Potential in Europe, Latin America and Middle East & Africa
Europe region holds 22% share of the NVOCC Aggregator Market. It capitalizes on harmonized customs frameworks and multimodal corridors connecting seaports to inland hubs. Port expansion and regional trade agreements drive logistics efficiency across Latin America. Middle East & Africa leverage smart port technologies and free trade zones to attract aggregator services. Aggregators navigate diverse regulatory environments to ensure compliance and maintain delivery reliability. Strong agent networks support service reach and enhance last-mile coordination.
Key Player Analysis:
- Apex Shipping
- Expeditors International
- DHL Global Forwarding
- Nippon Express
- DB Schenker
- Sinotrans
- Kuehne + Nagel
- CEVA Logistics
- Kintetsu World Express
- SEKO Logistics
Competitive Analysis:
Major global freight forwarders such as Kuehne + Nagel, DB Schenker, Nippon Express and CEVA Logistics vie for market share by providing integrated rate management and booking platforms. The NVOCC Aggregator Market shows moderate concentration with top tier companies that control broad carrier relationships and extensive route networks. It leverages strategic alliances with shipping lines to secure capacity during peak seasons. Emerging digital natives invest heavily in AI analytics and blockchain record keeping to differentiate service. Firms compete on pricing agility by offering spot, contract and subscription models tailored to shipper needs. Technology integration ranks high on buyer priorities, and platforms with robust API frameworks maintain a competitive edge. Customer service quality and compliance expertise influence retention and new customer acquisition. Regional specialists build local agent partnerships to offer tailored support in Asia Pacific and Latin America markets. Collaborative ventures with trade finance providers extend working capital solutions to clients.
Recent Developments:
- In January 2024, Nippon Express (NX Global Ocean Network, NXGO) launched new NVOCC services in Singapore, aiming to achieve competitive pricing through centralized purchasing and to globally unify the NX Group’s international ocean freight services under the “NX” brand.
- In January 2024, Expeditors International announced its intent to grow its operational footprint globally by leveraging partnerships across multiple regions, emphasizing innovative technology solutions and infrastructure investments to streamline operations and enhance efficiency.
- In August 2024, Sinotrans partnered with Hangzhou Aviation Economic Development Co to launch the eHub project in the Hangzhou Airport Economic Demonstration Zone.
Market Concentration & Characteristics:
The NVOCC Aggregator Market exhibits moderate concentration. The top five players account for significant share while numerous regional firms maintain niche positions. It features high barriers to entry due to established carrier alliances and strict regulatory compliance requirements. Major players leverage scale advantage to negotiate volume discounts and invest in advanced analytics and blockchain technologies to strengthen service reliability. Clients expect unified rate management, real-time visibility, and flexible pricing options. It balances consolidation benefits with the need for localized expertise. The market operates on network effects where platform adoption drives carrier participation and expands route coverage. Regulatory changes and sustainability mandates shape provider strategies and service portfolios. It encourages providers to pursue strategic mergers and acquisitions to broaden coverage and diversify services.
Report Coverage:
The research report offers an in-depth analysis based on Customer Type, Service Offering, Technology Adoption, Cargo Type, Pricing Model, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The NVOCC Aggregator Market will drive deeper integration of blockchain solutions to ensure tamper-proof documentation, accelerate global trade compliance, and improve auditability.
- It will prioritize adoption of AI-based predictive analytics to optimize route selection, forecast demand fluctuations, and improve capacity planning efficiency.
- It will invest in IoT sensor networks to provide granular visibility of cargo conditions throughout global multimodal transit operations.
- It will expand partnerships with fintech firms to offer embedded trade finance and flexible cargo insurance options on aggregator platforms.
- It will leverage digital twin models and scenario-based simulation tools to assess supply chain disruptions and strengthen resilience.
- It will scale cloud-native platforms to support dynamic, AI-powered resource allocation and real-time booking and tracking during peak demand.
- It will strengthen cybersecurity protocols to protect sensitive shipment data and secure platform integrity with advanced encryption and threat detection.
- It will enter emerging markets by establishing local agency networks and tailoring digital platform services to diverse trade requirements.
- It will enhance transparent sustainability reporting modules to help shippers track emissions and comply with evolving ESG mandates.
- It will foster strategic alliances across carriers and port authorities to streamline multimodal connectivity, integrate tracking platforms, and reduce lead times.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Cross-Border E-commerce Volume
The rapid expansion of cross-border e-commerce is driving demand for consolidated freight solutions, as NVOCC aggregators enable small and medium shippers to access bulk rates and streamlined booking processes, reducing costs and improving reliability.
Demand for End-to-End Supply Chain Visibility
Shippers increasingly require real-time tracking and centralized management of shipments across complex trade lanes, prompting adoption of aggregator platforms that offer integrated visibility, actionable insights, and secure document exchange.
Adoption of Cloud-Based Freight Management Platforms
Cloud-native platforms are transforming the market by enabling rapid deployment, seamless integration with carrier systems, and automated workflows for booking and rate comparison, which reduces IT overhead and accelerates service innovation.
Emphasis on Sustainable and Cost-Efficient Logistics
Environmental regulations and cost pressures are motivating shippers to partner with aggregators for cargo consolidation, which lowers emissions and unit freight costs, while supporting compliance with ESG reporting and sustainability mandates.
Integration of Advanced Technologies (AI, IoT, Blockchain)
The integration of AI-driven analytics, IoT-enabled tracking, and blockchain documentation enhances transparency, risk management, and operational efficiency, giving aggregators and their customers a competitive edge in global logistics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the NVOCC Aggregator Market size in 2024 and its forecast for 2032?
What drives growth in the NVOCC Aggregator Market?
Which technologies power NVOCC aggregator platforms?
Which region leads the NVOCC Aggregator Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cargo Type
- 1.2.1 Full Container Load (FCL)
- 1.2.2 Less than Container Load (LCL)
- 1.2.3 Breakbulk
- 1.2.4 Special Cargo
- 1.3 By Customer Type
- 1.3.1 Enterprise Shippers
- 1.3.2 Small and Medium Enterprises (SMEs)
- 1.3.3 E-commerce Retailers
- 1.4 By Service Offering
- 1.4.1 Rate Negotiation
- 1.4.2 Documentation Management
- 1.4.3 Cargo Consolidation
- 1.4.4 Visibility Platforms
- 1.5 By Technology Adoption
- 1.5.1 Cloud-Native Platforms
- 1.5.2 AI-Driven Analytics
- 1.5.3 IoT-Enabled Tracking
- 1.5.4 Blockchain Documentation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,325.11 million → 2032: USD 31,189.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global NVOCC Aggregator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global NVOCC Aggregator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global NVOCC Aggregator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global NVOCC Aggregator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global NVOCC Aggregator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global NVOCC Aggregator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global NVOCC Aggregator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global NVOCC Aggregator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,325.11 million → 2032: USD 31,189.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global NVOCC Aggregator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cargo Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Full Container Load (FCL)
- 12.3.7.2 Less than Container Load (LCL)
- 12.3.7.3 Breakbulk
- 12.3.7.4 Special Cargo
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enterprise Shippers
- 12.4.7.2 Small and Medium Enterprises (SMEs)
- 12.4.7.3 E-commerce Retailers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Offering - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rate Negotiation
- 12.5.7.2 Documentation Management
- 12.5.7.3 Cargo Consolidation
- 12.5.7.4 Visibility Platforms
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology Adoption - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cloud-Native Platforms
- 12.6.7.2 AI-Driven Analytics
- 12.6.7.3 IoT-Enabled Tracking
- 12.6.7.4 Blockchain Documentation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global NVOCC Aggregator End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global NVOCC Aggregator Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global NVOCC Aggregator Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global NVOCC Aggregator Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Apex Shipping
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Expeditors International
- 18.4 DHL Global Forwarding
- 18.5 Nippon Express
- 18.6 DB Schenker
- 18.7 Sinotrans
- 18.8 Kuehne + Nagel
- 18.9 CEVA Logistics
- 18.10 Kintetsu World Express
- 18.11 SEKO Logistics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

