
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
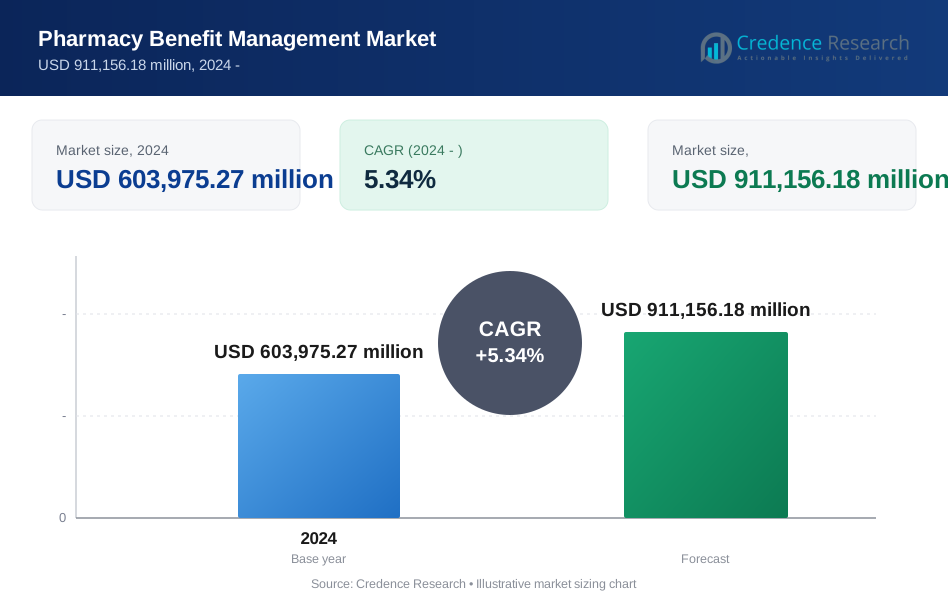
| Pharmacy Benefit Management Market Size 2024 | USD 603,975.27 million |
| Pharmacy Benefit Management Market, CAGR | 5.34% |
| Pharmacy Benefit Management Market Size 2032 | USD 911,156.18 million |
Market Overview
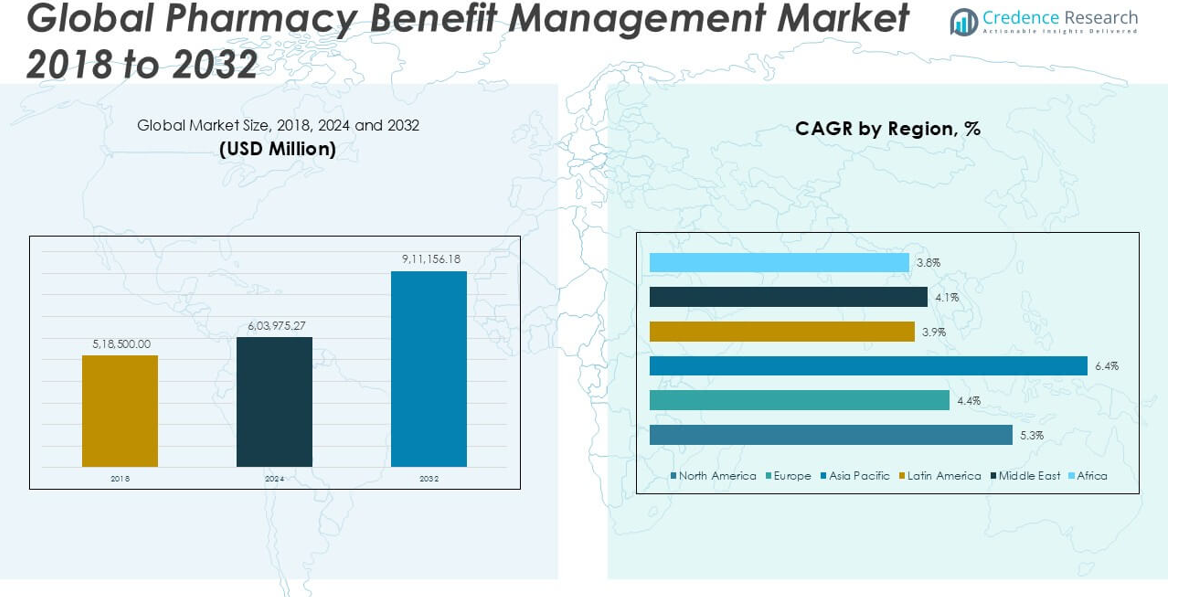
The Pharmacy Benefit Management market size was valued at USD 518,500.00 million in 2018 and USD 603,975.27 million in 2024, and it is anticipated to reach USD 911,156.18 million by 2032, growing at a CAGR of 5.34% during the forecast period.
The Pharmacy Benefit Management (PBM) market is led by major players such as CVS Health Corporation, Express Scripts Holding Company, OptumRx, Inc., Cigna Corporation, Prime Therapeutics LLC, and MedImpact Healthcare Systems, Inc. These companies dominate the competitive landscape through integrated healthcare solutions, robust specialty pharmacy services, and advanced cost management strategies. CVS Health Corporation holds a significant market presence due to its wide retail network and comprehensive PBM offerings. North America is the leading region, capturing approximately 37.7% of the global PBM market in 2024, driven by established healthcare infrastructure and high adoption of PBM services.
Market Insights
- The Pharmacy Benefit Management (PBM) market was valued at USD 603,975.27 million in 2024 and is expected to reach USD 911,156.18 million by 2032, growing at a CAGR of 5.34% during the forecast period.
- The growing demand for cost-effective prescription drug management and increasing use of specialty pharmacy services are driving the market growth, with specialty pharmacy services holding the largest segment share.
- Key trends include the rapid expansion of specialty drug management, the integration of digital health technologies, and the shift towards value-based care models enhancing PBM service offerings.
- The market is highly competitive with leading players such as CVS Health Corporation, Express Scripts, and OptumRx focusing on partnerships, specialty services, and transparent pricing strategies; however, regulatory pressures and increasing competition from direct-to-consumer models pose significant challenges.
- North America leads the market with a 37.7% share, followed by Asia Pacific at 30.0% and Europe at 20.3%, driven by strong healthcare systems and increasing adoption of PBM solutions.
Market Segmentation Analysis:
By Services:
In the Pharmacy Benefit Management (PBM) market, Specialty Pharmacy Services hold the dominant position within the services segment, accounting for the largest market share. The growing prevalence of chronic and complex diseases, such as cancer and autoimmune disorders, drives demand for specialty drugs that require close management and high-cost handling. These services offer tailored medication support and improved patient outcomes, contributing to their rapid adoption. Additionally, the increasing focus on cost-containment strategies and patient adherence programs further propels the growth of specialty pharmacy services, making them the most influential sub-segment in this category.
- For instance, CVS Specialty dispensed over 43 million specialty prescriptions in 2020, supported by its advanced medication therapy management programs that track patient adherence in real-time.
By Business Model
Among the business models, Health Insurance Management leads the Pharmacy Benefit Management market, holding the largest market share. The dominance of this model is driven by the widespread integration of PBM services within health insurance plans, which enables insurers to optimize drug pricing, manage formularies efficiently, and streamline claims processing. The growing emphasis on reducing healthcare costs and enhancing access to affordable medications significantly contributes to the expansion of this sub-segment. The rising adoption of value-based care models and increasing collaboration between insurers and PBMs further strengthen the growth of health insurance management as the primary business model.
- For instance, UnitedHealth Group’s OptumRx processed over 1.3 billion adjusted prescriptions in 2020, demonstrating its scale and efficiency in integrating PBM services with health insurance management.
By End Use
Within the end-use segment, the Commercial sector dominates the Pharmacy Benefit Management market, capturing the largest market share. This dominance is primarily attributed to the substantial presence of employer-sponsored health plans and the continuous demand for cost-effective prescription drug coverage among working populations. The commercial sector benefits from a competitive landscape where PBMs offer customized solutions to manage drug costs, improve formulary design, and enhance patient support services. Additionally, the increasing number of corporate partnerships with PBMs to control rising pharmaceutical expenditures further accelerates the growth of the commercial end-use segment.
Market Overview
Rising Demand for Cost-Effective Prescription Management
The increasing need to control rising pharmaceutical costs is a major growth driver in the Pharmacy Benefit Management (PBM) market. Employers, insurers, and government bodies are increasingly turning to PBMs to streamline drug pricing and negotiate lower rates with pharmaceutical manufacturers. PBMs play a critical role in reducing the financial burden on both payers and patients by offering effective formulary management and promoting the use of generics. This cost-control advantage significantly drives market adoption across various healthcare sectors, especially as drug prices continue to escalate globally.
- For instance, Express Scripts' Smart90 program saved employers and members over USD 2.5 billion by shifting chronic medication fills to 90-day supplies at lower unit costs.
Growth of Specialty Pharmaceuticals
The rapid expansion of specialty pharmaceuticals is significantly propelling the PBM market. Specialty drugs, often used to treat chronic and complex conditions like cancer, rheumatoid arthritis, and multiple sclerosis, require specialized handling and patient management programs. PBMs provide essential services such as prior authorizations, patient education, and medication adherence programs that support the proper use of these high-cost therapies. As the demand for specialty medications grows, PBMs are becoming increasingly indispensable in ensuring efficient distribution, cost management, and enhanced patient care, driving substantial market growth.
- For instance, Cigna’s Accredo Specialty Pharmacy supports more than 550 specialty medications and provides disease-specific centers of excellence, improving clinical oversight for approximately 400,000 patients annually.
Integration of Advanced Digital Technologies
The integration of digital health solutions, including data analytics, artificial intelligence, and electronic health records, is driving efficiency in the PBM market. These technologies enable PBMs to optimize formulary management, improve patient outcomes, and offer predictive insights into drug utilization trends. Digital tools also enhance transparency in pricing and streamline the claims adjudication process, which boosts payer confidence. The increasing adoption of telehealth and e-prescription platforms further supports PBMs in delivering timely and personalized pharmacy benefits, strengthening their role in modern healthcare ecosystems.
Key Trends & Opportunities
Rising Focus on Value-Based Care
The shift towards value-based care models presents a significant opportunity for PBMs to expand their service offerings. Payers and healthcare providers are increasingly emphasizing patient outcomes and cost-efficiency over traditional fee-for-service models. PBMs are well-positioned to support this transition by managing medication therapies that improve patient adherence and reduce hospital readmissions. By aligning their strategies with value-based goals, PBMs can foster stronger partnerships with insurers and employers while expanding their influence in outcome-driven healthcare systems.
- For instance, Prime Therapeutics’ MedDrive program delivered USD 1.4 billion in annual savings to participating health plans by supporting value-based formulary decisions and patient outcome improvements.
Expansion of Specialty Pharmacy Networks
The growing complexity and high cost of specialty drugs are driving the expansion of specialty pharmacy networks within the PBM market. PBMs are increasingly investing in dedicated specialty pharmacy divisions to ensure better control over drug distribution, patient monitoring, and adherence support. This trend presents a strategic opportunity for PBMs to strengthen their market position by offering comprehensive specialty drug management services. It also enables PBMs to negotiate favorable pricing terms and improve patient access to critical therapies, further supporting market growth.
- For instance, Humana Specialty Pharmacy expanded its reach to manage over 200,000 specialty patients, offering customized services that achieved a 93% medication adherence rate among those treated for complex conditions.
Key Challenges
Increasing Regulatory Scrutiny
The Pharmacy Benefit Management market faces mounting regulatory scrutiny over drug pricing transparency and rebate practices. Regulatory bodies are raising concerns about the lack of visibility in PBM pricing structures and their impact on prescription drug costs for consumers. Proposed legislative changes may require PBMs to disclose rebate arrangements and pricing methodologies, which could potentially limit their negotiating power with manufacturers. Navigating these evolving regulatory requirements remains a critical challenge for PBMs, requiring strategic adjustments to maintain compliance and market competitiveness.
Rising Competition from Direct-to-Consumer Models
The emergence of direct-to-consumer (DTC) pharmacy platforms poses a significant challenge to traditional PBM models. Several online pharmacies and large retailers are bypassing PBMs by offering transparent, lower-cost drug pricing directly to patients. This shift can erode the PBM’s intermediary role and diminish their influence over pricing and distribution. To remain competitive, PBMs must innovate by enhancing digital engagement, improving pricing transparency, and offering more personalized patient support services that add clear value over emerging DTC alternatives.
Complex Drug Supply Chain Management
Managing the increasingly complex pharmaceutical supply chain is a persistent challenge for PBMs. The rise in specialty drugs, global sourcing of raw materials, and stringent storage and handling requirements complicate the logistics of drug distribution. Supply chain disruptions, including manufacturing delays and transportation bottlenecks, can lead to drug shortages and impact timely patient access. PBMs must continuously strengthen their supply chain resilience and enhance coordination with manufacturers, pharmacies, and healthcare providers to mitigate these risks and ensure seamless drug availability.
Regional Analysis
North America
North America holds the largest share in the Pharmacy Benefit Management (PBM) market, accounting for approximately 37.7% of the global market in 2024. The market size increased from USD 195,993.00 million in 2018 to USD 225,641.54 million in 2024 and is projected to reach USD 339,954.01 million by 2032, growing at a CAGR of 5.3%. The region’s growth is driven by the strong presence of major PBM providers, well-established healthcare infrastructure, and high adoption of advanced pharmacy management solutions. Additionally, growing demand for cost-effective drug therapies and specialty pharmacy services supports continued market expansion.
Europe
Europe represents a significant portion of the Pharmacy Benefit Management market, contributing approximately 20.3% to the global market in 2024. The market grew from USD 110,440.50 million in 2018 to USD 122,469.67 million in 2024 and is expected to reach USD 171,983.15 million by 2032, registering a CAGR of 4.4%. Growth in this region is supported by rising healthcare expenditure, increasing focus on medication affordability, and the growing penetration of PBM models across European countries. Additionally, regulatory frameworks promoting drug price transparency and the rising adoption of disease management programs further fuel the market’s progress.
Asia Pacific
Asia Pacific is the fastest-growing region in the Pharmacy Benefit Management market, holding approximately 30.0% of the global market in 2024. The market expanded from USD 149,846.50 million in 2018 to USD 181,099.45 million in 2024, with projections reaching USD 297,310.99 million by 2032, at a robust CAGR of 6.4%. The rapid growth is driven by increasing healthcare access, rising demand for specialty pharmaceuticals, and expanding health insurance coverage across countries like China, India, and Japan. Additionally, the growing focus on reducing out-of-pocket drug expenses contributes to the region’s accelerating adoption of PBM services.
Latin America
Latin America accounts for approximately 4.3% of the global Pharmacy Benefit Management market in 2024. The market grew from USD 22,399.20 million in 2018 to USD 25,723.30 million in 2024 and is projected to reach USD 34,687.71 million by 2032, growing at a CAGR of 3.9%. Growth in this region is primarily driven by the expanding middle-class population, rising healthcare spending, and the increasing prevalence of chronic diseases that require long-term drug management. However, slower adoption of advanced PBM models and limited healthcare infrastructure in some countries present ongoing challenges to faster market penetration.
Middle East
The Middle East contributes approximately 3.8% to the global Pharmacy Benefit Management market in 2024. The market size increased from USD 20,791.85 million in 2018 to USD 22,765.94 million in 2024, with an anticipated rise to USD 31,166.55 million by 2032, growing at a CAGR of 4.1%. The market is supported by improving healthcare systems, growing investments in health insurance programs, and a rising focus on cost-containment strategies within pharmaceutical spending. The gradual adoption of PBM services, especially in Gulf countries, and increasing demand for specialty pharmacy services are key contributors to the region’s growth.
Africa
Africa holds a smaller but steadily growing share of approximately 4.4% in the global Pharmacy Benefit Management market in 2024. The market expanded from USD 19,028.95 million in 2018 to USD 26,275.37 million in 2024, with expectations to reach USD 36,053.77 million by 2032, at a CAGR of 3.8%. The growth is driven by the improving accessibility of healthcare services, rising healthcare awareness, and the increasing burden of chronic diseases that necessitate structured drug benefit management. Despite infrastructure limitations, the growing role of public-private partnerships in enhancing pharmaceutical access supports the region’s positive market trajectory.
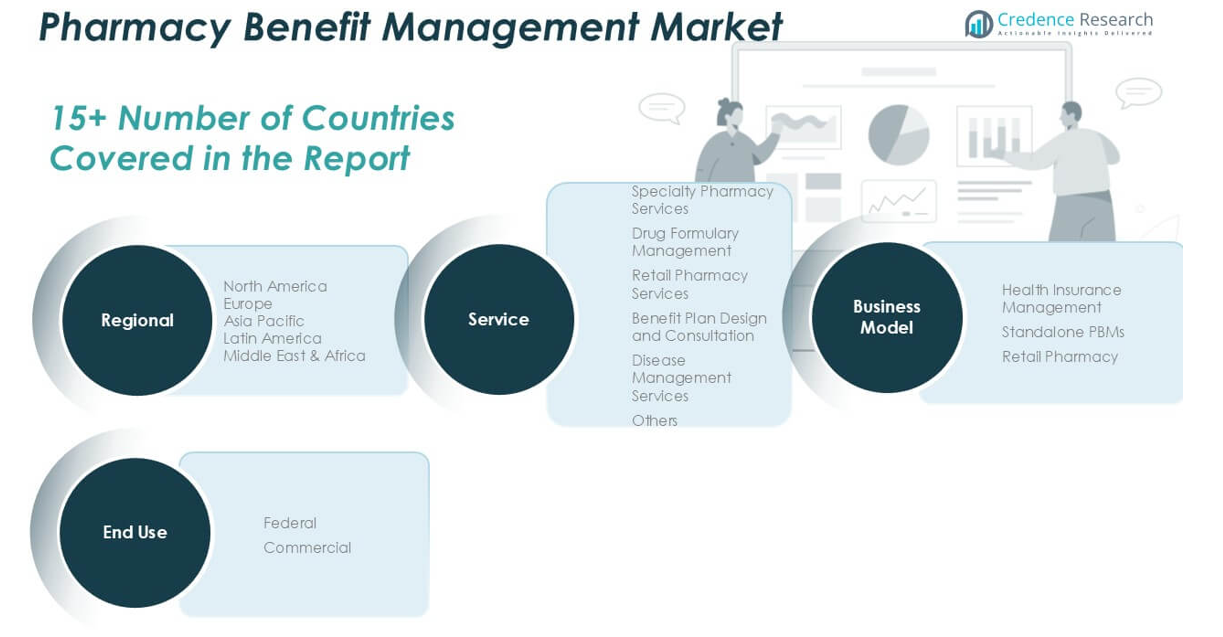
Market Segmentations:
By Services:
- Specialty Pharmacy Services
- Drug Formulary Management
- Retail Pharmacy Services
- Benefit Plan Design and Consultation
- Disease Management Services
- Others
By Business Model:
- Health Insurance Management
- Standalone PBMs
- Retail Pharmacy
By End Use:
- Federal
- Commercial
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Pharmacy Benefit Management (PBM) market is highly competitive, with key players focusing on strategic mergers, acquisitions, and partnerships to strengthen their market positions and expand service offerings. Leading companies such as CVS Health Corporation, Express Scripts Holding Company, and OptumRx, Inc. dominate the landscape, leveraging their extensive healthcare networks, integrated service models, and advanced technology platforms to deliver cost-effective and patient-centric solutions. These players prioritize enhancing specialty pharmacy services, improving formulary management, and increasing pricing transparency to maintain a competitive edge. Additionally, companies like Prime Therapeutics LLC and Magellan Health, Inc. are actively focusing on collaborative models with health insurers to provide tailored PBM services. The market also sees growing competition from emerging standalone PBMs and technology-driven firms offering innovative digital pharmacy solutions. Regulatory scrutiny around drug pricing and rebate practices further intensifies competition, pushing companies to adopt transparent, value-based strategies to ensure long-term market sustainability and customer trust.
Key Player Analysis
- Aetna, Inc.
- Centene Corporation
- Cigna Corporation
- CVS Health Corporation
- Express Scripts Holding Company
- Magellan Health, Inc.
- Medimpact Healthcare Systems, Inc.
- OptumRx, Inc.
- Prime Therapeutics LLC
- ProCare Rx
- SS&C Technologies, Inc.
Recent Developments
- In 2025, Cigna’s medical loss ratio (MLR) is expected to decrease due to the sale of its Medicare business. While the search results do not specify a major new PBM initiative for 2025, Cigna remains a top PBM market player through its Express Scripts division.
- In 2025, CVS Health, through its Aetna subsidiary, is integrating its prescription drug plans following the merger. Simultaneously, CVS is experiencing lower medical loss ratios (MLRs) due to positive performance in Medicare Advantage, ACA, and Medicaid products. CVS continues its dominance as a pharmacy benefit manager (PBM), managing benefits for various major insurers and health plans.
- In January 2024, Express Scripts significantly expanded its pharmacy benefits management (PBM) business by taking over the management of pharmacy benefits for Centene's approximately 20 million members. This transition, effective from the beginning of the year, is expected to reshape market share and industry dynamics within the PBM sector in 2024 and beyond.
- In January 2024, Centene, a major healthcare company, shifted its pharmacy benefit management (PBM) services from CVS Health to Express Scripts. This five-year agreement involves approximately 20 million Centene beneficiaries and is expected to transfer around $35 billion in pharmacy spending and over 400 million prescriptions to Express Scripts.
- In January 2022, Centene finalized its acquisition of Magellan Health, incorporating Magellan's behavioral health and specialty PBM services. This strategic move aimed to bolster Centene's capabilities in managing specialty and behavioral health pharmacy, enhancing their ability to offer comprehensive healthcare solutions.
Market Concentration & Characteristics
The Pharmacy Benefit Management Market demonstrates a high level of market concentration, with a few dominant players controlling a significant share. It is characterized by the strong presence of integrated healthcare service providers that combine retail pharmacy, insurance, and benefit management under one umbrella. These companies leverage their scale, established networks, and advanced data systems to negotiate favorable drug prices and manage complex pharmaceutical benefits efficiently. The market focuses heavily on cost containment, formulary management, and patient adherence programs. It also exhibits a growing reliance on specialty pharmacy services and digital health technologies to improve patient outcomes and operational efficiency. Regulatory scrutiny and rising demand for pricing transparency continue to shape its competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Services, Business Model, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Pharmacy Benefit Management market will see increased demand for specialty pharmacy services to support complex disease treatments.
- Digital transformation will continue to enhance PBM efficiency through data analytics, automation, and real-time benefit management.
- Value-based contracts between PBMs, insurers, and pharmaceutical companies will become more common to control drug costs and improve patient outcomes.
- Regulatory frameworks will tighten, requiring greater pricing transparency and accountability from PBM providers.
- Integration with telehealth and e-prescription platforms will strengthen PBM service delivery and patient accessibility.
- The role of PBMs in managing chronic diseases will expand through personalized medication support and adherence programs.
- Competition from direct-to-consumer pharmacy platforms will push PBMs to innovate and offer more patient-centric solutions.
- Mergers and acquisitions will remain a key strategy for market leaders aiming to consolidate services and expand geographic reach.
- The focus on improving formulary management will grow to ensure cost-effective access to essential medications.
- Partnerships between PBMs and health insurers will deepen to create integrated care models and optimize drug spending.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pharmacy Benefit Management Market?
What are the key segments within the Pharmacy Benefit Management Market?
What are some challenges faced by the Pharmacy Benefit Management Market?
Who are the major players in the Pharmacy Benefit Management Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pharmacy Benefit Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pharmacy Benefit Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 603,975.27 million → forecast year: USD 911,156.18 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pharmacy Benefit Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pharmacy Benefit Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pharmacy Benefit Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pharmacy Benefit Management Market Drivers
- 3.3 Pharmacy Benefit Management Market Restraints & Challenges
- 3.4 Pharmacy Benefit Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pharmacy Benefit Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pharmacy Benefit Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pharmacy Benefit Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pharmacy Benefit Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pharmacy Benefit Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pharmacy Benefit Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pharmacy Benefit Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pharmacy Benefit Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pharmacy Benefit Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pharmacy Benefit Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pharmacy Benefit Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pharmacy Benefit Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pharmacy Benefit Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pharmacy Benefit Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pharmacy Benefit Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pharmacy Benefit Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pharmacy Benefit Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pharmacy Benefit Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pharmacy Benefit Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
