
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Psoriatic Arthritis Treatment Market Size 2024 | USD 10,189.5 million |
| Psoriatic Arthritis Treatment Market, CAGR | 9.20% |
| Psoriatic Arthritis Treatment Market Size 2032 | USD 20,603.16 million |
Market Overview
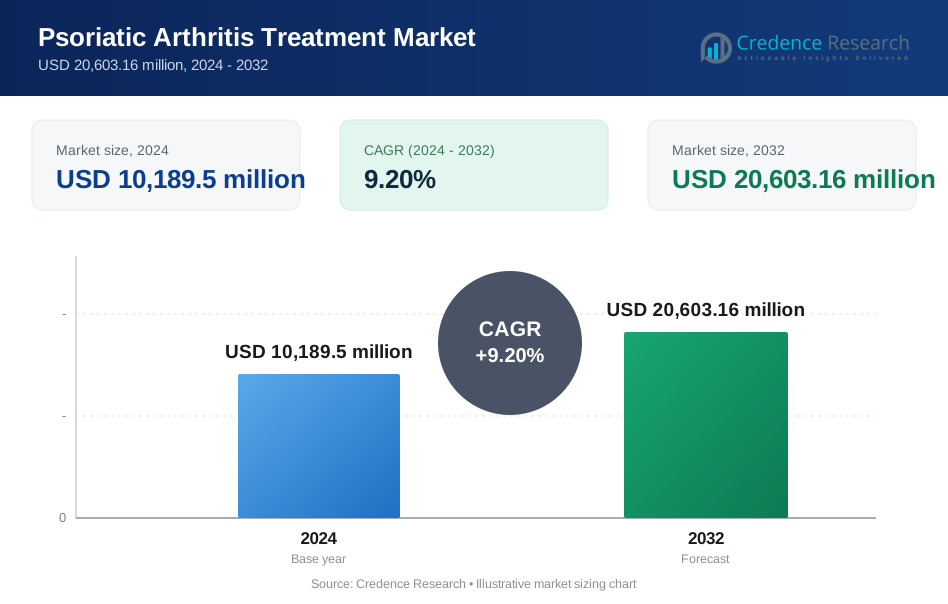
The psoriatic arthritis treatment market is projected to grow from USD 10,189.5 million in 2024 to USD 20,603.16 million by 2032, achieving a compound annual growth rate (CAGR) of 9.20%.
The psoriatic arthritis treatment market is driven by the rising prevalence of autoimmune diseases, increasing awareness of psoriatic arthritis among healthcare professionals and patients, and advancements in biologics and targeted therapies. Additionally, the growing demand for personalized medicine and innovative treatment options enhances market growth. Trends include the shift towards combination therapies, which offer improved patient outcomes, and the development of oral and injectable treatments that enhance patient compliance. Furthermore, ongoing research into new therapeutic agents and the expansion of telemedicine are shaping the landscape, making treatments more accessible and convenient for patients.
The psoriatic arthritis treatment market exhibits strong growth across key regions, with North America and Europe leading due to advanced healthcare infrastructure and high adoption of biologic therapies. North America holds the largest market share, followed by Europe, where increasing awareness and access to innovative treatments drive demand. Key players shaping this market include Amgen Inc., Novartis AG, AstraZeneca PLC, UCB S.A., Celgene Corporation, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Bristol-Myers Squibb Company, and Eli Lilly & Co. These companies focus on developing biologics, biosimilars, and novel therapies to enhance treatment outcomes and expand global market reach.
Market Drivers
Increasing Prevalence of Psoriasis and Psoriatic Arthritis
The rising prevalence of psoriasis and psoriatic arthritis significantly drives the treatment market. For instance, a comprehensive population-based study in Israel reported that the prevalence of psoriatic arthritis has tripled since 2006. Growing awareness among healthcare professionals and the general public has led to earlier diagnoses and prompt interventions. Additionally, the aging population, which is more susceptible to autoimmune diseases like psoriatic arthritis, further fuels the demand for effective treatments. As the population ages, the need for innovative therapies to manage these conditions becomes increasingly critical.
Advancements in Treatment Options
Recent advancements in treatment options have revolutionized how psoriatic arthritis is managed. For instance, the introduction of biologic therapies, such as IL-17 and IL-23 inhibitors, offers targeted and effective solutions, significantly improving patient outcomes. Moreover, the approval of new drugs contributes to market growth by providing patients with a broader array of choices. This diversification in treatment options empowers healthcare providers to tailor therapies to individual patient needs, enhancing overall satisfaction and compliance.
Improved Patient Outcomes
Effective treatments lead to improved patient outcomes by significantly reducing disease activity and enhancing the quality of life. Early intervention is crucial, as it can prevent joint damage and disability, allowing patients to maintain mobility and independence. As a result, the positive impact of these treatments extends beyond physical health, fostering a better overall quality of life for those affected by psoriatic arthritis.
Increased Healthcare Spending
Rising disposable incomes and increased healthcare spending are key factors driving the psoriatic arthritis treatment market. As individuals gain financial stability, they are more likely to seek advanced medical care and innovative treatment options. Furthermore, government initiatives in many countries are boosting healthcare investments, fostering a favorable environment for the development and accessibility of effective psoriatic arthritis treatments.
Market Trends
Shift Towards Biologics and Emerging Therapies
The psoriatic arthritis treatment landscape is witnessing a significant shift towards biologics, which are increasingly becoming the preferred option due to their effectiveness in managing disease activity and preventing joint damage. For instance, biologics such as Secukinumab and Adalimumab have shown high efficacy in clinical trials, with significant improvements in patient outcomes. Recent approvals have allowed these therapies to be utilized earlier in the disease course, potentially leading to improved patient outcomes. Alongside this trend, emerging therapies are making headway, particularly targeted therapies designed to address specific mechanisms involved in psoriatic arthritis. The exploration of gene therapies also holds promise for the future, as researchers investigate novel approaches that could transform treatment paradigms. This convergence of biologics and innovative therapeutic options underscores a dynamic shift towards more effective and tailored interventions in managing this complex condition.
Emphasis on Personalized Medicine and Patient-Centered Care
There is a growing emphasis on personalized medicine in psoriatic arthritis treatment, driven by advances in genetic testing and biomarker analysis. These innovations enable healthcare providers to tailor treatment approaches to individual patient profiles, significantly enhancing the efficacy of therapies. Furthermore, combination therapies are gaining traction, as healthcare professionals recognize that integrating various treatment modalities can yield better results for certain patients. Alongside these advancements, a focus on patient-centered care is reshaping the treatment landscape. Healthcare providers are prioritizing improved patient experiences through education, support, and streamlined access to care. Digital health technologies facilitate remote monitoring of disease activity, allowing for more effective patient adherence to treatment plans. Together, these trends reflect a holistic approach to psoriatic arthritis management, prioritizing both the effectiveness of treatments and the overall patient experience, ultimately leading to better health outcomes.
Market Challenges Analysis
High Treatment Costs and Limited Access to Care
One of the primary challenges facing the psoriatic arthritis treatment market is the high cost associated with biologic therapies. These advanced treatments, while effective, can be prohibitively expensive, limiting access for many patients. For instance, biologic medications can cost between $10,000 to $50,000 annually. Additionally, reimbursement policies vary significantly across different regions, impacting patient affordability and contributing to disparities in access to care. For instance, in some regions, patients may have out-of-pocket costs exceeding $2,500 per year despite having insurance coverage. In many areas, particularly rural or underserved regions, access to specialized healthcare providers is limited, further exacerbating the challenge. Socioeconomic factors also play a crucial role, as individuals from lower-income backgrounds may face additional barriers to obtaining necessary treatments, leading to significant healthcare disparities. This complex interplay of high costs and limited access creates a substantial obstacle for patients seeking effective management of their condition.
Disease Heterogeneity and Patient Adherence Challenges
Psoriatic arthritis is characterized by its heterogeneity, with individual patients experiencing varying disease severity and responses to treatment. This variability makes it challenging for healthcare providers to identify the optimal therapeutic approach for each patient, often requiring multiple trials of different treatments to achieve satisfactory results. Moreover, adherence to treatment regimens can be particularly difficult due to their complexity. Patients may struggle to maintain compliance with prescribed therapies, especially when faced with potential side effects associated with biologics and other treatments. Close monitoring is essential to manage these side effects, adding another layer of complexity to treatment. To enhance adherence, improved patient education and support systems are vital, empowering patients to better understand their condition and the importance of consistent treatment. This multifaceted approach is crucial to overcoming the challenges posed by disease heterogeneity and ensuring that patients can effectively manage their psoriatic arthritis.
Market Segmentation Analysis:
By Drug Class:
The psoriatic arthritis treatment market is segmented by drug class, with key categories including Non-steroidal Anti-inflammatory Drugs (NSAIDs), Non-biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs), Biologic DMARDs, and others. NSAIDs are commonly prescribed for managing inflammation and pain, providing symptomatic relief but not addressing the underlying disease progression. Non-biologic DMARDs, such as methotrexate, are traditional therapies aimed at slowing disease progression and reducing joint damage, offering a cost-effective option for patients. However, biologic DMARDs have revolutionized treatment by targeting specific immune pathways involved in psoriatic arthritis, making them highly effective for managing severe cases. Biologics are becoming the preferred option for many patients due to their targeted approach and superior outcomes, though they remain expensive. The “others” category includes newer therapies that do not fall into these conventional classes but offer promising alternatives. The diversity within the drug class segment reflects the complexity of psoriatic arthritis and the need for individualized treatment approaches based on disease severity and patient response.
By Route of Administration:
The market is further segmented by the route of administration into oral, parenteral, and topical treatments. Oral medications, such as NSAIDs and some DMARDs, remain the most convenient option for patients due to their ease of use and widespread availability. However, biologics and other advanced therapies are often administered parenterally, either through intravenous infusion or subcutaneous injection, to ensure targeted delivery and optimal efficacy. While parenteral treatments are more effective for severe cases, they require healthcare provider involvement and can be less convenient for patients. Topical treatments, though less common in managing psoriatic arthritis, are used in cases where skin symptoms dominate, providing localized relief without systemic side effects. The choice of administration route depends on the severity of the disease, patient preferences, and the specific treatment prescribed, with a growing trend toward more convenient options like self-administered injectables and oral therapies. This diversity of administration methods ensures that treatments can be tailored to individual patient needs for improved outcomes.
Segments:
Based on Drug Class
- Non-steroidal Anti-inflammatory Drugs (NSAIDs)
- Non-biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- Biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- Others
Based on Route of Administration
- Oral
- Parenteral
- Topical
Based on Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America commands the largest market share in the psoriatic arthritis treatment market, accounting for over 40% of global revenue. This dominance is attributed to the region's advanced healthcare infrastructure, high patient awareness, and widespread use of biologic therapies. The United States plays a key role, with strong healthcare reimbursement policies that support access to expensive biologics and novel treatments. The increasing prevalence of autoimmune diseases, coupled with rising healthcare expenditure, further drives demand. Additionally, North America benefits from robust pharmaceutical research and development, with numerous ongoing clinical trials contributing to the introduction of new, innovative treatments.
Europe
Europe holds the second-largest market share, contributing nearly 30% of global psoriatic arthritis treatment revenue. Countries like Germany, France, and the United Kingdom are leading the market in the region, thanks to government-supported healthcare systems that enhance patient access to advanced treatments. The availability of biologics, biosimilars, and non-biologic DMARDs has improved disease management. However, variations in healthcare systems and reimbursement policies across countries pose challenges. Despite these differences, the growing awareness of psoriatic arthritis and the expansion of biosimilars are driving competition and improving treatment accessibility, thereby supporting the region's steady market growth.
Key Player Analysis
- Amgen Inc.
- Novartis AG
- AstraZeneca PLC
- UCB S.A.
- Celgene Corporation
- Johnson & Johnson
- Pfizer Inc.
- AbbVie Inc.
- Bristol-Myers Squibb Company
- Eli Lilly & Co
Competitive Analysis
The competitive landscape of the psoriatic arthritis treatment market is dominated by leading pharmaceutical companies such as Amgen Inc., Novartis AG, AstraZeneca PLC, UCB S.A., Celgene Corporation, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Bristol-Myers Squibb Company, and Eli Lilly & Co. These key players focus on developing innovative biologic and non-biologic DMARDs, which significantly improve patient outcomes. The market is driven by advancements in biologic and non-biologic DMARDs, which have transformed the management of the disease. Biologics, in particular, dominate the market due to their targeted approach and effectiveness in reducing disease activity and preventing joint damage. Additionally, the rise of biosimilars is increasing competition and offering more cost-effective options for patients. Ongoing research and development efforts focus on new therapeutic approaches, including personalized and combination therapies, to address the diverse needs of patients.
Recent Developments
- In February 2024, Biocon Biologics announced that it had reached an agreement with Janssen Biotech Inc. and Johnson & Johnson to commercialize the drug Bmab 1200.
- In September 2023, Wellmin Health, in collaboration with the non-profit organization Versus Arthritis, launched the Pathway platform. It is a program developed to help patients with arthritis, including psoriatic arthritis.
- In September 2022, the U.S. Food and Drug Administration approved Bristol Myers Squibb’s Sotyktu (deucravacitinib) oral treatment for adults with moderate-to-severe plaque psoriasis. It is the first-in-class, oral, selective, allosteric tyrosine kinase 2 (TYK2) inhibitor.
Market Concentration & Characteristics
The psoriatic arthritis treatment market is characterized by moderate to high market concentration, with a few leading pharmaceutical companies holding a significant share of the market. These dominant players are responsible for the development and commercialization of biologic therapies, which have become the standard treatment for severe cases. The market is also defined by its focus on innovative drug development, particularly in biologics and targeted therapies, aimed at improving patient outcomes. However, the increasing presence of biosimilars is creating more competition, offering cost-effective alternatives to branded biologics. Market characteristics include a strong emphasis on research and development, regulatory approvals, and strategic partnerships to expand product pipelines. Additionally, the market sees continuous efforts to address unmet patient needs through personalized medicine and combination therapies. The growing global demand for effective treatments further fuels competition, while pricing pressures and regional variations in healthcare systems present ongoing challenges for market players.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Advancements in biologics and targeted therapies will continue to drive the growth of psoriatic arthritis treatment options.
- Increased adoption of biosimilars will lead to greater market competition and more affordable treatment options.
- Personalized medicine approaches will gain prominence, tailoring treatments to individual patient profiles for better outcomes.
- New drug approvals and expanded indications for existing therapies will offer more choices for patients and physicians.
- Ongoing research in gene therapies and novel mechanisms will pave the way for innovative treatments.
- Digital health technologies and remote monitoring will improve patient adherence and disease management.
- Expansion into emerging markets will present growth opportunities for pharmaceutical companies.
- Greater focus on early diagnosis and intervention will improve long-term patient outcomes and prevent joint damage.
- Rising healthcare spending and government initiatives will enhance access to advanced treatments.
- Increasing patient awareness and advocacy efforts will drive demand for improved care and treatment access globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Psoriasis and Psoriatic Arthritis
The rising incidence of psoriatic arthritis, driven by greater awareness and earlier diagnosis, is expanding the patient pool and fueling demand for effective treatments.
Advancements in Biologics and Targeted Therapies
Innovations in biologic DMARDs and targeted therapies, such as IL-17 and IL-23 inhibitors, are improving patient outcomes and expanding treatment options, encouraging adoption among healthcare providers.
Improved Patient Outcomes and Early Intervention
Effective therapies are enabling earlier intervention, reducing disease progression and joint damage, which increases both physician and patient preference for advanced treatments.
Rising Healthcare Spending and Access
Growing healthcare expenditure and supportive government initiatives are improving access to advanced therapies, particularly in developed regions, thereby driving market growth.
Expansion of Personalized Medicine and Combination Therapies
The trend toward personalized medicine and combination therapies is allowing for more tailored and effective treatment regimens, enhancing patient satisfaction and compliance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Psoriatic Arthritis Treatment market?
What factors are driving the growth of the Psoriatic Arthritis Treatment market?
What are the key segments within the Psoriatic Arthritis Treatment market?
What are some challenges faced by the Psoriatic Arthritis Treatment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Non-steroidal Anti-inflammatory Drugs (NSAIDs)
- 1.2.2 Non-biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- 1.2.3 Biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- 1.2.4 Others
- 1.3 By Route of Administration
- 1.3.1 Oral
- 1.3.2 Parenteral
- 1.3.3 Topical
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,189.5 million → 2032: USD 20,603.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Psoriatic Arthritis Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Psoriatic Arthritis Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Psoriatic Arthritis Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Psoriatic Arthritis Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Psoriatic Arthritis Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Psoriatic Arthritis Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Psoriatic Arthritis Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Psoriatic Arthritis Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,189.5 million → 2032: USD 20,603.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Psoriatic Arthritis Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Non-steroidal Anti-inflammatory Drugs (NSAIDs)
- 12.3.7.2 Non-biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- 12.3.7.3 Biologic Disease Modifying Anti-Rheumatic Drugs (DMARDs)
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oral
- 12.4.7.2 Parenteral
- 12.4.7.3 Topical
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Psoriatic Arthritis Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Psoriatic Arthritis Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Psoriatic Arthritis Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amgen Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Novartis AG
- 17.4 AstraZeneca PLC
- 17.5 UCB S.A.
- 17.6 Celgene Corporation
- 17.7 Johnson & Johnson
- 17.8 Pfizer Inc.
- 17.9 AbbVie Inc.
- 17.10 Bristol-Myers Squibb Company
- 17.11 Eli Lilly & Co
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

