
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
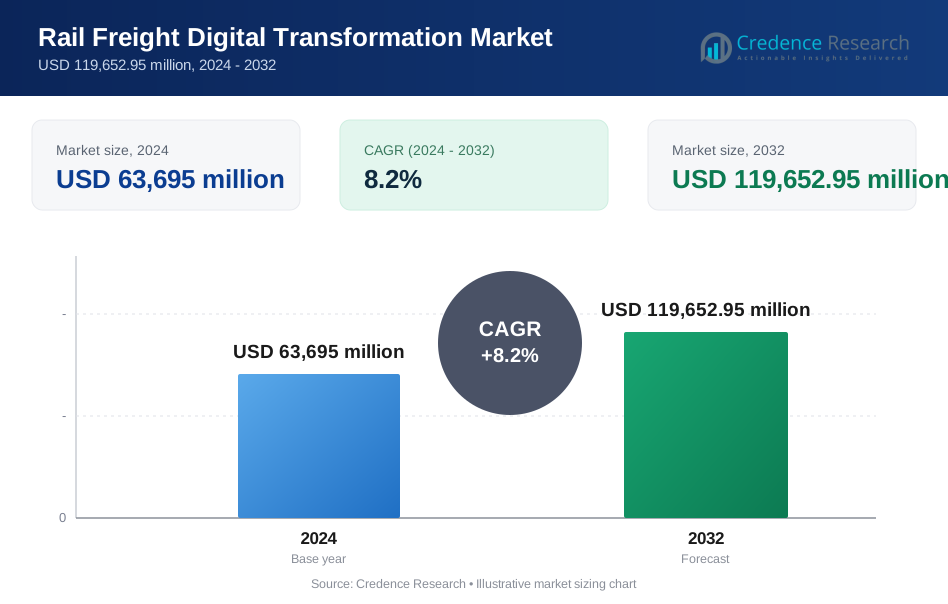
| Rail Freight Digital Transformation market Size 2024 | USD 63,695 million |
| Rail Freight Digital Transformation market, CAGR | 8.2% |
| Rail Freight Digital Transformation market Size 2032 | USD 119,652.95 million |
Market Overview
The Rail Freight Digital Transformation market is expected to grow from USD 63,695 million in 2024 to USD 119,652.95 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.2% during the forecast period (2024-2032).
The Rail Freight Digital Transformation market is driven by the increasing demand for efficiency, sustainability, and cost reduction in logistics. Advancements in technologies such as IoT, AI, and big data analytics enable real-time tracking, predictive maintenance, and optimized route planning, which enhance operational efficiency and reduce downtime. The push for green and sustainable transport solutions also accelerates the adoption of digital systems, as rail freight is considered eco-friendlier than road transport. Additionally, government initiatives to modernize infrastructure and the growing need for seamless, integrated supply chain solutions contribute to market growth. Key trends include the rise of automation and digital twin technologies, which improve predictive insights and decision-making. The implementation of cloud-based platforms and blockchain for better data security and transparency further propels the market forward, creating a more interconnected and efficient rail freight ecosystem. These factors collectively support the growing demand for digital transformation in the rail freight sector.
The Rail Freight Digital Transformation market is experiencing significant growth across key regions, with North America and Europe leading the way. North America, particularly the United States, holds a substantial market share due to advanced infrastructure and ongoing investments in digital technologies such as IoT and AI. Europe follows closely, driven by sustainability initiatives and modernization efforts across rail networks, with countries like Germany, France, and the UK at the forefront. Key players in the market include major rail operators such as BNSF Railway, Canadian National Railway, CSX Corporation, Deutsche Bahn AG, and Union Pacific Railroad, alongside logistics giants like DHL Group and SNCF Logistics. These companies are investing in automation, predictive maintenance, and real-time tracking solutions to enhance operational efficiency and meet rising demand for seamless, integrated supply chains.
Market Drivers:
Technological Advancements:
One of the primary drivers of the Rail Freight Digital Transformation market is the rapid advancement of technology. Innovations such as the Internet of Things (IoT), artificial intelligence (AI), machine learning, and big data analytics enable real-time tracking, monitoring, and optimization of rail operations. These technologies help improve predictive maintenance, allowing operators to detect and address potential issues before they result in costly breakdowns or delays. For instance, a report highlighted that the integration of IoT and AI in rail freight operations has significantly improved predictive maintenance and operational efficiency. The integration of digital tools into freight systems is also enhancing route planning and load optimization, contributing to improved operational efficiency and cost reductions.
Sustainability and Green Initiatives:
Sustainability concerns are driving the shift towards digital transformation in rail freight. With increasing pressure to reduce carbon emissions and environmental impact, rail transport is being recognized as a greener alternative to road and air freight. Digital transformation supports sustainability goals by optimizing fuel consumption, improving asset utilization, and reducing waste. Technologies like electric locomotives, automation, and smart sensors further contribute to lower energy consumption and enhanced environmental performance, aligning with global sustainability initiatives and regulatory requirements. For instance, a survey by the United Nations Environment Programme (UNEP) indicated that the adoption of digital technologies in rail freight has significantly reduced carbon emissions and improved environmental performance.
Government Investments and Infrastructure Modernization:
Government initiatives aimed at modernizing transportation infrastructure are significantly impacting the growth of the Rail Freight Digital Transformation market. Many countries are investing in smart railway systems, including digital signaling, automated freight terminals, and advanced logistics hubs. These investments not only enhance safety and efficiency but also foster the adoption of cutting-edge digital technologies. For instance, a report by the European Commission highlighted that investments in smart railway systems have significantly improved safety and efficiency in rail freight operations. Public-private partnerships are becoming more common, further accelerating the transformation of the rail freight sector and encouraging greater digital adoption across the industry.
Rising Demand for Supply Chain Efficiency:
The growing demand for efficient, seamless, and integrated supply chains is another key driver of the digital transformation in rail freight. As businesses seek faster, more reliable delivery options, digital tools are helping to streamline operations. By enabling real-time visibility of shipments, automated scheduling, and better coordination between different transportation modes, digital technologies are improving overall supply chain performance. For instance, a study by the International Transport Forum found that digital solutions in rail freight have significantly improved supply chain efficiency and reliability. This heightened need for operational efficiency and agility has led to the widespread adoption of digital solutions in rail freight, further accelerating market growth.
Market Trends:
Automation and Smart Freight Systems:
A prominent trend in the Rail Freight Digital Transformation market is the increasing use of automation. Automation technologies, such as automated trains, self-operating cargo systems, and robotic freight handling, are revolutionizing the rail freight industry. For instance, a report by DHL Freight highlighted that AI-based route planning and automated cargo handling have significantly improved operational efficiency and reduced human error in logistics. These innovations not only improve efficiency but also enhance safety by reducing human error. Automated systems streamline operations, accelerate cargo handling, and ensure more reliable and punctual delivery, driving overall performance across the supply chain.
Data Analytics and Predictive Maintenance:
Another key trend is the growing integration of data analytics and predictive maintenance tools. Rail operators are increasingly leveraging big data and AI-powered analytics to monitor train performance, track freight, and predict maintenance needs. For instance, a survey by MDPI highlighted that predictive maintenance using AI and big data analytics has significantly reduced maintenance costs and improved the reliability of rail networks. By analyzing historical and real-time data, operators can anticipate equipment failures, minimize downtime, and optimize asset management. This predictive approach significantly reduces maintenance costs and enhances the reliability of rail networks, aligning with the industry’s shift toward proactive rather than reactive maintenance strategies.
Blockchain for Supply Chain Transparency:
Blockchain technology is gaining traction in the rail freight sector due to its potential to enhance transparency, security, and efficiency. By offering a decentralized ledger for tracking and verifying transactions, blockchain helps create more secure and transparent supply chains. For instance, a study by SpringerLink highlighted that blockchain technology has significantly improved transparency and security in rail freight supply chains. It ensures the integrity of data and simplifies documentation processes, such as bills of lading, contracts, and customs clearances. This increased transparency promotes trust among stakeholders and facilitates smoother cross-border freight operations, which is particularly valuable in global supply chains.
Cloud Computing and Integrated Platforms:
Cloud computing is becoming integral to the digital transformation of rail freight. Cloud-based platforms provide a centralized, scalable solution for managing operations, data, and communication across the supply chain. For instance, a report by Global Railway Review highlighted that cloud-based platforms have significantly improved real-time tracking and operational efficiency in rail freight. These platforms enable real-time tracking of shipments, inventory management, and efficient coordination between freight operators, suppliers, and customers. By enhancing connectivity and streamlining processes, cloud computing is driving more agile, responsive, and efficient rail freight operations, contributing to the market’s continued growth.
Market Challenges Analysis:
High Initial Investment and Integration Costs:
One of the significant challenges facing the Rail Freight Digital Transformation market is the high upfront costs associated with the implementation of advanced technologies. The adoption of digital systems such as IoT, AI, and automation requires substantial capital investment in infrastructure, software, and training. Additionally, integrating new technologies with legacy systems poses a further hurdle, as many rail operators struggle to upgrade or replace outdated infrastructure. The complexity of these integrations can lead to delays, cost overruns, and operational disruptions, deterring some companies from pursuing digital transformation. Smaller operators, in particular, may face financial constraints that limit their ability to invest in such technologies, creating an uneven adoption landscape across the industry. Furthermore, the long return on investment (ROI) period can make it difficult for stakeholders to justify immediate expenditures, especially in markets with tight margins and economic uncertainty. This financial burden remains a significant barrier to the broader adoption of digital transformation in the sector.
Cybersecurity and Data Privacy Concerns:
As rail freight systems become increasingly digital and interconnected, cybersecurity and data privacy emerge as critical concerns. The integration of IoT devices, cloud computing, and real-time data sharing increases the vulnerability of rail systems to cyberattacks, which can disrupt operations, compromise sensitive information, and damage reputations. Securing data across multiple platforms and stakeholders requires robust security measures, which can be both complex and costly to implement. Additionally, compliance with varying data privacy regulations across regions further complicates efforts to safeguard data. Addressing these cybersecurity challenges is essential for ensuring the smooth and secure functioning of digital systems, as breaches or data leaks could severely impact trust and hinder market growth. Rail operators must also balance the need for open data sharing to enhance logistics and customer service with the imperative to protect proprietary business information. Without comprehensive cybersecurity strategies, the rail freight sector could face significant risks that slow digital adoption and undermine the overall benefits of transformation.
Market Segmentation Analysis:
By Cargo Type
The Rail Freight Digital Transformation market is segmented based on the type of cargo transported, with each category requiring specialized digital solutions. Bulk cargo, which includes raw materials such as coal, minerals, and grains, is a major segment driving market growth. This cargo type benefits from digital tools that enable real-time tracking, predictive maintenance, and route optimization to ensure uninterrupted delivery and cost efficiency. The containerized cargo segment, which involves goods like electronics, textiles, and machinery, is increasingly adopting digital solutions to improve tracking, inventory management, and overall supply chain visibility. This is essential for meeting the demand for faster and more transparent logistics. Special cargo, which includes perishable goods, hazardous materials, and temperature-sensitive items, requires precise tracking and temperature controls, making digital transformation a critical factor in managing safety and regulatory compliance. The segmentation by cargo type highlights the diverse needs of the rail freight sector and underscores the growing role of digital tools tailored to each category.
By Service Type
The Rail Freight Digital Transformation market is also segmented by service type, including freight management services, transportation services, and logistics services. Freight management services involve the use of advanced digital platforms to optimize the scheduling, routing, and tracking of freight shipments. These platforms enhance operational efficiency by providing real-time data and predictive insights that improve decision-making. The transportation services segment focuses on the movement of goods via rail, where digital transformation through automation and IoT technologies is helping to monitor and track shipments, improving safety and reducing operational costs. Real-time tracking of freight ensures better customer service and transparency in operations. The logistics services segment includes digital solutions for warehouse management, cargo handling, and inventory control. Cloud-based platforms are transforming how warehouses manage their resources, improving storage efficiency and reducing lead times.
Segments:
Based on Cargo Type:
- Containerized
- Non-containerized
- Liquid Bulk
Based on Service Type:
- Full carload (FCL)
- Less than carload (LCL)
- Intermodal transportation
Based on Distance:
- Short haul
- Medium-haul
- Long-haul
Based on End-User:
- Mining
- Agriculture
- Energy
- Manufacturing
- Construction
- Retail
- Automotive
- Chemical
- Food & beverages
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Rail Freight Digital Transformation market, driven by the advanced rail infrastructure in the region and growing demand for efficient logistics. The United States, in particular, is a key player, with extensive rail networks and ongoing investments in digital technologies such as IoT, AI, and predictive maintenance systems. These technologies are being adopted to optimize freight management and ensure seamless operations across the vast rail network. In 2023, North America accounted for approximately 35% of the global market share, with a notable emphasis on automating freight handling and improving supply chain visibility. Government initiatives, such as funding for infrastructure modernization and sustainability, are further supporting the adoption of digital solutions. The region’s strong focus on innovation, along with increasing demand for intermodal transport, positions North America for continued growth in the digital transformation of rail freight.
Europe
Europe is another key region in the Rail Freight Digital Transformation market, contributing around 30% of the global market share. The European Union’s emphasis on sustainability and reducing carbon emissions has accelerated the adoption of green technologies in rail freight. Countries like Germany, France, and the UK are leading the way in digitalizing rail networks, with significant investments in smart rail systems, digital signaling, and cloud-based logistics platforms. European rail operators are increasingly adopting IoT devices, AI, and blockchain to streamline operations, improve freight tracking, and enhance safety. The European market’s growth is also supported by public-private partnerships and regulatory frameworks encouraging the modernization of rail infrastructure. With a strong push toward digital solutions that integrate various transportation modes, Europe is poised to maintain a dominant position in the global Rail Freight Digital Transformation market.
Key Player Analysis:
- SNCF Logistics
- CSX Corporation
- Deutsche Bahn AG
- Union Pacific Railroad
- Canadian National Railway
- BNSF Railway
- Norfolk Southern Railway
- DHL Group
- Canadian Pacific Railway
- China Railway Corporation
Competitive Analysis:
The Rail Freight Digital Transformation market is highly competitive, with leading players continuously innovating to maintain their market positions. BNSF Railway, Canadian National Railway, CSX Corporation, Deutsche Bahn AG, Union Pacific Railroad, DHL Group, Canadian Pacific Railway, Norfolk Southern Railway, SNCF Logistics, and China Railway Corporation are at the forefront of this transformation, investing heavily in automation, IoT, AI, and data analytics to optimize operations. These companies are focused on improving freight tracking, predictive maintenance, and supply chain visibility to meet growing demands for efficiency and sustainability. Key strategies include partnerships with technology providers, development of smart rail systems, and the adoption of cloud-based platforms. The market is also characterized by a push toward sustainability, with companies adopting green technologies and meeting regulatory standards. As digital solutions continue to evolve, competition is expected to intensify, driving further innovation and adoption across the industry.
Recent Developments:
- In May 2024, Green Cargo introduced a new intermodal train service between Gothenburg Kombi and Norrköping Port, designed to improve goods transportation. This service offers daily departures from Monday to Friday for trailers, swap bodies, and containers, providing a fast, cost-effective, and eco-friendly transport option.
- In April 2024, DB Cargo announced the successful completion of two years of practical testing for a digital freight train equipped with a Digital Automatic Coupling (DAK) system. This technology aims to enhance the efficiency and power of rail freight transport, making it more climate-friendly.
- In October 2023, SNCF Logistics introduced a new digital platform aimed at optimizing freight operations. This platform leverages advanced data analytics to improve scheduling, reduce delays, and enhance overall service reliability.
- In March 2023, CSX Corporation released its annual report highlighting the introduction of innovative service solutions and the expansion of customer facilities along CSX lines. These initiatives are part of CSX's commitment to leveraging digital technologies to enhance safety and efficiency in rail freight operations.
Market Concentration & Characteristics:
The Rail Freight Digital Transformation market is characterized by moderate to high market concentration, with a few large players dominating the industry while several smaller companies contribute to niche segments. Major rail operators, logistics providers, and technology firms are leading the transformation by integrating advanced digital solutions such as IoT, AI, automation, and predictive analytics. The market is heavily influenced by key players who are investing in innovative technologies to improve operational efficiency, reduce costs, and meet growing sustainability demands. These companies often collaborate with tech providers to develop customized digital platforms that enhance freight tracking, real-time visibility, and predictive maintenance. While large players control the majority of the market share, regional players and smaller firms are gaining ground by offering specialized solutions tailored to local needs or specific cargo types. The market is evolving towards increased competition, with digital innovation and sustainability initiatives driving market dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Cargo Type, Service Type, Distance, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Rail Freight Digital Transformation market will continue to expand as more operators adopt digital technologies to enhance operational efficiency.
- Increased investments in automation, AI, and IoT will drive further innovation and improve freight tracking, predictive maintenance, and route optimization.
- The demand for eco-friendly and sustainable transport solutions will encourage the wider adoption of green technologies within the rail freight sector.
- The integration of blockchain technology will improve transparency and security in freight management, enhancing trust across the supply chain.
- Cloud-based platforms will become more prevalent, offering scalable, real-time data management and improved coordination across rail networks.
- Automation in rail freight operations will reduce costs and enhance safety, leading to a more efficient and reliable transportation system.
- Real-time tracking and data analytics will play a significant role in improving supply chain visibility and enhancing customer satisfaction.
- Public-private partnerships and government investments will continue to accelerate infrastructure modernization and digital transformation efforts.
- Smaller regional players will expand their market share by offering specialized solutions tailored to local or niche needs.
- The increasing focus on cybersecurity will drive innovations to protect rail freight systems from cyber threats, ensuring data integrity and operational security.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Rail Freight Digital Transformation market?
What factors are driving the growth of the Rail Freight Digital Transformation market?
What are some challenges faced by the Rail Freight Digital Transformation market?
Who are the major players in the Rail Freight Digital Transformation market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Rail Freight Digital Transformation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Rail Freight Digital Transformation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 63,695 million → 2032: USD 119,652.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Rail Freight Digital Transformation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Rail Freight Digital Transformation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Rail Freight Digital Transformation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Rail Freight Digital Transformation Market Drivers
- 3.3 Rail Freight Digital Transformation Market Restraints & Challenges
- 3.4 Rail Freight Digital Transformation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Rail Freight Digital Transformation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Rail Freight Digital Transformation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Rail Freight Digital Transformation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Rail Freight Digital Transformation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Rail Freight Digital Transformation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Rail Freight Digital Transformation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Rail Freight Digital Transformation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Rail Freight Digital Transformation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Rail Freight Digital Transformation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Rail Freight Digital Transformation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Rail Freight Digital Transformation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Rail Freight Digital Transformation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Rail Freight Digital Transformation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Rail Freight Digital Transformation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Rail Freight Digital Transformation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Rail Freight Digital Transformation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Rail Freight Digital Transformation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Rail Freight Digital Transformation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Rail Freight Digital Transformation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
