
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
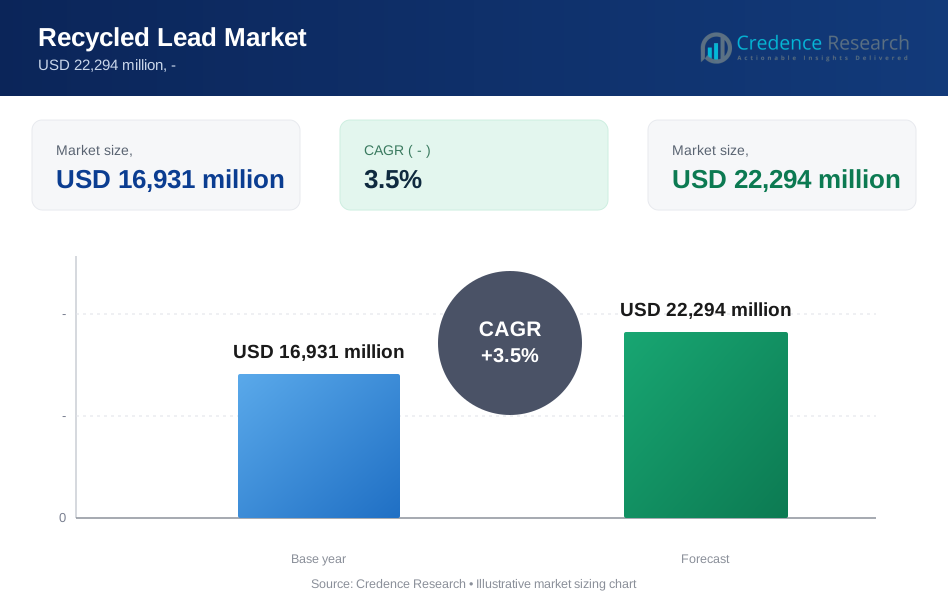
| Recycled Lead Market Size 2024 | USD 16,931 Million |
| Recycled Lead Market, CAGR | 3.5% |
| Recycled Lead Market Size 2032 | USD 22,294 Million |
Market Overview
The Recycled Lead Market is poised for notable expansion, driven by the increasing demand for sustainable materials and stringent environmental regulations. As of 2024, the global Recycled Lead Market is valued at approximately USD 16,931 million and is projected to grow at a compound annual growth rate (CAGR) of 3.5%, reaching around USD 22,294 million by 2032. This growth trajectory reflects a heightened awareness of the environmental impact of lead production and a shift towards recycling as a viable alternative.
Key factors fueling this market expansion include the rising demand for lead in various applications, particularly in batteries, construction, and electronics. The automotive industry's transition to electric vehicles is further increasing the need for lead-acid batteries, which are predominantly recycled. Additionally, government policies promoting recycling and sustainable practices are enhancing the market's growth prospects.
Regionally, North America is the largest market for recycled lead, driven by robust recycling programs and a well-established infrastructure for lead recovery. Europe follows closely, with stringent regulations on waste management and an increasing emphasis on sustainability bolstering market growth. The Asia-Pacific region is anticipated to experience significant growth, propelled by industrialization, urbanization, and rising awareness of the benefits of recycling. Emerging economies in this region, including China and India, are expected to provide substantial growth opportunities due to their expanding manufacturing sectors and commitment to improving environmental sustainability.
Market Drivers:
Increasing Demand for Sustainable Materials:
The global shift towards sustainability is a primary driver for the Recycled Lead Market. Governments and industries are increasingly recognizing the environmental benefits of recycling lead rather than producing it from virgin materials. This trend is evident in various sectors, particularly in battery manufacturing, where recycled lead is an essential component. According to the International Lead Association (ILA), approximately 85% of lead used in batteries is sourced from recycled materials, highlighting the industry's reliance on sustainable practices. For instance, the United Nations Environment Programme (UNEP) has reported that the global emphasis on sustainable development has led to policies encouraging recycling across multiple sectors. The International Monetary Fund (IMF) also supports this trend by promoting sustainable economic practices, which include the responsible management of resources such as lead. As more countries adopt stringent environmental regulations, such as the European Union's commitment to achieving 55% reductions in greenhouse gas emissions by 2030, the demand for recycled lead is expected to rise, aligning with global sustainability goals.
Stringent Environmental Regulations:
Government regulations regarding waste management and environmental protection are significant drivers of the Recycled Lead Market. Regulatory bodies around the world are implementing stricter policies aimed at reducing lead pollution and promoting recycling. For example, the European Union's Waste Framework Directive emphasizes recycling and recovery, mandating member states to increase recycling rates significantly. According to a report by the World Bank, countries are increasingly investing in policies that aim to achieve at least 50% recycling rates by 2025, pushing industries to adopt more sustainable practices. The U.S. Environmental Protection Agency (EPA) has also implemented regulations that encourage lead recycling, particularly in battery production, which further drives market growth. As industries comply with these regulations, including the EU's Circular Economy Action Plan that aims to make sustainable products the norm, the demand for recycled lead is expected to increase, leading to a more circular economy.
Technological Advancements in Recycling Processes:
Advancements in recycling technologies are enhancing the efficiency and effectiveness of lead recovery processes. Innovations such as hydrometallurgical methods and advanced pyrometallurgical processes are improving the purity and yield of recycled lead. These technologies not only make the recycling process more efficient but also reduce the environmental impact associated with traditional lead production methods. For instance, Research conducted by the National Renewable Energy Laboratory (NREL) indicates that the implementation of new recycling technologies can increase recovery rates of lead by up to 20%. Furthermore, investments in R&D by both private companies and government entities, such as the U.S. Department of Energy, which allocated over $1 billion for energy storage technologies in 2023, are driving innovations that contribute to the sustainability of the lead industry. As these technologies become more widespread, the competitiveness of recycled lead in various applications is likely to improve.
Rising Applications in Battery Manufacturing:
The demand for lead-acid batteries continues to grow, driven by the increasing use of electric vehicles (EVs) and renewable energy storage solutions. As the automotive industry transitions towards electrification, the need for reliable and cost-effective energy storage systems has surged. The International Energy Agency (IEA) projects that the global electric vehicle market will grow by more than 40% annually through 2030, significantly increasing the demand for lead-acid batteries, which predominantly use recycled lead. For instance, the Global Battery Alliance, supported by the World Economic Forum, estimates that lead-acid batteries will account for a substantial portion of the energy storage market in the coming years. As the need for efficient battery systems rises, so does the demand for recycled lead. In 2022, a survey conducted by the International Battery Association found that 70% of battery manufacturers are prioritizing recycled materials to meet sustainability targets. The convergence of renewable energy initiatives and the EV market further highlights the crucial role of recycled lead in supporting a sustainable energy future.
Market Trends:
Growth in Circular Economy Initiatives:
The Recycled Lead Market is increasingly influenced by the global shift towards a circular economy. This model emphasizes reducing waste and reusing materials, aligning with sustainability goals set by governments and international organizations. As countries adopt policies aimed at enhancing recycling rates, the demand for recycled lead is expected to rise significantly. For instance, the European Union's Circular Economy Action Plan, part of the European Green Deal, aims to promote the use of recycled materials across various sectors, including the lead industry. The European Commission has set a target of achieving a recycling rate of 70% for municipal waste by 2030, which underscores the importance of recycling initiatives. Additionally, the International Monetary Fund (IMF) supports sustainable economic practices, encouraging member nations to invest in circular economy frameworks that emphasize material recovery. This regulatory environment encourages industries to increase their reliance on recycled lead, positioning it as a key component of sustainable practices.
Technological Innovations in Recycling:
Technological advancements are playing a pivotal role in shaping the Recycled Lead Market. Innovative recycling techniques, such as advanced pyrometallurgical and hydrometallurgical processes, are enhancing the efficiency and effectiveness of lead recovery. These methods not only improve the yield and quality of recycled lead but also reduce the environmental impact associated with traditional production methods. For instance, the U.S. Department of Energy has invested over $100 million in R&D initiatives aimed at developing more efficient recycling technologies. A recent study by the National Renewable Energy Laboratory (NREL) indicates that implementing these new technologies can increase lead recovery rates by up to 20%, making recycling more economically viable. Furthermore, the International Lead Association (ILA) is collaborating with various stakeholders, including governmental bodies and industry leaders, to promote best practices in lead recycling, driving technological improvements in the sector. As industries continue to adopt these innovations, the Recycled Lead Market is likely to see increased efficiency and reduced costs, enhancing its competitiveness. This trend aligns with global sustainability goals and the demand for environmentally friendly materials, reinforcing the importance of recycled lead in a sustainable future.
Market Challenges Analysis:
Regulatory Compliance and Variability:
One of the significant challenges facing the Recycled Lead Market is navigating the complex landscape of regulatory compliance. Different countries and regions have varying regulations regarding lead recycling, waste management, and environmental protection, making it difficult for companies to operate consistently across borders. For instance, stringent regulations in the European Union, such as the Waste Framework Directive and REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals), impose strict requirements on lead recycling processes. Companies must invest substantial resources to ensure compliance, which can hinder operational efficiency and increase costs. the inconsistency in regulations can create uncertainty for businesses in the lead recycling sector. Companies operating in jurisdictions with less stringent regulations may find themselves at a competitive advantage, potentially undermining the market position of firms committed to higher environmental standards. This disparity complicates investment decisions, as companies must weigh the costs of compliance against potential profits. Furthermore, the evolving nature of regulations, as governments increasingly prioritize sustainability and environmental protection, adds another layer of complexity. Firms must stay informed and agile, adapting their practices to meet new requirements as they arise.
Market Perception and Public Awareness:
Another challenge is the market perception of recycled lead and its associated environmental impacts. Despite the advantages of recycling lead, public awareness and acceptance can be limited due to historical concerns about lead toxicity and environmental contamination. Negative perceptions can deter industries and consumers from utilizing recycled lead products, affecting market demand. For instance, campaigns and regulations that emphasize the dangers of lead exposure may overshadow the benefits of recycling, leading to a reluctance to engage with recycled materials. To combat this challenge, the industry must invest in education and outreach initiatives to enhance public understanding of the safety and benefits of recycled lead. Collaboration with government bodies, environmental organizations, and industry associations can help promote awareness of sustainable practices in lead recycling. For instance, the International Lead Association (ILA) has initiated various educational programs aimed at improving public knowledge about lead's safe use and the advantages of recycling. Addressing these perceptions is crucial for fostering a more favorable environment for recycled lead products, ultimately contributing to the market's growth and acceptance.
Market Segmentation Analysis:
By Type The Recycled Lead Market can be segmented based on the type of lead being recycled. This includes primary categories such as soft lead, lead alloys, and lead compounds. Soft lead is primarily used in applications like radiation shielding and roofing, while lead alloys are crucial for battery production, particularly in lead-acid batteries. The demand for specific types of recycled lead varies across industries, with soft lead witnessing steady demand in construction and shielding, while lead alloys are driven by the automotive sector's need for reliable energy storage solutions.
By Technology Technological advancements play a crucial role in the recycling of lead, and the market can be segmented by the recycling methods employed. Key technologies include pyrometallurgical processes, which involve high-temperature melting to extract lead, and hydrometallurgical methods that utilize aqueous solutions to recover lead from scrap materials. Emerging technologies, such as bioleaching and other innovative recovery methods, are also gaining traction. The choice of technology significantly impacts the efficiency, cost, and environmental footprint of lead recycling operations, with companies increasingly investing in advanced processes to enhance recovery rates and reduce emissions.
By End-User The Recycled Lead Market can be further segmented based on end-user industries, which include automotive, construction, electronics, and energy. The automotive industry is the largest consumer of recycled lead, primarily for lead-acid batteries used in vehicles. In construction, recycled lead is used in roofing and shielding applications, while the electronics sector utilizes it in various components. The energy sector, especially with the rise of renewable energy storage systems, is also becoming an important end-user, driving demand for recycled lead in energy storage solutions. Each of these industries presents unique challenges and opportunities, shaping the overall dynamics of the recycled lead market.
Segmentations:
Based on Product Type:
- Soft Lead
- Lead Alloys
- Lead Compounds
Based on Technology:
- Pyrometallurgical Processes
- Hydrometallurgical Methods
- Emerging Recovery Technologies
Based on End-User:
- Automotive
- Construction
- Electronics
- Energy
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Recycled Lead Market, accounting for approximately 35% of the total market. The region is characterized by a well-established recycling infrastructure, driven by stringent environmental regulations and a robust automotive industry that relies heavily on lead-acid batteries. The U.S. Environmental Protection Agency (EPA) has implemented regulations that promote the recycling of lead, particularly from batteries, which further supports market growth.
In addition, major players in the region are investing in advanced recycling technologies, which enhance recovery rates and improve the environmental footprint of lead recycling processes. The growing emphasis on sustainability and the circular economy is pushing both manufacturers and consumers towards recycled materials. As electric vehicles (EVs) gain traction, the demand for reliable energy storage solutions using recycled lead is expected to increase, solidifying North America's position as a leader in this market.
Europe
Europe is another key player in the Recycled Lead Market, capturing around 30% of the total market share. The region’s strong commitment to sustainability is reflected in its comprehensive regulatory framework, including the European Union's Circular Economy Action Plan and the Waste Framework Directive. These initiatives aim to promote recycling and reduce waste, which drives demand for recycled lead across various industries. Countries like Germany, the United Kingdom, and France are at the forefront of adopting advanced recycling technologies, thereby increasing lead recovery rates. The European market is also witnessing a growing awareness of the environmental impacts of lead, pushing industries to adopt recycled alternatives. The construction sector, along with automotive and electronics, significantly contributes to the demand for recycled lead. Furthermore, the European market benefits from a strong network of recycling facilities, which enhances operational efficiencies and supports a circular economy.
Asia-Pacific
The Asia-Pacific region is poised for rapid growth in the Recycled Lead Market, expected to capture about 25% of the total market share by 2025. This growth is primarily driven by rapid industrialization, urbanization, and increasing investments in recycling infrastructure in countries such as China, India, and Japan. China, in particular, is a significant player, being one of the largest consumers of lead globally and actively promoting lead recycling initiatives through government policies. As awareness of environmental sustainability increases, the region is witnessing a shift towards the adoption of recycled materials in various sectors, including automotive and construction. The rising demand for lead-acid batteries in the electric vehicle market is further fueling the growth of recycled lead consumption in Asia-Pacific. Additionally, government initiatives aimed at reducing lead pollution and promoting safe recycling practices are expected to create a conducive environment for market expansion.
Key Players:
- Aqua Metals, Inc.
- Boliden Group
- Gravita India Limited
- Eco Bat Technologies
- Korea Zinc Co., Ltd.
- Mayco Industries
- NYRSTAR
- Recyclex S.A.
- SAR Recycling SA
- Henan Yuguang Gold and Lead Co., Ltd.
- The Doe Run Company
- Mittal Pigments
Competitive Analysis
The Recycled Lead Market is highly competitive, characterized by the presence of several key players striving for market share through technological advancements and strategic partnerships. Major companies such as Exide Technologies, Johnson Controls, and Aquafix dominate the landscape, leveraging their extensive recycling capabilities and established supply chains to deliver high-quality recycled lead products. These companies invest significantly in R&D to enhance recycling processes, improve lead recovery rates, and reduce environmental impact. Additionally, regional players are emerging, particularly in Asia-Pacific, where growing demand for recycled materials is prompting local firms to innovate and compete effectively. The competitive landscape is further influenced by stringent environmental regulations that drive companies to adopt sustainable practices. Collaboration between industries and government entities is common, aimed at promoting recycling initiatives and developing best practices. As the market evolves, companies are increasingly focusing on sustainability, exploring new technologies, and expanding their geographic reach to meet the rising demand for recycled lead, especially in the automotive and construction sectors. The emphasis on a circular economy and regulatory support across regions will likely intensify competition, pushing firms to differentiate themselves through quality, efficiency, and commitment to environmental stewardship. As a result, companies that can navigate these dynamics effectively will be well-positioned to thrive in the growing Recycled Lead Market.
Recent Developments
- On April 4, 2023, Gravita India received the Best Investor and Employer award from the Sandiara Municipal and Investment Council in Senegal. This recognition highlights the company’s commitment to sustainable practices and its positive impact on local communities through investment and job creation.
- Following this achievement, on April 20, 2023, Gravita India expanded its lead recycling capacity at the Mundra Port plant in Gujarat by 40,500 tons per annum. This increase reinforces the company’s dedication to enhancing its operational efficiency and meeting growing demand in the recycling sector, further solidifying its position as a leader in sustainable resource management.
Market Concentration & Characteristics:
The Recycled Lead Market exhibits a moderate level of concentration, characterized by a mix of established multinational corporations and smaller regional players. Major companies, such as Exide Technologies and Johnson Controls, hold significant market shares due to their extensive recycling operations and strong distribution networks. However, the presence of smaller firms, particularly in emerging markets like Asia-Pacific, is increasing as they capitalize on local demand and invest in advanced recycling technologies. This dual landscape fosters healthy competition, driving innovation and efficiency in recycling processes. Additionally, the market is influenced by regulatory frameworks that promote sustainable practices, compelling firms to enhance their operational standards and environmental performance. The characteristics of the market include a growing emphasis on sustainability, with stakeholders increasingly prioritizing eco-friendly practices and circular economy principles. Demand is predominantly driven by the automotive and construction sectors, where recycled lead is a critical component. Furthermore, technological advancements in lead recovery methods are transforming the industry, allowing companies to achieve higher recovery rates and lower emissions. As sustainability becomes a core focus, collaboration between industry players, governmental bodies, and environmental organizations is becoming more common, reinforcing the commitment to responsible resource management. Overall, the Recycled Lead Market is evolving rapidly, balancing the strengths of established players with the agility of emerging firms, resulting in a dynamic and responsive industry landscape.
Report Coverage:
This report provides a comprehensive analysis of the Recycled Lead Market, encompassing key trends, drivers, challenges, and opportunities shaping the industry. It delves into the market segmentation based on product type, technology, end-user industries, and geographic regions, including North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The report highlights the competitive landscape, profiling major players such as Exide Technologies and Johnson Controls, while also acknowledging the rising influence of regional and emerging companies. Additionally, it examines the regulatory environment, emphasizing how stringent environmental policies and sustainability initiatives are driving the demand for recycled lead. Technological advancements in recycling processes are explored, showcasing innovations that enhance efficiency and recovery rates. The report also addresses market concentration and characteristics, discussing the balance between established multinationals and smaller, agile firms. Insights into market share percentages across different regions and sectors provide a clearer picture of the industry's dynamics. Overall, this report serves as a valuable resource for stakeholders, including manufacturers, investors, and policymakers, seeking to understand the complexities of the Recycled Lead Market and identify strategic opportunities for growth in a rapidly evolving landscape.
Future Outlook:
- Anticipate increased adoption of recycled lead due to rising sustainability mandates across various industries.
- Expect significant growth in electric vehicle production, driving demand for lead-acid batteries made from recycled materials.
- Monitor advancements in recycling technologies that improve efficiency and recovery rates, enhancing competitiveness.
- Anticipate stricter regulatory frameworks globally that will further promote lead recycling initiatives.
- Watch for increased investment in recycling infrastructure, particularly in developing regions like Asia-Pacific.
- Expect growing collaboration among industry players, governments, and environmental organizations to promote best practices in recycling.
- Anticipate heightened consumer awareness regarding the environmental impact of materials, influencing purchasing decisions.
- Monitor the rise of alternative technologies that may challenge traditional lead recycling methods, prompting innovation.
- Expect diversification of applications for recycled lead beyond batteries, including construction and electronics.
- Watch for shifts in global supply chains, with more emphasis on local sourcing of recycled materials to reduce carbon footprints.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Sustainable Materials
The global shift toward sustainability is driving industries to use recycled lead instead of primary lead, especially in batteries and construction, as companies and governments seek to reduce environmental impact and resource depletion.
Stringent Environmental Regulations
Governments worldwide are implementing stricter regulations on waste management and lead pollution, compelling industries to adopt recycled lead to comply with environmental standards and circular economy mandates.
Technological Advancements in Recycling Processes
Innovations such as advanced pyrometallurgical and hydrometallurgical methods are improving the efficiency, yield, and environmental footprint of lead recycling, making recycled lead more competitive and attractive for industrial applications.
Rising Applications in Battery Manufacturing
The growth of electric vehicles and renewable energy storage is increasing the demand for lead-acid batteries, which predominantly use recycled lead, thereby fueling market expansion.
Growth in Circular Economy Initiatives
Policies and initiatives promoting circular economy practices are encouraging higher recycling rates and the use of recycled materials, positioning recycled lead as a key component in sustainable industrial supply chains.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the Recycled Lead Market?
What is the projected market value of the Recycled Lead Market by 2032?
Which regions are leading in the Recycled Lead Market?
What applications are driving demand for recycled lead?
How do government policies influence the Recycled Lead Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Automotive
- 1.2.2 Construction
- 1.2.3 Electronics
- 1.2.4 Energy
- 1.3 By Technology
- 1.3.1 Pyrometallurgical Processes
- 1.3.2 Hydrometallurgical Methods
- 1.3.3 Emerging Recovery Technologies
- 1.4 By Product Type
- 1.4.1 Soft Lead
- 1.4.2 Lead Alloys
- 1.4.3 Lead Compounds
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 16,931 million → Forecast year: USD 22,294 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Recycled Lead Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Recycled Lead Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Recycled Lead Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Recycled Lead Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Recycled Lead Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Recycled Lead Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Recycled Lead Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Recycled Lead Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 16,931 million → Forecast year: USD 22,294 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Recycled Lead Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Construction
- 12.3.7.3 Electronics
- 12.3.7.4 Energy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pyrometallurgical Processes
- 12.4.7.2 Hydrometallurgical Methods
- 12.4.7.3 Emerging Recovery Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soft Lead
- 12.5.7.2 Lead Alloys
- 12.5.7.3 Lead Compounds
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Recycled Lead End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Recycled Lead Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Recycled Lead Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Recycled Lead Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aqua Metals, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Boliden Group
- 18.4 Gravita India Limited
- 18.5 Eco Bat Technologies
- 18.6 Korea Zinc Co., Ltd.
- 18.7 Mayco Industries
- 18.8 NYRSTAR
- 18.9 Recyclex S.A.
- 18.10 SAR Recycling SA
- 18.11 Henan Yuguang Gold and Lead Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

