
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Robotic Laser Cutting Market Size 2023 | USD 5,577.29 million |
| Robotic Laser Cutting Market, CAGR | 11.95% |
| Robotic Laser Cutting Market Size 2032 | USD 15,539.35 million |
Market Overview
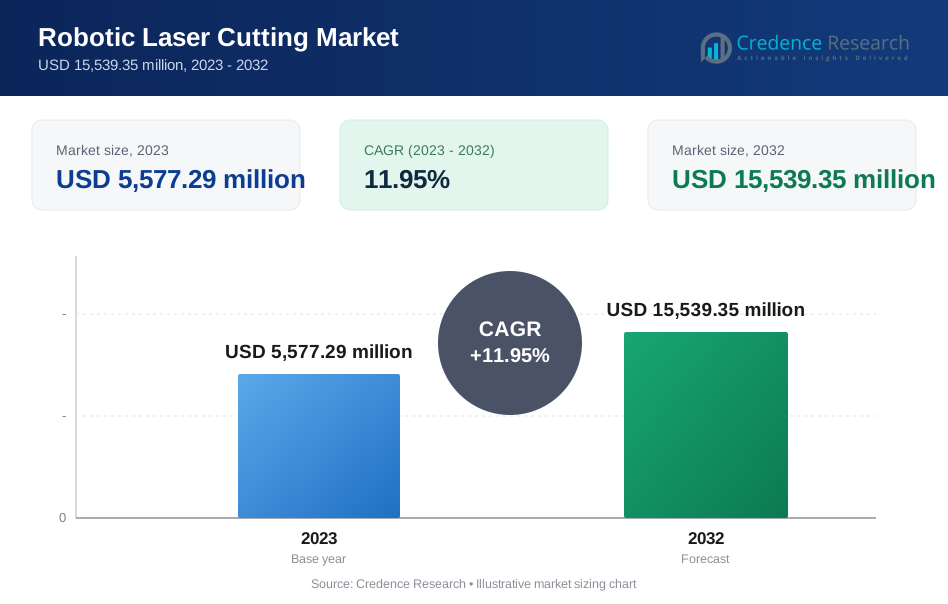
The Global Robotic Laser Cutting Market is poised for significant growth, with projections indicating an increase from USD 5,577.29 million in 2023 to an estimated USD 15,539.35 million by 2032. This expansion represents a robust compound annual growth rate (CAGR) of 11.95% from 2024 to 2032. The market's growth is driven by advancements in technology and increased adoption of robotic systems across various industries, enhancing productivity and precision in manufacturing processes.
Key drivers of the robotic laser cutting market include the rising demand for automation in manufacturing to improve operational efficiency and accuracy. Innovations in laser cutting technology and the integration of advanced robotics are further propelling market growth. Additionally, the increasing need for customization and high-quality production in sectors such as automotive, aerospace, and electronics is fueling the demand for robotic laser cutting solutions.
Geographically, the market shows substantial growth potential across regions, with North America, Europe, and Asia-Pacific being prominent contributors. North America and Europe are expected to lead due to advanced technological infrastructure and significant investments in manufacturing automation. Meanwhile, Asia-Pacific is anticipated to witness rapid growth driven by industrialization and increasing manufacturing activities. Key players in the market include FANUC Corporation, ABB Ltd., KUKA AG, and Yaskawa Electric Corporation, which are at the forefront of delivering innovative robotic laser cutting solutions.
Market Drivers
Advancements in Laser Technology
The rapid evolution of laser technology is a significant driver of the global robotic laser cutting market. Recent innovations, such as high-power fiber lasers and ultrafast lasers, have markedly improved the performance and capabilities of laser cutting systems. High-power fiber lasers offer superior cutting speeds and precision, while ultrafast lasers enable cutting of extremely thin materials with minimal heat-affected zones. These technological advancements enhance the efficiency and versatility of robotic laser cutting systems, making them increasingly attractive for a wide range of applications across various industries. As laser technology continues to advance, it will drive further adoption of robotic laser cutting solutions, as manufacturers seek to leverage these innovations to achieve higher productivity and better quality.
Rising Demand for Automation in Manufacturing
The growing emphasis on automation within the manufacturing sector is a crucial driver of the robotic laser cutting market. Automation provides significant advantages, including increased operational efficiency, reduced labor costs, and improved precision and consistency in production processes. For instance, by 2030, a staggering 2.1 million jobs are expected to remain unfilled, creating a substantial gap in the workforce. Robotic laser cutting systems, which combine the flexibility of robotics with the precision of laser technology, are particularly well-suited to meet these demands. They enable manufacturers to automate complex cutting tasks, reduce manual handling, and achieve higher throughput with fewer errors. As industries continue to seek ways to enhance their manufacturing processes and adapt to competitive pressures, the adoption of robotic laser cutting solutions is expected to increase significantly.
Expanding Applications Across Various Industries
The versatility of robotic laser cutting technology contributes to its growing adoption across a range of industries. Key sectors such as automotive, aerospace, electronics, and metal fabrication are increasingly utilizing robotic laser cutting systems due to their ability to deliver high-quality cuts with minimal material waste. In the automotive industry, robotic laser cutting is used for intricate parts and components, while in aerospace, it ensures precise cuts for lightweight materials. The electronics sector benefits from the technology's ability to handle delicate components, and metal fabrication industries leverage its capability to cut through various metals efficiently. For example, the Department of Energy's Office of Science utilizes more than 2,500 high-power laser systems at its ten national laboratories for a wide range of applications from medicine to semiconductor lithography. As these industries continue to expand and evolve, the demand for robotic laser cutting solutions is expected to grow, driven by the need for precise, efficient, and customizable cutting solutions.
Increasing Focus on Customization and Complex Designs
The growing trend toward customization and the demand for complex designs in manufacturing are significant drivers of the robotic laser cutting market. As consumer preferences shift towards personalized products and intricate designs, manufacturers are compelled to adopt technologies that can accommodate these requirements efficiently. Robotic laser cutting systems offer the flexibility to handle complex geometries and intricate patterns with high accuracy, making them ideal for applications requiring customization. This capability allows manufacturers to meet diverse customer needs while maintaining high production standards. For instance, in the prostheses manufacturing industry, the use of laser technology has reduced production costs and increased production speed, allowing manufacturers to significantly increase their manufacturing capacities. The ability to quickly adapt to changing design requirements and produce customized products efficiently will drive the continued growth of the robotic laser cutting market, as companies seek to stay competitive and responsive to market demands.
Market Trends
Integration of Artificial Intelligence and Machine Learning
One of the most notable trends in the global robotic laser cutting market is the integration of artificial intelligence (AI) and machine learning (ML) technologies. These advancements are transforming robotic laser cutting systems by enhancing their capabilities and efficiency. For instance, AI-driven systems can adjust cutting parameters dynamically to accommodate variations in material thickness or surface quality, leading to more precise and consistent results. AI algorithms are being employed to optimize cutting paths, predict maintenance needs, and improve quality control by analyzing real-time data from laser cutting processes. Machine learning, on the other hand, enables robotic systems to learn from past performance and continuously improve their accuracy and efficiency. For instance, AI-driven systems can adjust cutting parameters dynamically to accommodate variations in material thickness or surface quality, leading to more precise and consistent results. This trend is driven by the increasing need for advanced automation solutions that can handle complex and variable manufacturing requirements with minimal human intervention. As AI and ML technologies continue to evolve, their integration into robotic laser cutting systems is expected to become more prevalent, offering enhanced performance and operational efficiency.
Emergence of Hybrid Laser Cutting Systems
Another significant trend in the robotic laser cutting market is the development and adoption of hybrid laser cutting systems. These systems combine multiple laser technologies, such as fiber and CO2 lasers, within a single machine, providing greater flexibility and versatility in cutting various materials. Hybrid systems are designed to optimize cutting performance based on the specific requirements of different applications, whether it's for high-speed processing of thin metals or precision cutting of thicker materials. The ability to switch between different laser types or combine them in a single setup allows manufacturers to achieve higher efficiency and better quality in their cutting operations. This trend is particularly relevant for industries that require diverse cutting capabilities, such as automotive and aerospace, where material types and thicknesses can vary significantly. As the demand for versatile and adaptable manufacturing solutions grows, hybrid laser cutting systems are becoming increasingly popular, offering a competitive edge by providing enhanced functionality and performance in a single integrated solution.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the primary challenges in the global robotic laser cutting market is the high initial investment and ongoing maintenance costs associated with these systems. Robotic laser cutting equipment requires a substantial capital expenditure for acquisition, installation, and calibration. The cost of advanced laser technology, robotic arms, and control systems can be significant, particularly for small and medium-sized enterprises (SMEs) with limited budgets. Additionally, maintaining and servicing these sophisticated systems requires specialized knowledge and skills, further contributing to operational expenses. Regular maintenance and potential repairs can add to the overall cost, making it a considerable financial burden for businesses. This high cost can be a barrier to entry for companies looking to adopt robotic laser cutting technology, particularly in regions with lower industrial investment. As a result, some potential users may hesitate to invest in these systems despite their benefits, limiting market growth.
Technical Complexity and Integration Issues
The technical complexity of robotic laser cutting systems and the challenges associated with their integration into existing manufacturing processes pose significant obstacles. Robotic laser cutting involves intricate technology that requires precise programming, calibration, and integration with other manufacturing equipment. This complexity can lead to difficulties in achieving optimal performance and ensuring smooth operation within established production lines. Companies may face challenges in adapting their current processes to accommodate robotic systems, which can result in increased downtime and disruption during the transition period. Furthermore, the need for skilled personnel to operate and troubleshoot advanced robotic systems adds to the complexity. The integration of robotic laser cutting technology with other automation solutions and legacy systems may require substantial adjustments and technical expertise, which can be a barrier for some organizations. Addressing these challenges requires careful planning and investment in training and support, which can be a deterrent for potential adopters.
Market Segmentation Analysis
By Type
CO2 Laser Cutting Machines are valued for their versatility and high-quality cuts, excelling in processing non-metal materials such as plastics, wood, and glass with intricate designs and high precision. They operate using a CO2 gas mixture to generate the laser beam, though they are generally less efficient and require more maintenance compared to fiber lasers. Fiber Laser Cutting Machines have gained prominence for their superior efficiency and performance, particularly in metal cutting applications. Utilizing fiber optic cables to deliver the laser beam, they offer higher power density, faster cutting speeds, and better energy efficiency with lower operational costs. These advantages make them the preferred choice in industries like automotive, aerospace, and metal fabrication. YAG (Yttrium Aluminum Garnet) Cutting Machines are known for producing high-energy, concentrated laser beams ideal for cutting hard materials. Though less common than CO2 and fiber lasers, YAG lasers are used in specialized applications that demand high power and precision.
By Application
Robotic laser cutting technology is pivotal across various industries due to its precision and efficiency. In the automobile industry, it is used extensively for cutting body panels, chassis parts, and structural elements, enhancing productivity and supporting complex designs in high-volume production. The metal industry relies on robotic laser cutting for processing diverse metals, including steel, aluminum, and titanium, facilitating accurate cutting of sheets and plates crucial for structural fabrication and metalworking. In the aerospace sector, the technology's ability to handle advanced materials and complex geometries is vital for manufacturing high-quality aircraft components and engine parts. Additionally, in the others category, which encompasses electronics, medical devices, and consumer goods, robotic laser cutting supports specialized tasks requiring precision and customization, such as intricate component cutting and small-batch production.
Segments
Based on Type
- CO2 Laser Cutting Machines
- Fiber Laser Cutting Machines
- YAG Laser Cutting Machines
Based on Application
- Automobile Industry
- Metal Industry
- Aerospace
- Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (30%):
North America holds a significant share of the global robotic laser cutting market, accounting for approximately 30% of the market share. The United States and Canada are key contributors to this dominance, driven by advanced manufacturing infrastructure and high adoption rates of automation technologies. The region's robust automotive and aerospace industries rely heavily on robotic laser cutting for precision and efficiency. Additionally, continuous technological innovations and investments in manufacturing automation further bolster market growth in North America.
Europe (28%):
Europe represents a substantial portion of the global market, with an estimated market share of 28%. Countries such as Germany, the United Kingdom, and France lead in adopting robotic laser cutting technology due to their strong industrial base and emphasis on high-quality manufacturing processes. The automotive sector, along with aerospace and metal industries, drives significant demand for advanced laser cutting solutions. Europe's focus on technological advancements and sustainability also supports continued market growth, making it a crucial region for robotic laser cutting technologies.
Key players
- ABB Ltd.
- AMADA Co. Ltd.
- Amdoit Technologies Pvt. Ltd.
- BLM S.P.A.
- Chutian Laser
- Daihen Corp.
- DIVINE TECHNO ENGINEERS
- FANUC Corp.
- HGLaser Engineering Co. Ltd.
- Jenoptik AG
- KUKA AG
- Laser Photonics
- MIDEA Group Co. Ltd.
- Precitec GmbH and Co. KG
- Productive Robotics Inc.
- Shape Process Automation
- SHFULAI
- Spark Robotic
- Staubli International AG
- Suresh Indu Lasers Pvt Ltd.
- VP Synergic Weld Solutions Pvt Ltd.
- Yaskawa Electric Corp.
Competitive Analysis
The global robotic laser cutting market is highly competitive, with key players striving to differentiate themselves through technological innovation and comprehensive product offerings. Industry leaders such as ABB Ltd., FANUC Corp., and KUKA AG dominate with their advanced robotic systems and broad market reach. Companies like AMADA Co. Ltd. and Precitec GmbH and Co. KG focus on enhancing laser cutting precision and efficiency. Emerging players such as Amdoit Technologies Pvt. Ltd. and DIVINE TECHNO ENGINEERS are gaining traction by offering specialized solutions and targeting niche applications. Competitive strategies include continuous R&D, partnerships, and expanding product portfolios to meet diverse industrial needs. As the market evolves, maintaining technological leadership and adapting to industry demands will be crucial for sustaining competitive advantage.
Recent Developments
In August 2022, Bystronic Inc. collaborated with Nano Lock Security to develop customized security solutions tailored to the needs of sheet and tube metal cutting, bending, and automation systems. This partnership aims to tackle persistent security challenges faced by downstream industries, thereby addressing gaps in current solutions. By enhancing security measures for laser cutting technologies, this collaboration is expected to drive market growth and increase demand for advanced laser cutting solutions, ensuring that industry-specific needs are met with more robust and effective security measures.
In April 2022, Mazak Optonics Corp. introduced the Optiplex 3015 Neo 15kw, a state-of-the-art 2D fiber laser-cutting system known for its precise control over beam shape and diameter. This advanced system offers adaptable cutting capabilities for a wide range of materials and configurations, enhancing both speed and quality. The Optiplex 3015 Neo 15kw stands out for its ability to deliver exceptional performance across various applications, making it a significant innovation in the field of laser cutting technology.
In May 2022, Monport Tech Inc. launched the Monfort laser, notable for its exceptional customer service, affordability, and high output quality. Before its market introduction, this laser engraving machine demonstrated its reliability and efficiency through successful engraving of various valuable materials. The Monfort laser's combination of cost-effectiveness and superior performance makes it an attractive option for users seeking reliable engraving solutions, reinforcing Monport Tech Inc.'s commitment to delivering high-quality products.
In May 2021, Yamazaki Mazak Corporation released the FG-220, a precision cutting machine designed to accurately cut a variety of structural materials, including round, square, rectangular, and open profiles. This innovative machine offers several advantages, such as reduced setup time, faster lead times, lower operator dependency, and minimized floor space requirements. The FG-220 enhances operational efficiency and versatility, making it a valuable addition to manufacturing processes requiring precise and adaptable cutting solutions.
In March 2023, ABB announced its commitment to strengthening its presence in the U.S. robotics market by expanding its North American robotics headquarters and manufacturing facility in Auburn Hills, Michigan. This expansion underscores ABB's dedication to meeting the growing demand for robotic solutions and enhancing its capabilities in the region. The upgraded facility will support ABB's efforts to deliver advanced robotics technology and services, reinforcing its position as a key player in the North American robotics sector.
In July 2023, ABB Robotics unveiled four new robot models and 22 variants, offering significant advancements in energy efficiency and performance. These new robots provide up to 20% energy savings, with payload capacities ranging from 150kg to 310kg and reach capabilities from 2.5m to 3.2m. Designed to enhance resilience across various industries, including automotive, general manufacturing, foundry, food and beverage, and logistics, these robots represent ABB's commitment to innovation and meeting diverse customer needs in the evolving robotics market.
Market Concentration and Characteristics
The global robotic laser cutting market is characterized by a moderate to high level of concentration, with a significant presence of both established industry leaders and emerging players. Major companies, such as ABB Ltd., FANUC Corp., and KUKA AG, dominate the market due to their extensive product portfolios, advanced technological capabilities, and substantial market reach. These key players leverage continuous innovation and strategic partnerships to maintain competitive advantage. Simultaneously, the market features a growing number of specialized firms, such as Mazak Optonics Corp. and Monport Tech Inc., which contribute to market diversity with niche solutions and advancements in laser cutting technology. This blend of leading corporations and innovative newcomers creates a dynamic and competitive landscape, driving technological progress and catering to a wide range of industrial applications.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global robotic laser cutting market is expected to see broad adoption across diverse industries, including automotive, aerospace, and electronics. Enhanced precision and efficiency will drive growth as industries seek advanced manufacturing solutions.
- Ongoing technological innovations, such as improved laser sources and automation integration, will lead to more versatile and high-performance robotic laser cutting systems. These advancements will expand application possibilities and enhance cutting quality.
- The growing need for customized and complex designs in manufacturing will boost the demand for robotic laser cutting technologies. Systems that offer flexible and precise cutting will be increasingly valued by manufacturers.
- Future developments will emphasize energy-efficient laser cutting solutions to reduce operational costs and environmental impact. New technologies will aim to lower energy consumption while maintaining high performance.
- Emerging markets in Asia-Pacific and Latin America will experience significant growth in robotic laser cutting adoption. Expanding industrial activities and investments in automation will drive market expansion in these regions.
- The integration of robotic laser cutting systems with Industry 4.0 technologies, such as IoT and AI, will enhance automation and data-driven decision-making. This will improve operational efficiency and real-time process optimization.
- Innovations in software and control systems will provide more sophisticated features, including enhanced programming capabilities and real-time monitoring. These advancements will facilitate more precise and adaptable cutting processes.
- The rise of e-commerce and online retail will drive demand for robotic laser cutting in packaging and product customization. Companies will increasingly use laser cutting for creating tailored packaging solutions and unique product designs.
- Significant investments in research and development will continue to push the boundaries of robotic laser cutting technology. Enhanced R&D efforts will lead to breakthroughs in laser cutting performance and application versatility.
- As sustainability becomes a key focus, robotic laser cutting technologies will evolve to meet stricter environmental regulations. Market players will develop solutions that reduce waste and support sustainable manufacturing practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Laser Technology
Rapid innovation in high-power fiber and ultrafast lasers has significantly improved the speed, precision, and versatility of robotic laser cutting systems, making them more attractive for a wide range of industrial applications.
Increased Automation in Manufacturing
Manufacturers are adopting robotic laser cutting to address labor shortages, reduce operational costs, and achieve higher throughput with greater accuracy, driving widespread implementation across industries.
Expanding Applications Across Industries
The versatility of robotic laser cutting enables its use in automotive, aerospace, electronics, and metal fabrication, where it delivers high-quality, precise cuts and supports complex, customized production requirements.
Focus on Customization and Complex Designs
Growing demand for personalized products and intricate geometries in manufacturing is pushing companies to adopt robotic laser cutting systems, which offer the flexibility and precision needed for efficient, high-quality customization.
Integration of AI and Machine Learning
The adoption of AI and machine learning in robotic laser cutting systems is enhancing process optimization, predictive maintenance, and real-time quality control, leading to improved operational efficiency and product quality.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the global robotic laser cutting market?
What are the primary drivers behind the growth of the robotic laser cutting market?
Which regions are leading the growth in the robotic laser cutting market?
What challenges are faced by companies adopting robotic laser cutting technology?
How is the integration of AI and ML impacting the robotic laser cutting market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 CO2 Laser Cutting Machines
- 1.2.2 Fiber Laser Cutting Machines
- 1.2.3 YAG Laser Cutting Machines
- 1.3 By Application
- 1.3.1 Automobile Industry
- 1.3.2 Metal Industry
- 1.3.3 Aerospace
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 5,577.29 million → 2032: USD 15,539.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Robotic Laser Cutting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Robotic Laser Cutting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Robotic Laser Cutting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Robotic Laser Cutting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Robotic Laser Cutting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Robotic Laser Cutting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Robotic Laser Cutting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Robotic Laser Cutting Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 5,577.29 million → 2032: USD 15,539.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Robotic Laser Cutting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 CO2 Laser Cutting Machines
- 12.3.7.2 Fiber Laser Cutting Machines
- 12.3.7.3 YAG Laser Cutting Machines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automobile Industry
- 12.4.7.2 Metal Industry
- 12.4.7.3 Aerospace
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Robotic Laser Cutting End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Robotic Laser Cutting Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Robotic Laser Cutting Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Robotic Laser Cutting Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 FANUC Corporation
- 18.4 KUKA AG
- 18.5 Yaskawa Electric Corporation
- 18.6 AMADA Co. Ltd.
- 18.7 Precitec GmbH and Co. KG
- 18.8 Mazak Optonics Corp.
- 18.9 BLM S.P.A.
- 18.10 Jenoptik AG
- 18.11 Laser Photonics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

