
AI agents turn CRM rollouts into continuous programs
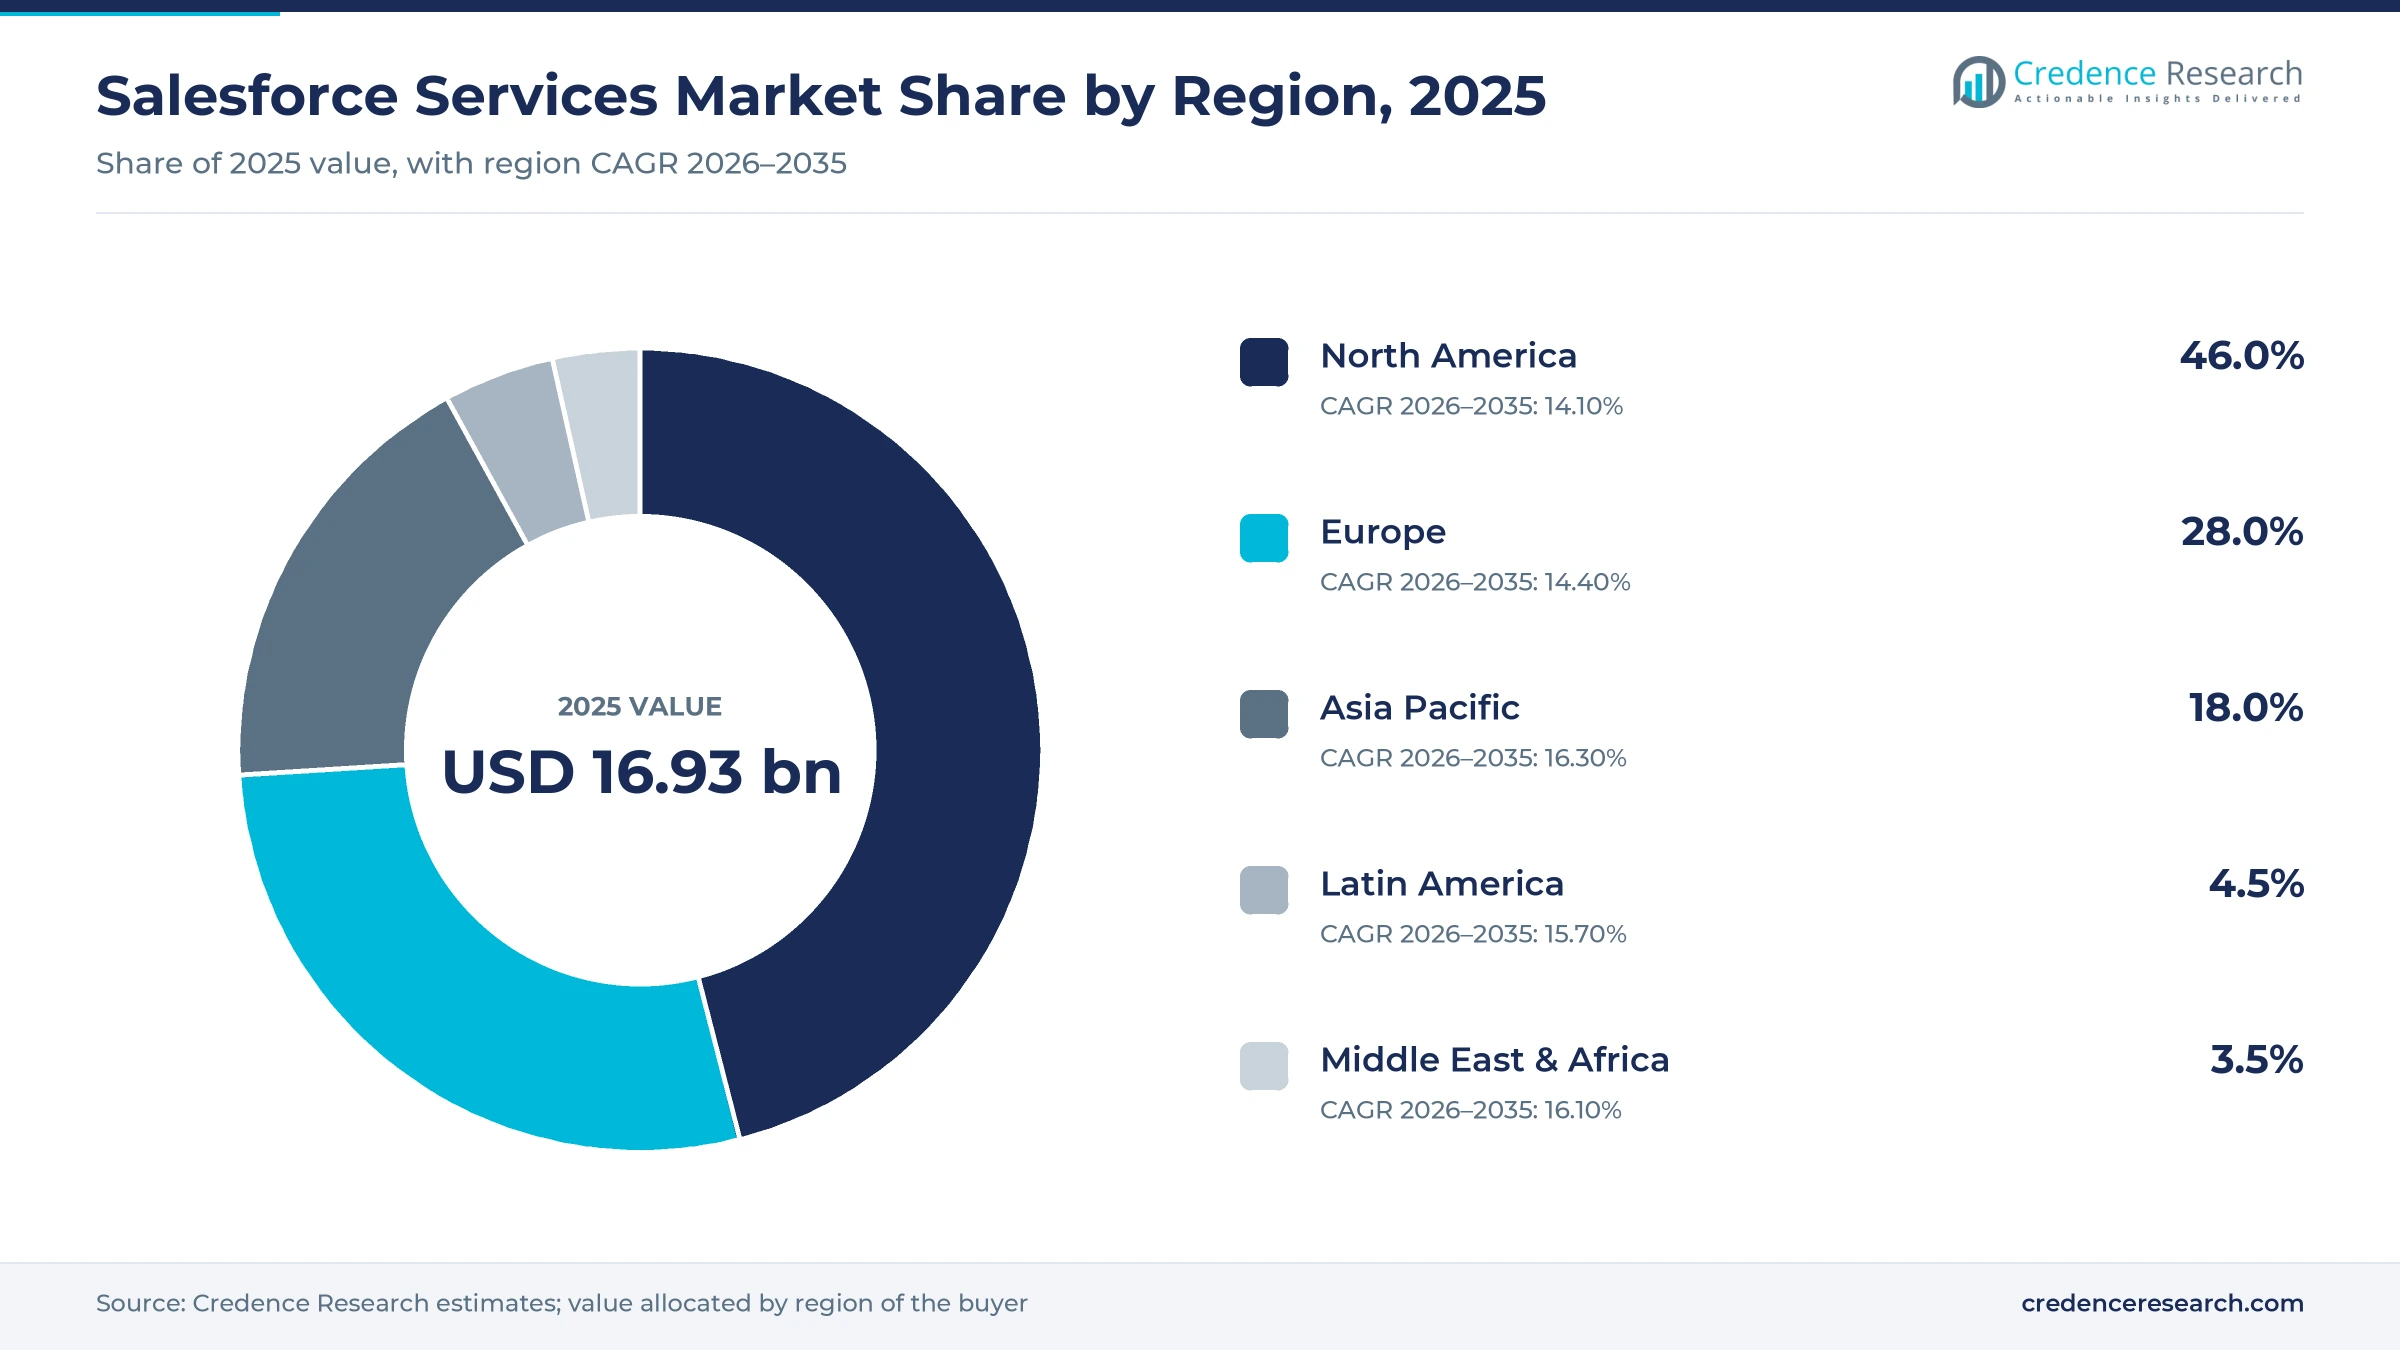
The global Salesforce services market was valued at USD 16.93 billion in 2025 and is projected to increase from USD 19.43 billion in 2026 to USD 67.02 billion by 2035, registering a CAGR of 14.75% during 2026–2035. Demand comes from banks, insurers, hospitals, retailers and public agencies that hire partners to plan, implement and run Sales Cloud, Service Cloud, Data Cloud and Agentforce deployments. North America held the largest regional share, 46.0% in 2025, because the U.S. federal government cleared Agentforce for FedRAMP High workloads in June 2025 and federal buyers gained steep Slack discounts through the GSA in May 2025. Asia Pacific is the fastest-growing region at 16.30% a year, as NTT DATA and Salesforce expand certified teams in Japan and India. The main commercial change is the move from classic CRM projects to AI agent work, since Salesforce reported more than 18,500 Agentforce deals by Oct. 31, 2025. Partners now sell data readiness, agent design and ongoing tuning alongside configuration.
What does the Salesforce services market include?
The report counts fees paid to consulting firms, systems integrators and specialist partners for planning, implementing, integrating and managing Salesforce applications, including Sales Cloud, Service Cloud, Marketing Cloud, industry clouds, MuleSoft, Tableau, Slack and Agentforce. Buyers usually purchase this work through fixed-price projects, time-and-materials contracts or multi-year managed service agreements.
Salesforce subscription fees are excluded, as are AppExchange software licenses and the salaries of in-house administrators. The value chain runs from Salesforce product teams through global integrators, regional boutiques and offshore delivery centers to the end customer, which pays for advisory work, delivery and ongoing support.

Salesforce Services Market Insights
- The market reached USD 16.93 billion in 2025 and is projected to rise to USD 67.02 billion by 2035, growing at a 14.75% CAGR during 2026–2035 as AI agent projects add to CRM work.
- North America held 46.0% of global value in 2025, ahead of Europe at 28.0%, because federal, banking and healthcare buyers there run large Salesforce estates.
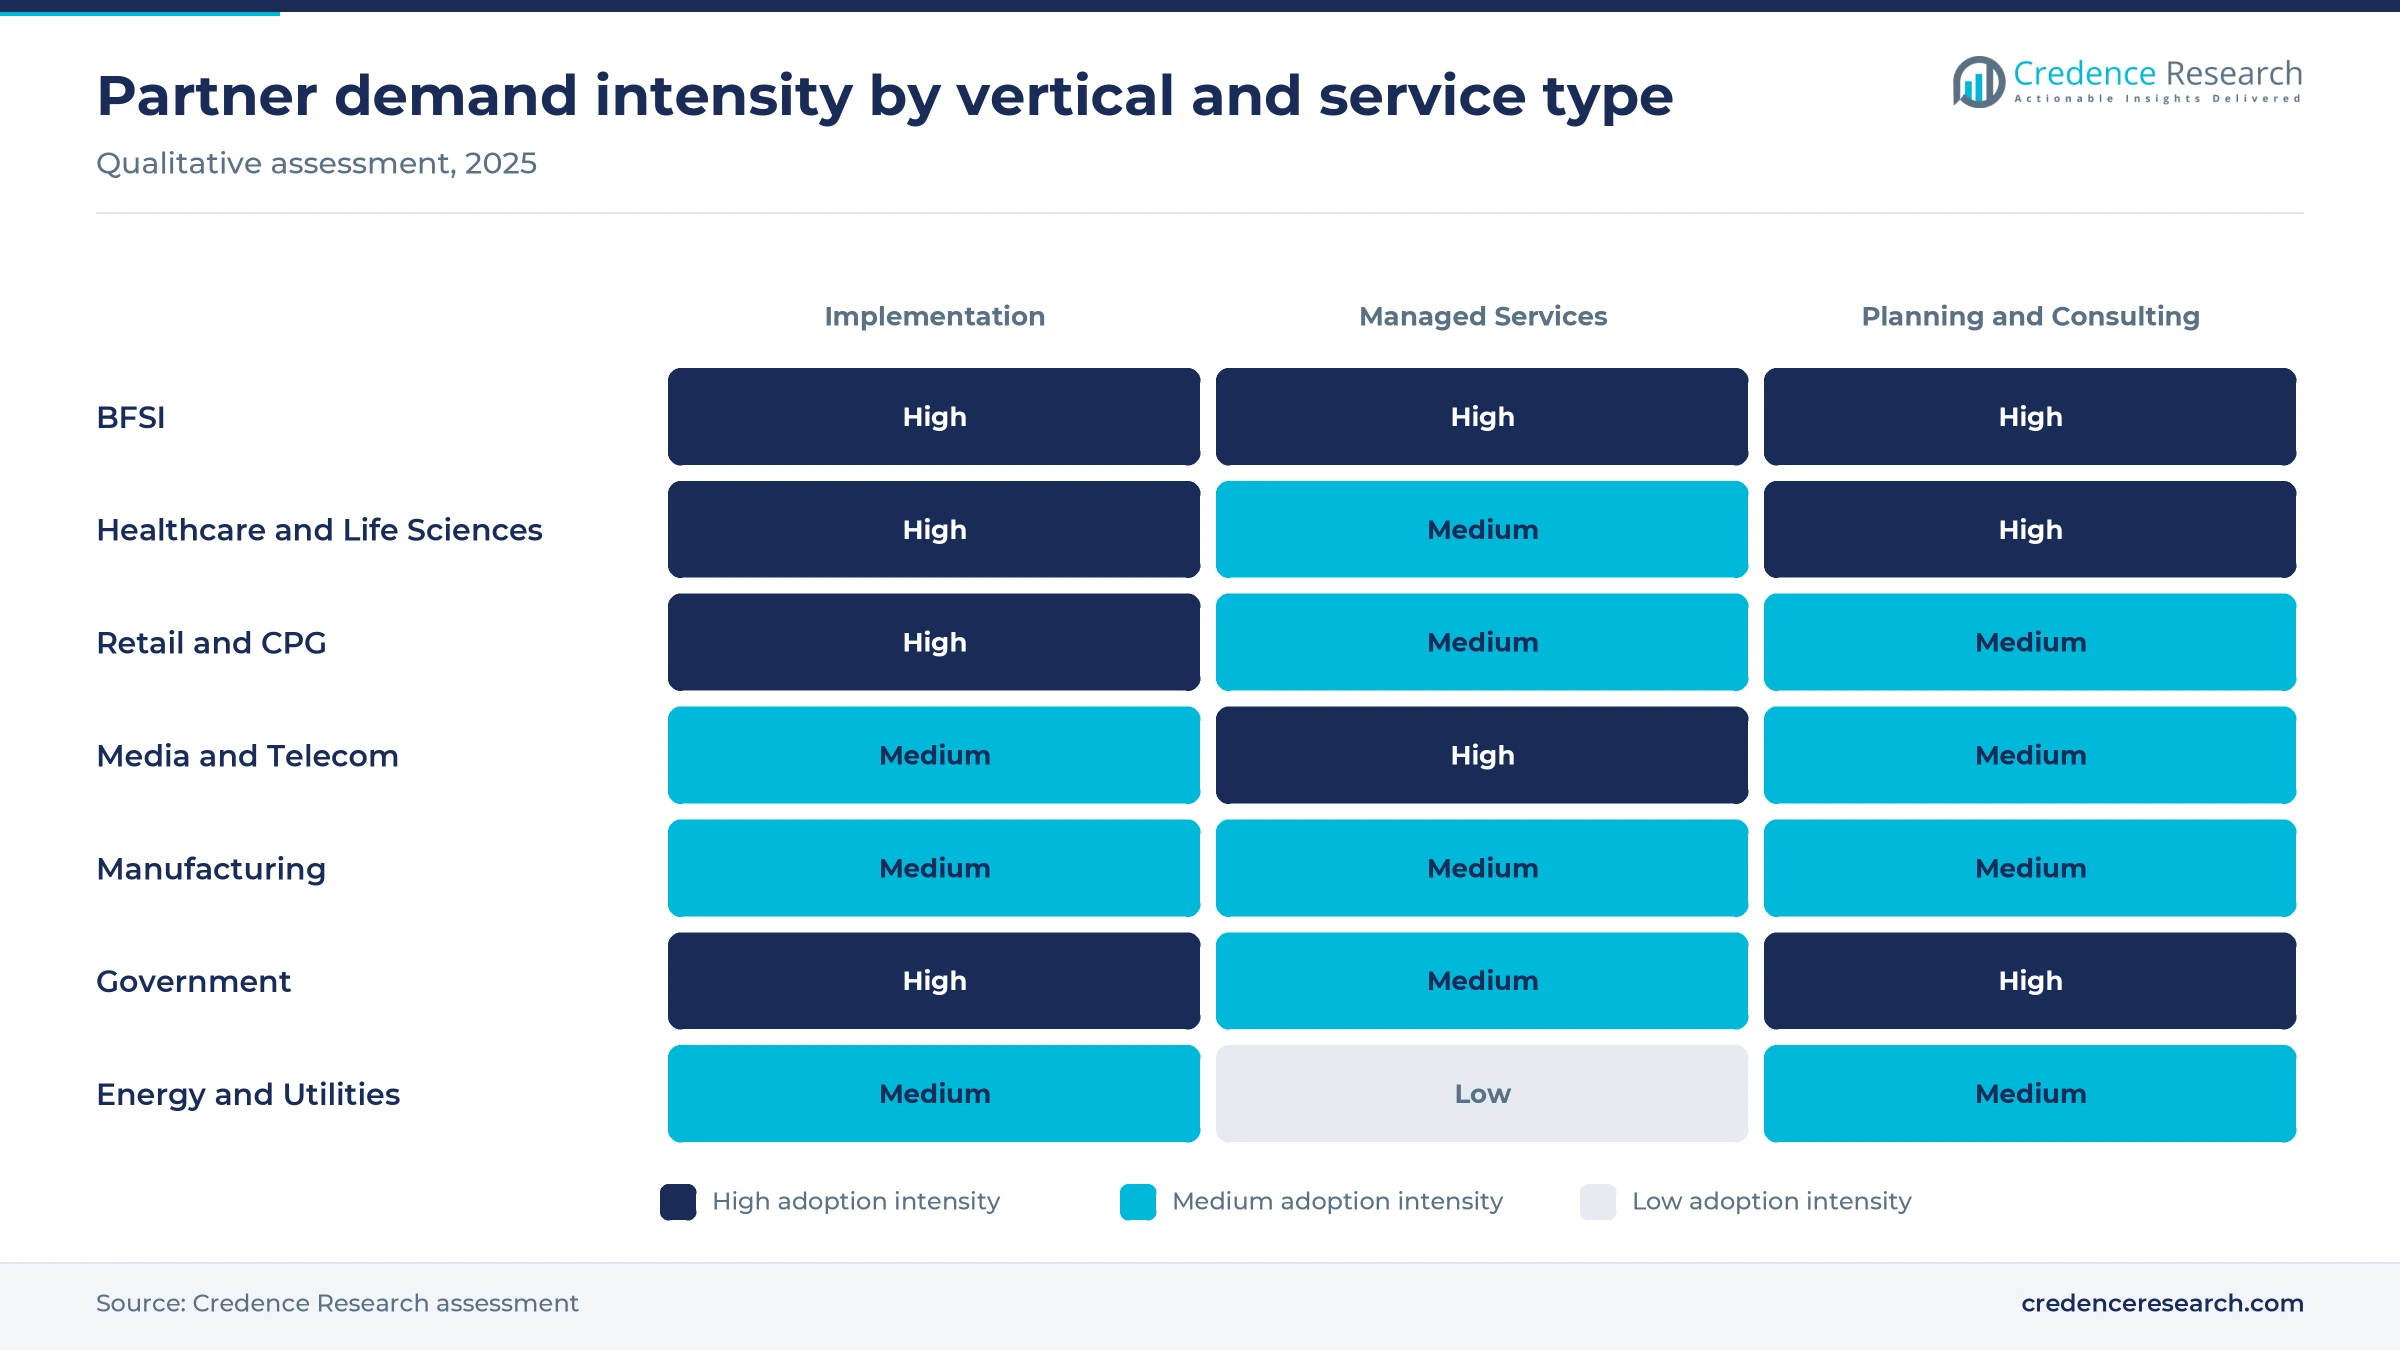
- Implementation led service types with 45.0% of 2025 value, while BFSI led verticals with 24.0% because banks and insurers manage complex, regulated customer data.
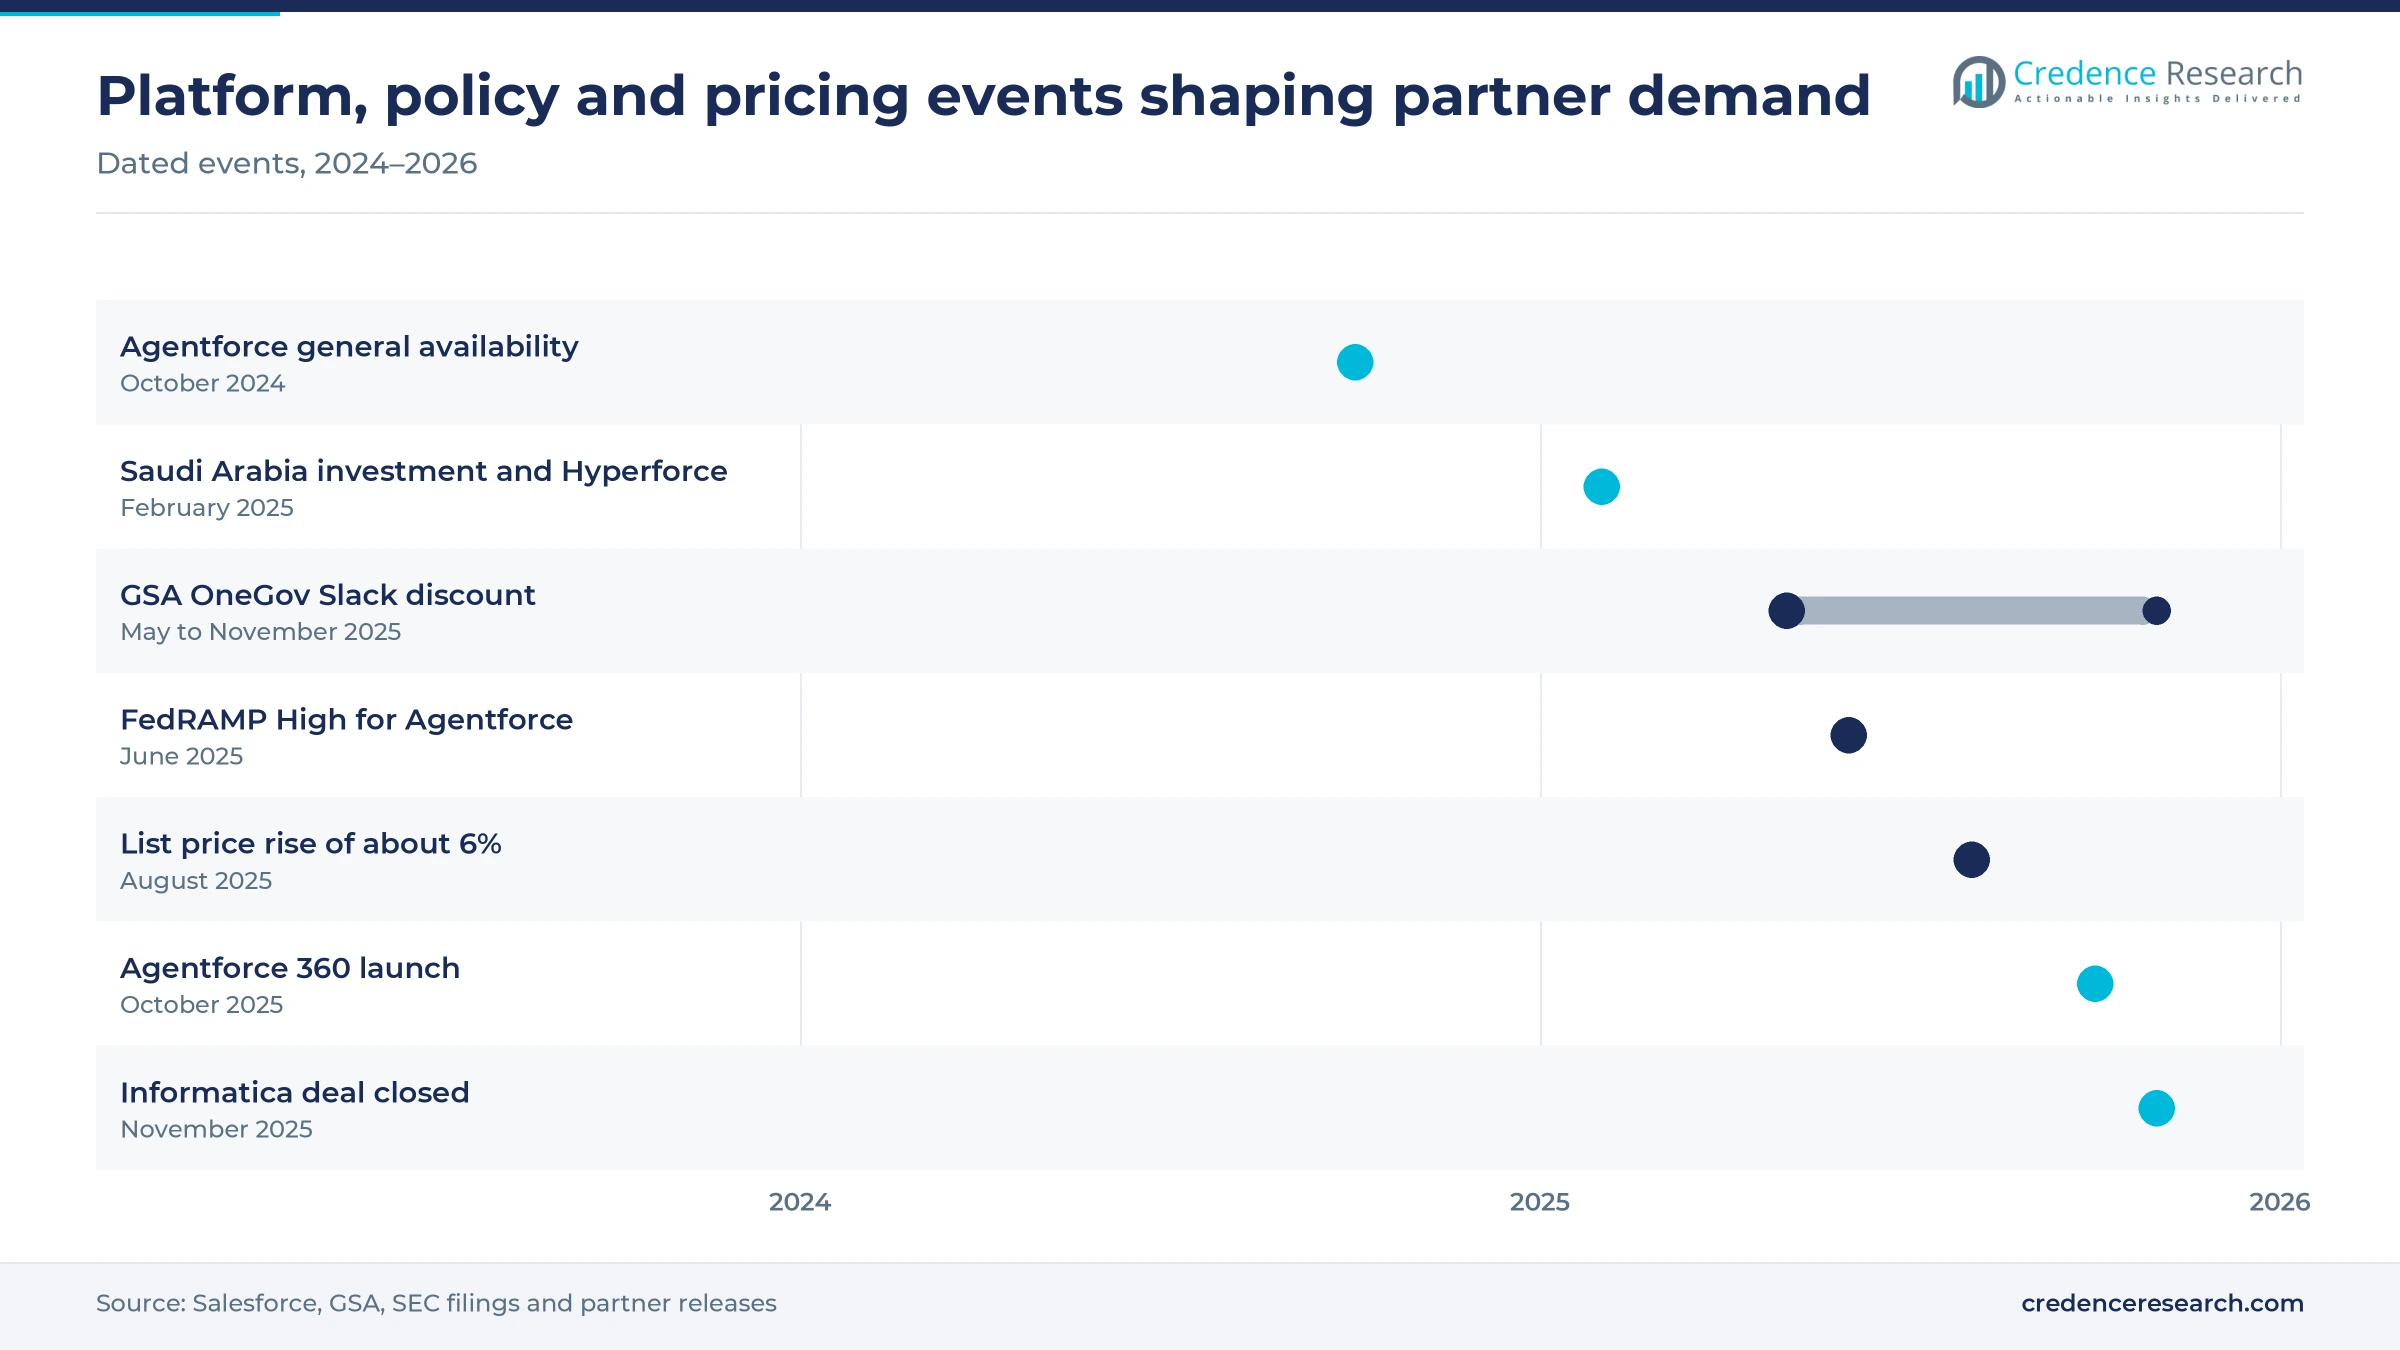
- Salesforce made Agentforce 360 generally available on Oct. 13, 2025 and closed its Informatica purchase on Nov. 18, 2025, widening the data and agent scope partners deliver.
- Global integrators are buying specialist boutiques, as Accenture agreed to acquire NeuraFlash in August 2025 and TCS bought ListEngage in October 2025 to add certified talent.
Implementation and BFSI work carry the most partner value
Why does implementation work carry the most Salesforce partner value?
Based on service type, the market is categorized into implementation, managed services and planning and consulting. Implementation led with 45.0% of 2025 value because every new cloud, data model or agent must be configured, integrated and tested before go-live. NeuraFlash, which Accenture agreed to acquire in August 2025, had completed more than 1,000 implementations for over 400 customers, according to Accenture. Managed Services grow fastest at 15.54% a year, as agents need constant tuning after launch. Salesforce reported that Agentforce accounts in production rose 70% quarter over quarter in the period ended Oct. 31, 2025.
Which industries buy the most Salesforce consulting and delivery?
Based on vertical, the market is categorized into BFSI, healthcare and life sciences, retail and CPG, media and telecom, manufacturing, government, energy and utilities, and others. BFSI led with 24.0% of 2025 value because lenders and insurers combine strict data rules with large service centers. NTT DATA said its Japan Salesforce hub, opened in April 2025, would serve financial clients first before expanding to government and manufacturing. Healthcare and Life Sciences grows fastest at 15.85% a year, as Salesforce made its Life Sciences Cloud customer engagement add-on generally available in October 2025 and announced Novartis as a global customer in December 2025.
How do large enterprises and SMEs buy Salesforce partner work?
Based on organization size, the market is categorized into large enterprises and SMEs. Large Enterprises led with 68.0% of 2025 value because multi-cloud estates need large delivery teams and long support contracts. Eurostat reported that 84.67% of large EU enterprises bought paid cloud services in 2025, against 49.3% of small firms. SMEs grow fastest at 15.42% a year, as packaged editions lower the cost of entry. Salesforce left its Starter, Pro and Foundations editions out of the Aug. 1, 2025 list price rise of about 6%, according to Salesforce Ben, which keeps smaller projects affordable.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Implementation | 45.0% | Managed Services | 15.54% |
| By Vertical | BFSI | 24.0% | Healthcare and Life Sciences | 15.85% |
| By Organization Size | Large Enterprises | 68.0% | SMEs | 15.42% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Agentforce, cloud uptake and public sector approvals
AI agent rollouts create new partner workloads
AI agents are adding a new layer of partner work, because each agent needs data grounding, guardrails, testing and change management. Salesforce made Agentforce generally available on Oct. 30, 2024, and its Dec. 3, 2025 filing reported more than 18,500 Agentforce deals since launch, of which over 9,500 were paid. The same filing counted more than 3.2 trillion tokens processed through its LLM gateway. Cognizant said in June 2025 that it was already implementing Agentforce for more than 25 clients, with about 60% of its Salesforce practice certified in AI specializations. As a result, buyers that once funded one CRM rollout now fund a series of agent projects, and partners that also deliver wider agentic AI programs are winning this work.
Cloud uptake in Europe widens the buyer base
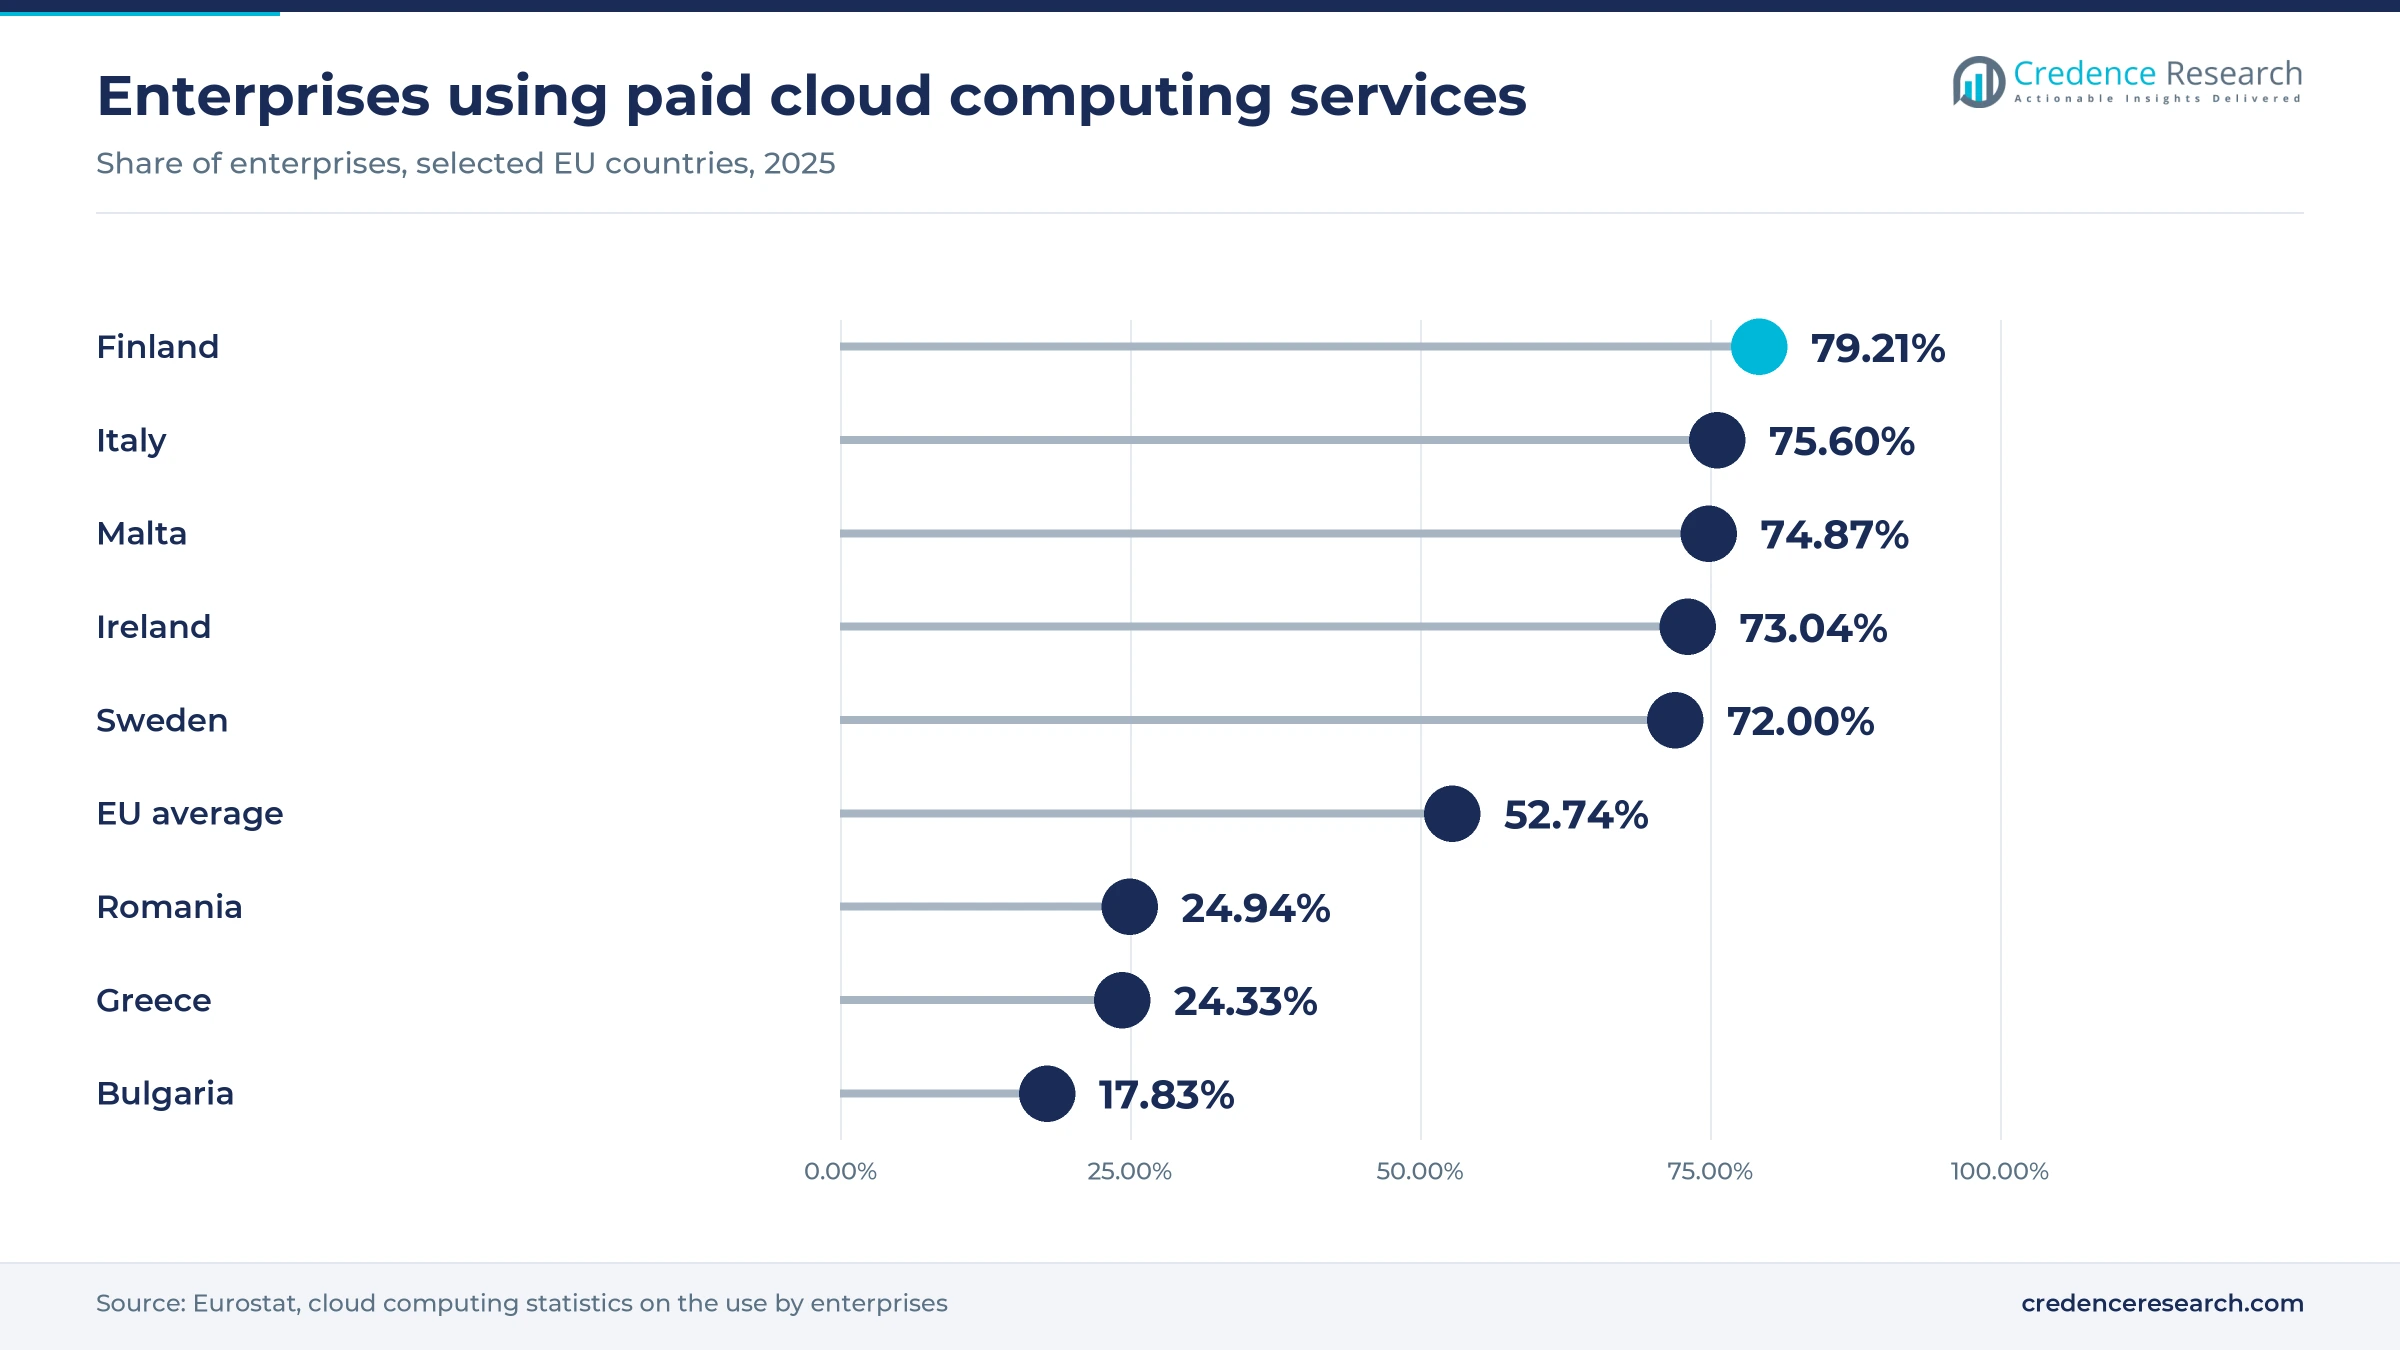
Wider cloud use enlarges the pool of firms that need CRM planning and integration help. Eurostat reported that 52.74% of EU enterprises used paid cloud computing in 2025, and 27.91% of those firms bought CRM applications as a cloud service. Adoption is uneven, since Finland reached 79.21% while Bulgaria stood at 17.83%, which leaves room for growth in eastern and southeastern member states such as Romania, Greece and Bulgaria. Large companies lead the shift, as the same Eurostat release counted 84.67% of large EU enterprises buying paid cloud services. Salesforce also named the U.K. its AI hub for Europe on Sept. 16, 2025, with a USD 6 billion commitment through 2030. In turn, Europe holds 28.0% of 2025 value in this report.
Public sector authorizations open government budgets
Government agencies are becoming larger buyers, because security approvals now allow AI and CRM tools in sensitive workloads. Salesforce said on June 4, 2025 that Agentforce, Data Cloud, Marketing Cloud and Tableau Next had received FedRAMP High authorization. Weeks earlier, Nextgov reported that the GSA and Salesforce agreed on May 19, 2025 to a temporary 90% price cut on Slack Enterprise Grid for federal agencies through Nov. 30, 2025. Salesforce also cited an estimate that agents could unlock up to USD 1 trillion in U.S. federal productivity gains. Agencies still need cleared integrators to move case work onto these platforms, so implementation demand follows each approval. Consequently, government is one of the faster-growing verticals in this report.
Data unification projects follow the Informatica deal
Agents only work when customer data is clean and connected, which turns data integration into a growing share of partner projects. Salesforce completed its acquisition of Informatica on Nov. 18, 2025, adding data catalog, integration, governance, quality and master data management tools to its platform. Salesforce also reported that Data Cloud ingested 32 trillion records in the quarter ended Oct. 31, 2025, up 119% from a year earlier. IBM had announced plans in September 2024 to connect Data Cloud with mainframe and Db2 data, which matters because IBM says more than 70% of global transactions by value run on IBM Z. These steps push buyers to fund data mapping and migration, which helps Implementation keep 45.0% of 2025 value.
Boutique buyouts and packaged industry agents
Integrators shift toward buying specialist boutiques
Large integrators are shifting from organic hiring to buying certified Salesforce boutiques, because agent work needs scarce skills quickly. Accenture said on Aug. 26, 2025 that it would acquire NeuraFlash, bringing about 510 professionals into its Salesforce Business Group from North America, Colombia and India. Tata Consultancy Services followed in October 2025 with ListEngage, a Massachusetts partner with more than 400 Salesforce certifications and over 5,000 completed projects. Deloitte said in March 2025 that it had passed 61,000 Salesforce certifications worldwide. This consolidation raises the bar for mid-size firms, which must specialize by industry or region to compete. As a result, buyers see fewer but larger partners on their shortlists for multi-cloud programs.
Packaged industry agents emerge as partner offerings
Partners are moving from custom builds to packaged industry agents, which shortens projects and makes pricing easier to compare. Wipro announced Agentforce agents for healthcare on March 24, 2025, covering provider onboarding, credentialing and checks of NPI and CAQH data. Infosys launched a Customer Experience Suite for Salesforce on Oct. 10, 2025, and said Finnish research center VTT was among the first organizations outside Salesforce to run a live SDR agent. NTT DATA introduced an industry-ready Agentforce service in June 2025. Deloitte also offers accelerators for financial services, government, life sciences and health care. This packaging favors vertical depth, which is why Healthcare and Life Sciences grows at 15.85% a year in this report.
Asia Pacific talent hubs offer delivery and demand growth
Asia Pacific is an opening for both new buyers and delivery capacity, since local Salesforce communities are expanding quickly. NTT DATA opened a Salesforce hub in Japan in April 2025 with about 1,800 people and plans roughly 5,000 by 2028, alongside a target of about 20,000 Salesforce certifications. Salesforce said on Nov. 25, 2025 that it employs more than 14,000 people across six Indian cities and that its Trailblazer community in India exceeds 3.9 million members. Indian customers named in that release include Air India, Tata Play and Bandhan Bank. Partners that build local language and industry skills can therefore capture demand in the fastest-growing region of this report.
Gulf and Latin American investments open new demand pools
Salesforce investment in the Gulf and Latin America opens new service demand where partner coverage is still thin. Salesforce announced on Feb. 10, 2025 that it plans to invest USD 500 million in Saudi Arabia and bring Hyperforce there through AWS, naming Capgemini, Deloitte, Globant, IBM and PwC as ecosystem partners. Reuters reported in October 2025 that Salesforce will spend USD 1 billion in Mexico over five years, including a Global Delivery Center for customers across the Americas. Local data residency makes regulated buyers more willing to move onto the platform, which needs migration and integration work. As a result, Latin America grows at 15.70% and the Middle East and Africa at 16.10% a year.
Security incidents, license costs and scarce skills
Connected app breaches raise security and audit costs
Third-party integrations have become a security weak point, which adds audit work to every project. Google Threat Intelligence Group reported that the UNC6395 actor used stolen Salesloft Drift OAuth tokens to query Salesforce instances from Aug. 8 to at least Aug. 18, 2025, and it was aware of more than 700 potentially affected organizations, according to The Hacker News. Partners now spend more time reviewing connected apps and token scopes, which lengthens delivery and favors firms with cybersecurity consulting skills.
License price rises squeeze project budgets
Higher license costs leave less room in customer budgets for partner fees. Salesforce raised list prices by an average of 6% on Enterprise and Unlimited editions of Sales Cloud, Service Cloud, Field Service and some industry clouds from Aug. 1, 2025, according to Salesforce Ben. Agentforce add-ons were listed at USD 125 per user per month and Agentforce 1 editions at USD 550. Buyers facing these increases often phase projects or cut scope, which slows new implementation work.
AI automation pressures traditional support contracts
AI agents are reducing the human labor needed for routine support, which threatens hourly managed service models. Fortune reported on Sept. 2, 2025 that Salesforce cut its own support headcount from about 9,000 to about 5,000 because agents now handle roughly half of service interactions. Clients are likely to expect similar savings from partners, so firms that bill by support hours face price pressure and must shift to outcome-based contracts tied to agent performance.
Scarce certified agent skills slow delivery
Skilled Agentforce staff remain scarce, which delays projects and raises day rates for experienced architects. Cognizant said in June 2025 that only about 15% of its Salesforce practice were Agentforce Specialists, even as it served more than 25 Agentforce clients. NTT DATA plans to more than triple its Salesforce certifications in Japan, from about 6,500 to 20,000 by 2028, to close the gap. Smaller partners without training budgets lose bids, while buyers face longer waits for senior talent.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 7.79 | 46.0% | 14.10% |
| Europe | 4.74 | 28.0% | 14.40% |
| Asia Pacific | 3.05 | 18.0% | 16.30% |
| Latin America | 0.76 | 4.5% | 15.70% |
| Middle East & Africa | 0.59 | 3.5% | 16.10% |
North America leads on federal and banking demand
North America held 46.0% of 2025 value and grows at 14.10% a year, the largest regional share in this report. Federal demand strengthened after Agentforce gained FedRAMP High authorization on June 4, 2025, and after the GSA OneGov Slack discount of May 2025. Integrator capacity is also concentrated here, as NeuraFlash of Burlington, Massachusetts, joins Accenture and ListEngage of Framingham joins TCS. As a result, U.S. banks, insurers and agencies have the deepest choice of certified partners for large programs.
Europe grows as cloud use and the U.K. hub expand
Europe held 28.0% of 2025 value and grows at 14.40% a year. Eurostat data show that 52.74% of EU enterprises used paid cloud services in 2025, with Finland at 79.21% and Italy at 75.6%. Salesforce made the U.K. its European AI hub in September 2025, adding research and development teams in London. Regulated buyers in Germany, France and the Nordic countries also need data residency and audit support, which keeps demand for planning and consulting steady across the region.
Asia Pacific grows fastest on Japan and India capacity
Asia Pacific held 18.0% of 2025 value and grows at 16.30% a year, the fastest pace among the five regions. Japan is building scale, as NTT DATA expands its Salesforce hub toward its 2028 staffing targets and plans to extend the model to the wider region. India adds both buyers and delivery capacity, with Salesforce reporting more than 14,000 local employees and 75,000 learners reached by skilling programs in 2025. Infosys, based in Bengaluru, launched its Customer Experience Suite for Salesforce in October 2025.
Latin America gains a new delivery center in Mexico
Latin America held 4.5% of 2025 value and grows at 15.70% a year. Salesforce plans to spend USD 1 billion in Mexico over five years, including a new Mexico City office and a Global Delivery Center for customers across the Americas, according to Reuters. The company has operated in the Mexican market since 2006. NeuraFlash staff in Colombia also join Accenture under the 2025 deal, which adds nearshore capacity for North American clients and for local buyers in Brazil, Mexico and Colombia.
Middle East and Africa build on Saudi cloud investment
The Middle East and Africa held 3.5% of 2025 value and grows at 16.10% a year. Salesforce announced a USD 500 million Saudi Arabia investment at LEAP 2025 in Riyadh on Feb. 10, 2025, with Hyperforce hosted locally through AWS. The plan names Capgemini, Deloitte, Globant, IBM and PwC as ecosystem partners and includes AI learning with Princess Nourah University. Local hosting removes a key barrier for ministries and banks that must keep data in the kingdom.
Platform launches and partner deals of 2025
| Development | Status and market relevance |
|---|---|
| In April 2025, NTT DATA opened a Salesforce hub in Japan with about 1,800 people at launch. | Operating; scales domestic delivery for financial and public sector clients |
| In August 2025, Accenture agreed to acquire NeuraFlash, a Burlington, Massachusetts partner focused on Salesforce and AI. | Announced; adds more than 1,000 completed implementations to the Accenture Salesforce Business Group |
| In October 2025, Salesforce made Agentforce 360 generally available at Dreamforce, combining Agentforce Builder, Agentforce Voice, Slack and Data 360. | Generally available; widens the agent design and integration work partners deliver |
| In October 2025, Tata Consultancy Services acquired ListEngage, a fully remote Salesforce partner based in Framingham, Massachusetts. | Completed; expands TCS Salesforce delivery capacity in North America |
| In November 2025, Salesforce completed its acquisition of Informatica, adding data catalog, integration, governance and master data management tools. | Completed; raises demand for data migration and governance projects |
Agents, unified data and integration shape delivery
- Agentforce lets partners build autonomous agents that resolve cases, qualify leads and update records, with Agentforce Builder used to design and test them in natural language.
- Data 360 unifies customer records from many systems so that agents and analytics work from one profile, which makes data mapping a core partner task.
- MuleSoft and Informatica connect Salesforce to ERP, mainframe and legacy systems, and add data quality, catalog and master data controls.
- Tableau and CRM Analytics give buyers dashboards on pipeline, service and agent performance, which keeps analytics consulting in demand after go-live.
- Hyperforce runs Salesforce on public cloud infrastructure in chosen countries, which helps regulated buyers meet data residency rules in markets such as Saudi Arabia.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global integrators compete on certified talent
Competition is led by global integrators with large certified benches, including Accenture, Deloitte, IBM, Capgemini, Cognizant, NTT DATA, Wipro, Infosys, Tata Consultancy Services and DXC Technology. These firms compete on industry accelerators, offshore delivery cost and the depth of their Agentforce skills rather than on price alone. Deloitte reported more than 61,000 Salesforce certifications in March 2025, and Cognizant said about 60% of its Salesforce practice holds AI specializations. Acquisitions are reshaping the field, with Accenture adding NeuraFlash and TCS adding ListEngage in 2025. Regional boutiques remain strong in mid-market projects, where speed and senior attention matter more than scale. Partner tiers, AppExchange listings and customer references weigh heavily in selection, and buyers increasingly ask for fixed-price agent pilots before signing multi-year programs. Partners that also advise on wider customer relationship management systems choices gain an edge in competitive bids.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Accenture | Global integrator | Runs a Salesforce Business Group and agreed to acquire NeuraFlash in August 2025 |
| Deloitte | Consulting and integration | Holds more than 61,000 Salesforce certifications and offers Agentforce industry accelerators |
| IBM | Consulting and technology | Builds watsonx agents for Agentforce and links Data Cloud to IBM Z and Db2 data |
| Capgemini | Global integrator | Named ecosystem partner for the Salesforce Saudi Arabia expansion |
| Cognizant | IT services | Implements Agentforce for more than 25 clients |
| DXC Technology | IT services | Runs a Salesforce practice with more than 600 projects and 10 global solution centers |
| NTT DATA | IT services | Operates a Japan Salesforce hub and an industry-ready Agentforce service |
| Wipro | IT services | Offers Agentforce agents for healthcare provider onboarding |
| Infosys | IT services | Launched a Customer Experience Suite for Salesforce in October 2025 |
| Tata Consultancy Services | IT services | Acquired Salesforce partner ListEngage in October 2025 |
Outcome-based agent work will decide partner share
Credence Research's view is that the market is moving from one-time CRM rollouts to continuous agent and data programs, which favors partners with industry depth and managed delivery. Salesforce reported more than 9,500 paid Agentforce deals by Oct. 31, 2025, yet many buyers are still in pilots, so the next phase is scaling agents into production. Partners that can prove measurable outcomes, secure connected apps after the 2025 Salesloft Drift incident and price agent work by results should gain share. Firms that rely on hourly support billing face the most pressure as automation lowers ticket volumes.
How Credence Research sized the market
The report uses 2025 as the base year and forecasts the market for 2026 to 2035. Market values come from the Credence Research market model, which was rebased from the earlier edition of this report and checked against public indicators such as Eurostat cloud adoption data, Salesforce filings and partner disclosures. Regional, service type, vertical and organization size splits are Credence Research estimates. Sources used include regulatory filings, government statistics, company press releases and trade press. No interviews or surveys were conducted for this edition of the report.
Agent and data operations set the pace to 2035
By 2035, the market is expected to reach USD 67.02 billion, with agent design, data integration and managed operations making up a larger share of partner work. North America should remain the largest region, while Asia Pacific grows fastest as Japan and India add certified talent. Healthcare and life sciences buyers will lift vertical demand as industry clouds mature. Security reviews, license pricing and skills shortages will slow some programs, yet they also raise the value of experienced partners. Overall, firms that combine Salesforce delivery with data governance and outcome-based pricing are best placed to grow through 2035.
Frequently Asked Questions
How big is the Salesforce services market?
What does the Salesforce consulting service market include?
How large is the Salesforce consulting market in Europe?
Which region leads the Salesforce services market?
Which vertical uses Salesforce services the most?
How is Agentforce changing Salesforce partner work?
Who are the leading Salesforce services providers?
What are the main challenges for Salesforce services providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Implementation
- 1.2.2 Managed Services
- 1.2.3 Planning and Consulting
- 1.3 By Vertical
- 1.3.1 BFSI
- 1.3.2 Healthcare and Life Sciences
- 1.3.3 Retail and CPG
- 1.3.4 Media and Telecom
- 1.3.5 Manufacturing
- 1.3.6 Government
- 1.3.7 Energy and Utilities
- 1.3.8 Others
- 1.4 By Organization Size
- 1.4.1 Large Enterprises
- 1.4.2 SMEs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 16.93 billion → 2035: USD 67.02 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Salesforce Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Salesforce Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Salesforce Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Salesforce Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Salesforce Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Salesforce Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Salesforce Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Salesforce Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 16.93 billion → 2035: USD 67.02 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Salesforce Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Implementation
- 12.3.6.2 Managed Services
- 12.3.6.3 Planning and Consulting
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Vertical - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 BFSI
- 12.4.6.2 Healthcare and Life Sciences
- 12.4.6.3 Retail and CPG
- 12.4.6.4 Media and Telecom
- 12.4.6.5 Manufacturing
- 12.4.6.6 Government
- 12.4.6.7 Energy and Utilities
- 12.4.6.8 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Organization Size - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Large Enterprises
- 12.5.6.2 SMEs
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Salesforce Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Salesforce Services Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Salesforce Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Salesforce Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Accenture
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Deloitte
- 18.4 IBM
- 18.5 Capgemini
- 18.6 Cognizant
- 18.7 DXC Technology
- 18.8 NTT DATA
- 18.9 Wipro
- 18.10 Infosys
- 18.11 Tata Consultancy Services
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

