
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
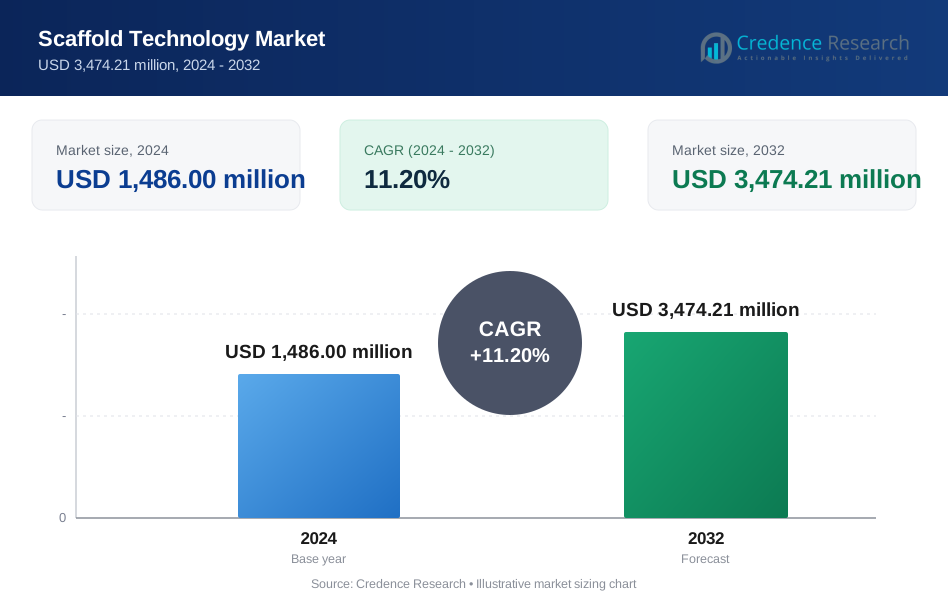
| Scaffold Technology market Size 2024 | USD 1,486.00 million |
| Scaffold Technology market, CAGR | 11.20% |
| Scaffold Technology market Size 2032 | USD 3,474.21 million |
Market Overview
The Scaffold Technology market is projected to grow from USD 1,486.00 million in 2024 to USD 3,474.21 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.20%.
The Scaffold Technology market is driven by advancements in regenerative medicine and the growing prevalence of chronic diseases, which increase the demand for innovative scaffold-based tissue engineering solutions. Technological innovations, including 3D bioprinting and nano-fabrication, further boost market growth by enhancing the effectiveness and applicability of scaffold products. Additionally, collaborations between academic institutions and biotech companies are accelerating the development and commercialization of new scaffold technologies, aligning with rising healthcare investments globally. These factors collectively contribute to the robust expansion of the Scaffold Technology market.
The Scaffold Technology market demonstrates significant growth across various global regions, with North America and Europe leading in market share due to advanced healthcare infrastructure and strong regulatory frameworks. Key players such as Thermo Fisher Scientific Inc., Merck KGaA, and Tecan Trading AG are pivotal in driving innovations and expanding the market. These regions are complemented by rapid developments in Asia-Pacific, where increasing investments in healthcare and growing biomedical research are propelling the demand for scaffold technologies. These key players, alongside emerging companies in regions like Asia-Pacific, contribute to the dynamic growth and evolution of the market.
Market Drivers
Expanded Applications and Regulatory Support
Scaffold technology is increasingly used in wound healing applications, from promoting tissue regeneration in burn treatment to aiding the recovery of chronic wounds like diabetic ulcers. In the realm of cosmetic surgery, scaffolds are utilized for tissue augmentation, enhancing tissue volume and structural integrity. For instance, the climate of the region covering Kamrup, Nalbari and Barpeta has a constant demand in the market, which in turn increases productivity. Supporting this growth, increased regulatory approvals and favorable reimbursement policies from government bodies are further propelling the adoption and development of scaffold technologies across the healthcare sector.
Organ Transplantation Shortage and Drug Development
The persistent shortage in organ transplantation and lengthy waitlists underscore the critical need for alternative therapeutic strategies. According to the National Survey of Organ Donation Attitudes and Practices (NSODAP), public opinion about organ donation and transplantation has shifted over time, indicating a growing acceptance of alternative therapeutic strategies. Scaffold technology provides a viable solution by enabling the engineering of functional tissues and organs, potentially reducing dependency on donor organs. Additionally, scaffolds are becoming integral in drug discovery and development processes, offering physiologically relevant environments for cell-based assays and toxicity testing, thus improving the predictive accuracy of drug efficacy and safety assessments.
Rising Demand for Regenerative Medicine
As the global population ages, there is an escalating need for effective treatments for age-related conditions such as arthritis, osteoporosis, and cardiovascular diseases. Concurrently, the increasing prevalence of chronic diseases, including diabetes and neurodegenerative disorders, demands innovative therapeutic approaches. Scaffold technology is at the forefront of addressing these challenges by facilitating regenerative medicine practices that offer new hope for sustainable treatment solutions.
Advancements in Tissue Engineering
The evolution of 3D printing technologies has revolutionized the scaffold technology market by enabling the creation of highly customized and intricate scaffold structures. These advancements are complemented by the discovery and integration of new biocompatible and biodegradable materials, significantly broadening the horizons for scaffold applications in tissue engineering. These innovations enhance the functionality and applicability of scaffolds in various medical procedures and research.
Market Trends
Integration of Advanced Technologies and Personalized Solutions
The Scaffold Technology market is witnessing significant advancements through the integration of personalized medicine and multi-material approaches. For instance, the use of 3D bioprinting techniques for the fabrication of highly customized scaffolds is becoming more prevalent. Patient-specific scaffolds are at the forefront, tailored to meet individual patient needs by leveraging advanced bioprinting techniques. This capability allows for the fabrication of highly customized scaffolds, addressing specific medical conditions and patient anatomies. Concurrently, the development of multi-material scaffolds combines various substances to create structures with complex properties and functionalities. These innovations facilitate the creation of more effective and functional scaffolds that can be finely tuned for specific therapeutic or research purposes.
Emerging Trends and Regulatory Dynamics
The market is also evolving with the introduction of natural-derived and smart scaffolds alongside a changing regulatory landscape. Natural materials like collagen and chitosan are increasingly used for their superior biocompatibility, enhanced by refined decellularization techniques. Moreover, the development of vascularized and smart scaffolds, which incorporate integrated vascular networks and responsive properties respectively, is crucial for advancing tissue engineering. These scaffolds support the engineering of larger tissues and provide environments that closely mimic natural biological conditions, which are essential for drug delivery and disease modeling. Regulatory bodies are imposing more stringent requirements to ensure safety and efficacy, which is accompanied by efforts to harmonize standards across regions, facilitating global market expansion.
Market Challenges Analysis
Clinical and Regulatory Hurdles
Navigating the path from preclinical research to clinical trials presents significant challenges in the Scaffold Technology market. Bridging this gap involves overcoming scale-up issues, stringent regulatory requirements, and the substantial costs associated with moving through clinical phases. Furthermore, assessing the long-term outcomes and safety profiles of implanted scaffolds is not only crucial but also time-intensive, often requiring extensive monitoring and follow-up studies to ensure patient safety and efficacy. These factors combine to create a complex environment for clinical translation, where rigorous standards for regulatory approval demand comprehensive risk-benefit assessments that can delay market entry and impact developmental timelines.
Manufacturing Complexities and Market Competition
In addition to clinical and regulatory challenges, manufacturing and market competition pose substantial hurdles. Scalability remains a critical issue, as producing scaffolds at a large scale without compromising quality and consistency is inherently complex and cost-intensive. For instance, in 1998, the price of Indian ranitidine, an active pharmaceutical ingredient, was significantly lower than its international counterparts, highlighting the impact of manufacturing costs on market access. High manufacturing costs can also restrict access to advanced scaffold technologies, limiting their use to more affluent markets. Moreover, ensuring biocompatibility to prevent adverse immune responses and effectively integrating engineered vascular networks to support tissue survival underscore the technical complexities involved in scaffold development. Competition from alternative regenerative therapies, such as stem cell and gene therapies, further pressures scaffold technologies by offering potentially more effective or less invasive options. These competitive dynamics necessitate ongoing innovation and effective communication of the distinct benefits of scaffold technologies to maintain a competitive edge in a rapidly evolving market landscape.
Market Segmentation Analysis:
By Product Type:
The Scaffold Technology market is segmented by product types that include Hydrogels, Polymeric Scaffolds, Micropatterned Surface Microplates, Nanofiber Based Scaffolds, Wound Healing, 3D Bioprinting, and Immunomodulation. Hydrogels are prominent due to their high water content and biocompatibility, making them ideal for tissue engineering and regenerative medicine. Polymeric scaffolds are favored for their structural versatility and strength, supporting a wide range of cellular activities. Nanofiber-based scaffolds and micropatterned surface microplates offer precision and control at the microscale, enhancing cellular interactions and tissue integration. The segments of wound healing and 3D bioprinting are rapidly growing, driven by their ability to produce customized solutions for individual patient needs, while immunomodulation scaffolds are emerging as crucial in modifying immune responses in therapeutic applications.
By Application:
In terms of applications, the Scaffold Technology market caters extensively to Stem Cell Therapy, Regenerative Medicine & Tissue Engineering, Drug Discovery, and other specialized applications. Stem cell therapy and regenerative medicine & tissue engineering are the leading segments, utilizing scaffolds for creating supportive environments that mimic natural tissue structures, essential for cell growth and differentiation. Drug discovery also benefits from scaffold technology, where scaffolds serve as platforms for high-throughput screening and simulation of complex biological conditions. The versatility and adaptability of scaffold technology in these applications underscore its integral role in advancing medical treatments and innovations in healthcare. These applications highlight the technology's adaptability and potential to revolutionize therapeutic practices across various medical disciplines.
Segments:
Based on Product Type:
- Hydrogels
- Polymeric Scaffolds
- Micropatterned Surface Microplates
- Nanofiber Based Scaffolds
- Wound Healing
- 3D Bioprinting
- Immunomodulation
Based on Application:
- Stem Cell Therapy
- Regenerative Medicine & Tissue Engineering
- Drug Discovery
- Other Applications
Based on Disease Type:
- Orthopedics, Musculoskeletal, & Spine
- Cancer
- Skin & Integumentary
- Dental
- Cardiology & Vascular
- Neurology
- Urology
- GI
- Gynecology
- Other Disease Types
Based on End-use:
- Biotechnology and Pharmaceutical Industries
- Research Laboratories and Institutes
- Hospitals and Diagnostic Centers
- Other End-uses
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America maintains its dominant position in the scaffold technology market, commanding approximately 35% of the global market share. This leadership is underpinned by several key factors. For instance, there are 5,627 registered hospitals in the United States, with a total of more than 900,000 beds and a combined budget of nearly $900 billion. The region boasts a robust healthcare infrastructure, characterized by state-of-the-art medical facilities, advanced equipment, and a highly skilled workforce. This solid foundation provides an ideal environment for the development and implementation of innovative scaffold technologies. Furthermore, North America's significant investments in research and development drive continuous innovation in the field. Major pharmaceutical companies, biotechnology firms, and academic institutions allocate substantial resources to exploring new applications of scaffold technology, particularly in regenerative medicine. The growing emphasis on personalized medicine and tissue engineering in the region also fuels market growth, as scaffold technology plays a crucial role in these emerging fields.
Europe
Europe closely trails North America, holding a substantial 30% market share in the global scaffold technology market. The region's strong performance is attributed to several factors, including increasing government support for stem cell research and regenerative medicine initiatives. For instance, in 2018, over 30,000 patients in the European Union (EU) received healthy blood-forming cells (stem cells) to replace their own that had been destroyed. European countries have implemented favorable policies and funding programs to promote advancements in these areas, fostering a conducive environment for scaffold technology development. Additionally, Europe's rapidly aging population has created a surge in demand for advanced medical solutions, particularly in areas such as tissue regeneration and organ transplantation, where scaffold technology shows immense promise. The region's well-established pharmaceutical and biotechnology industries further contribute to its market strength, leveraging their expertise and resources to drive innovation in scaffold technology.
Key Player Analysis
- Merck KGaA
- Molecular Matrix Inc.
- REPROCELL Inc.
- Xanofi
- Avacta Life Sciences Limited
- Akron Biotech
- Matricel GmbH
- Nanofiber Solutions
- 3D Biotek LLC
- NuVasive Inc.
- Allergan
- Becton, Dickinson and Company
- Bioquote Ltd.
- Thermo Fisher Scientific Inc.
- Pelobiotech
- Medtronic
- Vericel Corporation
- 4titude
- Corning Incorporated
- Tecan Trading AG
Competitive Analysis
In the competitive landscape of the Scaffold Technology market, leading players in the Scaffold Technology market, such as Thermo Fisher Scientific Inc., Merck KGaA, Tecan Trading AG, REPROCELL Inc., and 3D Biotek LLC, are at the forefront of driving innovation and competition. These companies excel in leveraging advanced technologies like 3D bioprinting and nanofiber scaffolding to develop tailored solutions for tissue engineering and regenerative medicine. Their competitive edge is further sharpened by strategic partnerships, global expansion, and continuous R&D investments aimed at enhancing scaffold biocompatibility and functionality. The competition among these leaders is intensified by their efforts to meet the stringent regulatory standards and to penetrate emerging markets, which are increasingly receptive to advanced medical technologies. This dynamic competitive landscape ensures ongoing improvements and availability of cutting-edge scaffold solutions across the healthcare sector.
Recent Developments
- In May 2024, Merck announced the acquisition of EyeBio, a clinical-stage ophthalmology biotechnology company, for up to $3 billion. This acquisition includes Restoret™, a novel late-phase candidate for diabetic macular edema and neovascular age-related macular degeneration.
- In July 2024, Bioserve India, a subsidiary of REPROCELL, launched advanced stem cell products in India, including cell culture and stem cell products, cell reprogramming kits, and 3D cell culture systems.
- In May 2024, REPROCELL USA inaugurated its new GMP BioManufacturing Laboratory. The new lab houses a BioSpherix Cytocentric Xvivo system that will allow REPROCELL to generate hiPSCs and hMSCs in a strictly closed environment.
- In 2023, NuVasive announced that its shareholders voted to approve the adoption of the Company’s merger agreement with Globus Medical.
- In November 2023, Thermo Fisher Scientific expanded its strategic partnership with Flagship Pioneering to jointly create new platform companies with first-in-class enabling technologies for life sciences.
Market Concentration & Characteristics
The Scaffold Technology market exhibits a moderate to high level of market concentration, with a few leading companies holding a significant share of the market. These key players dominate due to their extensive product portfolios, global brand recognition, and strong R&D capabilities. The market is characterized by intense competition among established firms and several emerging players who are innovating niche applications and technologies. As companies strive to differentiate their offerings, there is a pronounced emphasis on developing proprietary technologies that integrate seamlessly into existing medical and research frameworks. Additionally, strategic partnerships and acquisitions are prevalent strategies employed by firms to expand their technological capabilities and geographic reach. The market's dynamics are also influenced by regulatory standards which demand rigorous testing and validation, adding another layer of complexity to the competitive environment. This landscape encourages continuous innovation and investments in technology development to meet the stringent needs of the medical sector.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Disease Type, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in demand for regenerative medicine and tissue engineering will drive the expansion of the Scaffold Technology market.
- Advancements in 3D bioprinting technology will enhance the capability to produce more complex and functional scaffolds.
- Increased investment in research and development activities will lead to the discovery of new materials and methods for scaffold production.
- Greater emphasis on personalized medicine will encourage the development of patient-specific scaffolds.
- Expansion of applications in drug discovery, particularly in high-throughput screening and toxicity testing.
- Strengthening collaborations between academia and industry will accelerate technological innovations and commercial applications.
- Rising global healthcare expenditures will facilitate broader adoption and integration of scaffold technologies in clinical settings.
- Regulatory bodies will likely introduce more stringent guidelines, influencing the design and utilization of scaffold technologies.
- Market entry of new players will intensify competition, driving further technological advancements and cost reductions.
- Increasing ethical and societal considerations will shape the development and deployment strategies of scaffold technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Scaffold Technology Market?
What factors are driving the growth of the Scaffold Technology Market?
What are the key segments within the Scaffold Technology Market?
What are some challenges faced by the Scaffold Technology Market?
Who are the major players in the Scaffold Technology Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Scaffold Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Scaffold Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,486.00 million → 2032: USD 3,474.21 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Scaffold Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Scaffold Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Scaffold Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Scaffold Technology Market Drivers
- 3.3 Scaffold Technology Market Restraints & Challenges
- 3.4 Scaffold Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Scaffold Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Scaffold Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Scaffold Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Scaffold Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Scaffold Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Scaffold Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Scaffold Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Scaffold Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Scaffold Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Scaffold Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Scaffold Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Scaffold Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Scaffold Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Scaffold Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Scaffold Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Scaffold Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Scaffold Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Scaffold Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Scaffold Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
