
Market Overview
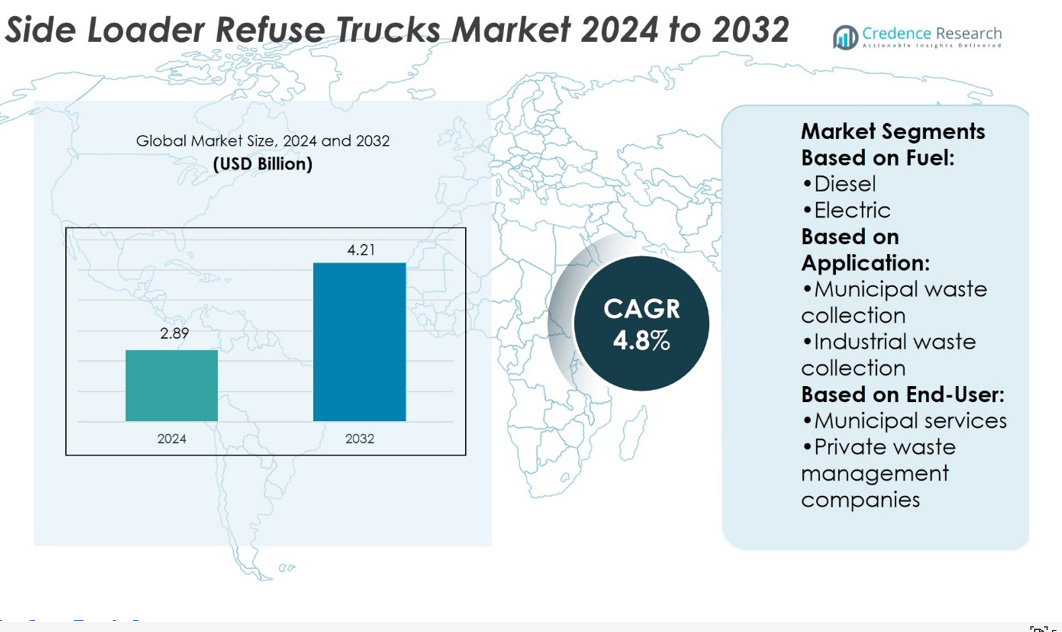
Side Loader Refuse Trucks Market size was valued at USD 2.89 billion in 2024 and is anticipated to reach USD 4.21 billion by 2032, at a CAGR of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Side Loader Refuse Trucks Market Size 2024 | USD 2.89 billion |
| Side Loader Refuse Trucks Market, CAGR | 4.8% |
| Side Loader Refuse Trucks Market Size 2032 | USD 4.21 billion |
The Side Loader Refuse Trucks Market grows through strong drivers and evolving trends shaped by urbanization, sustainability goals, and technological innovation. Rising municipal waste volumes push adoption of automated trucks that reduce labor needs and improve efficiency. Regulatory pressure on emissions accelerates demand for electric, hybrid, and CNG-powered models. Telematics and IoT integration enhance fleet performance, route optimization, and predictive maintenance. Operators also prioritize safety and ergonomics, influencing design improvements. Growing investments in smart city projects and public-private partnerships further strengthen opportunities, while automation and eco-friendly technologies define long-term growth directions for the global side loader refuse trucks industry.
North America leads the Side Loader Refuse Trucks Market with strong adoption supported by advanced infrastructure, while Asia Pacific shows the fastest growth driven by urbanization and government initiatives. Europe maintains significant share with strict emission regulations and sustainable fleet investments. Latin America and Middle East & Africa record smaller yet expanding adoption through urban projects. Key players shaping the market include Bridgeport Manufacturing, Mack Trucks, Dennis Eagle, Amrep, Peterbilt, Labrie Trucks, Heil, McNeilus Truck, New Way Refuse Trucks, and Autocar.
Market Insights
- Side Loader Refuse Trucks Market was valued at USD 2.89 billion in 2024 and will reach USD 4.21 billion by 2032 at a CAGR of 4.8%.
- Urbanization and rising municipal waste volumes drive adoption of automated trucks that improve efficiency.
- Sustainability goals and emission rules push demand for electric, hybrid, and CNG-powered side loader models.
- Competition focuses on innovation, with players investing in automation, telematics, and ergonomic designs.
- High initial costs and infrastructure limitations act as restraints, slowing adoption in developing regions.
- North America leads with strong infrastructure, Asia Pacific grows fastest with government support, Europe expands through sustainability mandates, while Latin America and Middle East & Africa record gradual growth.
- Key companies such as Bridgeport Manufacturing, Mack Trucks, Dennis Eagle, Amrep, Peterbilt, Labrie Trucks, Heil, McNeilus Truck, New Way Refuse Trucks, and Autocar shape the competitive landscape.
Market Drivers
Rising Demand for Efficient Waste Collection in Urban Areas
Rapid urbanization drives municipalities to adopt advanced waste collection solutions. The Side Loader Refuse Trucks Market benefits from the need for streamlined, space-efficient operations in crowded cities. Side loaders reduce manual labor by allowing automated or semi-automated loading of bins. It helps municipalities meet waste management targets while improving safety for operators. Cities facing limited budgets also focus on cost efficiency, favoring vehicles with higher productivity. Expanding urban populations continue to generate higher volumes of waste, reinforcing demand for these trucks.
- For instance, Mack Trucks has surpassed a milestone of 200,000 Class 8 trucks built with its proprietary telematics gateway since 2014. This confirms the active truck figure cited.
Shift Toward Automation and Technological Integration
Automation plays a central role in boosting adoption of side loader refuse trucks. These vehicles integrate robotic arms and sensor-based guidance to increase collection speed. The Side Loader Refuse Trucks Market grows with municipalities investing in technologies that minimize manual intervention. It reduces accident risk and enhances route optimization, enabling smoother operations. Advanced telematics and IoT features also support predictive maintenance and fleet management. Truck manufacturers develop models that combine automation with fuel efficiency, making them attractive to operators.
- For instance, Dennis Eagle introduced the Olympus Midi in April 2025 for narrow urban streets. It offers 9.8 m³, 10.8 m³, and 11.8 m³ body capacities. The vehicle’s 3.25 m wheelbase and 2,350 mm width boost maneuverability in tight spaces.
Emphasis on Sustainability and Environmental Regulations
Governments enforce stricter emission norms, encouraging investment in sustainable waste collection vehicles. The Side Loader Refuse Trucks Market responds with electric and hybrid variants that meet compliance standards. It supports cities in lowering carbon footprints while maintaining operational efficiency. Waste management firms prefer vehicles that align with sustainability goals and reduce lifecycle costs. Development of energy-efficient hydraulic systems further improves environmental performance. Green initiatives across regions continue to accelerate adoption of eco-friendly refuse trucks.
Expansion of Municipal and Private Sector Waste Management Contracts
Rising outsourcing of waste collection to private operators boosts market demand. Municipalities issue long-term contracts that require reliable, high-capacity trucks. The Side Loader Refuse Trucks Market benefits from the need for fleet upgrades in response to these contracts. It enables operators to improve service delivery and comply with contractual performance benchmarks. Large-scale residential and commercial projects also create steady demand for side loaders. Growth in public-private partnerships ensures continuous investment in waste management fleets.
Market Trends
Growing Adoption of Automated Collection Systems
Automation trends dominate the waste management industry with rising preference for smart trucks. The Side Loader Refuse Trucks Market advances through integration of robotic arms, automatic bin lifters, and sensor-based operations. It supports faster collection cycles while reducing physical strain on workers. Automated systems improve precision in handling varied container sizes, enhancing service efficiency. Municipalities and private operators favor automation for consistent performance in high-density urban areas. The shift toward mechanization sets a strong direction for future fleet investments.
- For instance, Amrep advertises that its automated side loaders can handle between 800 and 1,200 homes per route, depending on route density and landfill proximity. The figure of "up to 1,200 homes per route" is directly supported by this information.
Increasing Penetration of Electric and Hybrid Models
Sustainability goals push manufacturers to introduce eco-friendly refuse truck models. The Side Loader Refuse Trucks Market evolves with growing adoption of electric and hybrid variants. It aligns with regulatory requirements and helps operators reduce operational emissions. Battery technology improvements extend range and allow reliable deployment in municipal routes. Hybrid models also balance fuel efficiency and performance, lowering long-term costs. Urban governments encourage procurement of such vehicles through incentive programs and clean fleet policies.
- For instance, Peterbilt’s Model 520EV delivers 670 hp, supports a GCWR of 66,000 lbs, and handles up to 1,100 bin pickups (≈80–120 miles) on a single charge. It also charges fully in about 3 hours, featuring regenerative braking for added efficiency.
Integration of Telematics and Digital Fleet Management Tools
Digitalization transforms waste collection by enabling data-driven decision-making. The Side Loader Refuse Trucks Market incorporates telematics, GPS tracking, and real-time monitoring tools. It allows fleet operators to optimize routing, reduce idle time, and improve fuel efficiency. Predictive maintenance supported by IoT integration reduces downtime and service interruptions. Digital tools also provide municipalities with performance analytics for contract management. Growing reliance on connected technologies ensures smarter operations and higher customer satisfaction.
Focus on Ergonomic and Safety Enhancements
Operator safety and comfort remain critical factors influencing product innovation. The Side Loader Refuse Trucks Market emphasizes design improvements such as advanced cabin ergonomics and visibility systems. It reduces fatigue and enhances operational safety in urban environments. Automated loading arms further minimize direct worker contact with waste, lowering health risks. Truck makers also integrate advanced braking systems and stability features to prevent accidents. Safety-focused design trends continue to strengthen adoption across both municipal and private sectors.
Market Challenges Analysis
High Initial Costs and Maintenance Burden
The Side Loader Refuse Trucks Market faces challenges due to high acquisition and maintenance costs. Advanced automation systems, telematics, and eco-friendly powertrains raise upfront expenses for operators. It limits adoption among smaller municipalities and private contractors with budget restrictions. Ongoing maintenance of hydraulic systems, robotic arms, and digital sensors further increases operating costs. Spare parts and skilled technicians are also expensive, impacting long-term profitability. The cost barrier slows fleet modernization in emerging economies where funding is limited.
Infrastructure Limitations and Regulatory Compliance
Deployment of side loader refuse trucks is restricted by inadequate infrastructure in many regions. Narrow roads, irregular bin placement, and limited charging stations hinder efficient use of these vehicles. The Side Loader Refuse Trucks Market also struggles with evolving emission and safety regulations that vary across countries. It forces manufacturers to design multiple variants, increasing production complexity and costs. Operators face compliance challenges while transitioning fleets to meet stricter sustainability standards. Infrastructure gaps combined with regulatory uncertainty continue to constrain market expansion.
Market Opportunities
Expansion of Smart Waste Management Initiatives
Smart city projects and digital waste management programs create strong opportunities for advanced vehicles. The Side Loader Refuse Trucks Market gains traction from demand for trucks equipped with automation, sensors, and telematics. It supports municipalities in achieving efficiency targets while improving service reliability. Integration with data-driven platforms allows real-time monitoring, route optimization, and predictive maintenance. Public-private partnerships in waste management further accelerate fleet upgrades with smart capabilities. Growth of urban populations ensures steady demand for high-performance side loaders.
Rising Demand for Eco-Friendly and Electric Variants
Global sustainability commitments open pathways for electric and hybrid refuse trucks. The Side Loader Refuse Trucks Market benefits from government incentives and clean fleet policies encouraging adoption. It enables operators to reduce emissions, meet strict regulations, and align with carbon reduction goals. Battery technology improvements increase operational range, making electric side loaders more viable for urban routes. Hybrid solutions provide balance between fuel efficiency and performance, appealing to cost-sensitive buyers. Expansion of charging infrastructure strengthens prospects for wider deployment in developed and emerging markets.
Market Segmentation Analysis:
By Fuel
The Side Loader Refuse Trucks Market segments by fuel into diesel, electric, CNG, hybrid, and others. Diesel trucks maintain a dominant position due to established infrastructure and proven reliability in long routes. It remains a preferred option in regions where alternative fuel access is limited. Electric trucks gain strong traction as municipalities adopt zero-emission fleets supported by incentives and stricter emission norms. CNG-powered models find steady demand in countries with natural gas infrastructure, offering lower emissions and cost savings. Hybrid trucks bridge efficiency and sustainability, appealing to operators seeking transitional options. Other fuels, including biofuels and LNG, serve niche applications and support localized green initiatives.
- For instance, Curbtender’s PowerPak ASL achieves a high compaction rating of 1,000 pounds per cubic yard, with pack cycles completed in 16–20 seconds. Its 2,000-pound-capacity Power Arm lifts standard 300-gallon containers and includes a 5-year structural warranty.
By Application
Application-based segmentation covers municipal, industrial, commercial, and construction and demolition waste collection. Municipal waste collection accounts for the largest share due to urbanization and rising population density. The Side Loader Refuse Trucks Market benefits from large city contracts that require automated, high-capacity trucks. It supports municipalities in achieving efficient daily waste collection while meeting environmental goals. Industrial waste collection demands robust models capable of handling heavy and hazardous loads. Commercial waste collection emphasizes efficiency and flexibility in servicing retail, hospitality, and office facilities. Trucks designed for construction and demolition waste focus on durability and high-volume handling.
- For instance, Dennis Eagle’s purpose-built ProView chassis supports municipal and specialized fleets. It offers a best-in-class turning circle as small as 66.7 feet (curb-to-curb), aiding tight urban navigation.The low-entry cab has an 18.4‑inch ground-to-step height, flat walkthrough floor, and panoramic windows-ideal for crew safety and better driver visibility.
By End User
End users include municipal services, private waste management companies, specialized waste handlers, and others. Municipal services dominate adoption with strong investments in automated fleets and sustainability-driven procurement. It helps governments meet regulatory compliance while improving collection efficiency. Private waste management companies expand their fleets to secure long-term contracts from both public and commercial clients. Specialized waste handlers adopt side loaders for sectors such as healthcare and hazardous waste, where safety and precision are critical. Other users, including institutional facilities and large residential complexes, invest in side loaders for in-house waste management. The diversity of end users broadens the market’s long-term growth outlook.
Segments:
Based on Fuel:
- Diesel
- Electric
Based on Application:
- Municipal waste collection
- Industrial waste collection
Based on End-User:
- Municipal services
- Private waste management companies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America leads the Side Loader Refuse Trucks Market with about 35% of the global share. The U.S. dominates, driven by strong municipal budgets, modern waste infrastructure, and early adoption of automation. Cities such as New York, Los Angeles, and Chicago invest heavily in automated side loaders to improve efficiency and reduce labor costs. Canada follows a similar path, focusing on sustainable fleet modernization through electric and hybrid variants. Waste management companies across the region also benefit from supportive policies and incentive programs aimed at cutting emissions. The presence of established manufacturers and consistent fleet upgrades keeps North America a stable and mature market with strong growth potential.
Europe
Europe holds nearly 20% of the Side Loader Refuse Trucks Market, supported by strict environmental regulations and recycling mandates. Countries such as Germany, the UK, and France lead in adopting electric and CNG-powered refuse trucks to meet EU carbon targets. Municipalities in urban centers face pressure to manage high waste volumes while lowering emissions, creating steady demand for automated side loaders. Manufacturers also focus on ergonomic designs and advanced safety features to align with European worker safety standards. Continuous investment in sustainable fleets ensures long-term opportunities. Government funding and recycling targets accelerate adoption of both electric and hybrid side loader models across the continent.
Asia Pacific
Asia Pacific accounts for about 30% of the Side Loader Refuse Trucks Market and represents the fastest-growing region. Rapid urbanization in China, India, and Southeast Asia drives demand for efficient and automated waste collection. Rising populations in large cities create high daily waste volumes that require modern fleet solutions. Governments and private waste companies invest in side loaders to manage dense residential areas where manual collection is less practical. China invests in smart waste management projects under its urban modernization initiatives, while India focuses on fleet expansion through programs like Swachh Bharat. Growing interest in electric refuse trucks also reflects regional goals to curb urban pollution. Asia Pacific’s rapid economic growth and infrastructure development position it as a key market for future expansion.
Latin America
Latin America contributes around 10% to the Side Loader Refuse Trucks Market. Mexico and Brazil dominate the regional share due to rising urbanization and municipal waste collection needs. Cities such as São Paulo and Mexico City face mounting pressure to modernize waste fleets with automated side loaders. Public-private partnerships expand adoption, with contractors investing in fleets to meet service contracts. Regional governments encourage modernization but face budget constraints, which slows wider adoption. Demand focuses mainly on diesel and CNG trucks, though interest in electric fleets is gradually emerging. Latin America shows steady growth potential as waste collection infrastructure improves and service coverage expands.
Middle East & Africa
The Middle East & Africa hold a smaller share of about 5%, but rising urban development projects create opportunities. Gulf countries, including Saudi Arabia and the UAE, invest in modern side loader fleets as part of smart city and sustainability programs. These fleets help improve collection efficiency in fast-growing urban centers such as Dubai and Riyadh. In contrast, adoption across Africa remains limited due to infrastructure gaps, high vehicle costs, and limited access to advanced fuel technologies. Still, growing urban populations and waste management reforms in South Africa, Nigeria, and Egypt provide growth opportunities. Regional demand remains niche but is set to expand with government-backed sustainability initiatives and international investment in waste infrastructure.
Key Player Analysis
- Bridgeport Manufacturing
- Mack Trucks
- Dennis Eagle
- Amrep
- Peterbilt
- Labrie Trucks
- Heil
- McNeilus Truck
- New Way Refuse Trucks
- Autocar
Competitive Analysis
The Side Loader Refuse Trucks Market players include Bridgeport Manufacturing, Mack Trucks, Dennis Eagle, Amrep, Peterbilt, Labrie Trucks, Heil, McNeilus Truck, New Way Refuse Trucks, and Autocar. The Side Loader Refuse Trucks Market is highly competitive, with manufacturers focusing on technology integration, sustainability, and fleet efficiency to strengthen their positions. Companies emphasize automation, advanced hydraulic systems, and ergonomic designs to improve performance and operator safety. Growing demand for electric and hybrid models pushes innovation in low-emission solutions that align with global sustainability goals. Digital fleet management, telematics, and predictive maintenance tools further enhance competitiveness by reducing downtime and operating costs. Municipal contracts and public-private partnerships play a critical role, as operators seek reliable and cost-effective solutions. The market continues to evolve through product diversification, regional expansion, and continuous investment in research and development.
Recent Developments
- In Jun 2025, GFL Environmental Services acquired OSI, marking one of its first major deals since the company’s spin-off. This acquisition strengthens GFL’s market position and signals a renewed growth strategy post-restructuring.
- In January 2025, Amrep announced a new official dealer partnership with MTech With this agreement, MTech located in Cleveland, Ohio, will cover the Amrep front-end loaders, automated side loaders, and rear-loader refuse truck products for the entire Ohio, Michigan and Western Pennsylvania region.
- In September 2024, Casella Waste Systems announced the acquisition of Royal Carting and Welsh Sanitation, expanding its footprint in the Northeastern U.S. The move is expected to enhance operational efficiency and customer reach in key regional markets.
- In May 2024, Peterbilt will exhibit its extensive vehicle lineup for the refuse industry, including all-electric and natural gas engine-equipped models its new fleet of natural gas-powered garbage trucks in collaboration with Peterbilt Motors Company.
Report Coverage
The research report offers an in-depth analysis based on Fuel, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see steady demand driven by urban waste management needs.
- Electric and hybrid trucks will gain more adoption with stricter emission rules.
- Automation will remain central, with robotic arms and sensors improving efficiency.
- Telematics and IoT tools will expand for smarter fleet management and monitoring.
- Municipal contracts will drive steady fleet upgrades across developed regions.
- Developing countries will increase investments in modern waste collection fleets.
- Safety and ergonomic features will become standard in new product designs.
- CNG and alternative fuels will serve as transitional options alongside electrification.
- Private operators will expand their fleets through public-private partnerships.
- Sustainability initiatives will continue to shape innovation and product development.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Increased Waste Volumes
Rapid urban population growth is generating higher municipal waste volumes, compelling cities to adopt automated side loader refuse trucks for more efficient and space-saving waste collection in dense urban environments.
Sustainability Goals and Emission Regulations
Stricter government emission norms and sustainability mandates are accelerating the shift toward electric, hybrid, and CNG-powered side loader trucks, as municipalities and private operators seek to reduce carbon footprints and comply with environmental standards.
Technological Innovation and Automation
Integration of automation, telematics, and IoT in side loader refuse trucks is improving operational efficiency, route optimization, and predictive maintenance, making these vehicles more attractive for both municipal and private waste management fleets.
Expansion of Public-Private Partnerships
Growing reliance on public-private partnerships and long-term municipal contracts is driving steady investment in modern, high-capacity side loader fleets, supporting continuous upgrades and adoption of advanced technologies.
Focus on Operator Safety and Ergonomics
Increasing emphasis on operator safety and ergonomic design is influencing product development, with manufacturers introducing features such as advanced cabin layouts, automated loading arms, and enhanced visibility systems to reduce workplace injuries and improve operational comfort.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Side Loader Refuse Trucks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Side Loader Refuse Trucks Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Side Loader Refuse Trucks Market?
Who are the leading companies in the Side Loader Refuse Trucks Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel
- 1.2.1 Diesel
- 1.2.2 Electric
- 1.2.3 CNG
- 1.2.4 Hybrid
- 1.2.5 Others
- 1.3 By End User
- 1.3.1 Municipal services
- 1.3.2 Private waste management companies
- 1.3.3 Specialized waste handlers
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Municipal waste collection
- 1.4.2 Industrial waste collection
- 1.4.3 Commercial waste collection
- 1.4.4 Construction and demolition waste collection
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.89 billion → 2032: USD 4.21 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Side Loader Refuse Trucks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Side Loader Refuse Trucks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Side Loader Refuse Trucks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Side Loader Refuse Trucks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Side Loader Refuse Trucks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Side Loader Refuse Trucks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Side Loader Refuse Trucks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Side Loader Refuse Trucks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.89 billion → 2032: USD 4.21 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Side Loader Refuse Trucks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diesel
- 12.3.7.2 Electric
- 12.3.7.3 CNG
- 12.3.7.4 Hybrid
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Municipal services
- 12.4.7.2 Private waste management companies
- 12.4.7.3 Specialized waste handlers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Municipal waste collection
- 12.5.7.2 Industrial waste collection
- 12.5.7.3 Commercial waste collection
- 12.5.7.4 Construction and demolition waste collection
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Side Loader Refuse Trucks End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Side Loader Refuse Trucks Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Side Loader Refuse Trucks Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Side Loader Refuse Trucks Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bridgeport Manufacturing
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mack Trucks
- 18.4 Dennis Eagle
- 18.5 Amrep
- 18.6 Peterbilt
- 18.7 Labrie Trucks
- 18.8 Heil
- 18.9 McNeilus Truck
- 18.10 New Way Refuse Trucks
- 18.11 Autocar
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

