
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Entertainment Systems Market Size 2024 | SD 283.67 million |
| Smart Entertainment Systems Market, CAGR | 6.3% |
| Smart Entertainment Systems Market Size 2032 | USD 462.46 million |
Market Overview
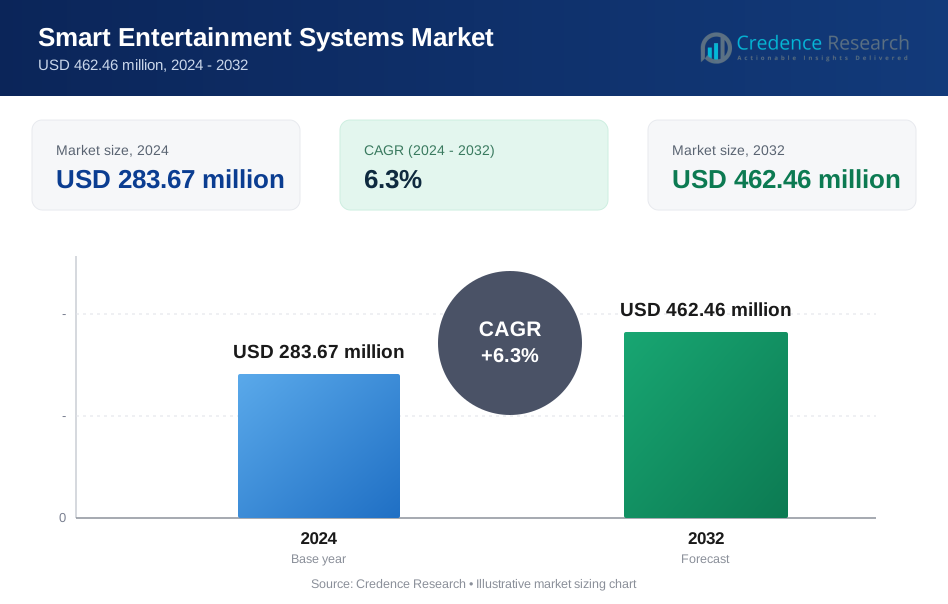
The Smart Entertainment Systems Market is projected to grow from USD 283.67 million in 2024 to an estimated USD 462.46 million by 2032, with a compound annual growth rate (CAGR) of 6.3% from 2024 to 2032.
Key drivers of the smart entertainment systems market include the increasing demand for advanced home entertainment experiences, with consumers seeking immersive, high-quality, and personalized content consumption. The growing adoption of smart devices, including smart TVs, streaming platforms, and connected home ecosystems, further fuels market growth. Additionally, the rise in disposable income and the increasing preference for on-demand entertainment drive the demand for more sophisticated entertainment solutions.
Technological advancements in artificial intelligence, voice control, and augmented reality also contribute to the development of smarter and more interactive entertainment systems. These innovations enhance user experience, providing enhanced customization, ease of use, and integration with other smart home devices. The shift towards 4K and 8K resolution content, as well as the increasing popularity of virtual and augmented reality in gaming and entertainment, are further driving market expansion. Regionally, North America and Europe dominate the smart entertainment systems market due to high consumer demand, technological innovation, and strong purchasing power. The United States and European countries are witnessing the highest growth, with significant investments in smart home technologies and digital infrastructure. In Asia Pacific, countries like China, Japan, and India are also seeing substantial growth, driven by urbanization, rising middle-class populations, and increasing digitalization. Latin America and the Middle East & Africa regions are expected to experience steady growth, with increasing investments in digital entertainment infrastructure and the growing popularity of streaming services contributing to the market’s expansion.
Market Insights
- The Smart Entertainment Systems Market is expected to grow from USD 283.67 million in 2024 to USD 462.46 million by 2032, with a CAGR of 6.3% from 2024 to 2032.
- Increasing demand for high-quality, immersive entertainment experiences and the growing adoption of smart devices like smart TVs and streaming platforms are major market drivers.
- Technological advancements, such as AI, voice control, and augmented reality, are enhancing user experiences and fueling the development of smarter entertainment systems.
- The shift toward 4K and 8K resolution content and rising popularity of virtual and augmented reality in gaming are further expanding the market.
- High initial costs of smart entertainment systems and limited internet infrastructure in certain regions may limit market growth.
- North America and Europe are leading the market due to strong consumer demand, technological innovations, and high purchasing power.
- The Asia Pacific region is experiencing significant growth, driven by urbanization, rising middle-class populations, and increasing digitalization in countries like China, Japan, and India.
Market Drivers
Increasing Demand for Immersive Entertainment Experiences
The demand for immersive entertainment experiences is increasing as consumers seek high-quality, interactive content. The International Telecommunication Union (ITU) has reported that the number of global broadband subscriptions reached 1.4 billion in 2020, with a steady growth trajectory expected in the coming years. This trend is particularly visible in the rise of 4K and 8K content, which requires higher internet speeds and better video quality. The ITU projects that the global broadband penetration rate is expected to increase by 25% in the next five years. This growing demand for high-quality content is directly driving the need for smart entertainment systems. The UK government’s Department for Digital, Culture, Media and Sport (DCMS) reported in 2021 that the number of UK households with access to high-definition television services increased by over 50% between 2015 and 2020.
Growth in Smart Device Adoption
Smart devices are at the core of the growing demand for smart entertainment systems. For instance, the U.S. Department of Energy’s 2020 Smart Home Market Trends report highlighted that nearly 50% of U.S. households were projected to own at least one smart device by 2023. These statistics emphasize the growing adoption of connected devices, which are central to the demand for sophisticated entertainment systems. As these devices become more integrated with digital ecosystems, smart entertainment systems are becoming more mainstream. In addition, the European Commission’s 2020 Digital Economy and Society Index (DESI) reported that 70% of EU households had a smart device, underlining the increasing penetration of these devices across both developed and emerging markets.
Technological Advancements in AI and Voice Control
Technological innovations such as artificial intelligence (AI) and voice control are becoming integral to the development of smarter entertainment systems. For instance, the U.S. National Institute of Standards and Technology (NIST) published in 2021 that over 65% of American households were expected to integrate voice assistants, like Amazon’s Alexa and Google Assistant, into their home entertainment systems by 2023. These AI-driven technologies are enabling more personalized and seamless user experiences, enhancing the appeal of smart entertainment systems. Additionally, in 2021, the European Union invested €500 million in AI research and development, further driving the integration of AI technologies in various consumer electronics, including entertainment systems.
Economic Factors Driving Demand for On-Demand Content
Economic factors such as rising disposable income are significantly impacting the demand for on-demand entertainment. For instance, the World Bank reported that global household consumption expenditures increased in 2020, with notable growth in regions such as Asia and Latin America. This rise in household income is fueling consumer spending on digital entertainment. In India, the Ministry of Finance’s 2021 report showed a 35% increase in household entertainment spending over the past five years, aligning with the growing adoption of smart entertainment systems.
Market Trends
Rising Popularity of Streaming Services
The growing preference for on-demand streaming services is one of the key trends shaping the smart entertainment systems market. his shift is also reflected in the UK, where the government’s Department for Digital, Culture, Media, and Sport (DCMS) reported that nearly 60% of UK households subscribed to at least one streaming service by 2021, representing a significant increase in content consumption habits. The global trend toward streaming services has created opportunities for advanced smart entertainment systems to cater to this growing demand.
Integration with Smart Home Ecosystems
The integration of entertainment systems into broader smart home ecosystems is becoming a critical trend. For Instance, The U.S. Department of Housing and Urban Development (HUD) reported that the adoption of connected home technologies increased by over 30% from 2018 to 2020, largely driven by consumer demand for seamless integration across smart devices. Additionally, the Australian Bureau of Statistics (ABS) indicated that smart home product ownership in Australia increased by 25% between 2017 and 2020, which includes the growing demand for smart entertainment systems that connect with home automation devices. This trend is expected to continue as consumers seek more cohesive and interconnected living environments.
Advancements in AI and Machine Learning
Artificial intelligence (AI) and machine learning (ML) are transforming the functionality of smart entertainment systems. The U.S. National Science Foundation (NSF) reports that AI and ML-based recommendation systems are increasingly being incorporated into entertainment platforms, improving content discovery and personalization. For Instance, in Japan, the Ministry of Internal Affairs and Communications (MIC) has invested $100 million into AI technology initiatives that enhance the capabilities of smart entertainment systems, including voice recognition and personalized user interfaces.
Government Support for Digital Infrastructure
Governments worldwide are investing heavily in digital infrastructure, which is supporting the growth of smart entertainment systems. The U.S. government’s $65 billion investment through the Infrastructure Investment and Jobs Act (2021) aims to expand broadband access nationwide, enhancing connectivity for smart entertainment systems. These investments in digital infrastructure are enabling more consumers to access high-quality entertainment experiences, further accelerating market growth.
Market Challenges Analysis
High Initial Costs and Affordability Concerns
One of the significant challenges faced by the smart entertainment systems market is the high initial cost of these advanced technologies. Smart entertainment systems, which often include smart TVs, sound systems, and other connected devices, tend to be priced higher than traditional alternatives. The U.S. Federal Trade Commission (FTC) reports that the average price of a smart TV in the U.S. increased by 15% between 2020 and 2021 due to the integration of cutting-edge features such as 4K, 8K resolution, and AI-based personalization. This price disparity can limit adoption, particularly in emerging markets where consumer purchasing power is lower. As a result, affordability remains a barrier, preventing some consumers from fully embracing these advanced systems.
Limited Broadband and Digital Infrastructure
Another major challenge is the uneven development of broadband and digital infrastructure, which affects the ability of consumers to fully utilize smart entertainment systems. High-definition streaming, smart home integration, and other advanced features require reliable, high-speed internet connections. For instance, the U.S. Department of Commerce's National Telecommunications and Information Administration (NTIA) reported in 2020 that approximately 19 million Americans still lack access to broadband internet, particularly in rural areas. This lack of infrastructure limits the effectiveness of smart entertainment systems in these regions, as poor internet connectivity can result in buffering, low-quality streams, and an overall suboptimal user experience. Similarly, other regions, including parts of Africa and Asia, also face challenges related to broadband availability, which restricts the adoption of connected entertainment solutions.
Market Opportunities
The Smart Entertainment Systems Market presents significant opportunities driven by continuous advancements in technology and the growing adoption of smart home ecosystems. As consumers increasingly seek personalized and immersive entertainment experiences, there is a rising demand for high-quality, connected devices that integrate seamlessly into daily life. The continued evolution of smart TVs, home theaters, and streaming platforms offers new opportunities for companies to develop innovative, user-friendly solutions that cater to diverse consumer preferences. Additionally, the growing interest in 4K and 8K resolution content, as well as the expansion of virtual and augmented reality technologies, offers vast potential for companies to enhance entertainment experiences. Integrating artificial intelligence (AI) into entertainment systems further provides opportunities to optimize content recommendations, voice control features, and personalized user interfaces, creating a more engaging and dynamic entertainment environment for users.
Another significant opportunity lies in the growing markets of Asia Pacific, Latin America, and the Middle East & Africa. These regions are witnessing increased urbanization, rising disposable income, and a growing appetite for digital content, which are driving demand for smart entertainment systems. The expansion of broadband infrastructure and the increasing availability of high-speed internet in these areas further support the market’s growth potential. In particular, countries like China, India, and Brazil are emerging as key players, where the demand for connected entertainment devices and streaming services is rapidly rising. Companies that focus on expanding their presence in these regions while developing affordable and region-specific products are poised to capitalize on these untapped growth opportunities.
Market Segmentation Analysis
By Product Type
The product type segment is diverse, with several key devices contributing to market growth. Smart TVs are the dominant category, as they integrate streaming capabilities, high-definition displays, and application features that enhance user experiences. Additionally, the demand for streaming devices is increasing as consumers seek flexible access to digital content across platforms. These devices, such as Roku and Amazon Fire Stick, allow users to stream media from various services. Smart speakers and soundbars also play a significant role, offering superior sound quality while doubling as voice-controlled hubs for smart homes. Home theater systems are in demand for those who prefer a more immersive cinematic experience at home, contributing to the market's expansion. Gaming consoles, including PlayStation and Xbox, remain a crucial part of entertainment setups, with gaming becoming an increasingly popular activity. The "Others" category includes devices like projectors and digital media players, rounding out the variety of products fueling market growth.
By Technology
In terms of technology, Bluetooth connectivity and Wi-Fi connectivity are the primary means of ensuring seamless integration and communication between devices. Bluetooth-enabled devices allow for wireless audio streaming and easy synchronization with other smart devices in the home. Wi-Fi connectivity, on the other hand, ensures stable and high-speed data transfer, especially for video streaming, gaming, and internet-based services. These technologies are critical in driving the user-friendly and interconnected features that modern smart entertainment systems offer.
By End User
The end-user segment of the market can be divided into commercial and residential categories. The residential sector holds a substantial share, as consumers continue to adopt smart entertainment systems for their homes, enhancing their entertainment experiences. The commercial sector, including businesses such as hotels, restaurants, and commercial entertainment venues, also shows growth, driven by the need for high-quality entertainment solutions in public spaces.
By Sales Channel
Sales channels for smart entertainment systems are varied, contributing to the market's accessibility. Modern trade continues to be a dominant sales channel, with large retail chains and electronic stores offering a wide range of products. Specialty stores cater to niche consumers seeking high-end devices and personalized services. Franchise outlets/mono-brand stores are also an essential distribution channel, as they allow for targeted marketing and brand-specific offerings. Online stores are rapidly growing in popularity, with the convenience of e-commerce driving a shift toward online purchases. Other sales channels, such as direct-to-consumer and third-party consumer channels, continue to evolve and support the diverse needs of the market.
Segmentations
By Product Type:
- Smart TVs
- Streaming Devices
- Smart Speakers & Sound Bars
- Home Theater Systems
- Gaming Consoles
- Others
By Technology:
- Bluetooth Connectivity
- Wi-Fi Connectivity
By End User:
- Commercial
- Residential
By Sales Channel:
- Modern Trade
- Specialty Stores
- Franchise Outlet/Mono-brand Stores
- Online Stores
- Direct to Consumer
- Third Party to Consumer
- Others Sales Channel
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America North America is a dominant region in the smart entertainment systems market, holding the largest market share. The United States, in particular, accounts for a significant portion of the market due to high consumer demand, technological innovation, and strong purchasing power. The adoption of smart home devices and high-definition entertainment systems is widespread, with the U.S. Department of Energy noting that nearly 50% of U.S. households are expected to own at least one smart device by 2025. The region's robust infrastructure for broadband and streaming services supports the rapid adoption of advanced entertainment technologies. Additionally, companies such as Amazon and Google, based in the U.S., are contributing to the growth of the market through innovations like voice control integration and AI-based personalization.
Europe Europe follows closely as a major player in the smart entertainment systems market, driven by increasing consumer demand for advanced and interconnected entertainment solutions. The United Kingdom, Germany, and France are among the leading countries in this region, with strong consumer interest in both smart TVs and integrated home theater systems. According to the European Commission, around 70% of EU households had a smart device in 2020, contributing to the widespread adoption of smart entertainment systems. Additionally, investments in digital infrastructure, such as 5G networks, further drive the adoption of high-quality streaming content. The European market holds 30% of the global market share, with the demand for AI and voice-controlled entertainment systems particularly strong.
Asia Pacific The Asia Pacific region is experiencing rapid growth in the smart entertainment systems market, driven by urbanization, rising disposable income, and increased internet penetration. Countries like China, Japan, and India are major contributors to the regional market, with a significant shift toward digital entertainment solutions. The rise of middle-class consumers in China and India has driven an increasing demand for smart TVs and streaming services. Additionally, the government of India has been heavily investing in expanding broadband access through initiatives like "BharatNet," which aims to connect rural areas to high-speed internet. As a result, Asia Pacific holds around 20% of the global market share in this segment and is expected to continue its rapid growth trajectory.
Key Player Analysis
- Samsung Electronics
- Sony Corporation
- LG Electronics
- Apple Inc.
- Amazon (Amazon Web Services)
- Google LLC
- Roku, Inc.
- Vizio, Inc.
- Microsoft Corporation
- Harman International Industries
Competitive Analysis
The smart entertainment systems market is highly competitive, with key players focusing on innovation and product differentiation to capture a larger market share. Companies like Samsung, Sony, and LG lead the market by offering high-quality smart TVs and audio systems that integrate cutting-edge technologies such as 4K/8K resolution, AI, and voice controlAdditionally, tech giants like Amazon and Google are enhancing their ecosystems with smart devices, such as Amazon Fire TV and Google Nest, which are gaining traction due to seamless integration with smart home platforms. The competition is also heating up in emerging markets, where companies are tailoring products to suit regional needs. Xiaomi’s aggressive pricing strategy in India and China has made it a strong contender in the market.
Recent Developments
- On January 2025, Samsung introduced its 2025 Smart Monitor lineup, which includes the Smart Monitor M9 featuring AI capabilities to enhance both entertainment and productivity. The company also unveiled the Odyssey OLED G6 and G8, marking the debut of the first 27” 4K OLED gaming monitors with a 500Hz refresh rate at CES 2025.
- On January 2025, Sony expanded its global partner network by adding 23 new members to its AV Alliance and Technology Partner Network. This expansion aims to enhance its display portfolio and improve content sharing across sectors such as retail and healthcare.
- On December 2024, Apple announced the upcoming release of three new smart home devices, including a wall-mounted smart display named 'HomePad', set to debut in March 2025. This device will integrate with existing smart home technologies and offer advanced features for improved user interaction.
Market Concentration & Characteristics
The smart entertainment systems market is moderately concentrated, with a few dominant players such as Samsung, Sony, LG, and Apple controlling a significant portion of the market share. These companies leverage strong brand recognition, vast distribution networks, and advanced technological capabilities to maintain their competitive edge. The market is characterized by rapid innovation, with a continual focus on enhancing user experience through features like 4K/8K resolution, AI integration, and seamless voice control systems. At the same time, the market has seen an influx of new entrants, particularly in regions like Asia Pacific, challenging established players with more affordable options. This has led to increased product differentiation and innovation, as companies strive to offer unique features and better integration with smart home ecosystems. Additionally, the shift towards streaming services and content personalization has further intensified competition, pushing companies to adopt more advanced software and hardware solutions to cater to evolving consumer demands.
Report Coverage
The research report offers an in-depth analysis based on product type, technology, end user, sales channel, region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for immersive home entertainment experiences will continue to grow, with consumers seeking smarter, high-quality solutions for their viewing needs.
- Technological advancements in artificial intelligence, voice control, and augmented reality will enhance user experience, providing more personalized and interactive entertainment systems.
- As 4K and 8K resolution content becomes more mainstream, consumers will increasingly invest in TVs and streaming devices that support these higher resolutions for superior viewing experiences.
- Smart entertainment systems will see broader integration with other smart home devices, allowing for seamless connectivity and a more cohesive home automation experience.
- The shift towards subscription-based streaming services will drive the growth of smart entertainment systems, as consumers demand devices that support a variety of content sources and platforms.
- The Asia Pacific region will continue to see rapid adoption of smart entertainment systems, driven by rising disposable incomes, urbanization, and increased access to digital infrastructure.
- Increased investment in broadband and 5G networks globally will provide the necessary infrastructure to support high-definition streaming and enhance the performance of smart entertainment devices.
- Consumer preferences will continue to evolve towards more sustainable and energy-efficient entertainment solutions, with companies developing eco-friendly smart TVs and devices.
- The growing popularity of virtual reality (VR) and augmented reality (AR) in gaming and entertainment will lead to innovations in hardware and software tailored to these technologies.
- As competition intensifies, both established players and new entrants will focus on improving product features, pricing strategies, and customer service to capture a larger share of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Immersive Entertainment Experiences
Consumers are seeking high-quality, interactive, and personalized content, driving the adoption of smart entertainment systems that support 4K/8K resolution and advanced audio-visual features for a more immersive experience.
Growth in Smart Device Adoption
The widespread integration of smart TVs, streaming devices, and connected home ecosystems is fueling market growth as consumers look for seamless, interconnected entertainment solutions within their homes.
Technological Advancements in AI, Voice Control, and AR
Innovations in artificial intelligence, voice assistants, and augmented reality are enhancing user experiences by enabling smarter, more intuitive, and interactive entertainment systems that can personalize content and integrate with other smart home devices.
Expansion of Streaming Services and On-Demand Content
The shift toward subscription-based streaming and on-demand content is increasing the need for devices that can support multiple platforms and high-definition streaming, boosting demand for advanced smart entertainment systems.
Rising Disposable Income and Urbanization in Emerging Markets
Growing middle-class populations and increased urbanization, especially in Asia Pacific and Latin America, are enabling more consumers to invest in sophisticated entertainment solutions, expanding the market's global reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Smart Entertainment Systems Market?
What factors are driving the growth of the Smart Entertainment Systems Market?
Which regions are leading the Smart Entertainment Systems Market?
What is the growth outlook for regions outside North America and Europe?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.3 By Technology
- 1.3.1 Bluetooth Connectivity
- 1.3.2 Wi-Fi Connectivity
- 1.4 By Product Type
- 1.4.1 Smart TVs
- 1.4.2 Streaming Devices
- 1.4.3 Smart Speakers & Sound Bars
- 1.4.4 Home Theater Systems
- 1.4.5 Gaming Consoles
- 1.4.6 Others
- 1.5 By Sales Channel
- 1.5.1 Modern Trade
- 1.5.2 Specialty Stores
- 1.5.3 Franchise Outlet/Mono-brand Stores
- 1.5.4 Online Stores
- 1.5.5 Direct to Consumer
- 1.5.6 Third Party to Consumer
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 283.67 million → 2032: USD 462.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Entertainment Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Entertainment Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Entertainment Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Entertainment Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Entertainment Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Entertainment Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Entertainment Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Entertainment Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 283.67 million → 2032: USD 462.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Entertainment Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bluetooth Connectivity
- 12.4.7.2 Wi-Fi Connectivity
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Smart TVs
- 12.5.7.2 Streaming Devices
- 12.5.7.3 Smart Speakers & Sound Bars
- 12.5.7.4 Home Theater Systems
- 12.5.7.5 Gaming Consoles
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Modern Trade
- 12.6.7.2 Specialty Stores
- 12.6.7.3 Franchise Outlet/Mono-brand Stores
- 12.6.7.4 Online Stores
- 12.6.7.5 Direct to Consumer
- 12.6.7.6 Third Party to Consumer
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Entertainment Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Entertainment Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Entertainment Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Entertainment Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sony Corporation
- 18.4 LG Electronics
- 18.5 Apple Inc.
- 18.6 Amazon
- 18.7 Google LLC
- 18.8 Roku, Inc.
- 18.9 Vizio, Inc.
- 18.10 Microsoft Corporation
- 18.11 Harman International Industries
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

