
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Africa Plastic Welding Equipment Market Size 2024 | USD 46.36 million |
| South Africa Plastic Welding Equipment Market, CAGR | 4.24% |
| South Africa Plastic Welding Equipment Market Size 2032 | USD 64.64 million |
Market Overview
South Africa Plastic Welding Equipment Market size was valued at USD 46.36 million in 2024 and is anticipated to reach USD 64.64 million by 2032, at a CAGR of 4.24% during the forecast period (2024-2032).
The South Africa plastic welding equipment market is driven by increasing demand for durable, high-performance materials in industries such as automotive, construction, and packaging. Growing adoption of plastic components in manufacturing processes, due to their lightweight, corrosion-resistant, and cost-effective properties, further fuels the market's expansion. Technological advancements in welding equipment, such as automation, improved precision, and energy efficiency, are enhancing production capabilities and attracting investments. Additionally, the rise in infrastructure development and the growing need for environmentally sustainable solutions are encouraging industries to adopt plastic welding technologies. The trend toward recycling and the use of eco-friendly materials is also boosting demand for plastic welding equipment, as it plays a crucial role in creating strong, reusable connections in recycled plastic products. These factors, combined with a focus on operational efficiency and cost reduction, are shaping the growth trajectory of the market in South Africa.
The South African plastic welding equipment market is geographically diverse, with key regions such as Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape playing significant roles in driving demand. Gauteng, as the industrial and economic hub, leads the market due to its concentration of manufacturing and engineering sectors. Western Cape benefits from its strong port presence and focus on sustainable industries. KwaZulu-Natal’s industrial base, particularly in automotive and packaging, also supports steady growth, while Eastern Cape is seeing a rise in demand due to its automotive manufacturing clusters. The market is highly competitive, with leading global and regional players like Leister Technologies AG, RITMO S.p.A., Emerson Electric Co., and Herrmann Ultraschalltechnik GmbH & Co. KG. These companies are leveraging advanced technology and innovation to meet the evolving demands of various industries, focusing on delivering high-quality, efficient plastic welding solutions across different sectors.
Market Insights
- The South Africa plastic welding equipment market was valued at USD 46.36 million in 2024 and is projected to reach USD 64.64 million by 2032, growing at a CAGR of 4.24% from 2024 to 2032.
- The global plastic welding equipment market was valued at USD 11,340.00 million in 2024 and is projected to reach USD 19,842.36 million by 2032, growing at a CAGR of 7.24% from 2024 to 2032.
- The increasing demand for plastic welding in automotive, packaging, and construction sectors is driving market growth.
- Advancements in welding technologies, including automation and precision equipment, are expected to support market expansion.
- Growing awareness of sustainability and eco-friendly production methods is influencing the adoption of modern plastic welding solutions.
- Intense competition among global and regional players is pushing companies to innovate and offer cost-effective solutions.
- Market restraints include high initial investment costs and a lack of skilled labor in certain regions.
- Gauteng and Western Cape are leading regions in terms of market share, while KwaZulu-Natal and Eastern Cape show steady growth.
Report Scope
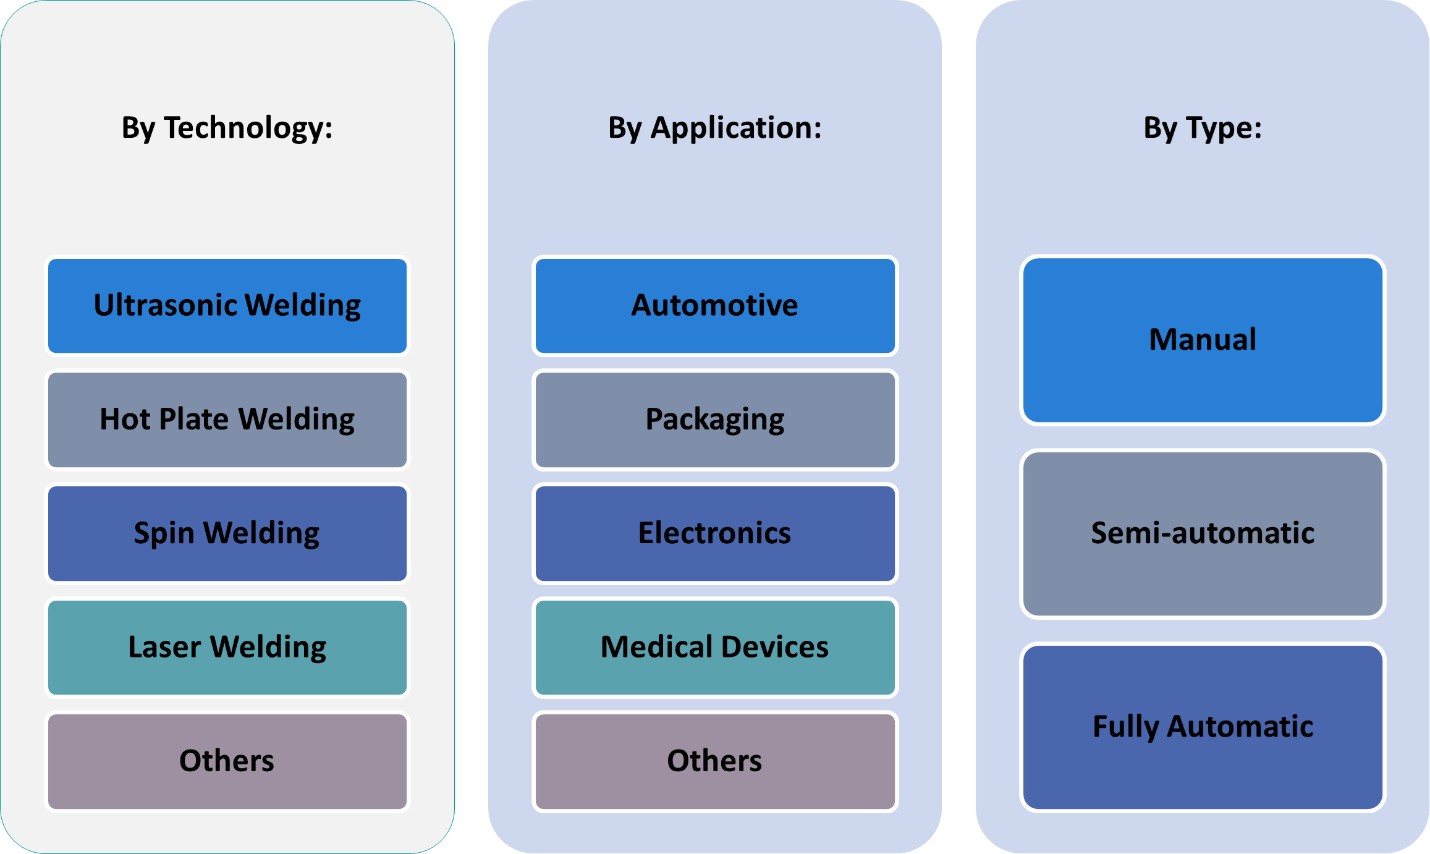
This report segments the South Africa Plastic Welding Equipment Market as follows:
Market Drivers
Growing Industrial Demand for Plastic Components
The increasing adoption of plastic components across various industries is a primary driver of the South Africa plastic welding equipment market. Plastics are preferred due to their versatility, cost-effectiveness, and durability, making them ideal for use in industries such as automotive, packaging, and construction. In the automotive sector, for example, manufacturers are using lightweight plastic materials to improve fuel efficiency and reduce vehicle weight, thus boosting the demand for plastic welding equipment to assemble these components. Similarly, the growing use of plastics in packaging, particularly in the food and beverage industry, further contributes to the demand for effective and efficient welding equipment. As industries continue to embrace plastic materials for a variety of applications, the need for advanced plastic welding equipment rises correspondingly.
Technological Advancements in Welding Equipment
Advancements in plastic welding technology are significantly influencing the market growth. Innovations such as automated and robotic welding systems are improving the precision and speed of the welding process, while also reducing labor costs and minimizing errors. These developments are particularly attractive to industries looking for enhanced efficiency and higher throughput. Modern plastic welding equipment now offers improved energy efficiency, reduced environmental impact, and greater precision in welding operations. With the integration of Industry 4.0 technologies, such as Internet of Things (IoT) and data analytics, manufacturers can optimize their operations, improving overall performance and reducing downtime. These technological advancements are making plastic welding more accessible, reliable, and cost-effective, thereby driving demand for high-quality welding solutions in South Africa.
Increasing Infrastructure and Construction Projects
South Africa's ongoing infrastructure development and construction projects are contributing to the growth of the plastic welding equipment market. The construction industry increasingly utilizes plastic materials for various applications, such as pipes, insulation, and waterproofing, owing to their durability, cost-efficiency, and resistance to corrosion. For instance, government-backed initiatives in South Africa are utilizing butt fusion welding technologies for water management projects to ensure the durability and efficiency of plastic pipelines. Plastic welding plays a vital role in ensuring these materials are securely joined to meet industry standards. As South Africa invests in its infrastructure, especially in transportation, water management, and residential construction, the need for efficient welding technologies grows. The government's emphasis on upgrading infrastructure and meeting the demand for sustainable construction solutions further bolsters the demand for advanced plastic welding equipment.
Environmental Sustainability and Recycling Trends
Environmental sustainability is a significant factor driving the demand for plastic welding equipment in South Africa. With a growing emphasis on recycling and reducing waste, industries are focusing on developing systems that allow for the efficient reuse of plastic materials. For instance, environmental agencies in South Africa report that automotive manufacturers are adopting vibration welding technologies to repair and reuse plastic components, aligning with circular economy principles. This trend is particularly evident in industries like automotive manufacturing, where the use of recycled plastics is increasing. As consumers and businesses alike become more environmentally conscious, the need for reliable and sustainable plastic welding solutions rises. Additionally, plastic welding is a key process in developing eco-friendly alternatives in packaging, construction materials, and other sectors. This heightened focus on sustainability and the efficient use of materials is shaping the plastic welding market in South Africa, encouraging manufacturers to invest in equipment that aligns with these green initiatives.
Market Trends
Integration of Advanced Technologies
The South African plastic welding equipment market is witnessing a significant shift towards the integration of advanced technologies such as Artificial Intelligence (AI) and the Internet of Things (IoT). These innovations enable real-time monitoring, predictive maintenance, and enhanced precision in welding processes. For instance, AI algorithms can optimize welding parameters, leading to improved joint quality and reduced defects. IoT connectivity allows for remote diagnostics and performance tracking, enhancing operational efficiency and reducing downtime. This technological evolution is particularly beneficial in sectors like automotive and electronics, where precision and reliability are paramount.
Expansion of Infrastructure Projects
South Africa's ongoing infrastructure development is a significant driver for the plastic welding equipment market. The construction of pipelines, tanks, and other infrastructure components increasingly utilizes plastic materials due to their durability and cost-effectiveness. For instance, government-backed initiatives in South Africa are utilizing butt fusion welding technologies for water management projects to ensure the durability and efficiency of plastic pipelines. Plastic welding plays a crucial role in joining these materials, ensuring structural integrity and longevity. Government initiatives aimed at boosting industrialization and infrastructure development further propel the demand for plastic welding solutions. As urbanization accelerates and infrastructure projects expand, the need for reliable and efficient plastic welding equipment continues to rise.
Shift Towards Sustainable Practices
Environmental sustainability is increasingly influencing the plastic welding equipment market in South Africa. There is a growing emphasis on energy-efficient and eco-friendly welding solutions that minimize waste and reduce carbon footprints. For instance, environmental agencies in South Africa report that manufacturers in the packaging sector are adopting ultrasonic welding technologies to reduce energy consumption and minimize waste during production. Manufacturers are developing equipment that consumes less energy and produces fewer emissions, aligning with global sustainability goals. Additionally, the trend towards recycling and reusing plastic materials is driving the demand for welding technologies that facilitate the repair and reuse of plastic components. This shift not only supports environmental objectives but also offers cost-saving benefits to industries adopting these practices.
Customization and Industry-Specific Solutions
As industries evolve, there is a growing demand for customized plastic welding equipment tailored to specific applications. Manufacturers are responding by offering solutions that cater to the unique requirements of various sectors, including automotive, medical devices, and packaging. For example, in the automotive industry, welding equipment is being designed to handle complex geometries and materials used in vehicle components. Similarly, the medical sector requires welding solutions that ensure the integrity and safety of devices. This trend towards customization enhances the functionality and efficiency of welding processes, meeting the precise needs of different industries.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
A significant challenge facing the South Africa plastic welding equipment market is the high initial investment and maintenance costs associated with advanced welding technologies. For instance, small and medium-sized enterprises (SMEs) in South Africa often rely on government programs like the Department of Trade, Industry, and Competition's (DTIC) Industrial Financing initiatives to access funding for adopting advanced manufacturing technologies. However, even with such support, many SMEs struggle to cover the substantial upfront costs of acquiring modern welding equipment, such as ultrasonic and laser systems. Additionally, maintaining sophisticated welding machines requires specialized training and expertise, further increasing operational expenses. For example, companies that adopt IoT-enabled welding systems often need to invest in predictive maintenance tools and operator training programs, which can be costly. For many businesses, the ongoing maintenance and repair costs of high-tech welding equipment can be a continuous financial strain, discouraging investment in the latest models and hindering market growth.
Skilled Labor Shortage and Training Challenges
Another challenge in the South African plastic welding equipment market is the shortage of skilled labor and the difficulty of training personnel to operate advanced equipment. As welding technologies evolve, there is a growing demand for workers with specialized skills in plastic welding and machine operation. However, the availability of qualified technicians remains limited, making it challenging for companies to find and retain skilled professionals. Moreover, the training process for operating high-precision welding machines can be time-consuming and costly. This skills gap impacts production efficiency and increases the risk of operational errors, potentially leading to increased downtime and defects in welded components. Consequently, businesses in South Africa may face difficulties in scaling operations effectively, which could slow the market's overall growth.
Market Opportunities
The South Africa plastic welding equipment market presents significant opportunities driven by several key factors. One notable opportunity is the growing demand for sustainable and eco-friendly manufacturing processes. As industries focus more on environmental responsibility, the need for plastic recycling and reusability has increased. Plastic welding plays a crucial role in these processes, allowing manufacturers to repair and reuse plastic components rather than relying on new raw materials. The development of energy-efficient and low-emission welding technologies further enhances this sustainability drive. Companies that invest in advanced, environmentally-friendly welding solutions are well-positioned to meet the rising demand for eco-conscious manufacturing practices, especially in industries like automotive, packaging, and construction.
Additionally, the ongoing expansion of infrastructure projects in South Africa provides a promising avenue for growth in the plastic welding equipment market. With the country’s increasing focus on infrastructure development, particularly in water management, transportation, and residential construction, the demand for durable plastic materials continues to rise. These sectors heavily rely on plastic welding to ensure secure, long-lasting connections in pipes, tanks, and other components. As both public and private investments in infrastructure grow, the need for efficient and reliable plastic welding technologies will continue to expand, presenting opportunities for equipment manufacturers to capitalize on this trend. Businesses that offer tailored solutions for specific applications, such as custom welding machines for the construction or automotive industries, will be able to tap into these emerging market segments and drive further growth.
Market Segmentation Analysis:
By Type:
The South Africa plastic welding equipment market can be segmented by type into manual, semi-automatic, and fully automatic categories. Manual welding equipment remains prevalent, particularly in small and medium-sized businesses, due to its cost-effectiveness and simplicity of operation. However, the market is seeing a shift towards semi-automatic and fully automatic welding solutions. Semi-automatic equipment offers a balance between control and efficiency, providing improved productivity while still allowing operators to manage key aspects of the welding process. This segment is particularly popular in industries where moderate automation is desired, such as packaging and automotive sectors. The fully automatic segment is growing rapidly, driven by advancements in technology and the need for higher precision and throughput. Fully automatic plastic welding systems are increasingly sought after in large-scale operations, such as electronics and medical device manufacturing, where high-volume production and strict quality standards are essential. As industries push for more efficient and precise welding solutions, the demand for semi-automatic and fully automatic equipment is expected to increase.
By Application:
The plastic welding equipment market in South Africa also shows strong segmentation based on application, with key sectors including electronics, packaging, automotive, medical devices, and others. The electronics sector is a prominent end-user of plastic welding equipment, as it relies on the technology for precise assembly of components such as casings and connectors. The packaging industry is another major driver, with plastic welding being essential for producing durable, leak-proof packaging solutions. Automotive manufacturing also significantly contributes to the demand for plastic welding equipment, as the industry increasingly utilizes lightweight plastic components in vehicle construction for improved fuel efficiency and performance. The medical device sector is growing rapidly, with plastic welding playing a crucial role in ensuring the integrity of devices that require airtight and hygienic sealing. Other industries such as construction, agriculture, and consumer goods also contribute to the market, as they utilize plastic welding for various applications, including pipe welding, plastic tank construction, and more. Each of these sectors drives specific demand for tailored welding solutions, fostering continued market growth.
Segments:
Based on Type:
- Manual
- Semi-automatic
- Fully Automatic
Based on Application:
- Electronics
- Packaging
- Automotive
- Medical Devices
- Others
Based on Technology:
- Ultrasonic Welding
- Hot Plate Welding
- Spin Welding
- Laser Welding
- Others
Based on the Geography:
- Gauteng
- Western Cape
- KwaZulu-Natal
- Eastern Cape
Regional Analysis
Gauteng
Gauteng, being the economic hub of the country, leads with a significant market share of approximately 35%. This dominance can be attributed to the concentration of industrial activities, manufacturing, and engineering firms in cities like Johannesburg and Pretoria. The region’s established infrastructure and proximity to major industries such as automotive, construction, and packaging, have driven the demand for advanced plastic welding solutions. Moreover, Gauteng’s well-developed industrial base facilitates the adoption of high-quality, specialized welding equipment for a variety of plastic materials.
Western Cape
In the Western Cape, the plastic welding equipment market holds a share of around 25%. Cape Town, the region's primary economic center, serves as a key port city, making it integral to international trade and manufacturing. The Western Cape has a strong presence of companies focused on agriculture, food packaging, and the renewable energy sector. As a result, the demand for plastic welding technologies, especially those that support food safety standards and environmentally friendly solutions, has grown substantially. The region’s focus on innovation and sustainable manufacturing practices also drives investments in advanced plastic welding equipment.
KwaZulu-Natal
KwaZulu-Natal, accounting for about 20% of the market, plays a crucial role in South Africa’s plastic welding industry. Durban, the province's largest city, hosts the country’s busiest port, contributing to significant trade in plastic materials and products. The industrial sector in KwaZulu-Natal is robust, particularly in the areas of automotive manufacturing, petrochemicals, and packaging. The province’s developing infrastructure and the growing number of manufacturing plants in and around Durban are fostering increased demand for plastic welding equipment, particularly in industries looking to improve production efficiency and reduce costs.
Eastern Cape
The Eastern Cape rounds out the regional distribution with a market share of approximately 15%. This region is notable for its automotive manufacturing clusters, particularly in Port Elizabeth, where major vehicle manufacturers are based. The demand for plastic welding equipment in the Eastern Cape is driven by the automotive and textile industries, with an emphasis on cost-effective and durable welding solutions. Although the market share is smaller compared to the other regions, the Eastern Cape continues to show steady growth in plastic welding technology adoption, especially in industries focusing on high-volume production and product innovation.
Key Player Analysis
- Leister Technologies AG
- RITMO S.p.A.
- Emerson Electric Co.
- Herrmann Ultraschalltechnik GmbH & Co. KG
- Frimo Group GmbH
- Bielomatik Leuze GmbH & Co. KG
- Mecasonic Group
- CEMAS Elettra
- CHN-TOP Machinery Group
- Haitian International Holdings Ltd.
Competitive Analysis
The South African plastic welding equipment market is characterized by intense competition, with several global and regional players actively shaping the industry. Leading companies such as Leister Technologies AG, RITMO S.p.A., Emerson Electric Co., Herrmann Ultraschalltechnik GmbH & Co. KG, Frimo Group GmbH, Bielomatik Leuze GmbH & Co. KG, Mecasonic Group, CEMAS Elettra, CHN-TOP Machinery Group, and Haitian International Holdings Ltd. dominate the market by offering a wide range of advanced products tailored to the needs of various industries, including automotive, packaging, and construction. Automation and precision are key focus areas, with manufacturers investing heavily in research and development to improve the efficiency and capabilities of their products. Additionally, many competitors emphasize sustainability, responding to growing demand for eco-friendly manufacturing processes.
In terms of competitive strategies, companies are focused on strengthening their market positions by offering comprehensive after-sales services, including training, maintenance, and technical support. This helps to enhance customer loyalty and ensures long-term business relationships. While the market has challenges, including the high capital cost of equipment and the need for skilled labor, leading companies continue to stay ahead by adapting to market needs and offering advanced solutions. Competitive pressure is also intensified by the continuous need to provide cost-effective options, making innovation in plastic welding technology a vital aspect of staying competitive in the region.
Recent Developments
- In March 2025, Leister transferred its laser plastic welding business to Hymson Novolas AG, a subsidiary of Hymson Laser Technology Group Co. Ltd. The transition ensures continuity and further development of existing product lines, with a new Laser Technology Center established in Switzerland. Leister will now focus more on its core competencies: plastic welding (hot air, infrared) and industrial process heat.
- In February 2025, Herrmann continues to set industry standards with its ultrasonic welding solutions, particularly for medical devices and sensitive components. The company emphasizes individualized process development, intelligent process control, and digital quality monitoring for reproducible, high-strength welds. Herrmann will showcase new applications and integration options at K 2025, focusing on automation and sustainability in medical and packaging industries.
- In January 2025, Dukane highlighted its patented Q-Factor, Melt-Match®, Low Amplitude Preheat, and Ultra-High Frequency (260–400 Hz) vibration welding technologies, emphasizing their leadership in process control and diagnostics.
- In May 2024, Emerson launched the Branson™ GLX-1 Laser Welder, designed for the automated assembly of small, intricate plastic parts. The GLX-1 features a compact, modular design suitable for cleanroom environments, advanced servo-based actuation, and the ability to “un-weld” plastics for closed-loop recycling. It uses Simultaneous Through-Transmission Infrared® (STTlr) laser-welding technology for high efficiency, weld strength, and aesthetics. Enhanced connectivity, security, and data collection features support Industry 4.0 integration.
Market Concentration & Characteristics
The South African plastic welding equipment market exhibits moderate concentration, with a few dominant global and regional players holding a significant share. These companies, including Leister Technologies AG, RITMO S.p.A., Emerson Electric Co., and others, possess strong technological capabilities and extensive product portfolios, enabling them to cater to diverse industrial applications such as automotive, construction, and packaging. The market is characterized by a high level of innovation, with companies continually introducing advanced, energy-efficient, and automated welding solutions to meet the evolving demands of industries. Despite the market being concentrated among key players, there is room for smaller, regional manufacturers to thrive by offering specialized, cost-effective solutions. The characteristics of the market are shaped by factors like the need for durable, high-quality equipment, technical support services, and a growing emphasis on sustainability and eco-friendly practices. As such, competition remains fierce, driving continuous advancements in product offerings
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for plastic welding equipment in South Africa is expected to rise as industries focus on more sustainable and durable materials.
- Advancements in welding technology will drive the adoption of more efficient and precise plastic welding equipment.
- The growing automotive and manufacturing sectors will increase the need for high-quality plastic welding solutions.
- Innovations in automation and robotics will likely enhance the performance and efficiency of plastic welding equipment.
- The construction and infrastructure development boom in South Africa will create opportunities for plastic welding applications.
- The increased focus on reducing plastic waste and enhancing recycling processes will lead to greater demand for plastic welding solutions.
- Training and skill development in plastic welding will be essential to ensure high-quality output in various industries.
- Regulatory policies promoting sustainability and eco-friendly practices will encourage investment in advanced plastic welding technologies.
- Integration of Internet of Things (IoT) technology into plastic welding systems will enhance real-time monitoring and process optimization.
- South Africa's strategic position within the African continent will make it a hub for exporting plastic welding equipment to neighboring regions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the South Africa Plastic Welding Equipment?
What factors are driving the growth of the South Africa Plastic Welding Equipment?
What are the key segments within the South Africa Plastic Welding Equipment?
Who are the major players in the South Africa Plastic Welding Equipment?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Africa Plastic Welding Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 South Africa Plastic Welding Equipment Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 46.36 million → 2032: USD 64.64 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Africa Plastic Welding Equipment Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Africa Plastic Welding Equipment Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Africa Plastic Welding Equipment Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 South Africa Plastic Welding Equipment Drivers
- 3.3 South Africa Plastic Welding Equipment Restraints & Challenges
- 3.4 South Africa Plastic Welding Equipment Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Africa Plastic Welding Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Africa Plastic Welding Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Africa Plastic Welding Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Africa Plastic Welding Equipment Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. South Africa Plastic Welding Equipment Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to South Africa Plastic Welding Equipment in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Africa Plastic Welding Equipment Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 South Africa Plastic Welding Equipment Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 South Africa Plastic Welding Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Africa Plastic Welding Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in South Africa Plastic Welding Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. South Africa Plastic Welding Equipment – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. South Africa Plastic Welding Equipment – Priority Domestic Market 1
Chapter 10. South Africa Plastic Welding Equipment – Priority Domestic Market 2
Chapter 11. South Africa Plastic Welding Equipment – Priority Domestic Market 3
Chapter 12. South Africa Plastic Welding Equipment – Priority Domestic Market 4
Chapter 13. South Africa Plastic Welding Equipment Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
