
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Third-Party Risk Management Market Size 2024 | USD 7,237.60 Million |
| Third-Party Risk Management Market, CAGR | 13.4% |
| Third-Party Risk Management Market Size 2032 | USD 19792.42 Million |
Market Overview:
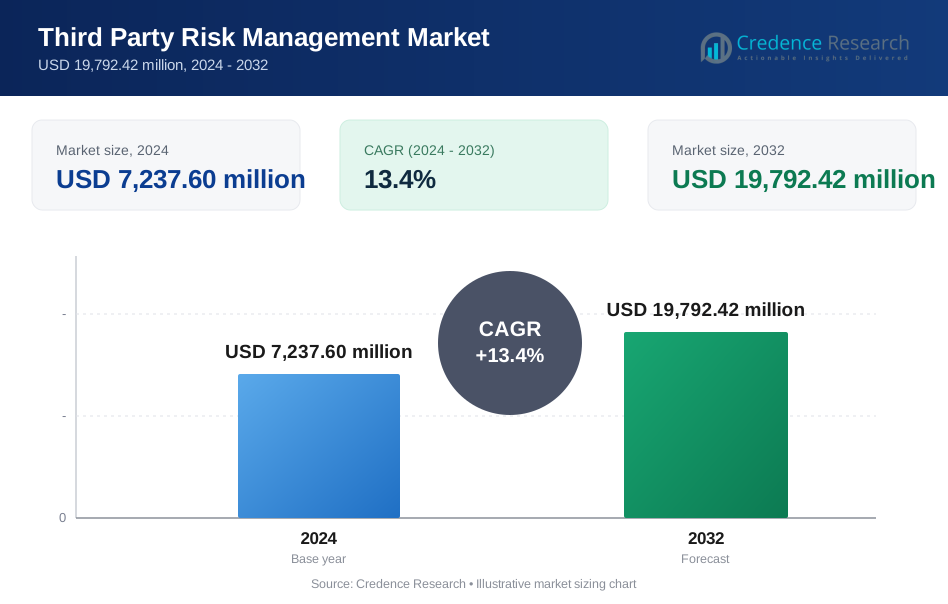
The Third-Party Risk Management Market is projected to grow from USD 7,237.60 million in 2024 to USD 19792.42 million by 2032, at a CAGR of 13.4% from 2024 to 2032.
Key drivers of the TPRM market include the growing regulatory compliance requirements, heightened security concerns, and the rise in cyber threats. With stringent regulations such as GDPR and other data privacy laws being enforced across industries, organizations are prioritizing third-party risk management solutions to ensure compliance and avoid costly penalties. The increasing complexity of global supply chains also drives the need for comprehensive risk management strategies. Additionally, cyberattacks targeting third-party vendors, often resulting in data breaches and financial losses, have underscored the importance of robust risk management practices. The increasing dependence on outsourced services and global partnerships also amplifies the need for effective TPRM solutions.
Geographically, North America holds the largest share of the TPRM market, driven by the presence of numerous industries such as finance, healthcare, and manufacturing, all of which face significant regulatory pressure and heightened security concerns. In this region, organizations are actively implementing TPRM solutions to safeguard against both compliance risks and operational disruptions. Europe follows closely, with businesses adopting comprehensive TPRM frameworks due to similar regulatory challenges. Additionally, companies in the region are emphasizing data protection as a key component of their third-party risk strategies. The Asia Pacific region is anticipated to witness the highest growth during the forecast period, as businesses in countries like China, India, and Japan are increasingly adopting third-party risk management solutions to navigate the evolving regulatory landscape and secure their global supply chains. This rapid adoption is also fueled by the region's growing digital transformation initiatives.
Market Drivers:
Growing Regulatory Compliance Requirements:
One of the primary drivers of the Third-Party Risk Management (TPRM) market is the increasing pressure from regulatory bodies. Stricter laws, such as the General Data Protection Regulation (GDPR) and other region-specific data privacy regulations, require organizations to manage risks associated with their third-party vendors more effectively. These regulations enforce heavy penalties for non-compliance, driving businesses to adopt comprehensive TPRM frameworks to mitigate risks and stay compliant. For instance, the GDPR imposes fines of up to €20 million or 4% of annual global turnover for non-compliance, compelling companies like Google and Facebook to implement stringent TPRM measures. As regulatory landscapes continue to evolve, organizations are prioritizing the implementation of solutions that can ensure ongoing compliance.
Heightened Security Concerns:
The rising number of cyberattacks, especially those targeting third-party vendors, is another critical factor driving the TPRM market. Cybercriminals often exploit the vulnerabilities in the supply chain, gaining unauthorized access to sensitive data and systems. For instance, the Target data breach in 2013, which compromised 40 million credit and debit card accounts, occurred through a third-party HVAC vendor. As organizations increasingly rely on third-party vendors for critical services, the risk of security breaches grows. This has prompted companies to seek robust third-party risk management solutions to safeguard their systems and data from cyber threats, ensuring both operational continuity and data protection.
Increased Outsourcing and Globalization:
The growing trend of outsourcing and expanding global supply chains further contributes to the demand for TPRM solutions. As organizations collaborate with a wider range of third-party vendors across the globe, the complexity of managing risks also increases. For instance, companies like Apple and IBM work with numerous suppliers and partners worldwide, increasing the need for comprehensive TPRM frameworks. Effective TPRM solutions are essential for businesses to assess, monitor, and mitigate risks across their entire vendor ecosystem, especially in an increasingly interconnected world.
Financial and Operational Losses:
Financial and operational losses resulting from third-party risks also play a significant role in driving the adoption of TPRM solutions. Incidents like data breaches, fraud, and service disruptions due to third-party failures can have severe consequences for businesses. For instance, Microsoft successfully mitigated third-party risks by implementing a robust third-party risk management solution, which helped them maintain operational continuity and avoid significant financial losses. Organizations are actively investing in risk management systems to minimize the financial impact of such events and ensure business continuity.
Market Trends:
Increased Adoption of Automation and AI:
A notable trend in the Third-Party Risk Management (TPRM) market is the growing use of automation and artificial intelligence (AI) to streamline risk assessment and monitoring processes. AI-driven tools enable organizations to analyze vast amounts of third-party data more efficiently, identifying potential risks quickly. For instance, IBM's OpenPages with Watson uses AI to automate risk assessments, providing real-time insights and reducing manual workload. Automation is also being utilized to ensure real-time monitoring and immediate alerts, reducing manual workload and improving response times. This shift toward AI and automation enhances the accuracy of risk assessments and enables businesses to proactively address potential threats.
Integration of Cybersecurity into TPRM Solutions:
As cyber threats become more sophisticated, integrating cybersecurity measures into third-party risk management frameworks has gained significant traction. Companies are focusing on evaluating their third-party vendors' cybersecurity practices and vulnerabilities. For instance, BitSight offers cybersecurity ratings that help organizations assess the security posture of their vendors. This trend is driven by the realization that a single weak link in the supply chain can compromise an entire organization’s security. TPRM solutions are now incorporating cybersecurity risk assessments to help companies ensure that third-party vendors meet stringent security standards.
Cloud-Based TPRM Solutions:
The shift toward cloud-based risk management solutions is another prominent trend in the market. Cloud technology provides businesses with more flexibility, scalability, and cost-efficiency in managing third-party risks. For instance, RSA Archer offers cloud-based TPRM solutions that enable organizations to access real-time data and collaborate seamlessly with stakeholders. With increasing digital transformation across industries, organizations are leveraging cloud-based TPRM solutions to access real-time data and collaborate seamlessly with stakeholders. This trend allows businesses to manage risks associated with global supply chains more effectively while maintaining operational agility.
Focus on Continuous Monitoring:
Traditional, periodic risk assessments are being replaced by continuous monitoring in the TPRM space. As the business landscape becomes more dynamic and complex, organizations are adopting tools that allow them to monitor third-party risks on an ongoing basis. For instance, Prevalent's continuous monitoring solution provides real-time updates on vendor risks, ensuring that any potential threats are promptly identified and mitigated. This shift ensures that risks are identified and mitigated promptly, reducing the likelihood of costly disruptions.
Market Challenges Analysis:
Complexity of Global Supply Chains:
One of the key challenges in the Third-Party Risk Management (TPRM) market is the increasing complexity of global supply chains. Organizations are partnering with a wide range of third-party vendors across multiple regions and industries, each with distinct regulatory environments, cultural norms, and operational risks. Managing such a diverse and global ecosystem of vendors requires advanced risk management solutions that can handle the complexities of different geographies and industries. The challenge lies in maintaining consistent risk mitigation strategies while adapting to varying regulatory and operational environments worldwide.
Data Privacy and Security Concerns:
Data privacy and security concerns are significant challenges for organizations when managing third-party risks. As businesses share sensitive information with external vendors, they expose themselves to potential data breaches and cyberattacks. Third-party vendors may not always have the same level of cybersecurity protocols in place, leaving organizations vulnerable to data leaks and security breaches. Ensuring that third-party vendors comply with stringent data privacy regulations, such as GDPR, and maintain high standards of security practices is a major hurdle for organizations adopting TPRM solutions.
Market Segmentation Analysis:
By Deployment Type
The Third-Party Risk Management (TPRM) market is segmented by deployment type into on-premise and cloud-based solutions. Cloud-based solutions dominate the market, driven by their scalability, flexibility, and cost-effectiveness. These solutions enable businesses to manage third-party risks from anywhere, providing real-time updates and improved collaboration. On-premise solutions, while still relevant for some organizations with specific security or regulatory needs, account for a smaller portion of the market due to the higher costs and complexity associated with managing infrastructure in-house.
By Organization Size
In terms of organization size, the TPRM market is divided into small and medium-sized enterprises (SMEs) and large enterprises. Large enterprises hold the largest market share, owing to their complex supply chains, regulatory compliance requirements, and heightened security concerns. SMEs are increasingly adopting TPRM solutions as well, driven by the growing awareness of third-party risks and the availability of affordable cloud-based solutions tailored to smaller businesses.
By Vertical
The TPRM market is further segmented by verticals such as banking and financial services, healthcare, manufacturing, retail, and information technology (IT). The banking and financial services sector holds the largest share, given its stringent regulatory requirements and the need for strong risk management frameworks. Healthcare and IT sectors are also witnessing significant adoption due to concerns over data privacy, compliance, and cybersecurity risks. Other industries, including retail and manufacturing, are increasingly integrating third-party risk management solutions as part of their broader risk mitigation strategies.
Segmentations:
By Deployment Type
- On-premise
- Cloud-based
By Organization Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
By Vertical
- Banking and Financial Services
- Healthcare
- Manufacturing
- Retail
- Information Technology (IT)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the Third-Party Risk Management (TPRM) market with a 40% market share. This is largely due to the presence of large enterprises across industries such as banking, healthcare, finance, and manufacturing, which face significant regulatory pressures and complex risk environments. The adoption of TPRM solutions is driven by increasing cyber threats and stringent compliance requirements, including data privacy regulations like GDPR and industry-specific laws like HIPAA. The demand for digital transformation and the need to ensure operational continuity further accelerate market growth in this region.
Europe
Europe holds the second-largest market share at 30%. The region’s growth is fueled by a stringent regulatory environment, including the General Data Protection Regulation (GDPR), which compels organizations to adopt robust third-party risk management strategies. Businesses in sectors like finance, healthcare, and manufacturing are actively implementing TPRM solutions to address compliance and operational risks. Additionally, the increasing prevalence of cybersecurity threats and the need to secure third-party relationships further contribute to the region’s growth. Europe's advanced infrastructure and focus on data protection make it a key player in the TPRM market.
Asia Pacific
Asia Pacific, with a 20% market share, is expected to experience the highest growth rate. Rapid economic development in countries like China, India, and Japan has led to a growing reliance on third-party vendors, creating an urgent need for effective risk management. Regulatory reforms and a strong focus on digital transformation also support the market’s expansion. Companies in the region are increasingly adopting cloud-based TPRM solutions to streamline risk management, ensure compliance, and safeguard against data breaches and cyberattacks, driving substantial growth.
Latin America
Latin America, with a 5% market share, is seeing gradual growth as businesses become more aware of the risks posed by third-party vendors. The increasing adoption of cloud technologies and evolving regulatory changes are driving the demand for TPRM solutions. Sectors such as banking, finance, healthcare, and manufacturing are prioritizing risk management practices to address regulatory challenges and cybersecurity threats.
Middle East and Africa (MEA)
The Middle East and Africa region also holds 5% of the TPRM market share. While still developing, the market is seeing increasing interest in TPRM solutions driven by rapid digitalization, growing concerns about data privacy, and security risks. Industries such as finance, telecommunications, and energy are adopting TPRM solutions to ensure compliance and mitigate risks within their supply chains.
Key Player Analysis:
- IBM
- SAP
- RSA Security
- MetricStream
- LogicManager
- Prevalent
- RiskWatch
- Deloitte
- Coupa Software
- Aravo Solutions
Competitive Analysis:
The Third-Party Risk Management (TPRM) market is highly competitive, with numerous key players offering a range of solutions to address diverse customer needs. Prominent companies in this space include IBM, SAP, RSA Security, and MetricStream, all of which offer comprehensive platforms that integrate risk management, cybersecurity, and compliance solutions. These companies are investing heavily in AI and automation to enhance the effectiveness of their risk management processes and improve scalability for organizations of all sizes. Additionally, newer entrants are focusing on cloud-based solutions, catering to the growing demand for flexible, scalable risk management tools. For instance, LogicGate offers a cloud-based TPRM platform that allows businesses to customize workflows and automate risk assessments. As the market grows, partnerships and acquisitions are becoming more common as companies seek to expand their offerings and strengthen their positions. With increasing emphasis on data privacy and security, competition is expected to intensify, prompting ongoing innovation within the TPRM space.
Recent Developments:
- In June 2023, IBM, The Office of the Comptroller of the Currency (OCC), Federal Reserve Board, and FDIC released interagency guidance on TPRM for financial institutions, emphasizing the need for robust due diligence and ongoing monitoring of third-party relationships.
- In December 2024, SAP's procurement strategies indicated a renewed focus on TPRM as a top priority for Chief Procurement Officers (CPOs), alongside cost reduction initiatives.
- In September 2023, RSA announced its commitment to government zero trust initiatives at the Billington CyberSecurity Summit. This includes leveraging open standards to enhance third-party risk management through improved identity access management.
Market Concentration & Characteristics:
The Third-Party Risk Management (TPRM) market is moderately concentrated, with several large players dominating the market, while numerous smaller and specialized vendors cater to niche segments. Major players such as IBM, SAP, and MetricStream account for a significant share, leveraging their extensive portfolios and global presence to offer comprehensive solutions. These companies focus on innovation through AI, automation, and cloud-based technologies to enhance scalability and streamline risk management processes. Additionally, the market includes emerging vendors that offer specialized tools designed to address specific aspects of third-party risk, such as cybersecurity and compliance. As demand for TPRM solutions increases, competition has intensified, leading to strategic partnerships, acquisitions, and the development of tailored solutions to meet the evolving needs of businesses across various industries. The market is characterized by rapid technological advancements, an emphasis on data privacy, and the growing importance of regulatory compliance.
Report Coverage:
The research report offers an in-depth analysis based on deployment type, organization size, vertical and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of third-party risk management solutions will continue to increase as organizations face growing regulatory and compliance requirements.
- The integration of artificial intelligence and machine learning will enhance the efficiency and accuracy of risk assessments.
- Cloud-based solutions will become the dominant deployment model due to their scalability, flexibility, and cost-efficiency.
- Organizations will prioritize continuous risk monitoring and real-time updates to mitigate potential third-party risks promptly.
- Cybersecurity will remain a central focus, with more businesses integrating robust security features into their TPRM frameworks.
- The rise in outsourcing and global supply chains will further drive the demand for comprehensive risk management solutions.
- Data privacy concerns will lead to the development of more advanced tools to ensure compliance with regulations like GDPR.
- Small and medium-sized enterprises (SMEs) will increasingly adopt TPRM solutions as costs decrease and cloud-based options become more accessible.
- The market will see further consolidation, with larger players acquiring smaller firms to enhance their capabilities and expand their offerings.
- The Asia Pacific region will experience rapid growth as businesses in emerging markets adopt third-party risk management solutions to secure their expanding supply chains.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Third-Party Risk Management (TPRM) market?
What are the key drivers for the growth of the TPRM market?
Why are organizations prioritizing third-party risk management solutions?
Which region holds the largest share of the TPRM market?
Which region is expected to experience the highest growth in the TPRM market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,237.60 million → 2032: USD 19,792.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Third Party Risk Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Third Party Risk Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Third Party Risk Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Third Party Risk Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Third Party Risk Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Third Party Risk Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Third Party Risk Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Third Party Risk Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,237.60 million → 2032: USD 19,792.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Third Party Risk Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Third Party Risk Management Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Third Party Risk Management Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Third Party Risk Management Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
