
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Thrombolytic Drugs Market Size 2024 | USD 3,110.41 million |
| Thrombolytic Drugs Market, CAGR | 8.23% |
| Thrombolytic Drugs Market Size 2032 | USD 6,125.41 million |
Market Overview
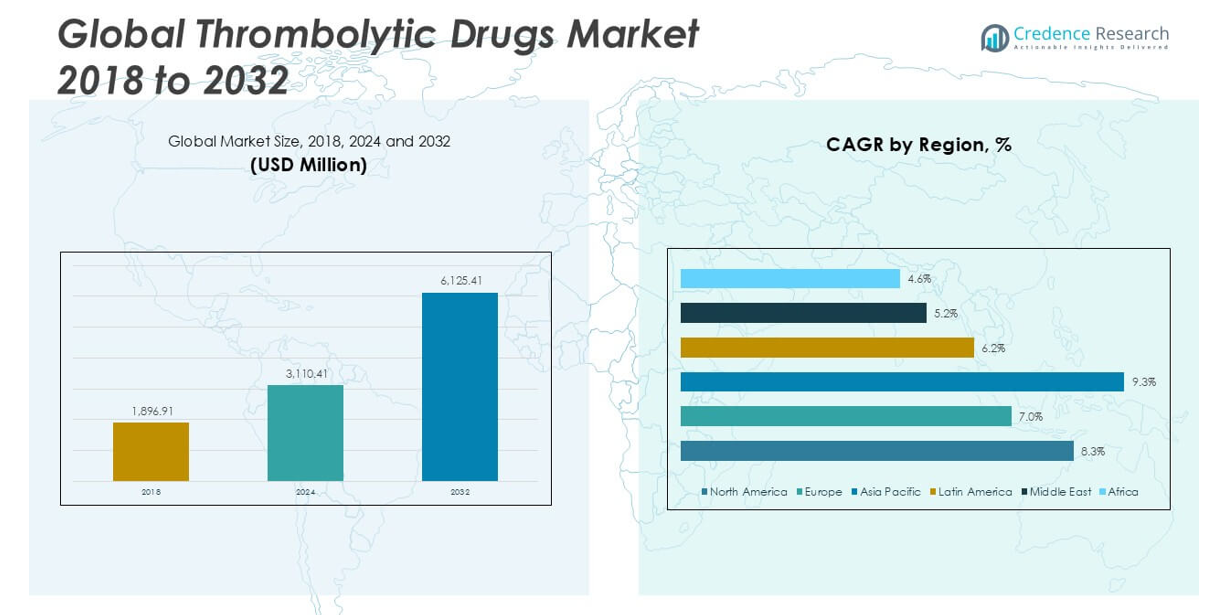
The Thrombolytic Drugs Market size was valued at USD 1,896.91 million in 2018, grew to USD 3,110.41 million in 2024, and is anticipated to reach USD 6,125.41 million by 2032, at a compound annual growth rate (CAGR) of 8.23% during the forecast period.
The Thrombolytic Drugs Market is experiencing robust growth, driven by the rising global incidence of cardiovascular diseases and stroke, which demand rapid and effective treatment solutions. Increased awareness about the benefits of early intervention in thrombotic events, advancements in drug formulations, and the growing adoption of minimally invasive procedures support market expansion. Healthcare systems are prioritizing timely management of acute conditions such as myocardial infarction and pulmonary embolism, fueling the demand for thrombolytic agents. Strategic initiatives by key players to enhance product portfolios and expand geographic presence further contribute to market development. However, the risk of adverse effects and the availability of alternative treatments pose challenges to wider adoption. Despite these restraints, ongoing clinical research and regulatory approvals for novel thrombolytic drugs are expected to sustain market momentum, while the increasing burden of lifestyle-related diseases continues to create long-term growth opportunities for industry participants.
The Thrombolytic Drugs Market demonstrates significant growth potential across key regions including North America, Europe, and Asia Pacific, driven by rising incidence of cardiovascular diseases and improvements in healthcare infrastructure. North America maintains a leading position due to its advanced hospital networks and high adoption of innovative therapies, while Europe benefits from strong regulatory frameworks and increasing emergency care accessibility. Asia Pacific experiences rapid market expansion, fueled by growing healthcare investments and heightened awareness of acute thrombotic disorders in countries such as China, India, and Japan. The market landscape features prominent players such as Genentech (F. Hoffmann-La Roche), Abbott Laboratories, and Boehringer Ingelheim, who leverage research advancements, broad product portfolios, and strategic regional partnerships to sustain their leadership. These companies, along with emerging local manufacturers, continue to shape the evolving competitive environment and meet diverse clinical needs worldwide.
Market Insights
- The Thrombolytic Drugs Market was valued at USD 3,110.41 million in 2024 and is expected to reach USD 6,125.41 million by 2032, with a CAGR of 8.23% over the forecast period.
- Growing prevalence of cardiovascular diseases and stroke continues to drive strong demand for rapid clot-dissolving therapies worldwide.
- Advances in drug formulations, precision medicine, and minimally invasive procedures are shaping product innovation and improving patient outcomes.
- Intense competition exists among global players, with Genentech (F. Hoffmann-La Roche), Abbott Laboratories, Boehringer Ingelheim, and emerging regional companies investing in research, product launches, and geographic expansion.
- Safety concerns such as bleeding risks and the availability of alternative treatments, including mechanical thrombectomy, limit broader adoption of thrombolytic drugs.
- North America leads the market with a 42.4% share and is supported by established healthcare systems and high awareness, while Asia Pacific rapidly expands, holding a 35.5% share due to rising healthcare investment and growing disease burden.
- Regulatory complexity, reimbursement policies, and evolving clinical guidelines influence market access and competitive positioning across major regions.
Market Drivers
Rising Prevalence of Cardiovascular Diseases and Stroke Fuels Demand
The Thrombolytic Drugs Market benefits significantly from the increasing global burden of cardiovascular diseases and stroke. Populations in both developed and developing regions face higher rates of risk factors such as hypertension, diabetes, obesity, and sedentary lifestyles, driving a steady demand for effective thrombolytic therapy. Hospitals and clinics require immediate solutions for acute myocardial infarction, pulmonary embolism, and ischemic stroke, creating a consistent need for these drugs. Healthcare providers prioritize early intervention protocols to reduce morbidity and mortality, further strengthening market growth. Strong epidemiological trends and a growing patient base support long-term expansion prospects for the market.
- For instance, Genentech’s tissue plasminogen activator (tPA), alteplase, has been used to treat over 2 million stroke patients globally, highlighting its clinical importance and widespread adoption.
Advancements in Drug Formulation and Delivery Technologies Accelerate Adoption
Innovative drug formulations and improved delivery methods drive progress in the Thrombolytic Drugs Market. Pharmaceutical manufacturers focus on developing agents with greater specificity, reduced bleeding risks, and enhanced efficacy. New recombinant products and next-generation molecules provide better patient outcomes and shorter hospital stays. The market sees an influx of research investments in alternative delivery technologies, such as catheter-directed thrombolysis, supporting adoption across diverse clinical settings. Technological progress helps overcome traditional limitations, broadening acceptance among healthcare professionals.
- For instance, Boehringer Ingelheim’s tenecteplase has been approved in over 90 countries and demonstrated a reduction in median hospital stay from 7 days to 5 days for acute myocardial infarction patients, according to the ASSENT-2 clinical trial.
Healthcare Infrastructure Expansion and Increased Treatment Accessibility
Expanding healthcare infrastructure, especially in emerging economies, strengthens the Thrombolytic Drugs Market. Governments and private sector investments in hospitals, emergency care, and diagnostic centers make advanced treatments more accessible. It benefits from improved reimbursement policies and the inclusion of thrombolytic therapies in standard treatment protocols. Widening access to healthcare services enables earlier intervention, driving adoption in both urban and rural regions. Rising public and private health expenditures sustain positive momentum for the market.
Strategic Initiatives by Industry Leaders to Strengthen Market Presence
Industry leaders in the Thrombolytic Drugs Market implement strategic partnerships, acquisitions, and product launches to expand their presence. Companies invest in clinical research and global regulatory approvals to bring novel therapies to market. Robust marketing strategies and educational programs help build awareness among healthcare providers and patients. It leverages these initiatives to maintain competitive differentiation and capture emerging growth opportunities. Strategic moves by key players contribute to a dynamic and resilient market environment.
Market Trends
Increasing Emphasis on Minimally Invasive Procedures Shapes Market Dynamics
The Thrombolytic Drugs Market reflects a strong shift toward minimally invasive procedures for treating thrombotic disorders. Interventional radiology and catheter-directed thrombolysis are gaining traction among healthcare professionals due to lower complication risks and faster recovery times. Hospitals invest in advanced imaging and delivery technologies to support precise administration of thrombolytic agents. Patients show a growing preference for less invasive options that allow for shorter hospital stays and quicker returns to normal activities. It capitalizes on these trends by integrating new drug formulations with evolving procedural techniques, thereby strengthening its relevance in contemporary medical practice.
- For instance, the EKOS Endovascular System by Boston Scientific has been used in more than 100,000 cases worldwide, with studies reporting a 50% reduction in pulmonary embolism treatment time compared to conventional methods.
Emergence of Next-Generation Biologics and Recombinant Agents
A surge in the development of next-generation biologics and recombinant thrombolytic agents characterizes the Thrombolytic Drugs Market. Pharmaceutical innovators focus on molecules with improved safety profiles and enhanced clot-dissolving capabilities. Recent clinical trials have produced agents that demonstrate superior efficacy with fewer adverse effects, supporting widespread adoption in critical care settings. The market witnesses a pipeline of novel drugs, some targeting specific patient populations or unique thrombotic conditions. It benefits from ongoing research partnerships between academic institutions and leading industry players, driving continuous innovation in product offerings.
- For instance, Chiesi Farmaceutici’s recombinant prourokinase has been evaluated in more than 3,000 patients in multicenter trials, demonstrating notable efficacy in the treatment of acute myocardial infarction.
Rising Focus on Early Diagnosis and Rapid Intervention Strategies
Healthcare systems place significant importance on early diagnosis and rapid intervention for thrombotic events, fueling demand in the Thrombolytic Drugs Market. Diagnostic advancements such as point-of-care testing and high-resolution imaging contribute to quicker decision-making and timely drug administration. Protocols emphasizing immediate treatment have been incorporated into stroke and cardiac care pathways worldwide. The market responds by aligning product development with these evolving clinical workflows. It supports improved patient outcomes and aligns with broader healthcare priorities focused on reducing long-term complications.
Expansion of Geographic Reach and Penetration in Emerging Markets
Global players in the Thrombolytic Drugs Market pursue strategies that expand their geographic reach, particularly in Asia Pacific, Latin America, and the Middle East. Investments in supply chain optimization, regulatory compliance, and local partnerships enable companies to access underserved patient populations. Economic growth and healthcare reforms in these regions create favorable environments for market entry and expansion. It adapts by tailoring product portfolios to meet diverse clinical and regulatory requirements. This trend enhances market resilience and ensures continued growth across both mature and developing healthcare landscapes.
Market Challenges Analysis
Concerns over Safety Profile and Risk of Adverse Events Limit Adoption
The Thrombolytic Drugs Market faces persistent challenges related to the safety profile and risk of adverse events associated with these therapies. Bleeding complications, particularly intracranial hemorrhage, remain a major barrier to widespread clinical adoption. Healthcare providers often hesitate to administer thrombolytic agents to patients with comorbidities or elevated risk factors. Strict patient selection criteria and monitoring protocols reduce the eligible treatment population, limiting overall market expansion. It must address these safety concerns through improved drug formulations and clearer clinical guidelines to build trust among physicians and patients. Efforts to enhance pharmacovigilance and post-marketing surveillance are critical for overcoming these limitations.
Regulatory Hurdles and Availability of Alternative Treatments Impede Growth
Navigating complex regulatory environments poses another significant challenge for the Thrombolytic Drugs Market. Obtaining approvals for new formulations or expanding indications requires extensive clinical data, which prolongs time-to-market and raises development costs. Variability in national regulations further complicates global commercialization efforts. The market also contends with the increasing availability of alternative treatment options, including mechanical thrombectomy and anticoagulant drugs, which offer different risk-benefit profiles. It must demonstrate clear clinical advantages and cost-effectiveness to compete successfully in a crowded therapeutic landscape. Market participants invest in evidence-based studies and health economics research to address these competitive and regulatory obstacles.
Market Opportunities
Advancements in Precision Medicine and Biomarker-Guided Therapies Create New Avenues
The Thrombolytic Drugs Market holds significant opportunity through the integration of precision medicine and biomarker-guided therapies. Advances in genetic profiling and molecular diagnostics enable tailored treatment approaches that optimize drug selection and dosing for individual patients. It can leverage these technologies to reduce adverse effects and improve efficacy, addressing a long-standing clinical challenge. Pharmaceutical companies have strong potential to develop companion diagnostics that support real-time therapeutic decisions in acute care settings. Early identification of high-risk patients enables faster and safer intervention, fostering greater confidence among clinicians. The market stands to benefit from expanded adoption in specialized centers and multidisciplinary care pathways.
Expanding Access and Awareness in Emerging Economies Drives Future Growth
Wider access to healthcare services and increasing awareness of thrombotic conditions present strong growth prospects for the Thrombolytic Drugs Market. Economic development and healthcare infrastructure investments in Asia Pacific, Latin America, and Africa drive greater demand for advanced therapies. It can capitalize on these trends by collaborating with local stakeholders and adapting products to suit regional needs. Strategic education initiatives and outreach programs play a pivotal role in building patient and physician understanding of timely thrombolytic intervention. Expansion of reimbursement frameworks further supports broader usage in both public and private healthcare sectors. The market remains well-positioned to capture unmet medical needs and address rising disease prevalence in these regions.
Market Segmentation Analysis:
By Drug Class:
Tissue plasminogen activators (tPAs) command a significant share due to their high efficacy and targeted mechanism of action in dissolving clots. Clinicians prefer tPAs for acute conditions such as ischemic stroke and myocardial infarction because they enable rapid intervention and improve patient outcomes. Streptokinase derivatives remain a viable option, particularly in resource-constrained settings, given their cost-effectiveness and broad clinical experience. Urokinase-type plasminogen activators (uPAs) offer alternative options, especially for patients who cannot tolerate other drug classes or require specific therapeutic approaches.
- For instance, Abbott Laboratories’ urokinase has been administered in over 1.5 million procedures worldwide for the management of pulmonary embolism and deep vein thrombosis.
By Indication:
Segmenting the Thrombolytic Drugs Market by indication highlights the dominance of ischemic stroke and myocardial infarction. Hospitals and emergency departments prioritize thrombolytic therapy for these critical events due to the need for immediate reperfusion to prevent long-term disability or fatality. Pulmonary embolism and deep vein thrombosis also represent key segments, reflecting the rising incidence of venous thromboembolic disorders globally. Catheter occlusion management and a category for other indications round out the market, allowing manufacturers to address a broader range of clinical needs and expand their product portfolios. Each indication segment benefits from protocol-driven interventions and growing awareness of the importance of early thrombolytic therapy.
- For instance, Microbix Biosystems’ recombinant streptokinase has been used in more than 500,000 catheter occlusion procedures, supporting its relevance in critical care interventions.
By End-Use:
Hospitals constitute the largest share of the Thrombolytic Drugs Market. Hospitals are the primary treatment centers for acute thrombotic events and possess the infrastructure needed for advanced diagnosis and rapid drug administration. Ambulatory surgical centers represent a growing segment, benefiting from the shift toward outpatient procedures and faster patient turnover. The "others" category includes specialized clinics and urgent care centers that support decentralized access to thrombolytic therapy, particularly in rural or underserved regions. It leverages the expansion of healthcare infrastructure and broader access to emergency services to drive sustained demand across all end-use segments.
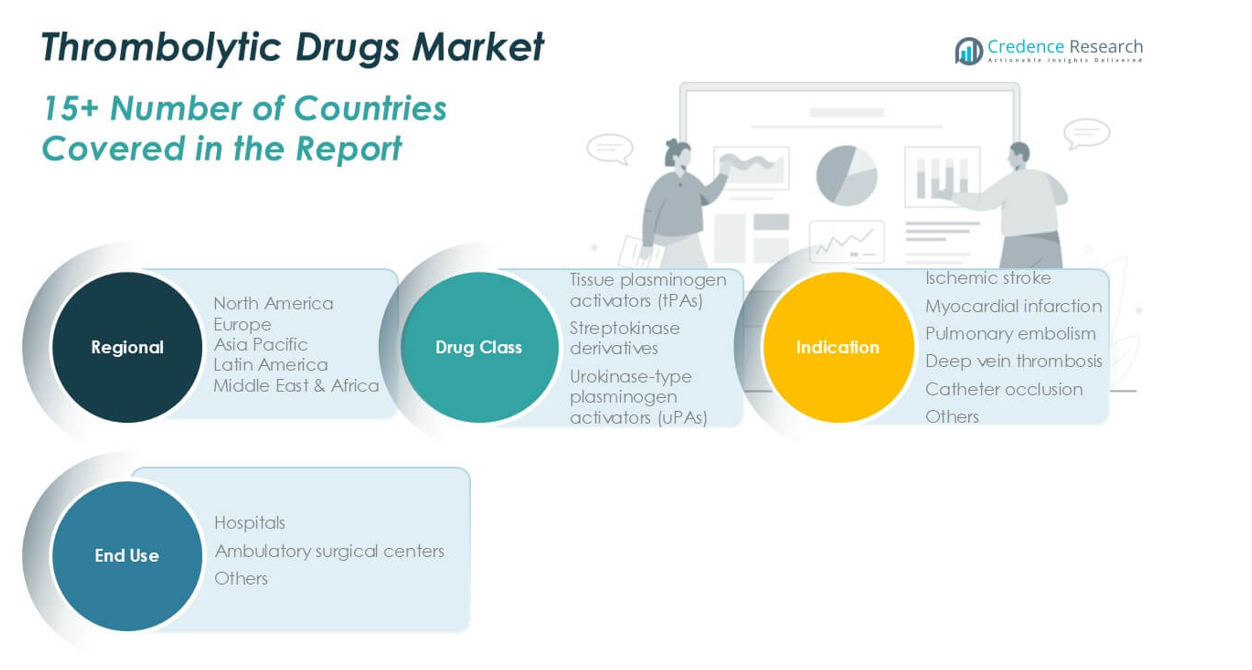
Segments:
Based on Drug Class:
- Tissue plasminogen activators (tPAs)
- Streptokinase derivatives
- Urokinase-type plasminogen activators (uPAs)
Based on Indication:
- Ischemic stroke
- Myocardial infarction
- Pulmonary embolism
- Deep vein thrombosis
- Catheter occlusion
- Others
Based on End-Use:
- Hospitals
- Ambulatory surgical centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Thrombolytic Drugs Market
North America Thrombolytic Drugs Market grew from USD 810.83 million in 2018 to USD 1,315.44 million in 2024 and is projected to reach USD 2,597.88 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.3%. North America is holding a 42.4% market share. The United States and Canada drive demand due to high healthcare spending, rapid adoption of advanced therapies, and an elevated incidence of cardiovascular diseases. It benefits from a robust network of hospitals and specialized stroke centers that prioritize rapid thrombolytic intervention. Favorable reimbursement policies and continuous clinical research reinforce its dominant market position. High awareness and established treatment protocols further stimulate sustained growth across the region.
Europe Thrombolytic Drugs Market
Europe Thrombolytic Drugs Market grew from USD 355.58 million in 2018 to USD 551.23 million in 2024 and is expected to reach USD 987.56 million by 2032, with a CAGR of 7.0%. Europe accounts for 16.1% of the total market share. Key contributors include Germany, the United Kingdom, France, and Italy, where government initiatives and improved access to emergency care support market expansion. It is characterized by strong regulatory oversight and high standards for product approval, driving adoption of clinically proven therapies. Increasing investments in healthcare infrastructure and ongoing training for medical staff help address growing demand. Regional clinical guidelines and collaborations among academic centers promote widespread utilization.
Asia Pacific Thrombolytic Drugs Marke
Asia Pacific Thrombolytic Drugs Marke grew from USD 590.38 million in 2018 to USD 1,018.24 million in 2024 and is forecast to reach USD 2,174.55 million by 2032, achieving a CAGR of 9.3%. Asia Pacific represents 35.5% market share, led by China, Japan, India, and Australia. Rising urbanization and a growing prevalence of cardiovascular and thrombotic disorders drive significant demand. It leverages expanding healthcare infrastructure and increasing government spending on emergency medical care. Pharmaceutical companies focus on affordable formulations and local manufacturing, catering to the diverse needs of this region. Public awareness campaigns and improved access to acute care centers accelerate market growth.
Latin America Thrombolytic Drugs Market
Latin America Thrombolytic Drugs Market grew from USD 73.14 million in 2018 to USD 118.11 million in 2024 and will likely reach USD 199.77 million by 2032, reflecting a CAGR of 6.2%. Latin America holds a 3.3% market share, with Brazil, Mexico, and Argentina as leading countries. It benefits from incremental improvements in healthcare systems and growing investments in hospital infrastructure. Broader insurance coverage and ongoing physician education encourage the adoption of thrombolytic therapy. Challenges remain due to resource constraints, but innovative distribution strategies help address rural and remote areas. Demand continues to rise in major metropolitan centers.
Middle East Thrombolytic Drugs Market
Middle East Thrombolytic Drugs Market grew from USD 41.96 million in 2018 to USD 61.32 million in 2024 and is projected to reach USD 96.25 million by 2032, registering a CAGR of 5.2%. The Middle East accounts for 1.6% of global market share. The United Arab Emirates, Saudi Arabia, and Israel are at the forefront of market growth, supported by expanding private healthcare facilities and investments in specialty care. It responds to increasing incidence of cardiovascular diseases and stroke with improved emergency response capabilities. Limited access in certain regions remains a challenge, but new public health initiatives are driving greater awareness.
Africa Thrombolytic Drugs Market
Africa Thrombolytic Drugs Market grew from USD 25.02 million in 2018 to USD 46.07 million in 2024 and is expected to reach USD 69.41 million by 2032, with a CAGR of 4.6%. Africa represents 1.1% market share. South Africa, Egypt, and Nigeria lead regional demand, benefiting from gradual healthcare reforms and targeted investments in critical care infrastructure. It faces challenges such as limited resources and unequal access to advanced therapies, but international aid and local initiatives are helping bridge care gaps. Efforts to expand physician training and improve rural healthcare delivery support the market’s long-term potential.
Key Player Analysis
- Genentech (F. Hoffmann-La Roche)
- Gennova Biopharmaceuticals
- Abbott Laboratories
- Boehringer Ingelheim
- Chiesi Farmaceutici
- MicrobixBiosystems
- Reliance Lifesciences
- Karma Pharmatech
- Lupin
- TechpoolBio-Pharma
Competitive Analysis
The Thrombolytic Drugs Market features a competitive landscape marked by innovation, strategic collaborations, and global expansion. Leading players such as Genentech (F. Hoffmann-La Roche), Gennova Biopharmaceuticals, Abbott Laboratories, Boehringer Ingelheim, Chiesi Farmaceutici, MicrobixBiosystems, Reliance Lifesciences, Karma Pharmatech, Lupin, and TechpoolBio-Pharma hold prominent positions through their extensive product portfolios and established distribution networks. These companies invest heavily in research and development to introduce next-generation thrombolytic agents with improved efficacy and safety profiles. Strategic acquisitions and partnerships enable market leaders to diversify offerings and strengthen their presence in emerging markets. Continuous product innovation and a strong focus on regulatory compliance help these firms maintain a competitive edge. Regional companies, particularly in Asia Pacific, also contribute to the dynamic nature of the market by addressing local demand and offering cost-effective solutions. Pricing strategies, robust marketing efforts, and physician engagement programs support brand loyalty and market share retention. Competitive intensity remains high, with new entrants and established players striving to capture unmet medical needs and expand their reach across both mature and developing healthcare landscapes
Recent Developments
- In March 2025, Genentech received FDA approval for TNKase (tenecteplase) for the treatment of acute ischemic stroke in adults. TNKase administration is a single, five second IV bolus that simplifies the emergency care necessitated by the conventional multi-step protocol. This development enhances clinical efficiency in treatment of stroke. This approval likely marked an advancement in accelerate growth in the market.
- In February 2025, Boehringer Ingelheim introduced a new acute ischemic stroke medication product containing Tenecteplase 25mg in the UAE, which seeks to enhance the treatment of strokes in emergencies by offering rapid and efficient therapy for critically ill patients. This launch is aimed at expanding effective product accessibility enhancing the patient recovery outcome with minimizing long-term treatments.
- In September 2024, The Thrombolytics Science Strike Industrial (TSI) received an FDA approval for the Investigational New Drug application of mutant prourokinase (mproUK), a recombinant fibrinolytic pro-enzyme. The clinical study was conducted in U.S. confirming mproUK’s safety in healthy volunteers and underlines its capability to transform treatment paradigms for thrombotic disorders through rapid and safer reperfusion. This development puts TSI in a position to shape innovation and increase competition in the thrombolytic drugs industry.
Market Concentration & Characteristics
The Thrombolytic Drugs Market demonstrates a moderate to high level of market concentration, with a small number of multinational pharmaceutical companies controlling a significant portion of global revenues. It features established players such as Genentech (F. Hoffmann-La Roche), Abbott Laboratories, and Boehringer Ingelheim, who drive industry standards through innovation, extensive product lines, and global distribution networks. The market is characterized by stringent regulatory requirements, a focus on clinical efficacy and safety, and ongoing investment in research and development for next-generation thrombolytic agents. It sees steady demand from acute care settings, supported by growing awareness of cardiovascular emergencies and the expansion of emergency medical services worldwide. Barriers to entry remain high due to the complexity of drug development, rigorous approval processes, and the need for substantial capital investment. Regional companies also compete by offering cost-effective alternatives and addressing specific local needs, contributing to a dynamic and evolving competitive landscape
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Material, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for thrombolytic drugs is expected to rise due to the increasing incidence of cardiovascular and cerebrovascular diseases.
- Ongoing research and development activities are likely to introduce more effective and targeted thrombolytic agents.
- The aging global population will contribute significantly to the growing need for clot-dissolving therapies.
- Rising awareness about the early treatment of stroke and heart attacks will boost market penetration.
- Healthcare infrastructure improvements in emerging economies will enhance accessibility to thrombolytic treatments.
- Regulatory support for fast-track approvals of life-saving drugs may accelerate product launches.
- Strategic collaborations among pharmaceutical companies are anticipated to drive innovation in thrombolytic therapies.
- Increased use of advanced diagnostics and imaging techniques will aid in timely administration of thrombolytics.
- The growing popularity of catheter-directed thrombolysis procedures is expected to support market expansion.
- Challenges such as bleeding risks and high treatment costs may spur the development of safer and more affordable alternatives.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases and Stroke
The increasing global incidence of cardiovascular diseases and stroke is driving demand for rapid and effective thrombolytic therapies, as hospitals and clinics require immediate solutions for acute events like myocardial infarction and ischemic stroke.
Advancements in Drug Formulation and Delivery Technologies
Innovations in drug formulations, such as next-generation recombinant agents and improved delivery methods like catheter-directed thrombolysis, are enhancing efficacy and safety, leading to broader adoption among healthcare providers.
Expansion of Healthcare Infrastructure and Accessibility
Growing investments in hospitals, emergency care, and diagnostic centers, especially in emerging economies, are making advanced thrombolytic treatments more accessible, supporting earlier intervention and higher adoption rates.
Strategic Initiatives and Product Launches by Industry Leaders
Major pharmaceutical companies are investing in research, clinical trials, and global regulatory approvals, as well as launching new products and forming strategic partnerships, which expand their market presence and drive overall market growth.
Increasing Emphasis on Early Diagnosis and Minimally Invasive Procedures
Healthcare systems are prioritizing early diagnosis and rapid intervention for thrombotic events, supported by advanced diagnostics and a shift toward minimally invasive procedures, which increases the timely use of thrombolytic drugs and improves patient outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Thrombolytic Drugs Market?
What factors are driving the growth of the Thrombolytic Drugs Market?
What are some challenges faced by the Thrombolytic Drugs Market?
Who are the major players in the Thrombolytic Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory surgical centers
- 1.2.3 Others
- 1.3 By Drug Class
- 1.3.1 Tissue plasminogen activators (tPAs)
- 1.3.2 Streptokinase derivatives
- 1.3.3 Urokinase-type plasminogen activators (uPAs)
- 1.4 By Indication
- 1.4.1 Ischemic stroke
- 1.4.2 Myocardial infarction
- 1.4.3 Pulmonary embolism
- 1.4.4 Deep vein thrombosis
- 1.4.5 Catheter occlusion
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,110.41 million → 2032: USD 6,125.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Thrombolytic Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Thrombolytic Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Thrombolytic Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Thrombolytic Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Thrombolytic Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Thrombolytic Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Thrombolytic Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Thrombolytic Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,110.41 million → 2032: USD 6,125.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Thrombolytic Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory surgical centers
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tissue plasminogen activators (tPAs)
- 12.4.7.2 Streptokinase derivatives
- 12.4.7.3 Urokinase-type plasminogen activators (uPAs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ischemic stroke
- 12.5.7.2 Myocardial infarction
- 12.5.7.3 Pulmonary embolism
- 12.5.7.4 Deep vein thrombosis
- 12.5.7.5 Catheter occlusion
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Thrombolytic Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Thrombolytic Drugs Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Thrombolytic Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Thrombolytic Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Genentech (F. Hoffmann-La Roche)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 Boehringer Ingelheim
- 18.5 Chiesi Farmaceutici
- 18.6 Gennova Biopharmaceuticals
- 18.7 Microbix Biosystems
- 18.8 Reliance Lifesciences
- 18.9 Lupin
- 18.10 Techpool Bio-Pharma
- 18.11 Karma Pharmatech
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

