
Market Overview:
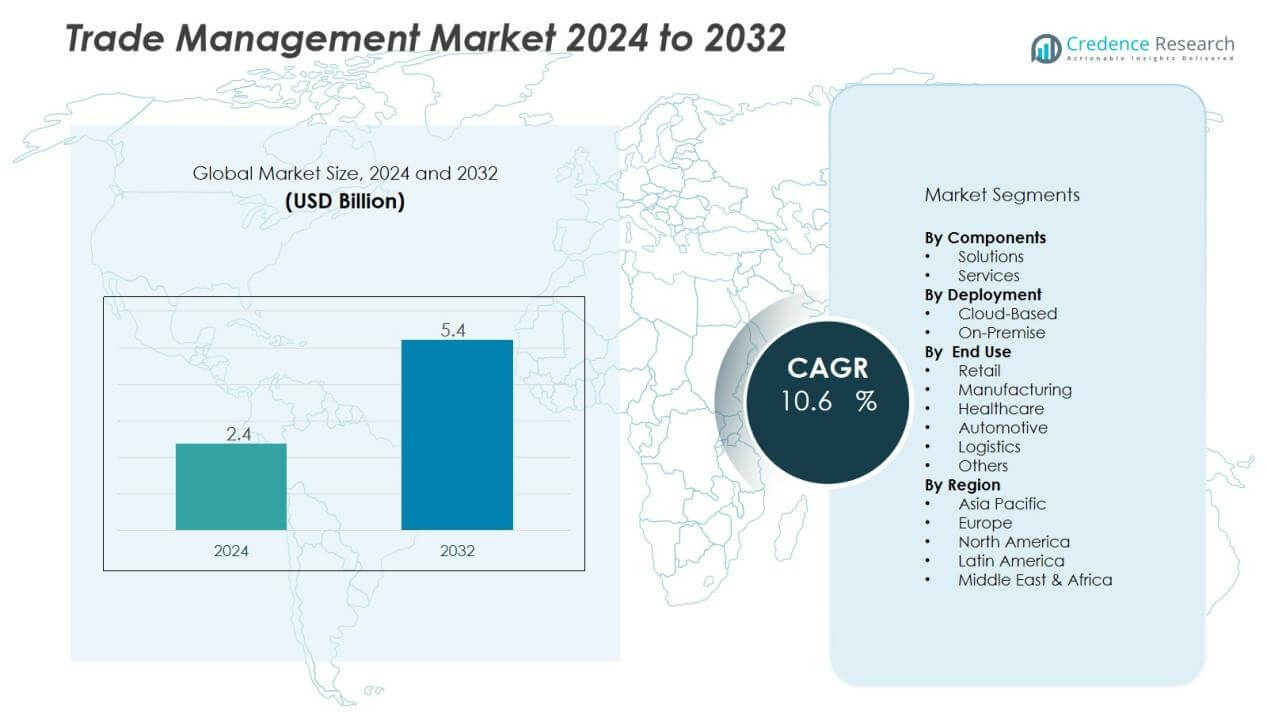
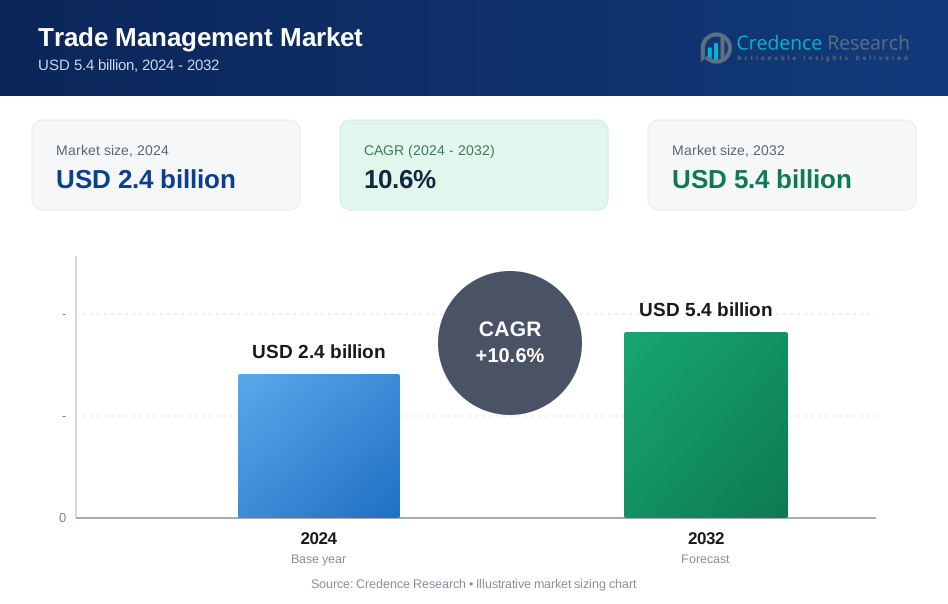
The trade management market size was valued at USD 2.4 billion in 2024 and is anticipated to reach USD 5.4 billion by 2032, at a CAGR of 10.6% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trade Management Market Size 2024 | USD 1.9 Billion |
| Trade Management Market, CAGR | 14.6% |
| Trade Management Market Size 2032 | USD 5.7 Billion |
Key drivers include rising globalization, regulatory complexity, and the need for real-time visibility across supply chains. Companies are investing in advanced trade management solutions to manage customs compliance, tariff classification, and duty management effectively. Adoption of cloud-based systems and integration with artificial intelligence (AI) and blockchain further enhance automation, predictive analytics, and security. The growing emphasis on risk management and cost reduction also fuels demand among multinational enterprises.
Regionally, North America holds the largest share due to strong adoption of advanced technologies and established trade networks. Europe follows, supported by stringent regulatory frameworks and cross-border trade within the EU. Asia-Pacific is expected to record the fastest growth, driven by booming exports, rising e-commerce, and government initiatives promoting digital trade infrastructure. Latin America and the Middle East & Africa show emerging potential, supported by ongoing trade modernization and logistics development.
Market Insights:
- The trade management market was valued at USD 2.4 billion in 2024 and is expected to reach USD 5.4 billion by 2032.
- Rising globalization and complex supply chains fuel demand for advanced compliance and logistics platforms.
- Companies adopt AI, blockchain, and cloud-based systems to enhance automation, visibility, and cost efficiency.
- Regulatory complexity and risk management needs drive enterprises to invest in reliable compliance platforms.
- High implementation costs and integration challenges remain barriers, especially for small and medium enterprises.
- North America leads with 38% share, supported by advanced technologies and established trade infrastructure.
- Asia-Pacific emerges as the fastest-growing region, driven by exports, e-commerce, and digital trade initiatives.
Market Drivers:
Rising Global Trade Volumes and Increasing Complexity of Supply Chains:
The trade management market benefits from expanding international trade and interconnected supply chains. Companies face growing complexity in managing cross-border transactions, tariffs, and logistics. It creates strong demand for systems that streamline operations while ensuring compliance with international trade rules. Businesses seek advanced solutions to enhance visibility, reduce manual errors, and maintain competitiveness.
- For instance, UPS Global Checkout launched in March 2025 and is available in 43 origin countries, delivering to over 200 destinations with fully pre-calculated duties and taxes to eliminate surprise fees at checkout.
Growing Focus on Regulatory Compliance and Risk Management:
Tightening global trade regulations drive companies to adopt reliable compliance management platforms. Organizations must handle customs documentation, tax duties, and product classifications with accuracy to avoid penalties. The trade management market addresses these challenges by providing automated solutions that reduce compliance risks. It helps enterprises improve governance, maintain audit readiness, and align with trade policies.
- For Instance, Sprinto's automated compliance dashboard updates in real-time with your compliance status, aligned with ISO 27001 and GDPR frameworks. By automating key workflows, the platform significantly reduces manual tasks, helping firms achieve continuous audit readiness and streamline compliance efforts.
Adoption of Digital Technologies to Enhance Efficiency and Transparency:
Cloud-based platforms, artificial intelligence, and blockchain integration strengthen efficiency in global trade operations. These technologies offer predictive analytics, real-time tracking, and secure data sharing across networks. The trade management market grows as companies adopt digital tools to optimize costs and decision-making. It empowers enterprises to achieve faster trade execution and stronger partner collaboration.
Rising Demand for Cost Optimization and Competitive Advantage:
Companies face pressure to minimize operational costs while sustaining global competitiveness. Automated trade management solutions reduce manual labor, eliminate redundant processes, and optimize duty spending. The trade management market plays a key role in supporting cost reduction strategies. It enables businesses to gain efficiency, strengthen supply chain resilience, and maintain profitability in dynamic markets.
Market Trends:
Integration of Advanced Technologies to Transform Trade Operations:
The trade management market is witnessing strong adoption of advanced technologies such as artificial intelligence, blockchain, and cloud-based platforms. Companies implement AI-driven analytics to forecast demand, optimize tariffs, and improve compliance accuracy. Blockchain supports secure and transparent data exchange, enhancing trust across global supply chains. Cloud deployment expands access to scalable and cost-efficient solutions for enterprises of all sizes. It enables real-time tracking of shipments, automates trade documentation, and reduces the risk of human error. The shift toward digital-first operations positions trade management solutions as vital enablers of global competitiveness.
- For instance, the TradeLens platform, developed by IBM and A.P. Moller–Maersk, processed 42 million container shipments on its blockchain network.
Rising Emphasis on Sustainable Trade Practices and Supply Chain Resilience:
Sustainability and resilience have become key priorities in global trade management. Organizations aim to reduce carbon footprints by adopting energy-efficient logistics and digital reporting tools. The trade management market reflects this shift, with growing demand for platforms that monitor environmental impact while ensuring compliance with green trade policies. Companies also prioritize risk mitigation strategies to handle disruptions caused by geopolitical tensions, pandemics, or supply shortages. It fosters the adoption of solutions that offer predictive risk management and flexible sourcing models. The increasing alignment of trade practices with sustainability goals strengthens the long-term growth trajectory of digital trade platforms.
- For example, Salesforce's Net Zero Cloud platform helps organizations track scope 1, 2, and 3 emissions with detailed environmental data, providing a unified view to manage carbon footprints and supporting annual emissions reduction reporting.
Market Challenges Analysis:
High Implementation Costs and Complexity of Integration:
The trade management market faces challenges due to the high cost of deployment and integration. Small and medium enterprises often struggle to adopt advanced solutions because of limited budgets. Complex global trade networks require customization, making implementation more resource-intensive. It creates longer adoption cycles and slows down market penetration in emerging economies. Businesses must also invest in skilled professionals to manage these systems effectively. The financial burden of software, infrastructure, and training reduces accessibility for smaller players.
Constantly Changing Regulatory Landscape and Data Security Risks:
Global trade regulations frequently change, creating compliance hurdles for companies operating across multiple regions. The trade management market must adapt quickly to support evolving tax rules, customs requirements, and trade agreements. It increases the risk of penalties and disrupts cross-border trade if updates are delayed. Data security also remains a concern due to rising cyber threats targeting sensitive trade information. Organizations must ensure strong cybersecurity measures while maintaining system efficiency. These challenges highlight the importance of innovation and resilience in trade management platforms.
Market Opportunities:
Expansion of Digital Trade Platforms and Cross-Border E-commerce Growth:
The trade management market holds significant opportunity through the expansion of cross-border e-commerce and digital trade platforms. Rapid growth in global online retail requires efficient systems to manage customs, tariffs, and shipping documentation. It creates demand for scalable, cloud-based trade solutions that support both large enterprises and small exporters. Businesses seek integrated platforms to enhance transparency, reduce delays, and improve customer satisfaction. Growing reliance on digital trade networks offers providers the chance to expand into new customer segments. This trend positions trade management solutions as key enablers of global e-commerce growth.
Adoption of AI-Driven Analytics and Sustainable Trade Solutions:
Artificial intelligence and predictive analytics present strong opportunities for advanced trade optimization. Companies are adopting AI to forecast demand, manage duties, and detect compliance risks in real time. The trade management market benefits from rising interest in sustainable practices, including carbon tracking and eco-friendly logistics. It encourages the development of solutions that align with environmental regulations and global sustainability goals. Enterprises that integrate smart and sustainable trade management tools gain a competitive advantage. These innovations create long-term opportunities for growth across industries and regions.
Market Segmentation Analysis:
By Components:
The trade management market is segmented into solutions and services, with solutions holding the dominant position. Enterprises prefer integrated platforms that manage compliance, documentation, and logistics in one system. It ensures cost savings, real-time visibility, and streamlined trade operations. Services including consulting, support, and training gain traction as companies seek expert guidance for complex implementations. Strong demand for both categories reflects the need for flexible and scalable trade management systems.
- For Instance, Thomson Reuters, ONESOURCE supports more than 21,000 businesses globally, including 100% of the Fortune 100 companies and 96% of the Fortune 1,000.
By Deployment:
Deployment is divided into cloud-based and on-premise models, with cloud solutions expanding at a faster pace. Companies adopt cloud platforms for scalability, cost efficiency, and accessibility across global networks. It provides real-time collaboration, secure data sharing, and automated updates. On-premise deployment remains relevant for industries with strict data security requirements and large-scale infrastructure. The growing digital-first trade environment continues to push organizations toward cloud adoption.
- For instance, Netflix leverages Amazon Web Services (AWS) cloud infrastructure to scale its streaming services seamlessly to over 238 million global subscribers, enabling real-time content delivery and automatic scaling during peak demand.
By End Use:
End-use segmentation includes retail, manufacturing, healthcare, automotive, logistics, and others. Large-scale industries like automotive and manufacturing drive demand with complex supply chains and regulatory requirements. The trade management market also grows in retail and e-commerce due to expanding cross-border transactions. It helps enterprises manage customs clearance, reduce delays, and maintain compliance with regional laws. Rising adoption across diverse industries highlights the universal importance of trade management platforms.
Segmentations:
By Components:
- Solutions
- Services
By Deployment:
- Cloud-Based
- On-Premise
By End Use:
- Retail
- Manufacturing
- Healthcare
- Automotive
- Logistics
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America holds 38% market share in the trade management market, making it the leading region. The region benefits from robust trade infrastructure, advanced logistics, and strong adoption of digital platforms. Enterprises in the United States drive demand through investments in automation, customs compliance, and predictive analytics. It is supported by regulatory frameworks that promote efficiency and secure trade practices. Canada and Mexico further contribute with growing cross-border trade and supply chain integration under USMCA agreements. The region’s strong technological ecosystem positions it as a key driver of innovation in trade management solutions.
Europe:
Europe accounts for 29% market share in the trade management market, supported by strict regulatory frameworks and active intra-regional trade. The European Union enforces harmonized policies that create demand for advanced compliance management tools. Enterprises adopt digital trade platforms to align with customs regulations, tax policies, and sustainability goals. It fosters growth in sectors such as automotive, manufacturing, and retail. Cross-border e-commerce also accelerates demand for efficient trade management solutions. Europe’s continued focus on regulatory compliance and sustainability strengthens the adoption of digital trade platforms.
Asia-Pacific:
Asia-Pacific secures 24% market share in the trade management market, emerging as the fastest-growing region. Strong export-driven economies such as China, Japan, and South Korea fuel rising adoption of digital trade systems. It is further supported by expanding e-commerce activity and government initiatives promoting digital infrastructure. India shows strong momentum with policy reforms encouraging global trade participation. Businesses in the region seek scalable, cloud-based platforms to manage growing transaction volumes efficiently. The rapid pace of digitalization positions Asia-Pacific as a future growth hub for trade management solutions.
Key Player Analysis:
- E 2open, LLC. (Amber Road, Inc.)
- Integration Point, Inc.
- Aptean
- Oracle
- Livingston International
- Noatum Logistics (MIQ Logistics, LLC)
- MIC.
- Precision Software LLC
- THE DESCARTES SYSTEMS GROUP INC
- Descartes QuestaWeb
Competitive Analysis:
The trade management market is highly competitive, driven by innovation, compliance needs, and global trade expansion. Key players include E2open, LLC. (Amber Road, Inc.), Integration Point, Inc., Aptean, Oracle, Livingston International, Noatum Logistics (MIQ Logistics, LLC), MIC, and Precision Software LLC. It reflects a diverse mix of technology providers, logistics specialists, and compliance solution experts catering to multinational enterprises. Companies focus on developing scalable cloud-based platforms, integrating AI, and enhancing automation to strengthen operational efficiency. Strategic partnerships and acquisitions remain common as firms expand geographic reach and service capabilities. Continuous investment in digital infrastructure, risk management, and regulatory compliance solutions helps players sustain competitiveness. The market’s fragmented nature drives companies to differentiate through specialized services, sector-focused offerings, and strong customer support networks.
Recent Developments:
- In August 2025, WiseTech Global completed the acquisition of E2open in an all-cash transaction valued at $2.1 billion, expanding its product portfolio beyond logistics into global trade and supply chain operations.
- In July 2025, Aptean launched the Aptean Fresh Produce ERP, a cloud-native evolution of its Produce Pro Software, featuring AI-powered analytics and integration with Microsoft 365.
Report Coverage:
The research report offers an in-depth analysis based on Components, Deployment, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The trade management market will witness rising adoption of AI-driven compliance and predictive analytics solutions.
- Blockchain integration will enhance transparency and trust across global supply chains.
- Cloud-based platforms will dominate deployments, offering scalability and cost efficiency for enterprises of all sizes.
- Sustainability initiatives will drive demand for solutions that track carbon emissions and support green logistics.
- E-commerce expansion will create strong demand for automated trade documentation and customs management tools.
- Geopolitical uncertainties and shifting trade agreements will increase reliance on adaptable and resilient platforms.
- Integration of IoT-enabled tracking systems will provide real-time visibility across international shipping routes.
- Small and medium enterprises will adopt modular trade management systems to improve competitiveness.
- Partnerships between technology providers and logistics companies will accelerate innovation and market expansion.
- The market will evolve toward unified platforms that combine compliance, analytics, and risk management in one ecosystem.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the trade management market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the trade management market projected to grow between 2024 and 2032?
Which trade management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the trade management market?
Who are the leading companies in the trade management market?
Which region commanded the largest share of the trade management market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Trade Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Trade Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.4 billion → 2032: USD 5.4 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Trade Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Trade Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Trade Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Trade Management Market Drivers
- 3.3 Trade Management Market Restraints & Challenges
- 3.4 Trade Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Trade Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Trade Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Trade Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Trade Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Trade Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Trade Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Trade Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Trade Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Trade Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Trade Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Trade Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Trade Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Trade Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Trade Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Trade Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Trade Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Trade Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Trade Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Trade Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
