
Market Overview
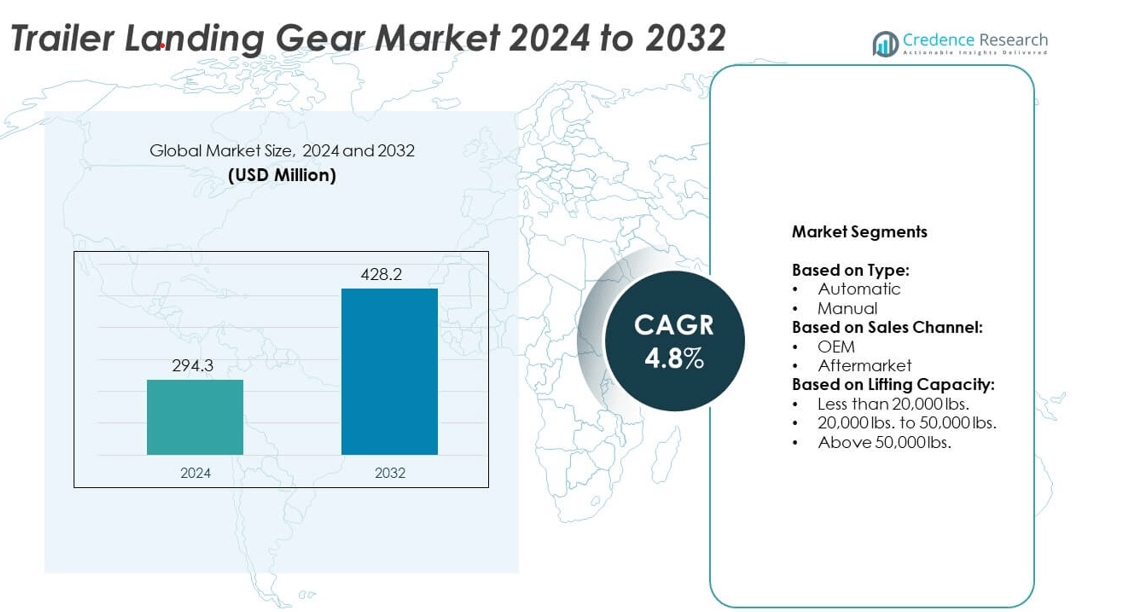
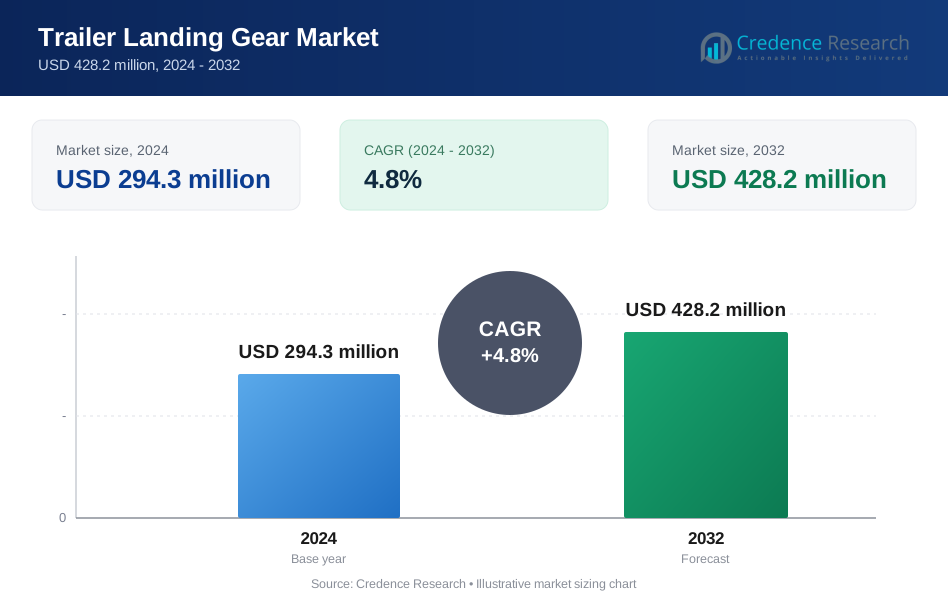
The Trailer Landing Gear Market size was valued at USD 294.3 million in 2024 and is anticipated to reach USD 428.2 million by 2032, growing at a CAGR of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trailer Landing Gear Market Size 2024 | USD 294.3 million |
| Trailer Landing Gear Market, CAGR | 4.8% |
| Trailer Landing Gear Market Size 2032 | USD 428.2 million |
The Trailer Landing Gear market grows through rising freight demand, fleet modernization, and strict safety regulations. Operators adopt advanced landing gear to improve efficiency, reduce downtime, and ensure cargo stability. Automation features and lightweight, corrosion-resistant materials drive innovation across product lines. Expanding logistics networks and cross-border trade strengthen the need for reliable trailer components. The market also benefits from sustainability initiatives, pushing adoption of eco-friendly materials. These drivers and trends collectively support steady growth across global regions.
North America leads the Trailer Landing Gear market with strong fleet modernization and advanced logistics infrastructure. Europe follows with emphasis on safety regulations, lightweight materials, and automated systems. Asia-Pacific records the fastest growth, supported by rapid industrialization, e-commerce expansion, and increasing trailer production. Latin America and the Middle East & Africa show steady demand through infrastructure development and regional trade growth. Key players influencing the market include JOST Werke AG, SAF-HOLLAND, BPW Bergische Achsen KG, and Fuwa Group.
Market Insights
- The Trailer Landing Gear market was valued at USD 294.3 million in 2024 and is projected to reach USD 428.2 million by 2032, growing at a CAGR of 4.8%.
- Growth is driven by rising freight volumes, expanding logistics networks, and strict trailer safety regulations.
- Automation and lightweight, corrosion-resistant materials are shaping product design and innovation in landing gear systems.
- Leading players focus on OEM partnerships, aftermarket presence, and R&D investments to strengthen their market position.
- High maintenance costs, frequent replacements, and intense price competition act as restraints for market growth.
- North America leads with advanced fleet modernization, Europe emphasizes regulatory compliance, and Asia-Pacific records the fastest growth with industrialization and e-commerce.
- Latin America and the Middle East & Africa show steady growth supported by infrastructure upgrades, regional trade expansion, and increasing trailer adoption.
Market Drivers
Rising Demand for Heavy-Duty Transportation and Logistics Expansion
The growth of global trade and e-commerce is fueling higher freight volumes across regions. The transportation industry requires durable trailer components that can handle heavy payloads. The Trailer Landing Gear market benefits from investments in efficient logistics infrastructure. Fleet operators are focusing on stability and reliability during loading and unloading. Strong landing gear systems reduce downtime and improve safety standards. It supports fleet modernization strategies aimed at meeting strict performance requirements.
- For instance, SAF-Holland produces various high-performance landing gear, such as the HOLLAND MARK V series, which has an ultimate load capacity of 200,000 lbs. (approximately 90,700 kg). The company also has a modular axle and suspension system, known as SAF MODUL, which offers customizable configurations for different vehicle requirements.
Stringent Safety Regulations and Compliance with Standards
Government bodies enforce strict safety norms for trailer equipment in major markets. These regulations push manufacturers to develop robust and reliable landing gear systems. The Trailer Landing Gear market is driven by compliance requirements that limit equipment failure. It ensures trailers meet standards for stability during parking and cargo operations. The focus on accident prevention is accelerating replacement of outdated systems. Regulatory compliance acts as a catalyst for innovation and design improvements.
- For instance, JOST Werke developed its Modul B landing gear, which is certified under various international standards, including the AAR. The standard Modul B offers a lifting capacity of 24,000 kg and a static test load of 50,000 kg.
Technological Advancements and Product Innovation in Trailer Components
Manufacturers are integrating advanced materials to reduce weight while maintaining strength. The Trailer Landing Gear market sees rising adoption of automation features for easier operation. It enhances driver convenience and improves overall efficiency in fleet operations. Companies invest in R&D to deliver higher load capacity and longer lifecycle products. Demand for cost-efficient and durable solutions drives continuous product upgrades. Lightweight and corrosion-resistant designs are gaining preference among fleet operators.
Fleet Modernization and Growth in Long-Haul Transportation
The rising number of trailers for long-haul operations increases demand for reliable landing gear. The Trailer Landing Gear market gains traction from investments in advanced fleets. It provides the stability and safety needed in challenging routes and conditions. Long-haul transportation growth highlights the need for durable components that extend service life. Fleet operators prioritize reducing maintenance costs and ensuring consistent performance. This shift strengthens market growth and broadens adoption across global regions.
Market Trends
Adoption of Lightweight and High-Strength Materials in Trailer Components
Manufacturers are shifting toward advanced materials such as aluminum and high-strength steel. The Trailer Landing Gear market reflects this trend with designs that balance durability and weight reduction. It helps fleets lower fuel consumption and improve efficiency. Lightweight gear also reduces wear on tires and axles, supporting longer vehicle lifespan. The push for sustainability encourages wider acceptance of eco-friendly materials. This trend enhances operational performance while addressing environmental goals.
- For instance, BPW Bergische Achsen introduced ECO landing gear that utilizes high-strength steel and advanced design for weight reduction, contributing to improved transport efficiency. The ECO landing gear series includes models with a lifting capacity of 24,000 kg
Integration of Automation and Ease-of-Use Features
Operators seek landing gear systems that minimize manual effort and improve safety. The Trailer Landing Gear market experiences rising demand for semi-automatic and fully automatic solutions. It ensures faster deployment, reduced physical strain, and better efficiency in fleet operations. Automated gear aligns with the broader digitalization trend in transportation. Manufacturers continue to integrate sensors and simple controls for improved usability. This development supports driver productivity and reduces operational risks.
- For instance, Hyundai Translead’s standard landing gear has a lifting capacity of 50,000 lbs, with heavy-duty options featuring reinforced footplates offering a higher capacity of 62,500 lbs
Emphasis on Durability and Corrosion Resistance in Harsh Environments
Fleet operators prioritize landing gear that withstands extreme weather and rough terrains. The Trailer Landing Gear market benefits from coatings and treatments that enhance corrosion resistance. It extends service life and reduces long-term maintenance expenses. Demand is high in regions with snow, rain, and coastal conditions where rust is common. Heavy-duty construction ensures stability during frequent loading and unloading. This trend strengthens the shift toward advanced finishing technologies.
Growth of Global Logistics and Fleet Expansion Strategies
Expanding logistics networks drive strong demand for advanced trailer components worldwide. The Trailer Landing Gear market supports rapid growth in freight movement across borders. It enables fleet operators to scale operations while maintaining safety and reliability. Global trade intensification requires equipment that adapts to diverse road conditions. Fleet expansions in Asia-Pacific, Europe, and North America highlight this momentum. The trend reflects the strategic investments of logistics companies in high-performance equipment.
Market Challenges Analysis
High Maintenance Costs and Operational Downtime for Fleet Operators
Fleet owners face rising expenses from frequent repairs and replacements of trailer components. The Trailer Landing Gear market encounters resistance due to high lifecycle costs of equipment. It often requires regular inspection and servicing to prevent mechanical failures. Unexpected breakdowns increase downtime and reduce overall fleet efficiency. Small and mid-sized operators struggle with limited budgets to upgrade gear systems. This challenge slows adoption of advanced solutions in price-sensitive regions.
Intense Price Competition and Pressure on Profit Margins
Manufacturers face strong competition from regional and global suppliers offering low-cost alternatives. The Trailer Landing Gear market is impacted by shrinking margins and pressure to reduce prices. It limits the ability of companies to invest heavily in innovation. Customers often prioritize cost over advanced features, restricting premium product adoption. The presence of counterfeit and substandard products further complicates competition. These market conditions create significant challenges for sustainable growth and long-term profitability.
Market Opportunities
Rising Demand for Advanced Trailer Fleets and Infrastructure Growth
Expanding logistics networks and growing cross-border trade create strong opportunities for trailer component suppliers. The Trailer Landing Gear market benefits from investments in modern fleets designed for higher efficiency. It supports infrastructure upgrades in developing regions where freight transportation is rapidly expanding. Governments promote road connectivity projects, further boosting trailer adoption. The demand for safe, durable, and high-performance landing gear aligns with these investments. This opportunity enhances growth potential across both developed and emerging economies.
Adoption of Automation and Sustainable Material Solutions
Fleet operators seek gear systems with automated functions that reduce manual effort and improve safety. The Trailer Landing Gear market gains opportunities from the shift toward lightweight, corrosion-resistant, and eco-friendly materials. It addresses global sustainability targets while improving overall vehicle performance. Automated systems also appeal to large logistics companies focused on efficiency and driver well-being. Manufacturers introducing smart, durable, and environmentally friendly designs can capture higher market share. These opportunities pave the way for long-term industry innovation and expansion.
Market Segmentation Analysis:
By Type:
The Trailer Landing Gear market is divided into automatic and manual systems. Automatic landing gear is gaining adoption due to its efficiency, reduced labor needs, and safety benefits. Fleet operators in large-scale logistics prefer automatic gear for time savings and consistent performance. Manual systems still hold a considerable share in cost-sensitive markets where affordability is critical. It offers durability and simplicity, making it suitable for smaller fleets and regions with limited access to advanced technologies. The demand trend indicates a gradual shift toward automation in developed economies while manual systems remain relevant in emerging markets.
- For instance, Alcoa Wheels supplies forged aluminum wheels for trucks and trailers in European fleets. These wheels offer significant weight savings compared to steel wheels. In 2015, a specific low-deck Alcoa wheel weighed 41% less than a comparable steel wheel, resulting in a 117 kg saving on a three-axle trailer.
By Sales Channel:
The Trailer Landing Gear market is segmented into OEM and aftermarket. OEM sales dominate due to direct integration of advanced systems into new trailers. Manufacturers focus on equipping fleets with reliable gear during production to ensure long-term safety and performance. Aftermarket demand is strong, driven by replacement needs and fleet modernization. It reflects opportunities for suppliers providing durable gear that meets regulatory standards. Growing wear and tear in high-volume freight markets sustains aftermarket sales across multiple regions.
- For instance, Schmitz Cargobull delivered 57,122 vehicles in the 2022/2023 financial year, a majority of which were to Europe, while also expanding its global footprint into new markets like India and Central Asia.
By Lifting Capacity:
The Trailer Landing Gear market is segmented into less than 20,000 lbs., 20,000 lbs. to 50,000 lbs., and above 50,000 lbs. The 20,000 lbs. to 50,000 lbs. segment holds the largest share, driven by its suitability for medium to heavy-duty trailers. It supports diverse freight requirements, balancing durability and cost efficiency. Less than 20,000 lbs. gear serves lighter trailers, often used in regional transport and smaller fleets. Above 50,000 lbs. capacity gear caters to specialized heavy-duty trailers handling oversized cargo. This segment sees growth in industries such as mining, construction, and energy transportation where extreme durability is essential.
Segments:
Based on Type:
- Automatic
- Manual
Based on Sales Channel:
- OEM
- Aftermarket
Based on Lifting Capacity:
- Less than 20,000 lbs.
- 20,000 lbs. to 50,000 lbs.
- Above 50,000 lbs.
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Trailer Landing Gear market, accounting for 32% in 2024. The region benefits from a highly developed freight network, strong trucking industry, and early adoption of advanced technologies. Fleet operators prioritize automatic and corrosion-resistant landing gear to enhance operational efficiency and safety. It is supported by strict government regulations related to trailer safety and stability standards. The presence of established OEMs and strong aftermarket demand further strengthens regional growth. Rising investments in cross-border trade between the U.S., Canada, and Mexico continue to fuel demand. Long-haul routes, combined with large fleet modernization initiatives, ensure sustained consumption of advanced trailer landing gear systems.
Europe
Europe represents 27% of the global Trailer Landing Gear market in 2024, driven by stringent safety regulations and environmental standards. The region emphasizes lightweight and durable designs, reflecting efforts to improve fuel efficiency and reduce emissions. It is supported by large logistics and freight companies operating in cross-border trade within the EU. Advanced manufacturing hubs in Germany, France, and the UK foster innovation and rapid adoption of automated systems. The aftermarket is also strong, supported by replacement needs across an aging fleet base. Demand for gear systems with corrosion-resistant coatings is high due to varied climates across the region. Government support for sustainable transportation continues to encourage adoption of modern trailer components.
Asia-Pacific
Asia-Pacific accounts for 24% of the Trailer Landing Gear market in 2024 and records the fastest growth rate. The region benefits from expanding logistics infrastructure, rapid industrialization, and strong growth in e-commerce. China, India, and Southeast Asian countries are key contributors to market expansion. It is driven by large-scale investments in transportation networks and cross-border trade routes, including Belt and Road initiatives. Fleet operators focus on affordable yet durable manual gear, while adoption of automatic systems grows in advanced economies like Japan and South Korea. The aftermarket is also robust, reflecting frequent fleet upgrades and high freight activity. Increasing demand for cost-effective solutions ensures rising opportunities for global and regional manufacturers.
Latin America
Latin America holds 9% of the Trailer Landing Gear market in 2024, supported by gradual modernization of freight fleets. Brazil and Mexico are the major markets, benefiting from trade expansion and industrial growth. It is influenced by demand for reliable manual gear that balances cost and performance. OEM penetration is rising, but aftermarket sales remain dominant due to the region’s reliance on fleet maintenance. Harsh road conditions and extended operational use increase replacement demand. Adoption of advanced gear remains slow, but growing logistics investments create future opportunities. Government initiatives to improve transportation efficiency are expected to strengthen demand over the forecast period.
Middle East & Africa
The Middle East & Africa region represents 8% of the Trailer Landing Gear market in 2024, with steady growth supported by infrastructure projects and logistics expansion. Gulf countries invest heavily in logistics hubs, creating strong demand for durable landing gear. It is driven by long-haul freight movements across deserts and challenging terrains. Africa records rising demand, particularly in South Africa, due to growing industrialization and trade activities. Manual gear dominates due to cost considerations, but OEMs are gradually introducing advanced solutions. Harsh environmental conditions increase the need for corrosion-resistant systems that ensure long-term stability. Expanding trade routes and regional connectivity projects create sustained opportunities for manufacturers.
Key Player Analysis
- JOST Werke AG
- Yangzhou Tongyi Machinery Co., Ltd.
- Butler Products Corp.
- SAF-HOLLAND
- Zhenjiang Baohua Semi-Trailer Parts Co., Ltd.
- haacon
- Sinotruck Howo Sales Co., Ltd.
- BPW Bergische Achsen KG
- Fuwa Group
- D. Trailers Pvt. Ltd.
- AXN Heavy Duty
Competitive Analysis
The leading players in the Trailer Landing Gear market include JOST Werke AG, SAF-HOLLAND, BPW Bergische Achsen KG, Fuwa Group, Butler Products Corp., haacon, Sinotruck Howo Sales Co., Ltd., Yangzhou Tongyi Machinery Co., Ltd., Zhenjiang Baohua Semi-Trailer Parts Co., Ltd., H.D. Trailers Pvt. Ltd., and AXN Heavy Duty. These companies compete on product durability, technological advancements, and cost efficiency. Global players focus on integrating automation, lightweight materials, and corrosion-resistant designs to meet diverse fleet requirements. Regional manufacturers target cost-sensitive markets with reliable manual systems, supporting affordability while maintaining safety standards. Strong OEM partnerships enable major suppliers to secure long-term contracts with trailer manufacturers. The aftermarket also plays a key role, where competitive pricing and availability of replacement parts strengthen brand presence. Innovation remains a defining factor, with companies investing in research and development to differentiate offerings. Automation in landing gear is gaining momentum, giving established players an advantage in developed markets. At the same time, smaller regional firms compete on pricing strategies, especially in Asia-Pacific and Latin America. Competitive intensity is expected to increase as logistics expansion drives fleet modernization globally. This dynamic environment ensures continuous product upgrades and evolving strategies among leading players.
Recent Developments
- In 2025, Randoncorp, a Brazilian manufacturer of trailer components, announced the acquisition of AXN Heavy Duty. This integration is expected to broaden AXN's product portfolio and market reach.
- In 2024, JOST has made significant progress in automation, with its KKS automatic coupling system, which includes the Modul E-Drive electric landing gear. While the E-Drive was not a new product in 2024, it was a central component of JOST's automation push for safer and faster trailer operations.
- In 2023, BPW introduced the ePower generator axle, which provides an independent power source for electric and hybrid refrigeration systems on trailers. This development is part of the larger shift toward electrifying logistics and reducing transport emissions.
Report Coverage
The research report offers an in-depth analysis based on Type, Sales Channel, Lifting Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Trailer Landing Gear market will see steady growth supported by global freight expansion.
- Automatic landing gear adoption will rise as fleets prioritize efficiency and driver safety.
- Manual systems will remain relevant in cost-sensitive and developing regions.
- Demand for lightweight and corrosion-resistant materials will strengthen product innovation.
- OEM sales will dominate with integration of advanced systems in new trailers.
- Aftermarket demand will grow due to replacement needs in aging fleets.
- Asia-Pacific will record the fastest growth driven by logistics investments and e-commerce.
- North America and Europe will maintain strong shares with advanced fleet modernization.
- Manufacturers will focus on automation, durability, and eco-friendly material solutions.
- Rising global trade and infrastructure projects will expand opportunities across emerging economies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Trailer Landing Gear market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Trailer Landing Gear Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Trailer Landing Gear market?
Who are the leading companies in the Trailer Landing Gear Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Trailer Landing Gear Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Trailer Landing Gear Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 294.3 million → 2032: USD 428.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Trailer Landing Gear Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Trailer Landing Gear Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Trailer Landing Gear Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Trailer Landing Gear Market Drivers
- 3.3 Trailer Landing Gear Market Restraints & Challenges
- 3.4 Trailer Landing Gear Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Trailer Landing Gear Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Trailer Landing Gear Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Trailer Landing Gear category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Trailer Landing Gear Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Trailer Landing Gear Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Trailer Landing Gear market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Trailer Landing Gear Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Trailer Landing Gear Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Trailer Landing Gear Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Trailer Landing Gear (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Trailer Landing Gear Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Trailer Landing Gear Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Trailer Landing Gear Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Trailer Landing Gear Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Trailer Landing Gear Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Trailer Landing Gear Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Trailer Landing Gear Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Trailer Landing Gear Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Trailer Landing Gear Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
