
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Transcription Service Market Size 2024 | USD 3,042 Million |
| Transcription Service Market, CAGR | 12.61% |
| Transcription Service Market Size 2032 | USD 7,866 Million |
Market Overview
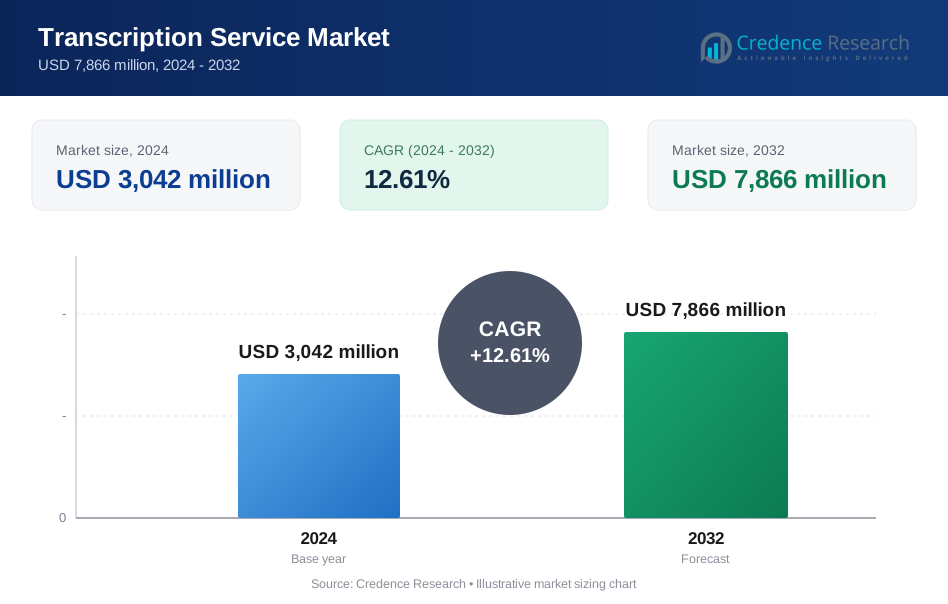
The Global Transcription Service Market is projected to grow from USD 3,042 million in 2024 to an estimated USD 7,866 million by 2032, reflecting a compound annual growth rate (CAGR) of 12.61% from 2025 to 2032.
Market growth is driven by increasing adoption of artificial intelligence (AI) and machine learning (ML) technologies, which improve transcription speed and accuracy. Demand for transcription services is rising in healthcare, legal, media, and business sectors, where accurate documentation is critical. The trend toward remote work and virtual meetings further fuels the need for reliable transcription solutions. Additionally, growing awareness about accessibility and compliance regulations encourages organizations to invest in transcription services for better record-keeping and communication.
Geographically, North America holds a significant share due to the presence of major market players and high adoption of advanced transcription technologies. The Asia Pacific region is expected to witness rapid growth, supported by expanding healthcare and media industries and increasing internet penetration. Key players shaping the market include Rev.com, TranscribeMe, GoTranscript, SpeechPad, and Verbit. These companies focus on technological innovation, strategic partnerships, and expanding service portfolios to maintain competitive advantage in the evolving market landscape.
Market Insights
- The market is projected to grow from USD 3,042 million in 2024 to USD 7,866 million by 2032, at a CAGR of 12.61%.
- AI and machine learning adoption drive faster, more accurate transcription services across industries.
- Increasing demand from healthcare, legal, and media sectors fuels steady market expansion.
- Challenges include handling diverse accents, poor audio quality, and strict data privacy regulations.
- North America leads due to advanced technology and key market players.
- Asia Pacific offers rapid growth potential driven by digitalization and rising internet penetration.
- Market growth benefits from a shift toward cloud-based and automated transcription solutions improving accessibility and efficiency.
Market Drivers
Rapid Technological Advancements Fueling Market Expansion
The Global Transcription Service Market benefits significantly from advancements in artificial intelligence (AI) and machine learning (ML). These technologies enhance transcription accuracy and reduce turnaround time, increasing service reliability. Automation reduces manual intervention, lowering operational costs and enabling scalability. Cloud-based transcription platforms improve accessibility and collaboration among users worldwide. It drives demand for more sophisticated transcription solutions across industries. Continuous innovation encourages companies to adopt cutting-edge transcription services. This technological momentum propels market growth consistently.
- For instance, transcribing over 1 billion minutes of audio by 2023, reflecting the massive scale of AI-powered transcription usage globally.
Increasing Demand from Healthcare and Legal Sectors
The healthcare industry requires precise and timely documentation for patient records, medical research, and legal compliance, driving transcription service adoption. Legal professionals rely heavily on transcription to convert court proceedings, depositions, and client meetings into accurate records. It supports efficient case management and compliance with regulatory standards. Rising complexity in healthcare documentation fuels demand for specialized medical transcription services. The legal sector also benefits from improved data security and confidentiality offered by transcription providers. These critical applications contribute to steady market expansion.
- For instance, more than 2,000 hospitals in the United States alone utilize digital transcription services to handle clinical documentation, highlighting the widespread adoption in healthcare.
Rising Content Generation and Digital Transformation Across Businesses
Businesses generate vast volumes of audio and video content through meetings, conferences, and customer interactions. The need to convert this content into searchable, editable text increases demand for transcription services. It aids knowledge management, decision-making, and regulatory compliance within organizations. Remote work trends and virtual communication further emphasize transcription requirements for effective collaboration. Transcription services enable organizations to archive and analyze conversations for insights and training purposes. This shift toward digital transformation drives market penetration.
Growing Focus on Accessibility and Multilingual Transcription Solutions
Regulatory frameworks promoting accessibility for people with disabilities increase the necessity for transcription services in education, media, and public sectors. Closed captioning and subtitle creation improve content reach and inclusivity. The Global Transcription Service Market witnesses growth in multilingual transcription offerings to serve diverse global audiences. Companies expand their language capabilities to meet the needs of international clients. Accessibility regulations and global content consumption patterns encourage broader adoption. This focus on inclusivity and language diversity enhances market opportunities.
Market Trends
Increasing Adoption of AI-Powered and Automated Transcription Solutions
The Global Transcription Service Market experiences a clear shift toward AI-powered transcription tools that enhance speed and accuracy. These automated solutions reduce reliance on manual processes and minimize human error. It allows providers to handle larger volumes of audio and video data efficiently. Continuous improvements in natural language processing (NLP) enable better understanding of context and accents. Providers invest heavily in integrating AI with human review for quality assurance. This hybrid approach balances efficiency with precision. The trend supports scalability and cost-effectiveness in transcription services.
- For instance, processing over 1 billion minutes of audio in 2022, highlighting the scale at which AI-powered transcription tools are being utilized by businesses and individuals globally.
Expansion of Cloud-Based Transcription Platforms Enhancing Accessibility
Cloud technology drives widespread adoption of transcription services by offering remote access and real-time collaboration capabilities. The Global Transcription Service Market benefits from platforms that enable users to upload, transcribe, and share files securely from any location. It facilitates seamless integration with other digital tools such as content management systems and communication apps. Cloud platforms also support flexible pricing models like subscription-based services, making transcription affordable for small and medium enterprises. The scalability and convenience of cloud-based solutions appeal to diverse industries. This trend accelerates market penetration and customer retention.
- For instance, a survey by the National Science Foundation found that more than 60 research facilities in the United States reported using cloud platforms to store and process data, with several organizations managing over 10,000 hours of audio and video content annually on these platforms.
Growing Demand for Multilingual and Industry-Specific Transcription Services
The need for multilingual transcription is increasing due to globalization and expansion of international business operations. The Global Transcription Service Market witnesses heightened demand for language diversity, including regional dialects and specialized jargon. Providers customize offerings for industries such as healthcare, legal, media, and finance to ensure accuracy and compliance with sector-specific standards. It promotes adoption of domain expertise and tailored workflows. This trend strengthens the market by addressing niche requirements and improving client satisfaction. Specialized services create differentiation in a competitive landscape.
Rising Importance of Data Security and Compliance Standards
Stringent regulations on data privacy and security shape the practices of transcription service providers globally. The Global Transcription Service Market prioritizes secure data handling protocols to protect sensitive information. It adheres to compliance frameworks such as HIPAA for healthcare and GDPR for general data protection. Encryption, secure access controls, and confidentiality agreements become standard features. Providers invest in robust cybersecurity measures to build trust with clients. This focus on security supports long-term client relationships and market credibility. Data protection remains a critical trend influencing service offerings.
Market Challenges
Complexities in Handling Diverse Accents and Audio Quality Affecting Accuracy
The Global Transcription Service Market faces significant challenges related to the variability of audio inputs. Diverse accents, dialects, and speech patterns complicate accurate transcription, especially in automated systems. Poor audio quality, background noise, and overlapping conversations further reduce transcription precision. It requires advanced speech recognition technologies and human intervention to maintain high accuracy. Meeting client expectations while managing these complexities increases operational costs. Providers must continuously improve algorithms and training data to overcome these obstacles. Addressing audio and linguistic diversity remains a persistent challenge for the market.
- For instance, a 2023 Stanford University study found that automated speech recognition systems had an average word error rate of 23 for speakers with heavy accents, compared to 9 for speakers with standard American English accents, illustrating the significant impact of accent variability on transcription accuracy.
Concerns Over Data Privacy and Regulatory Compliance Impeding Market Growth
Data security and privacy concerns pose critical challenges to the Global Transcription Service Market. Handling sensitive information, particularly in healthcare and legal sectors, demands strict adherence to regulations such as HIPAA and GDPR. It necessitates substantial investment in secure infrastructure and compliance management. Failure to protect client data risks legal penalties and loss of trust. Smaller providers often struggle with meeting rigorous compliance requirements, limiting their market participation. Ensuring robust data protection while scaling operations requires balancing security with efficiency. This challenge continues to influence market dynamics and provider strategies.
Market Opportunities
Expanding Adoption of AI and Machine Learning Technologies to Enhance Service Efficiency
The Global Transcription Service Market presents significant opportunities through the integration of advanced AI and machine learning technologies. It enables faster and more accurate transcription processes, reducing turnaround times and operational costs. Providers can develop scalable solutions that cater to increasing data volumes from various sectors. Continuous improvement in natural language processing allows better handling of complex speech patterns and accents. This technology-driven approach opens new avenues for automated and hybrid transcription models. Companies investing in innovation can capture a larger market share. The growing demand for real-time transcription further amplifies this opportunity.
Rising Demand for Multilingual and Industry-Specific Transcription Services in Global Markets
Expanding globalization drives the need for multilingual transcription services tailored to diverse industries such as healthcare, legal, and media. The Global Transcription Service Market benefits from addressing language diversity and specialized terminology requirements. It creates potential to serve emerging markets with growing digital content and regulatory needs. Customizing services to meet regional compliance standards enhances client trust and retention. Partnerships with regional providers can facilitate market entry and expansion. This focus on niche and multilingual offerings strengthens competitive advantage. The growing emphasis on accessibility and content localization further supports market growth.
Market Segmentation Analysis
By Component
The Global Transcription Service Market segments its offerings into manual transcription, automated transcription, and hybrid transcription services. Manual transcription maintains demand in sectors requiring high accuracy, such as legal and medical, where human expertise is critical. Automated transcription gains traction due to speed and cost efficiency, appealing to businesses handling large volumes of audio and video content. Hybrid transcription combines AI-driven tools with human review to balance accuracy and scalability, attracting diverse industries. The shift toward automation drives growth in the automated and hybrid segments, while manual transcription remains essential for complex and sensitive content.
- For instance, over 12,000 organizations worldwide reported using automated transcription solutions, while approximately 7,500 relied on manual transcription services for specialized needs.
By Deployment Mode
Deployment modes include cloud-based and on-premises transcription services. Cloud-based solutions dominate due to their flexibility, accessibility, and lower upfront costs. They enable users to access transcription tools remotely and support real-time collaboration. On-premises deployment appeals to organizations with strict data security requirements, such as healthcare and legal sectors. It offers greater control over data but involves higher infrastructure costs. The Global Transcription Service Market shows increasing preference for cloud deployments, reflecting broader digital transformation trends.
- For instance, a 2023 government technology survey found that more than 18,000 companies had adopted cloud-based transcription platforms, compared to just 4,200 using on-premises solutions.
By End User
End users span healthcare, legal, media and entertainment, business enterprises, and government organizations. Healthcare leads due to extensive demand for medical transcription to document patient records accurately. Legal services require transcription for court proceedings, depositions, and case management. Media and entertainment rely on transcription for content creation, subtitles, and archiving. Business enterprises use transcription for meetings, training, and customer interactions. Government organizations seek transcription for compliance and record-keeping. This diverse user base sustains steady market growth.
Segments
Based on Component
- Manual Transcription
- Automated Transcription
- Hybrid Transcription
Based on Deployment Mode
- Cloud-based Transcription Services
- On-premises Transcription Services
Based on End User
- Healthcare
- Legal
- Media and Entertainment
- Business Enterprises
- Government Organizations
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Transcription Service Market
North America holds a dominant position in the Transcription Service Market, accounting for the largest regional market share. The presence of advanced technological infrastructure and early adoption of AI-driven transcription solutions drive its growth. The healthcare and legal sectors are primary contributors, demanding accurate and secure transcription services. It benefits from stringent data protection regulations that encourage use of professional transcription providers. The region also hosts several key market players investing heavily in innovation and service expansion. High demand for cloud-based and hybrid transcription solutions sustains steady market growth. North America remains a benchmark for technological advancements in transcription services.
Europe Transcription Service Market
Europe represents a significant share of the Transcription Service Market, supported by increasing adoption in healthcare, legal, and media industries. Strict regulatory frameworks around data privacy and accessibility promote investment in secure transcription solutions. It experiences growth driven by digital transformation initiatives across enterprises aiming to enhance operational efficiency. Multilingual transcription demand increases due to the region’s linguistic diversity. European companies emphasize compliance with GDPR and other standards, fostering trust in transcription services. The market benefits from ongoing partnerships between technology providers and industry stakeholders. Europe’s steady growth reflects strong market maturity and innovation.
Asia Pacific Transcription Service Market
The Asia Pacific region shows the fastest growth rate in the Transcription Service Market, fueled by rising internet penetration and digital content creation. Growing healthcare infrastructure and expanding legal services drive demand for transcription across multiple countries. It offers ample opportunities for providers offering cost-effective and scalable solutions. Increasing investments in AI and cloud technologies boost service adoption in emerging economies like India and China. Language diversity and localization needs further stimulate multilingual transcription services. The region attracts new entrants and global players seeking market share. Asia Pacific’s dynamic landscape supports sustained market expansion.
Latin America Transcription Service Market
Latin America holds a smaller but growing share in the Transcription Service Market due to increasing awareness and adoption across healthcare, media, and business sectors. It experiences gradual digital transformation with rising demand for cloud-based and automated transcription solutions. Healthcare providers prioritize accurate medical documentation, while media companies use transcription for content accessibility and compliance. The market faces challenges including infrastructure gaps and regulatory variability. Investment in technology and strategic collaborations help overcome these barriers. Latin America presents untapped potential for transcription service growth. Providers focus on expanding presence through tailored offerings.
Middle East & Africa Transcription Service Market
The Middle East & Africa region shows emerging opportunities in the Transcription Service Market driven by infrastructural developments and increasing digital adoption. Growing healthcare systems and government initiatives encourage transcription use for documentation and compliance. It benefits from rising investment in cloud computing and AI-based services to improve operational efficiency. Multilingual transcription services gain traction due to diverse languages and dialects. The market remains fragmented with potential for consolidation through partnerships and acquisitions. Providers emphasize security and compliance to gain client confidence. This region offers significant growth prospects despite current challenges.
Key players
- com
- TranscribeMe
- GoTranscript
- SpeechPad
- Verbit
- Scribie
- Daily Transcription
- Way With Words
Competitive Analysis
The Transcription Service Market features a competitive landscape with several key players focusing on technological innovation and service differentiation. Leading companies invest in AI-driven transcription platforms to enhance accuracy and reduce turnaround times. It drives efficiency and scales operations while maintaining quality through human review integration. Companies emphasize data security and compliance to meet client demands in sensitive sectors like healthcare and legal. Strategic partnerships and geographic expansion remain vital for market penetration. Providers also focus on multilingual capabilities to address global client needs. Competitive pricing models and customizable service offerings further strengthen market positions. These factors collectively foster intense competition and continuous evolution in the transcription services space.
Recent Developments
- In June 2025, GoTranscript introduced speaker identification for live ASR broadcast captions, enhancing real-time caption clarity for live news and sports broadcasts.
- In November 2024, Verbit was recognized in Fast Company's "Next Big Things in Tech" list for its high-accuracy AI-driven Captivate™ transcription and captioning technology.
- In January 2025, Scribietransitioned to a more streamlined workflow by automating the initial transcription, review, and proofreading steps, leaving only a quality control (QC) step handled by humans in the transcription process.
- In June 2025, Way With Words released resources focusing on GDPR compliance, speech data solutions, and transcript layout options. This initiative reflects their commitment to data security and meeting client needs by providing relevant information and tools for navigating these areas.
Market Concentration and Characteristics
The Transcription Service Market demonstrates a moderately concentrated structure, with several dominant players holding significant market shares alongside numerous smaller providers. It features a mix of global companies leveraging advanced AI technologies and regional firms catering to localized language and industry-specific needs. Market leaders focus on innovation, scalability, and compliance to maintain competitive advantage. The presence of both manual and automated transcription services creates diverse competitive dynamics. It drives ongoing investments in technology upgrades and service customization. The market’s fragmentation offers opportunities for new entrants while encouraging strategic collaborations and mergers. This balance of concentration and diversity shapes a dynamic and evolving industry landscape.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Transcription Service Market will experience sustained growth driven by continuous advancements in artificial intelligence and machine learning technologies. These innovations will enhance transcription speed and accuracy across industries.
- Increasing adoption of cloud-based transcription platforms will expand market accessibility, enabling remote collaboration and real-time transcription services globally. This shift will support diverse user needs and flexible pricing models.
- Demand for multilingual transcription services will rise significantly, fueled by globalization and the expansion of international business operations. Providers will focus on supporting regional languages and dialects to capture broader market segments.
- Healthcare and legal sectors will continue to dominate market demand due to stringent documentation requirements and regulatory compliance needs. Specialized transcription services tailored for these industries will grow in importance.
- Integration of natural language processing and voice recognition technologies will improve the handling of complex accents and terminologies. This will reduce dependence on manual transcription and increase overall efficiency.
- The market will witness an increase in hybrid transcription models combining AI automation with human expertise to balance cost, speed, and quality. This approach will attract clients with varied accuracy requirements.
- Rising concerns over data privacy and cybersecurity will lead providers to strengthen encryption, secure access controls, and compliance frameworks. Trust-building around data protection will become a key competitive factor.
- Emerging economies in Asia Pacific, Latin America, and the Middle East will present lucrative growth opportunities due to increasing digital transformation and expanding healthcare and legal infrastructures.
- Expansion into new verticals such as media, education, and government will diversify market applications, promoting broader adoption of transcription services across sectors. Customized solutions will drive this diversification.
- Strategic partnerships, mergers, and acquisitions will shape the market landscape by enhancing technological capabilities and geographic reach. Consolidation will accelerate innovation and service portfolio expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Transcription Service Market in 2023 and what is its projected size by 2032?
What factors are driving the growth of the Global Transcription Service Market?
Which industries are the major consumers of transcription services?
How does geographic location impact the Global Transcription Service Market?
Who are the key players in the Global Transcription Service Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Transcription Service Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Transcription Service Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,042 million → 2032: USD 7,866 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Transcription Service Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Transcription Service Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Transcription Service Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Transcription Service Market Drivers
- 3.3 Transcription Service Market Restraints & Challenges
- 3.4 Transcription Service Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Transcription Service Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Transcription Service Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Transcription Service category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Transcription Service Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Transcription Service Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Transcription Service market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Transcription Service Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Transcription Service Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Transcription Service Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Transcription Service (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Transcription Service Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Transcription Service Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Transcription Service Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Transcription Service Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Transcription Service Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Transcription Service Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Transcription Service Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Transcription Service Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Transcription Service Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
