
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| United Kingdom Diabetes Care Devices Market Size 2023 | USD 1,389.49 Million |
| United Kingdom Diabetes Care Devices Market, CAGR | 8.49% |
| United Kingdom Diabetes Care Devices Market Size 2032 | USD 2,991.76 Million |
Market Overview
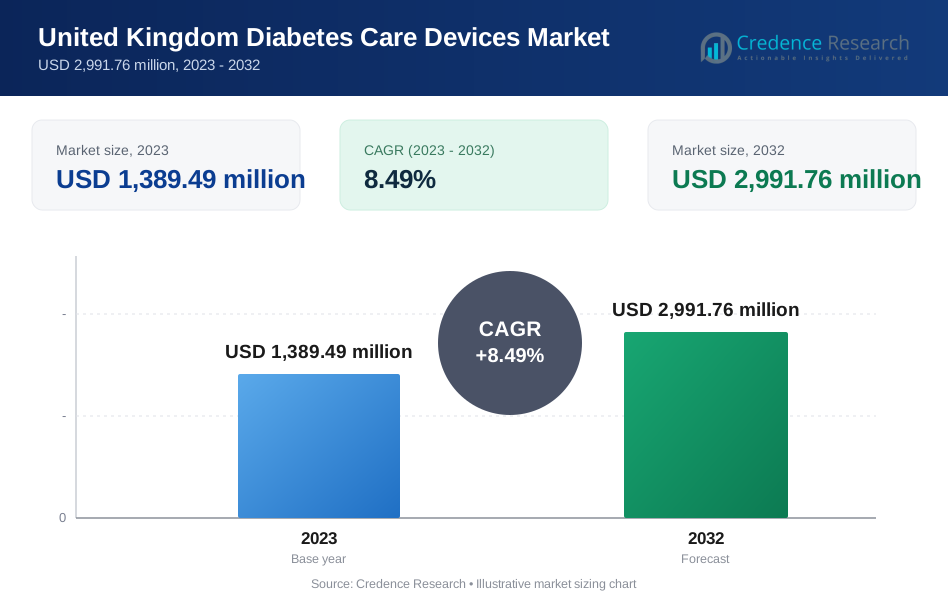
The United Kingdom Diabetes Care Devices Market is projected to grow from USD 1,389.49 million in 2023 to USD 2,991.76 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.49%.
The United Kingdom diabetes care devices market is driven by the rising prevalence of diabetes, an aging population, and increased awareness of the importance of early detection and management. Technological advancements, such as the development of continuous glucose monitoring (CGM) systems and insulin pumps, are enhancing the convenience and accuracy of diabetes management. Additionally, the growing focus on personalized medicine and the adoption of digital health solutions are fueling market growth. The increasing healthcare expenditure and government initiatives to improve diabetes care further support market expansion. Trends also show a shift towards home-based care, with patients seeking more accessible and user-friendly devices for self-monitoring. These drivers, coupled with innovations in device connectivity and integration with mobile apps, are contributing to a positive market outlook for diabetes care devices in the UK.
The United Kingdom diabetes care devices market is influenced by the rising prevalence of diabetes and the increasing demand for advanced healthcare solutions. Key players in this market include major global and regional companies such as Abbott Laboratories, ACON Laboratories, Ascensia Diabetes Care, Becton, Dickinson and Company, Dexcom, F. Hoffmann-La Roche, and Medtronic. These companies lead the market with their innovative products, including continuous glucose monitors, insulin pumps, and self-monitoring devices. Their strong presence across the UK ensures widespread availability of diabetes care solutions, catering to the needs of healthcare providers and patients. The market is also supported by the growing healthcare infrastructure, improved patient awareness, and technological advancements. Regional factors such as government initiatives and healthcare funding further contribute to the development of the diabetes care sector in the UK. These factors are driving growth opportunities and ensuring the market remains competitive and innovative.
Market Insights
- The United Kingdom diabetes care devices market is valued at USD 1,389.49 in 2023 and is projected to grow at a CAGR of 49% from 2023 to 2032.
- Rising prevalence of diabetes and the demand for advanced monitoring and treatment solutions are key drivers of market growth.
- Government initiatives promoting awareness and the adoption of diabetes care devices are further boosting the market.
- Technological advancements, such as continuous glucose monitoring systems and insulin pumps, are driving the adoption of diabetes care devices.
- Invasive procedures and the risk of infection associated with some devices act as a restraint for market expansion.
- High treatment costs of advanced devices may hinder the market for some segments, particularly in price-sensitive regions.
- The market is highly concentrated in regions such as London and Manchester, with strong support from healthcare infrastructure and patient awareness.
Market Drivers
Rising Prevalence of Diabetes
The rising prevalence of diabetes, particularly type 2, is a significant driver of the United Kingdom diabetes care devices market. Type 2 diabetes, closely linked to sedentary lifestyles, poor dietary habits, and obesity, has seen a sharp increase in the UK. For instance, Diabetes UK reports that more than 5.6 million people in the UK are living with diabetes, with around 90% of these cases being type 2 diabetes. Additionally, the aging population is more susceptible to developing diabetes, further intensifying the demand for diabetes care solutions. As more individuals seek ways to manage their condition, the need for innovative and effective devices is growing, supporting the market's expansion.
Technological Advancements
Technological advancements have significantly transformed diabetes care, with continuous glucose monitoring (CGM) systems playing a crucial role in real-time glucose tracking. CGMs enable patients to make informed decisions regarding insulin dosing and lifestyle adjustments, improving overall management. For instance, the NHS has been rolling out hybrid closed-loop systems, also known as artificial pancreas systems, which combine CGMs and insulin pumps to automate insulin delivery. Insulin pumps are another key development, providing precise insulin delivery that enhances glycemic control while reducing the risk of hypoglycemia. Additionally, the rise of digital health solutions, including apps and platforms, facilitates remote monitoring and personalized diabetes management, further driving the demand for advanced devices in the UK.
Government Initiatives and Reimbursement Policies
Government support, particularly through the National Health Service (NHS), is a critical factor in the market's growth. The NHS provides funding for diabetes care devices, ensuring they remain accessible to a broad section of the population. For instance, the NHS Long Term Plan includes commitments to expand access to CGMs and insulin pumps, particularly for those from deprived backgrounds and ethnic minority groups. Moreover, favorable reimbursement policies incentivize the adoption of advanced diabetes technologies, making it easier for patients to access innovative solutions. These initiatives play an essential role in boosting market demand and ensuring that diabetes care devices are integrated into the healthcare system effectively.
Increased Awareness and Patient Empowerment
Increased awareness about diabetes and its associated complications has empowered patients to take a more active role in managing their health. As patients become more knowledgeable about the disease, they are seeking devices that enable self-monitoring and insulin delivery at home. This growing trend of patient empowerment is driving the demand for user-friendly and efficient diabetes care devices. Additionally, the COVID-19 pandemic accelerated the adoption of telehealth, enabling remote monitoring and virtual consultations, which further supported patient involvement in chronic disease management.
Market Trends
Rising Prevalence of Diabetes and Technological Advancements
The increasing prevalence of type 2 diabetes in the United Kingdom is driven by a combination of factors, including an aging population, sedentary lifestyles, unhealthy diets, and rising obesity rates. As these lifestyle-related conditions become more common, the demand for diabetes care devices continues to grow. The aging population is particularly vulnerable, with older adults at a higher risk of developing diabetes, contributing significantly to the market expansion. In parallel, technological advancements in diabetes management are transforming the landscape. Continuous glucose monitoring (CGM) systems, which offer real-time, accurate tracking of glucose levels, are becoming more accessible and user-friendly. These devices empower patients to make better-informed decisions about insulin dosing and lifestyle adjustments. Insulin pump technology has also evolved, providing precise insulin delivery that improves glycemic control and minimizes the risk of hypoglycemia. Additionally, digital health solutions, including apps and platforms, have further enhanced diabetes management by enabling remote monitoring, data sharing, and personalized care plans. These technological innovations not only improve patient outcomes but also contribute to the overall growth of the market by making diabetes management more efficient and convenient.
Government Support, Patient Empowerment, and Telehealth Adoption
Government initiatives, particularly through the National Health Service (NHS), have played a vital role in driving the adoption of advanced diabetes care devices. The NHS continues to prioritize diabetes care, increasing funding for innovative devices and therapies, thus ensuring greater accessibility for patients across the UK. Favorable reimbursement policies also encourage healthcare providers to adopt cutting-edge technologies, further fueling market growth. Alongside these developments, patient empowerment has become a significant trend. Patients are taking an active role in managing their diabetes, seeking devices that allow for self-monitoring and insulin delivery at home. For instance, Diabetes UK's "Taking Control" campaign aims to increase the provision and uptake of diabetes self-management education, helping patients gain the skills and confidence to manage their condition. Educational campaigns and increased awareness are helping individuals make informed decisions about their healthcare, thereby driving demand for more advanced devices. The COVID-19 pandemic accelerated the shift toward telehealth, making remote consultations and monitoring more common. Telehealth platforms and remote monitoring devices have improved patient care, provided convenience, and helped reduce healthcare costs, contributing to the market's continued growth and transformation.
Market Challenges Analysis
High Cost of Devices and Complex Reimbursement Processes
One of the significant challenges facing the United Kingdom diabetes care devices market is the high cost of advanced devices, such as continuous glucose monitoring (CGM) systems and insulin pumps. These devices, while highly effective, often come with a hefty price tag, making them inaccessible to many patients, particularly those with lower incomes. For instance, the NHS provides funding for flash glucose monitors, but only for up to 20% of the type 1 diabetes population, leaving many patients without access to these devices. Additionally, the National Health Service (NHS) faces budget constraints, which further limits the availability of funding for these advanced technologies. As a result, patients may not have access to the most up-to-date and effective devices, hindering their ability to manage their diabetes effectively. The complex reimbursement processes also add another layer of difficulty. Patients and healthcare providers often encounter bureaucratic hurdles, which can be both time-consuming and frustrating. Moreover, varying reimbursement policies across different regions and healthcare providers can create inconsistencies in access to devices, leading to disparities in diabetes care. These financial and procedural challenges contribute to slower adoption rates and reduced accessibility for many patients.
Patient Adherence, Data Privacy, and Regulatory Hurdles
Patient adherence to device usage is another major challenge in the diabetes care devices market. Many of the advanced devices, particularly insulin pumps and CGM systems, can be complex to use and require ongoing maintenance, which may overwhelm patients, especially those with limited experience. Furthermore, user errors, such as incorrect device usage, can lead to inaccurate glucose readings and suboptimal treatment outcomes. Long-term device use can also result in discomfort and fatigue, leading to reduced adherence and decreased effectiveness of treatment. In addition to these challenges, the increasing use of diabetes devices raises concerns about data privacy and cybersecurity. Since these devices collect sensitive health information, they are vulnerable to security breaches and cyberattacks, which could compromise patient privacy. Lastly, stringent regulatory standards in the UK further complicate market entry for new products. The highly competitive nature of the market makes it difficult for new entrants to gain traction, and the delays caused by regulatory hurdles can limit the availability of innovative solutions. These factors together create significant obstacles for both manufacturers and patients, hindering the overall growth and accessibility of the diabetes care devices market.
Market Opportunities
Technological Innovation and Product Development
The United Kingdom diabetes care devices market offers significant opportunities driven by ongoing technological advancements. As continuous glucose monitoring (CGM) systems and insulin pumps become more accurate, affordable, and user-friendly, there is a growing demand for devices that improve the ease and effectiveness of diabetes management. Innovations such as integrated CGM systems, artificial pancreas technologies, and closed-loop systems present opportunities to enhance patient outcomes. Additionally, the rise of digital health solutions, including mobile apps and remote monitoring platforms, offers considerable potential for improving diabetes care. These technologies allow for personalized treatment plans, real-time data sharing with healthcare providers, and more proactive disease management, thus creating a dynamic space for market expansion.
Expanding Market Reach and Government Support
Another opportunity lies in the increased focus on patient empowerment and self-management. With growing awareness about the importance of diabetes care, patients are actively seeking solutions that enable them to manage their condition independently. This trend is expected to drive the demand for self-monitoring devices and insulin delivery systems. Moreover, government initiatives, such as funding from the National Health Service (NHS), are creating a supportive environment for the adoption of advanced diabetes technologies. As the NHS continues to prioritize diabetes care, the increased accessibility of these devices through favorable reimbursement policies will further stimulate market growth. With expanding access to innovative devices, the UK market presents substantial opportunities for manufacturers and healthcare providers to meet the evolving needs of patients.
Market Segmentation Analysis:
By Type:
The United Kingdom diabetes care devices market is segmented into two main types: monitoring devices and delivery devices. Monitoring devices are essential for tracking glucose levels and ensuring effective diabetes management. These include continuous monitoring devices, lancets, test strips, and self-monitoring devices. Continuous glucose monitoring (CGM) systems have gained significant traction in recent years due to their ability to provide real-time glucose data, empowering patients to make informed decisions about their insulin dosing and lifestyle adjustments. Lancets and test strips remain widely used, especially for traditional blood glucose testing, though they are gradually being overshadowed by CGM systems. Self-monitoring devices, while more basic, continue to serve as an affordable and accessible option for many patients, especially those who may not have access to more advanced technologies.
By Monitoring Devices:
The market for lancets and test strips remains a critical component of diabetes management in the UK, particularly for patients who rely on traditional methods of self-monitoring their glucose levels. Lancets, used for blood sample collection, and test strips, used for glucose measurement, continue to play a vital role in the management of diabetes, even with the rise of continuous monitoring technologies. Despite the growth of CGM systems, the demand for self-monitoring devices, which include glucose meters and associated testing products, remains steady due to their affordability, accessibility, and ease of use. These devices are particularly important for patients with type 2 diabetes or those who prefer to manage their condition with less invasive technology. While the market for self-monitoring devices may face competition from more advanced monitoring solutions, it still represents a significant segment within the overall diabetes care devices market in the UK.
Segments:
Based on Type:
- Monitoring
- Delivery
Based on Monitoring Devices:
- Continuous Monitoring Devices
- Lancets
- Test Strips
- Self Monitoring Devices
Based on Delivery Devices:
- Insulin Pumps
- Pens
- Syringes
- Needles
Based on End-Users:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Based on Indication:
- Diabetes Type I
- Diabetes Type II
- Gestational Diabetes
Based on the Geography:
- London
- Manchester
- Birmingham
- Scotland
Regional Analysis
London and Manchester
London, as the capital city, holds the largest market share, estimated at around 35% of the national market. This is driven by the city's diverse and aging population, which has a higher prevalence of diabetes, as well as the large number of healthcare facilities and diabetes care centers. The demand for diabetes care devices in London is also supported by the high adoption of advanced technologies such as continuous glucose monitoring (CGM) systems and insulin pumps, along with government initiatives like the National Health Service (NHS) funding. In addition, the presence of leading healthcare providers, medical device manufacturers, and digital health companies in London fosters a thriving market for diabetes care devices. Manchester, with a market share of approximately 25%, also contributes significantly to the market's growth. The city's robust healthcare system and high diabetes prevalence are key factors driving the demand for monitoring devices, such as self-monitoring glucose meters and test strips, along with insulin delivery systems. Manchester benefits from a strong focus on healthcare innovation, which supports the expansion of diabetes care technology in the region.
Birmingham and Scotland
Birmingham and Scotland represent other key regions in the UK, with distinct characteristics influencing the demand for diabetes care devices. Birmingham, the second-largest city in the UK, is witnessing rapid growth in the adoption of advanced diabetes management technologies. With an estimated market share of 20%, Birmingham benefits from a large population of diabetes patients and a growing emphasis on healthcare improvement. The region has a strong medical and research community, facilitating the development and distribution of innovative diabetes care solutions. The increasing awareness and demand for devices such as CGMs and insulin pumps are particularly evident in the city’s healthcare infrastructure, supporting the expansion of the diabetes care market. In contrast, Scotland, with a market share of approximately 15%, is experiencing a rise in the use of diabetes care devices due to the growing emphasis on healthcare accessibility and patient empowerment. The region’s government and healthcare policies focus on improving diabetes management, making advanced devices more accessible to the population. However, Scotland faces unique challenges in terms of geographic disparities in access to healthcare, with rural areas experiencing lower availability of specialized care and advanced devices. Despite this, the overall market in Scotland continues to grow steadily, supported by government-funded programs and patient education initiatives aimed at enhancing diabetes care across the region.
Key Player Analysis
- Abbott Laboratories
- ACON Laboratories, Inc.
- Ascensia Diabetes Care Holdings AG
- Becton, Dickinson and Company
- Dexcom, Inc.
- Hoffmann-La Roche Ltd
- Johnson & Johnson
- Medtronic plc
- Novo Nordisk A/S
- DIABELOOP
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The competitive landscape of the United Kingdom diabetes care devices market is highly dynamic, with several leading players focusing on innovation and strategic collaborations to maintain their market share. Major companies, including Abbott Laboratories, ACON Laboratories, Ascensia Diabetes Care, Becton Dickinson, Dexcom, F. Hoffmann-La Roche, Johnson & Johnson, Medtronic, and Novo Nordisk, dominate the market. Companies are heavily investing in the development of advanced technologies such as continuous glucose monitoring (CGM) systems, insulin pumps, and smart insulin pens, which cater to the growing demand for accurate and user-friendly solutions. Research and development efforts are centered around improving device accuracy, ease of use, and affordability to meet the diverse needs of patients.
Strategic partnerships, mergers, and acquisitions play a significant role in expanding product portfolios and enhancing market presence. Many companies are also focusing on expanding their distribution networks, ensuring that their products are readily available across multiple healthcare channels. The increasing adoption of digital health technologies, such as mobile applications integrated with diabetes care devices, has become a key competitive factor.
Furthermore, companies are focusing on providing personalized diabetes management solutions, which include tailored treatment plans and remote monitoring capabilities. With advancements in wearable devices and improved connectivity, the competition in this market is expected to intensify, with companies striving to lead in terms of both innovation and customer service.
Recent Developments
- In October 2024, Glooko secured a USD 100 million investment aimed at expanding its diabetes management system. The funding was intended to enhance the company's reach across North America, as well as the Middle East and Asia.
- In August 2024, Medtronic announced its partnership with Abbott, which was expected to improve its struggling diabetes care segment by integrating advanced glucose monitoring technology, enhancing their offerings and potentially strengthening Medtronic's position in the market.
- In March 2024, Dexcom introduced its newest CGM system, Dexcom ONE+, in Ireland. Dexcom ONE+ utilizes Dexcom's top-tier and highly accurate sensor design. This product launch will bolster the company's product portfolio in the Irish market and is expected to boost the company's revenue.
- In May 2023, Medtronic agreed to acquire EOFlow, a manufacturer of insulin devices. The integration of EOFlow with Medtronic's Meal Detection Technology algorithm and advanced continuous glucose monitor (CGM) is expected to enhance the company's ability to serve a broader range of people with diabetes
- In April 2023, Undbio announced its plan to invest USD 100 million in constructing a US-based insulin manufacturing plant. The South Korean company intends to build a new facility in West Virginia to manufacture insulin and distribute its products within the country
- In July 2023, CharmHealth and Bioverge jointly invested in My Diabetes Tutor, a startup focused on improving the lives of individuals with diabetes
Market Concentration & Characteristics
The market concentration of diabetes care devices in the United Kingdom is moderately fragmented, with several key players and emerging companies competing for market share. The presence of both multinational corporations and local innovators ensures a diverse landscape, with competition driving continuous advancements in technology and product offerings. Market concentration is influenced by the dominance of well-established players, which invest heavily in research and development to maintain their competitive edge. These companies focus on expanding their product portfolios with advanced devices, such as continuous glucose monitoring (CGM) systems, insulin pumps, and smart insulin pens, which are gaining popularity due to their precision and ease of use. The characteristics of the UK diabetes care devices market are shaped by growing consumer demand for innovative and user-friendly products that support personalized diabetes management. Key trends include the integration of digital health technologies, such as mobile apps and cloud-based platforms, which enhance remote monitoring and data management for patients and healthcare providers. Furthermore, the increasing prevalence of diabetes in the UK has resulted in greater emphasis on accessibility and affordability of diabetes care devices. The market is also characterized by the growing adoption of wearable devices, which enable continuous monitoring, offering convenience and improved disease management for patients. This dynamic environment fosters innovation, with companies focusing on both product quality and customer experience.
Report Coverage
The research report offers an in-depth analysis based on Type, Monitoring Devices, Delivery Devices, Indication, End-Users and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The United Kingdom diabetes care devices market is expected to experience steady growth driven by the increasing prevalence of diabetes.
- Technological advancements in continuous glucose monitoring (CGM) systems will significantly enhance diabetes management for patients.
- The adoption of insulin pumps and smart insulin pens will rise as they offer more precise and convenient ways to manage blood sugar levels.
- Digital health technologies, including mobile applications and cloud-based platforms, will become integral to diabetes care solutions.
- The integration of artificial intelligence (AI) and machine learning will further improve the accuracy and efficiency of diabetes monitoring devices.
- Wearable diabetes devices will gain popularity due to their ability to offer continuous monitoring with minimal patient intervention.
- Increased focus on patient-centric solutions will lead to the development of more personalized and user-friendly diabetes care products.
- Government initiatives and reimbursement policies will support the expansion and accessibility of diabetes care devices in the UK.
- The demand for non-invasive glucose monitoring devices will rise as patients seek alternatives to traditional finger-prick tests.
- Companies will continue to invest in research and development to introduce next-generation devices that improve both functionality and patient outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the United Kingdom Diabetes Care Devices market?
What factors are driving the growth of the United Kingdom Diabetes Care Devices market?
What are the key segments within the United Kingdom Diabetes Care Devices market?
What are some challenges faced by the United Kingdom Diabetes Care Devices market?
Who are the major players in the United Kingdom Diabetes Care Devices market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 United Kingdom Diabetes Care Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global United Kingdom Diabetes Care Devices Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,389.49 million → 2032: USD 2,991.76 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 United Kingdom Diabetes Care Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. United Kingdom Diabetes Care Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 United Kingdom Diabetes Care Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 United Kingdom Diabetes Care Devices Market Drivers
- 3.3 United Kingdom Diabetes Care Devices Market Restraints & Challenges
- 3.4 United Kingdom Diabetes Care Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 United Kingdom Diabetes Care Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 United Kingdom Diabetes Care Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, United Kingdom Diabetes Care Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 United Kingdom Diabetes Care Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. United Kingdom Diabetes Care Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the United Kingdom Diabetes Care Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 United Kingdom Diabetes Care Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 United Kingdom Diabetes Care Devices Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 United Kingdom Diabetes Care Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in United Kingdom Diabetes Care Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New United Kingdom Diabetes Care Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global United Kingdom Diabetes Care Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America United Kingdom Diabetes Care Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe United Kingdom Diabetes Care Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific United Kingdom Diabetes Care Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America United Kingdom Diabetes Care Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East United Kingdom Diabetes Care Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa United Kingdom Diabetes Care Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. United Kingdom Diabetes Care Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
