
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Luxury Interior Design Market Size 2023 | USD 4,590.88 million |
| UK Luxury Interior Design Market, CAGR | 3.72% |
| UK Luxury Interior Design Market Size 2032 | USD 6,377.42 million |
Market Overview
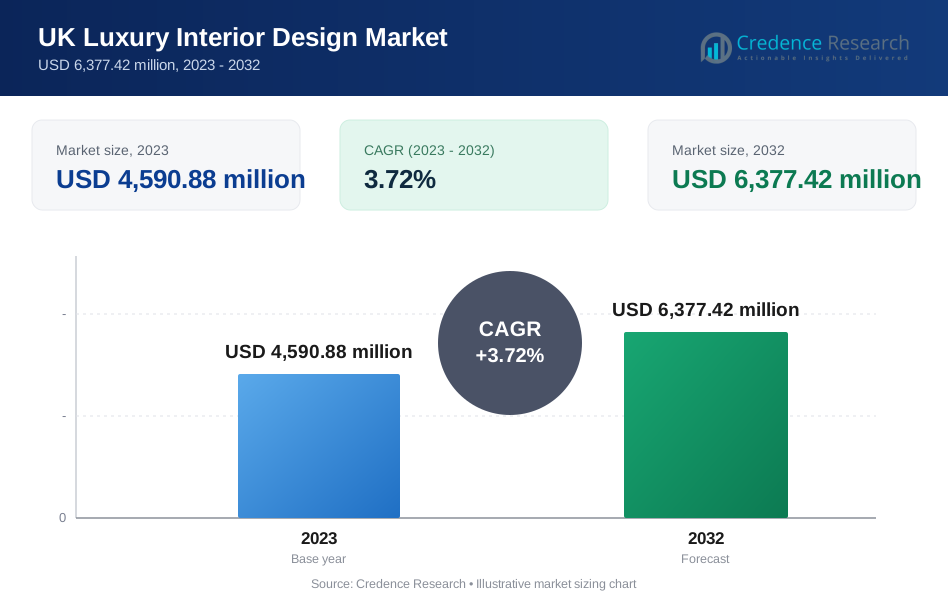
The UK Luxury Interior Design Market is projected to grow from USD 4,590.88 million in 2023 to an estimated USD 6,377.42 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.72% from 2024 to 2032. This growth underscores the increasing demand for bespoke, high-end interior solutions driven by affluent consumers and expanding residential and commercial real estate development.
Key drivers influencing market growth include the rising preference for luxury living spaces, fueled by increased disposable incomes and evolving consumer tastes. Additionally, technological advancements in home automation and sustainable design practices are setting new trends in the industry. The growing emphasis on eco-friendly and energy-efficient designs further bolsters demand, as sustainability becomes a core focus for both designers and end-users. The integration of smart home systems and luxury furnishings also adds significant value, enhancing the appeal of high-end interior design services.
Geographically, London dominates the market due to its concentration of wealth and real estate investments, followed by affluent regions such as South East England and Scotland. These areas showcase significant demand for luxury residential and commercial projects. Prominent players in the UK luxury interior design market include Helen Green Design, Katharine Pooley, and Candy & Candy, alongside emerging boutique firms specializing in bespoke solutions. These companies are driving innovation and offering tailored services to meet the diverse preferences of a discerning clientele.
Market Insights
- The market is projected to grow from USD 4,590.88 million in 2023 to USD 6,377.42 million by 2032, with a CAGR of 3.72% from 2024 to 2032.
- Increasing preferences for personalized, high-end interiors and premium materials are driving significant market growth.
- Smart home integration, virtual design tools, and home automation systems are reshaping luxury interior solutions and attracting affluent clients.
- A strong focus on eco-friendly materials, energy-efficient designs, and ethical sourcing aligns with consumer trends and regulatory demands.
- Expensive premium materials, skilled labor, and sustainability certifications pose challenges for project budgets and timelines.
- London accounts for 42% of the market share, driven by wealth concentration and luxury real estate developments, followed by South East England and Scotland.
- Expanding luxury real estate projects in regions like the Midlands and North West England present new growth opportunities for designers and firms.
Market Drivers
Rising Affluence and Demand for Personalized Spaces
The luxury interior design market in the UK is significantly influenced by the increasing wealth among high-net-worth individuals (HNWIs) and ultra-high-net-worth individuals (UHNWIs). For instance, a recent report indicated a 4.2% rise in the number of UHNWIs globally in 2024, showcasing a growing clientele eager to invest in bespoke interior designs. This trend is particularly evident in urban centers like London, where affluent clients seek personalized spaces that reflect their unique lifestyles. They prioritize exclusive materials, custom furnishings, and artworks that resonate with their identities. This demand extends beyond urban areas to suburban and rural regions, where luxury second homes are often outfitted with top-tier design solutions. As consumers increasingly value individuality and self-expression in their living environments, the luxury interior design sector is adapting to meet these expectations, emphasizing tailored experiences that combine functionality with elegance.
Advancements in Technology and Smart Homes Integration
Technological advancements, particularly in smart home systems, have become a pivotal driver in the UK luxury interior design market. Affluent consumers demand seamless integration of technology, such as intelligent lighting, climate control, and automated security systems, into their interiors. Designers are increasingly collaborating with technology providers to deliver aesthetic solutions that do not compromise functionality. Innovations in virtual and augmented reality tools have also enhanced design visualization, allowing clients to interact with proposed layouts before execution. This fusion of technology and design not only enhances convenience but also aligns with the market’s trend of delivering luxurious yet practical living experiences.
Growing Focus on Sustainability and Eco-Friendly Design
Sustainability has emerged as a central theme in luxury interior design, driven by heightened environmental awareness among consumers and regulatory pressures. For instance, designers are increasingly prioritizing eco-friendly materials such as responsibly sourced wood and recycled metals while ensuring quality and aesthetics remain uncompromised. This shift towards sustainability is evident as many designers now incorporate energy-efficient systems and green building certifications into their projects. A notable trend is the integration of solar energy solutions and water-saving fixtures, appealing to socially conscious clients who value ethical consumption. This emphasis on sustainable practices not only aligns with consumer preferences but also enhances the overall value proposition of luxury designs. As clients seek to blend opulence with environmental stewardship, the luxury interior design market is evolving to meet these demands, reflecting a broader societal commitment to sustainability.
Expanding Real Estate and Commercial Development
The resurgence of the UK real estate sector presents significant opportunities for luxury interior designers. For instance, high-value residential projects and upscale commercial developments are driving demand for sophisticated design solutions tailored to affluent consumers. Luxury hotels are increasingly investing in bespoke refurbishments aimed at attracting high-end travelers and business clients. Recent trends indicate that developers are focusing on creating immersive environments that resonate with modern consumers seeking unique experiences. As competition intensifies within the real estate market, property owners recognize the importance of high-end interiors in differentiating their offerings. This has led to a notable increase in investments aimed at enhancing aesthetic appeal through innovative design strategies. Consequently, interior designers are tasked with delivering exceptional spaces that not only meet but exceed client expectations, solidifying their role as key players in the evolving landscape of luxury real estate development.
Market Trends
Incorporation of Smart Technologies and Home Automation
The integration of smart technologies is revolutionizing the UK luxury interior design market, transforming how affluent clients interact with their homes. For instance, modern luxury residences often feature intelligent lighting systems that adjust automatically based on the time of day or occupancy, enhancing both convenience and ambiance. Homeowners can control their lighting with voice commands or smartphone apps, allowing them to create the perfect atmosphere for any occasion. Additionally, automated window treatments are becoming standard, providing privacy and energy efficiency while maintaining a sleek aesthetic. These systems can be programmed to open or close based on natural light levels, seamlessly blending functionality with design. Moreover, smart kitchens equipped with voice-activated appliances streamline meal preparation by allowing users to set timers or adjust temperatures remotely. This convergence of technology and design not only elevates the living experience but also aligns with the growing demand for sophisticated, user-friendly environments that cater to modern lifestyles.
Emphasis on Sustainability and Ethical Design
Sustainability has emerged as a central tenet in luxury interior design, reflecting a shift in consumer values towards eco-conscious living. For instance, high-end projects are increasingly incorporating reclaimed materials such as wood and metal, which add character while promoting environmental responsibility. Designers are also utilizing energy-efficient systems like low-energy lighting and solar panels, ensuring that luxurious spaces do not compromise on sustainability. Furthermore, the use of biodegradable fabrics and non-toxic finishes is becoming commonplace, catering to clients who prioritize health and wellness alongside aesthetics. This commitment to sustainability is evident in projects like eco-friendly villas that harmonize luxury with environmental stewardship. By integrating biophilic elements such as indoor gardens and natural light optimization, designers create serene spaces that foster well-being while reflecting a deep respect for nature. This holistic approach to design not only enhances the beauty of interiors but also embodies a responsible ethos that resonates with today's discerning homeowners.
Revival of Artisanal Craftsmanship and Customization
Bespoke design and artisanal craftsmanship are at the heart of the UK luxury interior design market. Clients increasingly desire unique, one-of-a-kind pieces that reflect their personal tastes and preferences. This trend has revived traditional craftsmanship techniques, with designers collaborating with artisans to create custom furniture, handwoven textiles, and intricate artworks. Luxury interior design is now characterized by an appreciation for detail, with elements such as hand-carved woodwork, inlaid stone patterns, and custom-designed lighting fixtures becoming staples of high-end projects. This resurgence of craftsmanship also emphasizes the importance of storytelling, as clients value designs that showcase heritage, skill, and authenticity.
Rise of Multifunctional and Hybrid Spaces
The evolving lifestyles of luxury consumers have fueled demand for multifunctional and hybrid spaces within homes and commercial properties. Post-pandemic, there has been a significant shift toward creating interiors that accommodate diverse needs, from work and relaxation to fitness and entertainment. High-end residences now often include home offices with luxurious furnishings, state-of-the-art gyms, and private cinemas. In commercial settings, luxury interiors are designed to foster collaboration, creativity, and comfort, blending workspaces with lounge-like aesthetics. This trend highlights the growing emphasis on versatility in design, ensuring that spaces remain functional without compromising on elegance and style.
Market Challenges
High Cost of Materials and Skilled Labor
The UK luxury interior design market is significantly impacted by the high costs associated with premium materials and skilled labor. For instance, the procurement of rare materials such as exotic woods and natural stones can lead to project budgets soaring into tens of thousands of pounds. A single bespoke furniture piece crafted by a skilled artisan may command prices that reflect both the quality of materials and the level of craftsmanship involved. Additionally, the sourcing of sustainable materials adds complexity; eco-friendly options like reclaimed wood or recycled metals are often limited in availability and come at a premium, complicating design choices and inflating costs. Moreover, the reliance on skilled professionals further exacerbates these challenges. Designers and artisans with extensive experience demand higher fees due to their expertise, which can lead to significant cost increases for clients. The scarcity of such talent can also result in project delays, as firms struggle to find qualified individuals to meet client expectations. Consequently, these financial pressures can limit access to luxury interior design services, particularly during economic downturns when clients may be more budget-conscious.
Navigating Sustainability Expectations and Regulatory Compliance
The growing emphasis on sustainability in the UK luxury interior design market presents a complex challenge for designers. Clients increasingly demand eco-friendly solutions that align with luxury aesthetics, but achieving this balance is not straightforward. For instance, while sustainable materials are in high demand, they are often more expensive and less readily available than traditional options. Designers face difficulties in sourcing high-quality, sustainable materials that meet both environmental standards and luxury expectations. Furthermore, evolving regulations surrounding environmental compliance add another layer of complexity. Designers must stay abreast of changing building standards and sustainability regulations, which can vary significantly across regions. This necessitates continuous education and adaptation, straining resources for many firms, particularly smaller or boutique studios. As a result, meeting these dual demands without compromising on quality or aesthetic appeal remains a significant hurdle in the luxury interior design landscape.
Market Opportunities
Growing Demand for Sustainable Luxury Design Solutions
The UK luxury interior design market is increasingly influenced by the demand for sustainable and eco-conscious design solutions. Many interior designers are prioritizing the use of eco-friendly materials such as reclaimed wood, bamboo, and recycled glass. These materials enhance the aesthetic appeal of luxury spaces while significantly reducing the environmental impact associated with traditional building materials. Additionally, the trend towards biophilic design focuses on incorporating natural elements into interiors, improving air quality and occupant well-being. By utilizing large windows for natural light and integrating indoor plants, designers create serene environments that foster a connection with nature.Advancements in energy-efficient technologies are also becoming standard in luxury interior design. High-end projects now often feature smart home systems that optimize energy use, such as intelligent lighting and heating solutions. These innovations help reduce carbon footprints and lower utility costs for homeowners, making them attractive options for affluent clients who prioritize sustainability alongside luxury. This growing segment not only positions firms as leaders in ethical luxury design but also attracts socially conscious consumers, expanding their client base and reinforcing the importance of responsible design practices in today’s market.
Expanding Luxury Real Estate and Commercial Developments
The continuous growth of luxury real estate and high-end commercial projects in the UK offers substantial opportunities for the luxury interior design market. Urban hubs like London and affluent regions in South East England and Scotland are witnessing an increase in premium residential developments, boutique hotels, and high-end office spaces. Developers are investing heavily in bespoke interiors to differentiate their offerings in a competitive market. This demand for high-quality interiors provides designers with opportunities to collaborate on large-scale projects, showcasing their expertise.Moreover, the rising trend of hybrid spaces—combining residential and commercial elements—offers further scope for innovation and customization in luxury interiors. Designers can create versatile environments that cater to both living and working needs, appealing to a clientele that values flexibility without compromising on style or quality. As property owners seek to enhance their spaces' appeal through unique designs, the collaboration between developers and designers becomes essential. This synergy not only elevates the standard of luxury interiors but also contributes to a vibrant real estate landscape that continually adapts to evolving consumer preferences.
Market Segmentation Analysis
By Type
The repeatedly decorated segment dominates the market, driven by high-net-worth individuals (HNWIs) and businesses seeking to refresh and modernize their interiors. This segment reflects a preference for staying aligned with evolving design trends, such as the integration of smart technologies, sustainable materials, and customized aesthetics. Repeated renovations often involve minor upgrades or complete overhauls to maintain exclusivity and elegance. This segment benefits significantly from affluent customers’ willingness to invest in high-quality craftsmanship and bespoke solutions. The newly decorated segment encompasses projects for new properties, including luxury homes, boutique hotels, and premium commercial spaces. Growth in this segment is fueled by the expansion of the real estate market and new developments targeting affluent buyers and tenants. High demand for turnkey luxury interiors in prime urban areas such as London further supports this segment. Designers in this space often work collaboratively with property developers to create unique, high-end spaces that attract discerning clients.
By Application
The residential segment accounts for a significant share of the UK luxury interior design market. Increasing demand for bespoke interiors in private homes, apartments, and estates drives growth in this segment. Homeowners prioritize creating personalized, elegant living spaces that reflect their lifestyles, incorporating features like custom furniture, eco-friendly materials, and smart home systems. Post-pandemic trends, such as multifunctional spaces for work and leisure, have also contributed to heightened demand in this segment. The commercial segment, including luxury hotels, office spaces, and retail outlets, represents another critical area of growth. Businesses are investing in high-end interiors to enhance brand image and provide immersive experiences for clients and employees. Boutique hotels and premium office spaces, in particular, rely on sophisticated interiors to attract and retain clientele in competitive markets. This segment also benefits from the growing trend of hybrid spaces combining work, relaxation, and entertainment elements. The "others" segment includes specialized spaces such as art galleries, museums, and luxury yachts. This niche segment caters to clients seeking highly customized interiors with unique design requirements. While smaller in scale, it offers significant opportunities for designers focusing on exclusivity and innovation.
Segments
Based on Type
- Repeatedly Decorated
- Newly Decorated
Based on Application
- Residential
- Commercial
- Others
Based on Region
- London
- South East England
- Scotland
- others
Regional Analysis
London (42%)
London dominates the UK luxury interior design market, accounting for approximately 42% of the market share. The city’s high concentration of high-net-worth individuals (HNWIs), international investors, and luxury real estate developments fuels this dominance. Central London neighborhoods, such as Mayfair, Chelsea, and Knightsbridge, are hotspots for bespoke residential interiors and luxury commercial spaces, including boutique hotels and premium office environments. London also leads in sustainability trends, with clients increasingly seeking eco-friendly, smart home-integrated designs. The city’s global influence attracts renowned designers, making it a hub for innovation and high-end design projects.
South East England (25%)
South East England holds the second-largest market share at approximately 25%. This region benefits from its proximity to London, attracting affluent homeowners who seek luxury interiors for suburban residences and vacation homes. Areas such as Surrey and Berkshire are notable for high-end residential developments and estates. The region also features luxury refurbishments in commercial properties, particularly boutique hotels and spas, catering to an upscale clientele. Growth in South East England reflects an increasing demand for personalized, sustainable interiors outside urban centers.
Key players
- Aecom
- Gensler
- Jacobs Engineering Group Inc.
- Perkins and Will
- Stantec Inc.
- Areen Design Services Ltd.
- IA Interior Architects
- Cannon Design
- Hirsch Bedner Associates
- NELSON & Associates Interior Design and Space Planning Inc.
- Alidad
- Bergman Interiors
Competitive Analysis
The UK luxury interior design market is characterized by intense competition among global giants and niche local players, each striving to differentiate themselves. Firms like Aecom, Gensler, and Jacobs Engineering Group Inc. leverage their extensive global presence and multidisciplinary expertise to secure large-scale projects. Meanwhile, companies such as Areen Design Services Ltd., Alidad, and Bergman Interiors focus on bespoke, high-quality designs, catering to niche clientele seeking personalized services. Sustainability and technological integration serve as key competitive differentiators, with market leaders incorporating eco-friendly materials and smart technologies into their designs. Boutique firms excel by offering tailored services, emphasizing artisanal craftsmanship and heritage design elements. The competitive landscape is further intensified by the growing demand for innovative, multifunctional spaces, challenging players to consistently evolve their offerings while maintaining the highest standards of luxury. This diversity fosters dynamic competition, driving overall market growth.
Recent Developments
- In December 2024, AECOM announced its success in securing positions on the UK’s Asset Management Period 8 (AMP8) water infrastructure frameworks, exceeding the value of previous contracts. This achievement reflects AECOM's commitment to sustainable design solutions in the UK, aligning with the growing demand for environmentally responsible practices in luxury interior design projects. The firm continues to integrate innovative strategies to enhance the aesthetic and functional aspects of its designs, contributing to a more sustainable built environment.
- In January 2025, Gensler released its annual Design Forecast report, highlighting trends that will shape the future of luxury interior design. The report emphasizes the importance of sustainability and adaptive reuse in creating luxurious spaces that meet modern needs. Gensler's focus on integrating artificial intelligence into design processes aims to enhance creativity and efficiency, positioning the firm as a leader in innovative design solutions within the UK luxury market.
- In October 2024, Jacobs showcased its commitment to creating people-centric environments through a series of projects aimed at improving workplace functionality and aesthetics. This initiative aligns with the increasing demand for bespoke interior solutions that reflect clients' values and preferences in the luxury sector.
- In January 2025, the Perkins and Will unveiled its first Environmental, Social, and Governance (ESG) report, outlining advanced sustainable design guidance for global teams. This initiative underscores Perkins and Will's dedication to creating luxurious interiors that not only meet aesthetic standards but also promote environmental responsibility.
- In April 2024, Stantec was appointed as the lead interior designer for a landmark redevelopment project in Hollywood, Florida. This mixed-use development will feature luxury residential units alongside retail spaces, showcasing Stantec's expertise in creating high-end environments that cater to diverse client needs. The project reflects Stantec's ongoing commitment to innovative design solutions that enhance urban living experiences while maintaining a focus on sustainability.
- In November 2024, Areen was appointed to oversee the interior design of a new five-star hotel in Morocco, blending traditional Moroccan aesthetics with modern luxury elements. This project highlights Areen's ability to create unique environments that resonate with local culture while appealing to international clientele.
- In June 2024, Alidad's recent work showcased at the WOW!House exhibition highlighted his ability to merge historical influences with contemporary luxury design. His project for Watts 1874 was particularly noted for its intricate detailing and rich narrative elements, demonstrating how personal stories can enhance interior spaces. This approach resonates well with current trends emphasizing character-driven design.
- In May 2024, Bergman Interiors were awarded for their unique designs that blend luxurious materials with functional layouts. Their focus on creating bespoke environments tailored to individual client needs positions them as a leading firm within London's competitive luxury interior market.
Market Concentration and Characteristics
The UK luxury interior design market exhibits a moderately concentrated structure, with a blend of global firms and boutique specialists dominating the competitive landscape. Large multinational players such as Aecom, Gensler, and Jacobs Engineering Group Inc. leverage their scale, technological expertise, and extensive portfolios to capture high-value commercial and residential projects. Simultaneously, boutique firms like Alidad and Bergman Interiors cater to niche markets, emphasizing personalized services, bespoke craftsmanship, and heritage-driven designs. The market is characterized by its focus on innovation, sustainability, and customization, driven by affluent clients who demand unique and exclusive solutions. Technological integration, such as smart home systems, and a growing emphasis on eco-friendly materials further shape the market's offerings. The presence of both global leaders and highly specialized local firms ensures dynamic competition and a wide array of design options, reflecting the diverse needs of the UK’s luxury clientele.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK luxury interior design market is expected to grow steadily, driven by increasing demand for bespoke designs and a forecasted CAGR of 3.72% from 2024 to 2032.
- Smart home integration and advancements in virtual and augmented reality tools will redefine design processes, enhancing customer engagement and project execution.
- Eco-friendly designs and sustainable material sourcing will continue to gain prominence as consumers and businesses prioritize environmental consciousness.
- Growth in high-value residential and commercial real estate projects, particularly in London and South East England, will boost demand for premium interior design services.
- The trend of multifunctional spaces combining work, leisure, and entertainment will create new opportunities for innovative and versatile interior design solutions.
- Clients will increasingly seek highly personalized interiors, emphasizing bespoke craftsmanship and unique design elements to reflect their lifestyles.
- Adoption of design management software and digital collaboration tools will streamline processes, reduce costs, and improve project delivery timelines.
- International design trends and collaborations with global brands will shape the UK market, enhancing its diversity and appeal to a broader clientele.
- Designs promoting wellness, with features like natural lighting, biophilic elements, and ergonomic layouts, will gain traction among luxury clients.
- Regions like the Midlands and North West England will see increased demand for luxury interiors, fueled by urban regeneration and regional economic growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK luxury interior design market in 2023, and what is the projected size by 2032?
What are the primary factors driving growth in the UK luxury interior design market?
Which geographical regions dominate the UK luxury interior design market?
How is sustainability influencing the UK luxury interior design market?
What role does technology play in the UK luxury interior design market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Luxury Interior Design Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Luxury Interior Design Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 4,590.88 million → 2032: USD 6,377.42 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Luxury Interior Design Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Luxury Interior Design Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Luxury Interior Design Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Luxury Interior Design Market Drivers
- 3.3 UK Luxury Interior Design Market Restraints & Challenges
- 3.4 UK Luxury Interior Design Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Luxury Interior Design Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Luxury Interior Design Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Luxury Interior Design category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Luxury Interior Design Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Luxury Interior Design Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Luxury Interior Design market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Luxury Interior Design Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Luxury Interior Design Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Luxury Interior Design Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Luxury Interior Design (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Luxury Interior Design Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Luxury Interior Design Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Luxury Interior Design Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Luxury Interior Design Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Luxury Interior Design Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Luxury Interior Design Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Luxury Interior Design Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Luxury Interior Design Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Luxury Interior Design Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
