
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Managed Services Market Size 2023 | USD 15,349.99 million |
| UK Managed Services Market, CAGR | 7.03% |
| UK Managed Services Market Size 2032 | USD 28,291.12 million |
Market Overview
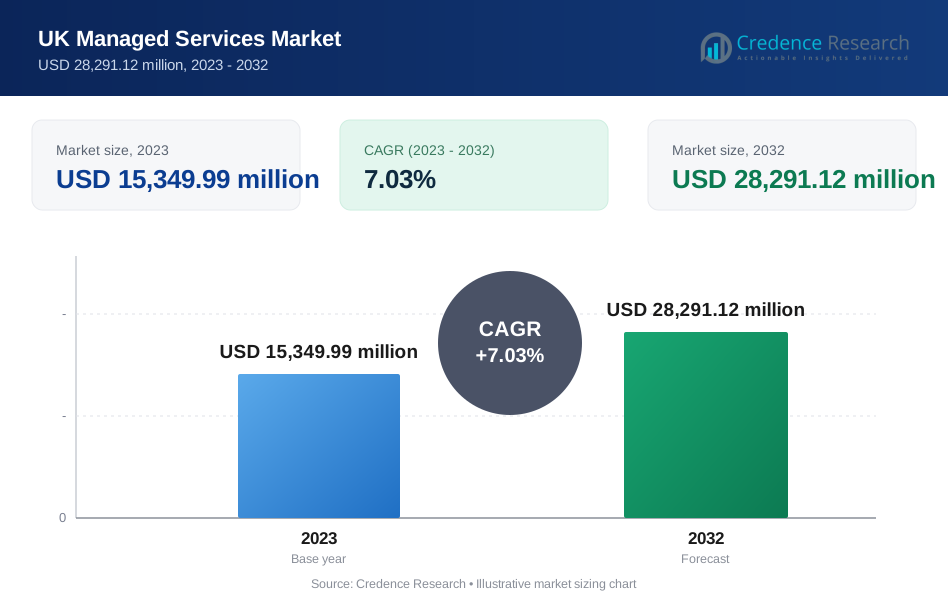
The UK Managed Services Market is expected to grow from USD 15,349.99 million in 2023 to USD 28,291.12 million by 2032, with a compound annual growth rate (CAGR) of 7.03%.
The UK Managed Services market is driven by the increasing demand for cost-effective IT solutions, digital transformation, and the growing complexity of IT infrastructure. Businesses are increasingly outsourcing their IT management to focus on core operations while ensuring scalability, security, and efficiency. The rise in cybersecurity threats is also fueling the demand for managed security services, as companies seek expert assistance to protect sensitive data and systems. Additionally, the adoption of cloud computing and the need for businesses to leverage advanced technologies, such as artificial intelligence and automation, are contributing to market growth. The shift toward remote and hybrid work models further accelerates the need for managed services that offer seamless support, robust network management, and collaboration tools. As companies seek to stay competitive, the adoption of managed services continues to rise, driven by a need for flexibility, cost optimization, and enhanced service delivery.
The UK Managed Services market is characterized by a diverse geographic landscape, with major hubs in cities like London, Manchester, Birmingham, and Scotland, each hosting a variety of industries that drive the demand for IT solutions. London remains the central business hub, attracting global enterprises that require comprehensive IT and security services. Manchester and Birmingham, with their growing tech sectors, are seeing increasing demand for managed network and cloud services. Scotland’s focus on energy and finance sectors also contributes to the growing need for specialized managed services. Key players in the UK Managed Services market include industry leaders like BT, Deloitte, Microsoft, and Google, alongside local providers such as BCN Group, OryxAlign, and Babble. These companies offer a wide range of services, including IT infrastructure management, cybersecurity, cloud services, and business continuity solutions, catering to businesses of all sizes across the country.
Market Insights
- The UK Managed Services market was valued at USD 15,349.99 million in 2023 and is expected to reach USD 28,291.12 million by 2032, growing at a CAGR of 7.03%.
- Increased adoption of cloud computing and digital transformation across industries is driving the demand for managed services in the UK.
- Rising cybersecurity threats and the need for robust IT infrastructure are fueling the demand for managed security services.
- Key trends include the integration of AI and automation in managed services, enabling enhanced operational efficiency and service delivery.
- The market is highly competitive, with major players like BT, Deloitte, Microsoft, and Google, alongside local providers such as BCN Group and OryxAlign.
- Market restraints include the talent shortage in the IT sector and challenges in maintaining regulatory compliance, especially in data privacy.
- Regional markets like London, Manchester, and Birmingham are leading the adoption of managed services due to their diverse industries and technological advancements.
Market Drivers
Increasing Demand for Cost-Effective IT Solutions
One of the primary drivers of the UK Managed Services market is the rising demand for cost-effective IT solutions. Businesses are under pressure to optimize operational expenses, and outsourcing IT management provides an efficient way to do so. By leveraging managed services, companies can avoid high upfront costs associated with infrastructure and staff recruitment. Instead, they benefit from predictable monthly fees, which help in budgeting and reducing overall IT expenditures. This cost-efficient approach is particularly appealing to small and medium-sized enterprises (SMEs) that seek to remain competitive without investing heavily in IT infrastructure.
Digital Transformation and Cloud Adoption
The ongoing digital transformation and the widespread adoption of cloud computing are major factors propelling the demand for managed services in the UK. As businesses migrate to cloud platforms, the complexity of managing these environments increases. Managed services providers (MSPs) offer specialized expertise to ensure seamless cloud integration, maintenance, and optimization. For instance, a report by PA Consulting highlighted that UK businesses are increasingly outsourcing IT services to reduce costs and improve operational efficiency. This allows companies to focus on their core business operations while relying on MSPs to handle the technical aspects. The flexibility and scalability provided by cloud solutions further encourage businesses to seek managed services to maximize their IT infrastructure.
Rising Cybersecurity Concerns
Cybersecurity threats continue to be a significant driver in the UK Managed Services market. With the increasing frequency and sophistication of cyberattacks, organizations are recognizing the need for robust security measures. Managed security services offer businesses access to expert cybersecurity professionals who can monitor, detect, and mitigate potential risks in real-time. For instance, the Cyber Security Breaches Survey 2024 reported that 50% of UK businesses experienced some form of cyberattack in the past year. By outsourcing security management, companies can ensure their networks, systems, and data are protected against breaches, thereby minimizing the impact of potential security threats. As cyber threats grow more complex, the reliance on managed security services is expected to increase.
Shift Toward Remote and Hybrid Work Models
The shift to remote and hybrid work models has further fueled the demand for managed services. With a geographically dispersed workforce, organizations need reliable IT infrastructure and support to ensure seamless communication, collaboration, and data access. Managed services help businesses maintain network stability, provide secure remote access, and manage virtual environments effectively. As more organizations embrace flexible work arrangements, the need for managed services to support these operations is becoming more critical, driving market growth in the UK.
Market Trends
Increased Adoption of Artificial Intelligence and Automation
One of the key trends in the UK Managed Services market is the increasing adoption of artificial intelligence (AI) and automation. Businesses are leveraging AI-driven tools to enhance operational efficiency and decision-making. Managed services providers are integrating AI technologies into their offerings, enabling predictive maintenance, automated network management, and improved system monitoring. For instance, the UK government's AI sector study highlighted that over 3,000 AI companies are operating in the UK, contributing significantly to the economy and driving innovation across various sectors. Automation is also playing a vital role in streamlining routine tasks, reducing human error, and improving service delivery. This trend is helping organizations optimize resources and enhance their overall IT performance, driving further demand for managed services.
Focus on Cybersecurity as a Service
As cybersecurity threats become more sophisticated, there is a growing trend of Managed Security Services (MSS) in the UK. Companies are increasingly turning to managed services providers for specialized security solutions to safeguard their networks, applications, and data. Services such as threat detection, vulnerability management, and compliance monitoring are in high demand. Managed Security Service Providers (MSSPs) are focusing on advanced security capabilities, including real-time threat intelligence and proactive defense strategies, which are critical as cyberattacks become more prevalent. For instance, the Cyber Security Breaches Survey 2024 reported that 50% of UK businesses experienced some form of cyberattack in the past year, highlighting the critical need for robust cybersecurity measures. This trend is reshaping the cybersecurity landscape and is expected to continue growing in the managed services sector.
Shift to Cloud-Based Managed Services
The UK Managed Services market is witnessing a significant shift toward cloud-based services. As more businesses move their operations to the cloud, the need for managed services to oversee cloud infrastructure and optimize performance increases. Managed services providers are offering cloud management, migration, and optimization services to help businesses leverage the full potential of cloud computing. Additionally, cloud-based solutions offer scalability, flexibility, and cost-efficiency, making them increasingly attractive to companies of all sizes. This trend is fueling the growth of the market as more organizations prioritize cloud-first strategies.
Rise in Demand for Hybrid IT Environments
The trend toward hybrid IT environments is another notable development in the UK Managed Services market. Many businesses are opting for a combination of on-premises infrastructure and cloud services to meet their unique operational needs. Managed services providers are helping organizations manage and integrate these hybrid environments, ensuring smooth data flow and connectivity across both cloud and on-premise systems. As hybrid IT strategies become more common, businesses are relying on managed services to ensure optimal performance, security, and compliance across their IT ecosystems. This trend is expected to continue as organizations seek flexible and customized IT solutions.
Market Challenges Analysis
Talent Shortage and Skill Gaps
One of the significant challenges facing the UK Managed Services market is the ongoing shortage of skilled professionals. As businesses increasingly rely on managed services for complex IT tasks, the demand for highly trained personnel in areas like cybersecurity, cloud management, and AI integration continues to grow. However, the availability of qualified talent does not meet this demand. The skills gap in the technology sector makes it difficult for managed services providers to recruit and retain the necessary expertise. This shortage can result in service delivery delays, lower-quality solutions, and a potential increase in operational risks, as businesses may struggle to find and hire the right professionals for their needs.
Data Privacy and Regulatory Compliance
Data privacy and regulatory compliance remain significant challenges for the UK Managed Services market. As data protection regulations such as the GDPR become more stringent, businesses must ensure their managed services providers comply with these laws. Failure to adhere to regulatory requirements can result in severe penalties and damage to a company’s reputation. For managed services providers, maintaining compliance across diverse industries and jurisdictions is complex and resource-intensive. Additionally, the growing concerns around data security and privacy make it crucial for providers to implement strong data protection measures. Furthermore, the UK Information Commissioner's Office (ICO) reported an increase in data breach incidents, emphasizing the need for robust compliance measure. Balancing the need for innovation with compliance and security requirements can be challenging, particularly as the landscape of regulations continues to evolve.
Market Opportunities
The UK Managed Services market presents significant opportunities driven by the growing need for digital transformation and technological advancements. As businesses increasingly move towards cloud-based solutions, the demand for managed services to optimize cloud infrastructure, ensure data security, and manage remote networks is expanding. Providers have the opportunity to capitalize on the shift to cloud-first strategies by offering services that enhance scalability, cost efficiency, and business continuity. Furthermore, the rise in automation and artificial intelligence (AI) presents opportunities for managed services providers to deliver smarter, more efficient solutions, automating routine tasks and improving service delivery. This technological shift allows providers to introduce innovative offerings that address the evolving needs of businesses across various sectors.
Another key opportunity lies in the expanding need for managed security services. As cyber threats become more sophisticated, businesses are prioritizing cybersecurity and turning to managed services providers for expertise in safeguarding their data and infrastructure. Providers can capitalize on this growing demand by offering tailored cybersecurity services, such as threat detection, risk assessments, and compliance management. Additionally, the increasing adoption of hybrid IT environments provides managed services companies with the chance to help organizations navigate and manage complex IT ecosystems that blend on-premises and cloud solutions. As businesses continue to prioritize flexibility, security, and efficiency, managed services providers can position themselves as crucial partners in driving digital transformation while maintaining operational integrity and compliance.
Market Segmentation Analysis:
By Service Type:
The UK Managed Services market is segmented by service type, with each category addressing specific business needs. The Managed IT Infrastructure & Data Center segment remains a dominant player, as businesses seek external expertise to manage their IT infrastructure and data storage efficiently. Managed Network services are also in high demand, providing organizations with network management, optimization, and security solutions to ensure seamless connectivity and minimize downtime. Managed Communication & Collaboration services are growing rapidly due to the rise in remote and hybrid work models, offering businesses tools to enhance internal and external communication. Managed Security services are witnessing substantial growth as cybersecurity threats increase, with organizations seeking to protect their data and networks. Managed Information services focus on data management, analytics, and business intelligence, enabling organizations to derive actionable insights. Other services, such as managed services for AI and IoT, also contribute to the market, catering to niche demands.
By Deployment Type:
The deployment type segment of the UK Managed Services market is divided into on-premise and cloud solutions, each catering to specific customer needs. On-premise managed services are preferred by organizations that require full control over their IT infrastructure and data security. This model is popular among industries with stringent regulatory requirements or those handling sensitive data. On the other hand, cloud-based managed services are rapidly gaining traction due to their flexibility, scalability, and cost-efficiency. As businesses increasingly adopt cloud-first strategies, the demand for cloud-managed services continues to rise, enabling companies to offload infrastructure management to service providers while focusing on core business operations. This shift toward the cloud offers growth opportunities for managed services providers to offer integrated solutions that meet the evolving needs of businesses in the digital age.
Segments:
Based on Service Type:
- Managed IT Infrastructure & Data Center
- Managed Network
- Managed Communication & Collaboration
- Managed Information
- Managed Security
- Others
Based on Deployment Type:
- On-premise
- Cloud
Based on Enterprise Size:
- Large Enterprises
- SME’s
Based on End User:
- IT & Telecom
- BFSI
- Manufacturing
- Retail
- Government
- Others
Based on the Geography:
- London
- Manchester
- Birmingham
- Scotland
Regional Analysis
London
London, the capital of the UK, dominates the Managed Services market, accounting for approximately 45% of the total market share. The region's robust business ecosystem, high concentration of enterprises, and ongoing digital transformation efforts make it a prime location for managed services adoption. London is home to a diverse range of industries, including finance, technology, healthcare, and retail, all of which rely heavily on IT infrastructure and data management services. As these industries continue to embrace cloud technologies, cybersecurity, and AI-driven solutions, demand for managed services has surged. The market is expected to maintain a strong growth trajectory in this region, fueled by an increasing reliance on managed IT and security services, especially as businesses shift toward cloud-first strategies and remote work models.
Manchester
Manchester, another key player in the UK Managed Services market, holds a market share of around 20%. As a major hub for industries such as manufacturing, education, and IT, Manchester has witnessed a significant rise in the adoption of managed services. The city’s thriving tech sector, combined with the growing need for businesses to outsource complex IT functions, has driven demand for managed network, cloud, and security services. The Manchester market benefits from a strong presence of mid-sized enterprises looking for cost-effective and scalable IT solutions. The ongoing digital transformation across businesses in this region is expected to continue supporting market growth, especially as automation and AI become more integrated into managed services offerings.
Birmingham
Birmingham, as the second-largest city in the UK, holds a significant portion of the managed services market, accounting for approximately 18% of the market share. The region is an important center for industries such as automotive, manufacturing, and professional services, which rely on efficient and secure IT infrastructure to support their operations. With a growing emphasis on business continuity, data security, and network optimization, businesses in Birmingham are increasingly turning to managed services providers for tailored IT solutions. The shift towards cloud adoption and the need for robust cybersecurity measures are expected to drive the demand for managed services in the region. As businesses continue to digitize and modernize, Birmingham’s managed services market is anticipated to experience steady growth, benefiting from both large enterprises and small to medium-sized businesses seeking to outsource their IT management.
Scotland
Scotland’s Managed Services market, which holds around 17% of the market share, is steadily growing due to the region's increasing emphasis on technology-driven business transformation. Key industries such as energy, finance, and tourism are leveraging managed IT services to optimize their operations and maintain competitive advantages. The rise in remote work and cloud adoption is particularly strong in Scotland, where businesses are adopting managed services to improve operational efficiency and reduce overheads. With a focus on cybersecurity, compliance, and business continuity, businesses in Scotland are investing heavily in managed security services. The market is further supported by the presence of government initiatives and public sector organizations increasingly embracing digital technologies, providing additional growth opportunities for managed services providers in the region. As demand for advanced IT services continues to rise, Scotland's managed services sector is set to experience significant expansion in the coming years.
Key Player Analysis
- BT
- Deloitte
- BAE Systems
- BCN Group
- OryxAlign
- Babble
- Lima Technology
- Google LLC
- Microsoft Corporation
- Stone Group
- OneAdvanced
- ACUTEC Limited UK
- Kuiper Technology Limited
- Ericsson
- BSL Group
- Others
Competitive Analysis
The UK Managed Services market is highly competitive, with several leading players offering diverse solutions across industries. Major companies like BT, Deloitte, Microsoft, Google, BAE Systems, BCN Group, OryxAlign, Babble, Lima Technology, Stone Group, OneAdvanced, ACUTEC Limited UK, Kuiper Technology, Ericsson, and BSL Group dominate the market. These companies maintain a competitive edge through their vast resources, innovative solutions, and ability to handle large-scale projects for enterprise clients. For instance, a survey by the Department for Science, Innovation and Technology (DSIT) found that large managed service providers (MSPs) account for just 4% of firms but generate 74% of total estimated revenue, highlighting their significant market influence. Smaller players focus on providing specialized services tailored to the needs of mid-sized businesses, differentiating themselves through personalized customer service and niche offerings. These companies often emphasize flexibility, quicker response times, and industry-specific expertise, positioning themselves as more agile alternatives to the larger players. In this competitive landscape, continuous innovation is critical, with companies investing heavily in automation, AI, and advanced security technologies to improve service delivery and meet the evolving demands of the market. Moreover, the shift towards cloud computing, combined with the increasing need for robust cybersecurity measures, has spurred companies to offer integrated solutions that address both operational efficiency and security concerns. This environment fosters a dynamic market where companies must stay ahead of technological trends to remain competitive.
Recent Developments
- In January 2024, Accenture acquired NaviSite to strengthen its managed services offerings, particularly in application and infrastructure management. The acquisition will enhance Accenture’s ability to assist US and Canadian clients in modernizing their digital infrastructure, focusing on AI, cloud, and data-driven solutions for digital transformation.
- In September 2024, TCS launched two AI-powered cybersecurity solutions - Managed Detection and Response (MDR) and Secure Cloud Foundation - in collaboration with Google Cloud. The MDR service was intended to offer continuous, managed threat detection and response, while Secure Cloud Foundation aimed to enhance cloud security posture and governance across hybrid environments. Both solutions leverage Google Cloud’s security tools to provide proactive enterprise protection.
- In June 2024, DXC Technology and Dell partnered to establish Enterprise Intelligence Services (EIS). This service aimed to improve managed services by combining artificial intelligence, data analytics, and cloud technology. EIS’s multi-cloud strategy was expected to help organizations streamline operations, make smarter decisions, and improve customer experiences, proving DXC’s position as the leader in managed multi-cloud solutions.
- In October 2023, technology services provider Logicalis launched an Intelligent Connectivity suite that includes solutions such as SASE, SSE, SD-WAN, and Private 5G powered by Cisco Systems, Inc. This will enable Logicalis customers to access digitally managed services developed using Cisco technology and supported by the Logicalis Digital Fabric Platform.
- In September 2023, communications & technology solution provider Cloud5 Communications launched its new managed services division. The division is designed to support the IT-related requirements & challenges in various markets, such as the hospitality industry, student housing, and senior living, among others. This division will assist consumers in efficiently managing IT operations, technology infrastructures, and security.
- In May 2023, Alfar Capital and Walter Capital Partners completed the acquisition of MSP Corp, a managed IT service provider in Canada. The MSP Corp would merge with Groupe Access, an MSP of IT and cybersecurity solutions. The acquisition would help company to deliver cutting-edge solutions and strengthen its position in Canada.
- In January 2023, Rackspace Technology, a multi-cloud technology solutions provider, launched Rackspace Technology Modern Operations, a managed service for public cloud for customers across Azure, AWS, and GCP. The service will provide benefits including 24x7x365 managed support, cloud expertise, cloud resiliency, and innovation with cloud services which help the company’s customers manage complex cloud environments.
Market Concentration & Characteristics
The UK Managed Services market exhibits moderate to high concentration, with a blend of large multinational companies and specialized regional players competing for market share. The presence of global players offering a wide range of IT solutions, including cloud services, cybersecurity, and business continuity, dominates the market landscape. These companies leverage significant resources, advanced technologies, and established reputations to cater to large enterprises and public sector clients. On the other hand, smaller, niche players focus on providing customized services, often targeting mid-sized businesses with specialized IT needs.
The market is characterized by its dynamic nature, driven by the rapid pace of technological advancements and increasing demand for digital transformation. Cloud adoption, AI integration, and automation are key trends reshaping service offerings. Additionally, businesses are increasingly outsourcing IT functions to reduce operational costs, improve efficiency, and access specialized expertise. Another defining characteristic is the rising importance of cybersecurity, as businesses face growing threats from cyberattacks and data breaches. This has created a robust demand for managed security services. The market also faces challenges, including talent shortages and the need for compliance with stringent data protection regulations. As a result, the UK Managed Services market is evolving rapidly, with service providers constantly innovating to meet the changing needs of clients.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Deployment Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK Managed Services market is expected to continue its strong growth, driven by the increasing adoption of cloud technologies.
- Cybersecurity will remain a top priority, leading to higher demand for managed security services to protect against evolving threats.
- AI and automation integration will play a significant role in enhancing service efficiency and delivering advanced solutions.
- The shift towards hybrid and multi-cloud environments will create more opportunities for managed services providers to offer flexible, scalable solutions.
- Small and medium-sized businesses will increasingly turn to managed services for cost-effective IT solutions and specialized expertise.
- The growing need for regulatory compliance, especially in data privacy, will drive demand for managed services that ensure adherence to legal frameworks.
- Managed network services will see rising demand as businesses require enhanced connectivity, performance, and uptime for their digital operations.
- The adoption of Internet of Things (IoT) solutions will create new opportunities for managed services providers to support connected devices and systems.
- Increased focus on business continuity and disaster recovery will lead organizations to rely more on managed services for risk mitigation.
- The UK market will witness consolidation, with larger players acquiring smaller firms to expand their service portfolios and enhance their competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Managed Services market?
What factors are driving the growth of the UK Managed Services market?
What are the key segments within the UK Managed Services market?
What are some challenges faced by the UK Managed Services market?
Who are the major players in the UK Managed Services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Managed Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Managed Services Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 15,349.99 million → 2032: USD 28,291.12 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Managed Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Managed Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Managed Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Managed Services Market Drivers
- 3.3 UK Managed Services Market Restraints & Challenges
- 3.4 UK Managed Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Managed Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Managed Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Managed Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Managed Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Managed Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Managed Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Managed Services Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Managed Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Managed Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Managed Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Managed Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Managed Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Managed Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Managed Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Managed Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Managed Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
