
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Large Language Model Market Size 2023 | USD 1,358.06 Million |
| U.S. Large Language Model Market, CAGR | 35.2% |
| U.S. Large Language Model Market Size 2032 | USD 20,538.15 Million |
Market Overview
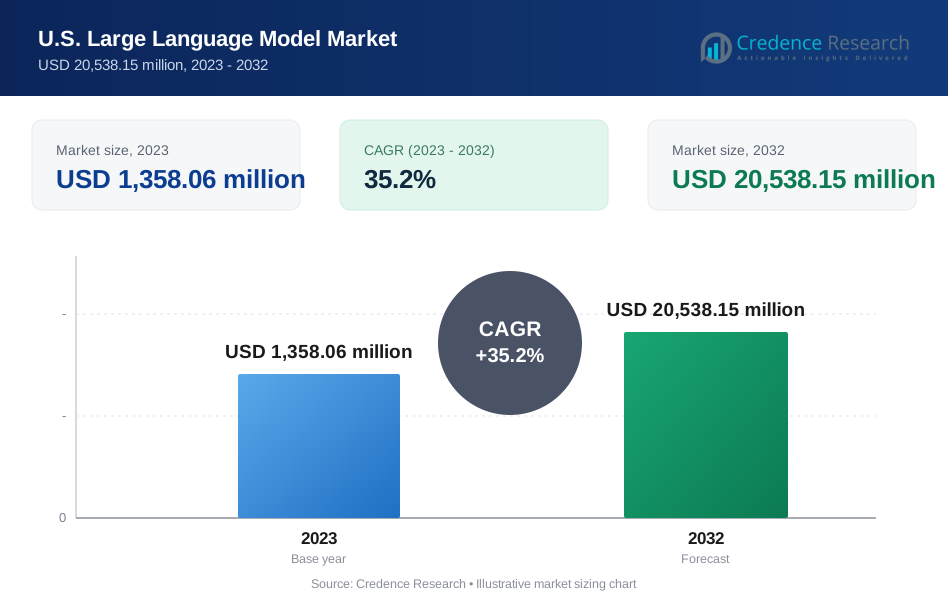
The U.S. Large Language Model Market is projected to grow from USD 1,358.06 million in 2023 to an estimated USD 20,538.15 million by 2032, registering a robust CAGR of 35.2% from 2024 to 2032. This substantial growth is driven by the increasing demand for AI-powered applications across industries, such as healthcare, finance, retail, and customer service.
The market is witnessing rapid advancements in deep learning algorithms, cloud-based AI services, and multimodal AI models, contributing to its accelerated adoption. Key drivers include the growing need for automated content generation, intelligent virtual assistants, and personalized AI-driven customer interactions. Additionally, rising investments from tech giants and startups in AI research and development, along with increasing regulatory frameworks promoting ethical AI usage, are shaping market dynamics.
Geographically, the U.S. dominates the global LLM market, benefiting from strong AI infrastructure, leading AI research institutions, and major technology firms. Key players in the market include OpenAI, Google DeepMind, Microsoft, Meta, Amazon Web Services (AWS), and IBM, among others. These companies are continuously innovating by launching advanced models and expanding their AI service offerings to maintain a competitive edge. The market is expected to remain highly competitive, with ongoing partnerships and acquisitions shaping the landscape.
Market Insights
- The U.S. Large Language Model Market is expected to grow from USD 1,358.06 million in 2023 to USD 20,538.15 million by 2032, with a CAGR of 35.2%.
- Key drivers include the increasing demand for AI-powered automation, virtual assistants, and personalized customer interactions across multiple industries.
- Advancements in NLP, deep learning algorithms, and cloud-based AI services are accelerating the market’s growth and adoption.
- The market faces high computational costs and challenges related to scalability, limiting widespread deployment for smaller enterprises.
- Ethical concerns, such as bias in AI models and data privacy regulations, are key factors shaping market dynamics and driving regulatory attention.
- West Coast leads the market with a 40% share, driven by major players like Google, Microsoft, and Amazon, while the Northeast focuses on financial services and healthcare applications.
- The market is highly competitive, with key players like OpenAI, Meta, and IBM continually advancing LLM technologies to stay ahead in the evolving landscape.
Market Drivers
Growing Demand for AI-Powered Automation and Efficiency
Organizations across healthcare, finance, e-commerce, and customer service are integrating LLMs into their workflows to boost productivity, reduce manual labor, and optimize resource utilization. For instance, companies now deploy LLM-powered chatbots and virtual assistants to enhance customer engagement and provide instant support. These AI-driven assistants manage large volumes of inquiries with human-like responses, which significantly reduces operational costs. Marketing teams use LLMs to create high-quality content and personalized campaigns. Businesses also use LLMs to analyze vast amounts of data and extract valuable insights, enhancing operational efficiencies. Tech companies leverage LLMs to assist software developers in writing and debugging code. As digital transformation initiatives increase, the demand for AI-powered automation continues to drive market growth, establishing LLMs as essential for modern enterprise solutions.
Advancements in Natural Language Processing (NLP) and Deep Learning
Technological innovations in deep learning, neural networks, and NLP are significantly advancing the U.S. LLM market. Research institutions and tech companies are refining transformer architectures, reinforcement learning, and multimodal AI models. For instance, modern LLMs, such as GPT-4 and PaLM 2, demonstrate enhanced contextual understanding, reasoning, and multilingual proficiency, enabling more natural interactions and refined responses. Ongoing research focuses on improving model efficiency, reducing computational costs, and making large-scale AI models more accessible through optimized training techniques and better infrastructure. The evolution of LLMs into multimodal AI models enhances their usability across diverse applications, including AI-driven content moderation and healthcare diagnostics. Researchers are also focusing on making LLMs more interpretable and reducing biases to ensure ethical AI usage.
Expanding Enterprise Adoption and Investment in AI
Corporate investments in AI-driven applications and cloud-based AI solutions are accelerating the adoption of LLMs across industries. Companies recognize the competitive advantages of AI-powered automation, real-time decision-making, and personalized customer experiences, leading to increased AI-related expenditures. For instance, organizations in banking, retail, and legal sectors integrate LLMs for fraud detection, sentiment analysis, and automated document processing. Cloud providers offer AI-as-a-Service (AIaaS) solutions, making LLM-powered tools more accessible to businesses. Leading U.S. tech firms invest heavily in LLM research to ensure continuous innovation and development. Strategic partnerships between AI startups, enterprises, and research institutions foster innovation and expand the LLM ecosystem. The demand for customizable and scalable LLMs will remain critical as enterprises continue to integrate AI-driven solutions.
Regulatory Support and Ethical AI Initiatives
Regulatory frameworks and ethical AI initiatives play a significant role in shaping the U.S. LLM market. As AI adoption increases, policymakers and industry leaders emphasize responsible AI development, transparency, and compliance with data protection regulations to ensure safe and ethical usage. For instance, the U.S. government and regulatory bodies are formulating AI governance policies, ensuring responsible AI deployment while addressing concerns related to bias, misinformation, and data privacy. Compliance with regulations like GDPR and CCPA influences LLM development, prompting companies to focus on privacy-first AI solutions. Organizations are investing in ethical AI research to ensure transparency in AI decision-making and minimize biases in training datasets. As regulatory measures enhance public trust in AI technologies, enterprises and consumers are more likely to adopt AI-powered solutions.
Market Trends
Integration of Large Language Models with Enterprise Workflows
One of the most significant trends in the U.S. LLM market is the integration of AI-powered language models into enterprise operations. Businesses across various industries leverage LLMs to enhance automation, improve customer interactions, and optimize decision-making processes. For instance, companies deploy LLM-powered chatbots and voice assistants to handle customer inquiries, personalize responses, and improve resolution times. Delta Airlines utilizes LLMs in their Ask Delta chatbot, which assists customers with flight check-in, luggage tracking, and finding flights, leading to a reported 20% decrease in call center volume. Organizations utilize LLMs to generate blog articles, social media content, product descriptions, and ad copies, streamlining content production and ensuring consistency across platforms, thus improving SEO strategies and audience engagement. LLMs assist software developers in writing, debugging, and optimizing code, accelerating development cycles and improving software efficiency. LLMs can predict and suggest the next lines of code as developers type, reducing the need for manual input and speeding up the coding process. As enterprises prioritize digital transformation, the adoption of LLM-driven solutions will continue to grow, improving business productivity and decision-making.
Advancements in Multimodal AI and Model Efficiency
The U.S. LLM market is witnessing a shift toward multimodal AI models that process and generate text, images, audio, and video simultaneously. These advancements enhance AI capabilities and enable a broader range of applications beyond traditional text-based interactions. Leading AI developers, including OpenAI, Google DeepMind, and Meta, are introducing models that combine text processing with visual, audio, and video comprehension. For instance, Bank of America's virtual assistant, Erica, supports over 25 million mobile banking customers by providing voice, text, and image recognition capabilities, allowing users to conduct banking tasks and receive financial advice. AI research focuses on making LLMs more efficient by reducing computational requirements and improving inference speed. Companies are adopting low-rank adaptation (LoRA) and quantization techniques to develop optimized models that run on fewer resources while maintaining high accuracy. Businesses and developers are increasingly using fine-tuned LLMs for domain-specific applications, such as legal document analysis, medical diagnostics, and financial modeling. As concerns over AI energy consumption rise, companies focus on developing environmentally sustainable AI models. These advancements are making LLMs more powerful, adaptable, and efficient, increasing their usability across multiple industries.
Expansion of AI-as-a-Service (AIaaS) and Cloud-Based LLM Solutions
The increasing availability of cloud-based AI services and AI-as-a-Service (AIaaS) platforms is a significant trend shaping the U.S. LLM market. Businesses are leveraging LLMs through cloud providers to scale AI-powered applications without requiring extensive on-premise infrastructure. Tech giants such as Microsoft Azure, Google Cloud, and Amazon Web Services (AWS) provide LLM-powered APIs and enterprise AI solutions, allowing companies to access scalable and cost-effective AI capabilities. Cognizant and Google Cloud are collaborating to leverage generative AI, including LLMs, in the cloud to tackle healthcare challenges, aiming to streamline administrative processes like appeals and patient engagement, using Google Cloud’s Vertex AI platform. The availability of LLM-based services on a subscription model enables SMEs to leverage AI-driven tools without investing in costly infrastructure. Microsoft has integrated ChatGPT into its Azure OpenAI Service, offering an enterprise-focused solution that enables businesses to apply advanced AI models to their operations. As AIaaS and cloud-based solutions continue to expand, more businesses will adopt LLM-powered applications, driving faster AI adoption across multiple sectors.
Regulatory Frameworks and Ethical AI Implementation
With the rapid expansion of LLMs, regulatory frameworks and ethical AI practices are becoming critical factors in shaping the U.S. market. Governments, businesses, and AI research organizations focus on establishing policies that promote responsible AI deployment while ensuring compliance with privacy and security standards. U.S. policymakers are working on AI governance frameworks that regulate data privacy, misinformation, and ethical AI deployment. The Biden administration released an Executive Order on Safe, Secure, and Trustworthy Artificial Intelligence, addressing issues such as standards for critical infrastructure, AI-enhanced cybersecurity, and federally funded biological synthesis projects. Organizations are investing in bias detection techniques and diverse training datasets to create fair and unbiased AI models. With increasing concerns over user data security, companies focus on developing privacy-preserving AI models that align with GDPR, CCPA, and emerging AI regulations. Businesses and regulatory bodies emphasize AI explainability, ensuring that AI-generated decisions are interpretable, auditable, and accountable. As AI regulations continue to evolve, companies must align their LLM strategies with ethical AI guidelines to maintain market credibility and consumer trust.
Market Challenges
High Computational Costs and Scalability Limitations
The development and deployment of large language models face significant hurdles due to high computational costs and scalability limitations. For instance, training a large language model like GPT-3 can cost around $1.4 million for a single training session, demanding thousands of GPUs and significant electricity consumption. This expense limits the accessibility of advanced AI development to well-funded organizations, creating barriers for startups and smaller enterprises. Resource-intensive deployment further exacerbates these challenges, as running LLMs in real-world applications requires substantial processing power. This restricts their usability on low-power devices and necessitates investments in optimized AI models and cloud-based solutions. The considerable energy consumption associated with training and deploying LLMs also raises concerns about their environmental impact, pushing AI developers to focus on creating more efficient model architectures. Addressing these cost, scalability, and efficiency challenges is crucial for the sustainable growth and integration of LLMs into various business operations.
Ethical Concerns and Regulatory Compliance
Ethical concerns and regulatory compliance present substantial obstacles to the widespread adoption of large language models. For instance, Amazon's AI recruiting system exhibited bias against women because it was trained on historical data that contained biases against women. This highlights the critical need for robust bias detection mechanisms and diverse training datasets to minimize discriminatory outputs. Furthermore, the processing of vast amounts of user data by LLMs raises significant privacy concerns under regulations such as GDPR and CCPA. Companies must implement secure data-handling practices, encryption techniques, and privacy-preserving AI models to protect user information and ensure compliance. The absence of standardized AI regulations adds further complexity for businesses, requiring them to navigate evolving AI laws and ethical requirements. Explainability and transparency are also essential to enhance trust and regulatory acceptance, ensuring responsible AI deployment and long-term market stability.
Market Opportunities
Enterprise-Driven AI Transformation Across Industries
The integration of Large Language Models (LLMs) into enterprise workflows presents a substantial opportunity as businesses across sectors like healthcare, finance, retail, education, and legal are leveraging AI-powered automation, data-driven insights, and enhanced customer engagement solutions. This trend is fueled by the need for greater efficiency and improved customer experiences. For instance, enterprises are using LLM-driven automation to streamline document processing and reduce operational workflows, enhancing efficiency. Businesses are also employing LLMs to power conversational AI and virtual assistants, which can improve customer engagement and retention. Companies are further investing in cloud-based AI solutions and AI-as-a-Service (AIaaS) platforms, making LLMs accessible for businesses of all sizes and expanding adoption beyond tech-driven enterprises. The demand for AI-driven transformation creates long-term revenue opportunities for both LLM providers and enterprise AI solution developers, solidifying AI's role in reshaping business operations and customer interactions.
Advancements in Customized and Domain-Specific LLMs
The demand for tailored AI solutions is on the rise, as various industries seek specialized LLMs for domain-specific applications. Companies are investing in fine-tuned AI models optimized for areas such as healthcare diagnostics, financial analysis, legal documentation, and cybersecurity. This shift towards customization is driven by the need for greater accuracy and relevance in specific fields. For instance, organizations require LLMs trained on domain-specific datasets to improve accuracy and relevance in financial risk assessment, medical research, and legal compliance. Businesses are also developing proprietary LLMs that cater to sector-specific challenges, enabling more secure, efficient, and precise AI applications. The expansion of AI research, startup investments, and AI-focused venture capital funding is further fostering the development of innovative, niche AI models, thereby driving market growth. As the demand for custom AI solutions increases, businesses that invest in LLM specialization and tailored AI applications are poised to gain a competitive advantage in the evolving market landscape.
Market Segmentation Analysis
By Offerings
The AI market is primarily divided into two key offerings: software and services. Software solutions dominate the market, capturing the largest share due to the extensive integration of AI-driven models into various enterprise applications. These software solutions enable businesses to automate processes, enhance productivity, and leverage advanced analytics. Meanwhile, services-which include offerings such as model fine-tuning, consulting, and API integrations-are witnessing rapid growth. As companies increasingly seek tailored AI implementations, there is a growing demand for specialized services that optimize and customize AI models to meet specific business needs. This dynamic trend highlights the expanding role of AI across industries and underscores the importance of both software and services in driving adoption.
By Software Type
The AI software market is segmented based on the type of large language models (LLMs) being utilized. General Purpose LLMs are the most widely used, supporting a broad range of applications such as customer service, content generation, and conversational AI. Domain-Specific LLMs cater to industries like healthcare, legal, and finance, offering specialized solutions that aid in regulatory compliance and data processing. Additionally, Multilingual LLMs are gaining popularity for their ability to facilitate cross-border communication, support translation services, and enhance global customer engagement. Lastly, Task-Specific LLMs are designed to address specific tasks such as summarization, sentiment analysis, and automated report generation, contributing to improved workflow efficiency and productivity.
Segments
Based on Offerings
- Software
- Services
Based on Software Type
- General-Purpose LLMs
- Domain-Specific LLMs
- Multilingual LLMs
- Task-Specific LLMs
Based on Deployment Type
- On-Premise
- Cloud-Based
Based on Modality Type
- Text-Based LLMs
- Code-Based LLMs
- Image-Based LLMs
- Video-Based LLMs
Based on Application
- Information Retrieval
- Language Translation & Localization
- Content Generation & Curation
- Code Generation
- Others
Based on End-User Industry
- IT & ITES
- Healthcare
- BFSI (Banking, Financial Services, and Insurance)
- Retail & E-Commerce
- Other Industries
Based on Region
- Northeast U.S
- West Coast
- Midwest & South
Regional Analysis
West Coast (40%)
The West Coast of the United States, particularly areas like Silicon Valley, Seattle, and Los Angeles, commands the largest share of the U.S. LLM market, estimated at approximately 40%. This dominance can be attributed to the high concentration of leading technology companies and AI research institutions in these regions. Prominent firms such as Google, Microsoft, OpenAI, and Amazon are at the cutting edge of LLM development, with significant investments in creating and deploying advanced AI models. The West Coast's strong emphasis on innovation, combined with its established ecosystem of tech giants, startups, and academic research, provides a fertile ground for the continuous evolution of large language models (LLMs). The region's robust funding infrastructure and access to top-tier talent also contribute to its leadership in the field. Furthermore, Silicon Valley's position as a global hub for technology innovation ensures that companies and institutions in the West Coast continue to push the boundaries of AI development. The close integration between private sector advancements and academic research accelerates the growth of the LLM market, enabling faster implementation of cutting-edge solutions across various industries. With continuous breakthroughs, the West Coast remains a key player in shaping the future of AI and LLM technologies.
Northeast U.S. (25%)
The Northeast U.S., which encompasses major cities like New York City, Boston, and Philadelphia, holds approximately 25% of the U.S. LLM market share. This region is a critical hub for financial services, healthcare, and research-driven industries, all of which are significantly influenced by the advancements in artificial intelligence. Notably, the Northeast is home to some of the nation’s top AI research institutions, including MIT and Harvard University. These prestigious institutions play a pivotal role in driving AI innovation, fostering collaboration between academia and industry. This unique synergy between research and business has made the region an important contributor to the overall growth of the LLM sector. The strength of the Northeast's economy further amplifies its importance in the LLM market. The area's dominance in industries like finance and healthcare has led to the accelerated adoption of AI technologies, particularly large language models, to enhance decision-making, automate processes, and improve customer experiences. As these industries continue to leverage LLMs for data analysis and operational efficiencies, the Northeast's market share is expected to grow, solidifying its position as a key player in the ongoing evolution of AI.
Key players
- Google LLC
- Anthropic
- Meta Platforms Inc.
- OpenAI
- Microsoft Corporation
- Amazon Web Services
- NVIDIA
- IBM Corporation
- Oracle Corporation
- HPE
- Hugging Face
- Turing
- Together AI
- Adept
- FedML
Competitive Analysis
The U.S. Large Language Model Market is highly competitive, with established players such as Google LLC, Microsoft Corporation, and Amazon Web Services leading the charge. These industry giants dominate through their extensive AI research, infrastructure, and global cloud services, enabling widespread adoption of LLM technologies across sectors. OpenAI has established itself as a major player with its cutting-edge GPT series, driving innovation in natural language processing. Companies like Meta Platforms Inc. and NVIDIA offer advanced AI frameworks, fueling the development of multimodal models. Emerging firms like Anthropic, Hugging Face, and FedML focus on ethical AI development, model fine-tuning, and creating open-source solutions, distinguishing themselves by offering customizable and accessible tools. Despite varying strategies, all players are increasingly investing in research, partnerships, and AI-as-a-Service solutions to maintain competitive advantages in the rapidly evolving LLM market.
Recent Developments
- In January 2025, Anthropic is receiving $2 billion in new funding, giving the company an overall evaluation of $60 billion.
- In February 2025, Meta shares have gained 20% since the start of 2025, making the stock the top performer over that stretch among the Magnificent Seven group, driven by AI optimism.
- In February 2025, AWS is expanding its selection of models to include new ones alongside established industry favorites. DeepSeek-R1 Distill Llama and Qwen models are now available in Amazon Bedrock Marketplace and Amazon SageMaker JumpStart.
- In January 2025, Nvidia experienced a significant market cap drop due to concerns about increased competition in the AI arena. Nvidia's GPUs hold a dominant position in the U.S. market for AI data center chips, with major tech firms investing billions in these processors.
Market Concentration and Characteristics
The U.S. Large Language Model Market is characterized by a high concentration of key players, including industry giants such as Google LLC, Microsoft Corporation, OpenAI, Amazon Web Services, and Meta Platforms Inc., who dominate the market with their extensive research, infrastructure, and AI-powered offerings. These companies lead the way in the development of state-of-the-art models, cloud services, and AI-as-a-Service platforms, catering to a broad range of industries. The market also sees growing participation from emerging players like Anthropic, Hugging Face, and FedML, which contribute through open-source solutions, ethical AI development, and customizable LLM applications. Despite the presence of major players, the market remains dynamic, with a high degree of innovation, partnerships, and acquisitions, creating a competitive environment that fosters rapid advancements and diverse application areas for LLMs.
Report Coverage
The research report offers an in-depth analysis based on Offerings, Software Type, Deployment Type, Modality Type, Application, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. Large Language Model (LLM) market will continue to expand as industries like healthcare, finance, and retail increasingly integrate AI-driven solutions for efficiency and personalization. LLMs will be instrumental in driving digital transformation across sectors.
- The demand for cloud-based LLM solutions will surge as AI-as-a-Service platforms become more accessible, allowing businesses of all sizes to implement advanced AI tools without heavy infrastructure investments. This will drive widespread adoption across small and medium enterprises (SMEs).
- The development of multimodal AI models, which can process text, images, video, and audio, will expand the applicability of LLMs, enhancing their capabilities in areas such as creative content generation, real-time analytics, and cross-media applications.
- There will be a growing emphasis on ethical AI development, with companies focusing on bias reduction, transparency, and explainability in LLMs to address regulatory concerns and ensure responsible usage in sensitive industries like healthcare and finance.
- Customization of LLMs to meet industry-specific needs will become more prevalent. Businesses will deploy domain-specific models for legal, medical, and financial applications, enhancing accuracy and performance in niche areas.
- As AI regulations tighten, companies will increasingly focus on ensuring LLM compliance with data privacy laws such as GDPR and CCPA, creating an environment that fosters responsible AI deployment while minimizing risks related to data security.
- The integration of LLMs with edge computing will enable more real-time processing in industries like autonomous driving and smart manufacturing, where quick, on-site AI decision-making is critical for operational efficiency.
- LLMs will see increasing use in medical diagnostics, personalized healthcare, and clinical decision support systems. Their ability to process vast amounts of medical data will enhance patient care and health outcomes.
- There will be a significant rise in the adoption of open-source LLM platforms like Hugging Face that foster collaboration and innovation within the AI community, allowing organizations to access high-performance models and contribute to the development of AI technology.
- The market will witness sustained investments in AI research and development, as leading firms and startups continue to push the boundaries of LLM capabilities. This will drive innovation in AI hardware, software architecture, and deep learning models to improve efficiency and scalability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enterprise AI-Powered Automation
Organizations in sectors such as healthcare, finance, and retail are rapidly integrating LLMs to automate workflows, reduce manual labor, and enhance productivity, fueling market growth as businesses seek efficiency and cost savings.
Advancements in NLP and Deep Learning
Continuous improvements in transformer architectures, multimodal AI, and deep learning algorithms are making LLMs more powerful, efficient, and accessible, driving broader adoption across industries and enabling new applications.
Expansion of Cloud-Based AI Services
The proliferation of AI-as-a-Service and cloud-based LLM platforms allows businesses of all sizes to access advanced language models without heavy infrastructure investments, accelerating adoption especially among SMEs.
Regulatory Support and Ethical AI Initiatives
Emerging regulatory frameworks and a focus on ethical AI development are increasing trust and compliance, encouraging more enterprises to deploy LLMs in sensitive and regulated industries such as healthcare and finance.
Customization and Domain-Specific LLMs
Growing demand for tailored AI solutions is driving investment in domain-specific and fine-tuned LLMs, enabling higher accuracy and relevance for specialized applications in fields like legal, medical, and financial services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. Large Language Model Market in 2023 and 2032, and what is the expected CAGR?
What are the main drivers of the U.S. Large Language Model Market?
How is the U.S. Large Language Model Market expected to evolve over the next decade?
Which sectors are driving the adoption of large language models in the U.S.?
Who are the key players in the U.S. Large Language Model Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offerings
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Software Type
- 1.3.1 General-Purpose LLMs
- 1.3.2 Domain-Specific LLMs
- 1.3.3 Multilingual LLMs
- 1.3.4 Task-Specific LLMs
- 1.4 By Deployment Type
- 1.4.1 On-Premise
- 1.4.2 Cloud-Based
- 1.5 By End-User Industry
- 1.5.1 IT & ITES
- 1.5.2 Healthcare
- 1.5.3 BFSI (Banking, Financial Services, and Insurance)
- 1.5.4 Retail & E-Commerce
- 1.5.5 Other Industries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,358.06 million → 2032: USD 20,538.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Large Language Model Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Large Language Model Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Large Language Model Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Large Language Model Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Large Language Model Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Large Language Model Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Large Language Model Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Large Language Model Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,358.06 million → 2032: USD 20,538.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Large Language Model Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offerings - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Software Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 General-Purpose LLMs
- 12.4.7.2 Domain-Specific LLMs
- 12.4.7.3 Multilingual LLMs
- 12.4.7.4 Task-Specific LLMs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premise
- 12.5.7.2 Cloud-Based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 IT & ITES
- 12.6.7.2 Healthcare
- 12.6.7.3 BFSI (Banking, Financial Services, and Insurance)
- 12.6.7.4 Retail & E-Commerce
- 12.6.7.5 Other Industries
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Large Language Model End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Large Language Model Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Large Language Model Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Large Language Model Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 OpenAI
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Google LLC
- 18.4 Microsoft Corporation
- 18.5 Amazon Web Services
- 18.6 Meta Platforms Inc.
- 18.7 IBM Corporation
- 18.8 NVIDIA
- 18.9 Anthropic
- 18.10 Hugging Face
- 18.11 Oracle Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

