
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| United States luxury Fine Jewelry Market Size 2024 | USD 17,356.1 million |
| United States luxury Fine Jewelry Market, CAGR | 3.7% |
| United States luxury Fine Jewelry Market Size 2032 | USD 23,210.37 million |
Market Overview
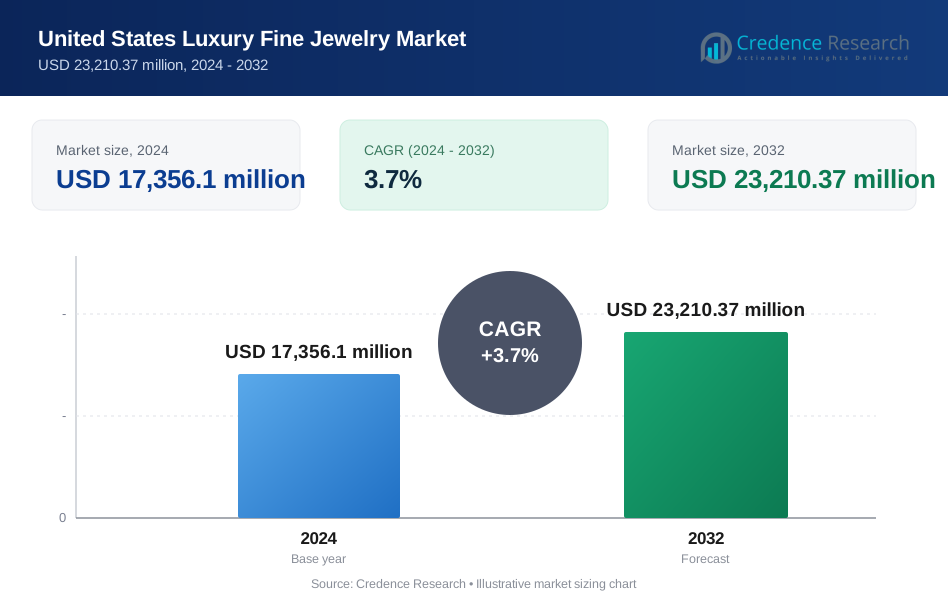
The United States luxury fine jewelry market is projected to grow from USD 17,356.1 million in 2024 to USD 23,210.37 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.7%.
The United States luxury fine jewelry market is driven by several key factors, including increasing disposable income, rising demand for high-end, personalized, and unique jewelry, and the growing influence of social media and celebrity endorsements. As consumers increasingly seek exclusive and premium products, fine jewelry brands are leveraging advanced technology and craftsmanship to offer bespoke designs, fueling market growth. Furthermore, the shift towards sustainable and ethically sourced materials is reshaping the market, with consumers showing greater preference for eco-friendly and conflict-free jewelry. The expansion of online platforms and e-commerce is also contributing to market growth, providing consumers with convenient access to luxury fine jewelry from the comfort of their homes. These trends, coupled with an increasing interest in investing in valuable assets such as gold and diamonds, are expected to continue driving the market’s upward trajectory. The market is also witnessing growth in demand for jewelry as a form of self-expression and a status symbol.
The United States luxury fine jewelry market is geographically diverse, with key demand concentrated in regions like the Northeast and West. The Northeast, particularly New York, is a major hub for luxury jewelry, driven by its affluent consumer base and fashion influence. The West, including cities like Los Angeles and San Francisco, follows closely, with demand fueled by the entertainment industry and celebrity culture. Key players in the market include iconic brands such as Tiffany & Co., Cartier, Harry Winston, and Bulgari, which dominate the high-end segment with their legacy, craftsmanship, and exclusivity. Additionally, emerging brands like Pandora, David Yurman, and Blue Nile are capturing the attention of consumers with personalized options and innovative e-commerce strategies. These players drive growth through a combination of traditional retail presence and expanding digital channels.
Market Drivers
Increasing Disposable Income
One of the primary drivers of growth in the United States luxury fine jewelry market is the steady rise in disposable income among high-net-worth individuals and affluent consumers. For instance, a survey by the U.S. Bureau of Economic Analysis highlights that the disposable personal income in the U.S. has been on a consistent upward trend, enabling more consumers to indulge in luxury goods, including fine jewelry. This increased purchasing power enables consumers to seek out premium products, thus fueling the demand for high-quality, expensive jewelry pieces that signify prestige and status.
Rising Demand for Personalized Jewelry
The growing trend towards personalized and custom-made jewelry is another key factor driving the market. For instance, a report by the Jewelry Consumer Opinion Council indicates that a significant percentage of consumers prefer personalized jewelry that reflects their personal tastes and style. As a result, fine jewelry brands are focusing on offering customizable options, including engravings, personalized gemstones, and tailored designs, allowing customers to create one-of-a-kind pieces. This customization trend is becoming an essential offering for luxury jewelry brands as they cater to the demand for individuality and exclusivity.
Shift Towards Ethical and Sustainable Jewelry
Sustainability and ethical sourcing are becoming central to the purchasing decisions of luxury fine jewelry consumers. For instance, a survey by the World Gold Council found that a growing number of consumers are prioritizing eco-friendly practices and conflict-free, responsibly sourced materials. This shift towards sustainability is influencing market growth, with many luxury jewelry brands adapting to these trends by incorporating recycled materials, fair trade practices, and transparent supply chains into their business models, appealing to conscientious consumers.
Growth of Online and E-Commerce Platforms
The expansion of e-commerce and online retail platforms is playing a pivotal role in shaping the U.S. luxury fine jewelry market. For instance, data from the U.S. Census Bureau shows a significant increase in online retail sales, which has prompted luxury jewelry brands to invest in user-friendly websites and digital marketing strategies to reach a broader audience. The convenience of online shopping, coupled with virtual try-ons, secure payment systems, and home delivery, has significantly increased the accessibility of luxury fine jewelry, further driving its market growth.
Market Trends
Increasing Popularity of Sustainable Jewelry
A significant trend in the United States luxury fine jewelry market is the growing demand for sustainable and ethically sourced products. For instance, a report by the U.S. Environmental Protection Agency highlights that consumers are increasingly prioritizing eco-friendly practices and conflict-free materials. This includes using recycled metals, conflict-free diamonds, and lab-grown stones. As sustainability becomes a key factor in purchasing decisions, brands are emphasizing transparency in sourcing and manufacturing, which not only aligns with consumer values but also strengthens brand loyalty.
Influence of Technology and Innovation
The integration of technology into luxury fine jewelry is reshaping the market. For instance, a study by the National Institute of Standards and Technology notes that innovations such as 3D printing, augmented reality (AR) for virtual try-ons, and advanced gemstone-cutting techniques are offering new ways to enhance the customer experience. AR tools enable consumers to try on jewelry remotely, providing convenience and encouraging online shopping. Additionally, brands are incorporating digital platforms to offer personalized experiences, such as custom design features, further boosting engagement with tech-savvy consumers.
Rise of Investment-Grade Jewelry
Investment-grade jewelry is becoming an increasingly popular segment within the U.S. luxury fine jewelry market. For instance, a report by the U.S. Geological Survey indicates that consumers are viewing high-end jewelry not just as a symbol of wealth or status, but also as a tangible asset. With the growing interest in precious metals and gemstones as stores of value, pieces like rare diamonds, gold, and platinum are in demand. This trend reflects a broader shift toward luxury items as financial assets, driven by economic uncertainty and a desire for stable, appreciating investments.
Focus on Digital and Social Media Marketing
Digital and social media platforms are playing an influential role in shaping current trends in the U.S. luxury fine jewelry market. For instance, a study by the Pew Research Center highlights that brands are leveraging platforms like Instagram, TikTok, and YouTube to showcase their products and connect with younger, tech-driven consumers. Influencers, celebrities, and high-profile endorsements are helping to shape purchasing decisions, making social media a critical tool for driving brand visibility and consumer engagement. This trend is increasing the importance of a strong online presence for luxury jewelry brands.
Market Challenges Analysis
Volatility in Precious Metal Prices
One of the primary challenges faced by the United States luxury fine jewelry market is the volatility in the prices of precious metals such as gold, platinum, and silver. These metals form the core of most high-end jewelry pieces, and fluctuations in their prices can significantly impact the cost of production and profit margins. Price instability, driven by factors such as global economic shifts, geopolitical tensions, inflation rates, and changes in supply and demand dynamics, poses challenges for manufacturers and retailers alike. The rising costs of materials often lead to higher retail prices, which may, in turn, dampen consumer demand, especially during periods of economic uncertainty or financial downturns. This volatility also affects inventory planning, as brands struggle to balance maintaining sufficient stock while managing cost variations. As a result, businesses are increasingly exploring strategies such as material diversification and dynamic pricing models to mitigate risks associated with price fluctuations.
Counterfeit and Fraudulent Products
The increasing prevalence of counterfeit luxury fine jewelry poses a significant challenge to the market, impacting both consumers and brands. With the growth of online platforms and the ease of purchasing products digitally, counterfeiters are exploiting these channels to distribute fake goods with increasing sophistication. Consumers may be unaware that they are purchasing counterfeit jewelry, leading to dissatisfaction and potentially tarnishing the reputation of legitimate brands. This growing issue not only erodes market trust but also results in significant revenue losses for authentic jewelry manufacturers. To combat this challenge, brands are investing in advanced authentication technologies such as blockchain tracking, QR-coded certificates, and holographic labeling, along with stronger measures for verifying product authenticity. However, the ongoing battle against fraud remains a persistent concern, requiring constant vigilance, innovation, and cooperation with regulatory bodies to ensure market integrity and safeguard consumer confidence.
Market Segmentation Analysis:
By Type
The United States luxury fine jewelry market is primarily segmented by type, with key categories including rings, necklaces, earrings, bracelets, and watches. Among these, rings hold the largest market share, driven by their popularity in engagement, wedding, and fashion jewelry. Engagement rings, in particular, continue to be a significant driver, with consumers opting for high-quality diamonds and unique designs. Necklaces and earrings also maintain strong demand, particularly those crafted from precious metals and featuring gemstones such as diamonds, sapphires, and emeralds. Watches, as a luxury segment, are increasingly sought after for both functionality and as a status symbol, with high-end brands offering bespoke and innovative designs. This segmentation highlights the diverse preferences of affluent consumers who are willing to invest in different types of luxury jewelry based on personal style, occasion, and investment potential.
By Application
The luxury fine jewelry market in the United States is also segmented by application, primarily categorized into personal use and gifting. Personal use remains the dominant segment, driven by consumers seeking to invest in high-quality, long-lasting jewelry pieces as a form of self-expression and status. Gifting, particularly for special occasions such as birthdays, anniversaries, and holidays, also represents a significant portion of the market. Jewelry pieces given as gifts often carry emotional value, with engagement rings and other milestone-related items leading the category. Additionally, investment-grade jewelry is gaining traction as an alternative asset class, with consumers purchasing luxury jewelry pieces as financial investments. As the demand for personalized and custom-designed pieces grows, the application segment continues to evolve, with increasing interest in both self-purchase and gifting scenarios.
Segments:
Based on Type:
- VCI bags (flat, gusseted, and zipper)
- VCI films (stretch, shrink, and sheet)
- VCI paper
- Foam
- Emitters
- Desiccants
Based on Application:
- Automotive
- Electrical and Electronics
- Aerospace and Defense
- Metal Works
- Construction
- Primary Metal
- Heavy Equipment
Regional Analysis
Northeast Region
The Northeast region holds a significant share of the United States luxury fine jewelry market, contributing 35% of the total market value. This dominance is driven by high-income states such as New York, Massachusetts, and Connecticut. Metropolitan areas like New York City serve as global hubs for luxury shopping, with a dense concentration of wealthy individuals and a strong presence of high-end retailers, making it a key market for luxury jewelry. Events such as galas, red carpet occasions, and fashion weeks also drive demand, as consumers view fine jewelry as a symbol of wealth, status, and personal style. Moreover, the region's economic stability, high disposable income, and long-established luxury retail infrastructure have solidified its position as the leader in the market. With its diverse consumer base and deep cultural connection to fashion and luxury, the Northeast is expected to continue driving a substantial portion of the U.S. luxury fine jewelry market for the foreseeable future. As luxury consumer preferences evolve, this region remains at the forefront of trends, innovation, and new product introductions.
West Region
The West region, particularly California, holds a growing share of the U.S. luxury fine jewelry market, contributing around 30% of the total market value. Major cities like Los Angeles, San Francisco, and San Diego are pivotal, fueled by their economic strength from the entertainment, technology, and fashion industries. These cities, known for their high concentration of affluent individuals, business moguls, and global celebrities, are significant drivers of luxury fine jewelry demand. The influence of celebrities, social media influencers, and high-profile events such as film premieres, award ceremonies, and exclusive charity galas contribute to the growing appeal of luxury jewelry, particularly statement pieces, rare gemstones, and high-end designer collections. Furthermore, the increasing trend of luxury self-purchasing, especially among women in urban areas like Los Angeles, has boosted the demand for fine jewelry as a form of personal expression. With a diverse and expanding affluent consumer base, the West continues to show strong market potential. As a result, this region is expected to maintain solid growth in the coming years, further increasing its share in the U.S. luxury fine jewelry market and shaping the industry's future with its emphasis on individuality, customization, and premium design.
Key Player Analysis
- Tiffany & Co.
- Cartier
- Harry Winston
- Bvlgari
- Van Cleef & Arpels
- David Yurman
- Mikimoto
- Roberto Coin
- John Hardy
- Kwiat
- Brilliant Earth
Competitive Analysis
The United States luxury fine jewelry market is highly competitive, with a range of well-established players driving innovation and growth. Leading brands like Tiffany & Co., Cartier, Harry Winston, and Bulgari dominate the market, offering a wide range of premium products, including engagement rings, necklaces, and bracelets. These brands are renowned for their craftsmanship, exclusivity, and long-standing heritage. Competition is further fueled by emerging players who focus on customization, sustainable sourcing, and unique designs to cater to the evolving preferences of consumers. For instance, a survey by the Jewelers of America highlights that companies like Pandora, David Yurman, and Blue Nile are gaining traction by offering personalized jewelry, while leveraging e-commerce platforms to expand their reach. With an increasing trend towards sustainable practices, brands are incorporating ethically sourced materials, appealing to socially conscious consumers. Overall, the market remains dynamic, with both legacy and emerging brands striving for market share by blending tradition with innovation.
Recent Developments
- In July 2024, Ben Bridge Jeweler, announced successful collaborations with Indian manufacturers. The partnerships aimed to create unique jewelry concepts for USA customers. This initiative highlighted India's rich jewelry tradition and expertise, enhancing the brand's offerings and strengthening connections in the luxury market.
- In August 2024, emoji® and Gnoce launched an exclusive luxury jewelry collection. The collection features 26 unique charms, bracelets, earrings, and necklaces inspired by popular emojis. Crafted from premium 925 sterling silver and 18k gold plating, these pieces blend playful design with sophistication, enhancing self-expression through jewelry.
- In May 2024, Watches of Switzerland acquired Roberto Coin Inc. for USD 130 million. The deal granted exclusive distribution rights for the North American market, including the USA, Canada, and the Caribbean.
- In January 2024, Lark & Berry opened its first USA showroom in Houston, Texas, celebrating its connection to the city and Rice University, alma mater of founder Laura Chavez. Known for its cultured diamonds, the brand aims to redefine luxury jewelry by offering ethically sourced, high-quality pieces at accessible prices.
Market Concentration & Characteristics
The United States luxury fine jewelry market exhibits a moderate to high level of market concentration, with a few established brands dominating the industry. Leading players such as Tiffany & Co., Cartier, and Harry Winston hold substantial market shares, benefiting from their strong brand equity, exclusive designs, and long-standing reputations for quality. These players often employ a high degree of vertical integration, controlling both manufacturing and retail distribution to maintain product exclusivity. However, the market also features a growing number of emerging brands and online retailers, such as Blue Nile and David Yurman, which cater to changing consumer preferences for customization and personalized experiences. This shift towards e-commerce and digital platforms is reshaping the market, as consumers increasingly value convenience and direct access to luxury products. The market is characterized by high consumer loyalty, premium pricing, and a continuous drive for innovation in design and materials.
Report Coverage
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The United States luxury fine jewelry market is expected to continue growing, driven by rising disposable incomes and increasing consumer affluence.
- Demand for sustainable and ethically sourced jewelry will increase as consumers become more environmentally and socially conscious.
- Online sales will experience significant growth, with e-commerce platforms becoming a key channel for luxury jewelry purchases.
- Customization and personalization will be central to consumer preferences, with more brands offering bespoke jewelry options.
- The market will see continued expansion in emerging regions, with a focus on catering to affluent consumers in smaller cities and towns.
- Advances in technology, including 3D printing and augmented reality, will enhance the customer experience and streamline production processes.
- Jewelry as an investment asset will gain popularity, with more consumers purchasing fine jewelry for both personal use and as financial assets.
- Luxury jewelry brands will increasingly collaborate with designers, celebrities, and influencers to attract younger consumers.
- The trend toward minimalistic and modern designs will grow, appealing to younger generations seeking high-end yet understated pieces.
- The market will face increased competition, with both established and new brands focusing on differentiation through unique designs and superior craftsmanship.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Disposable Income
Rising disposable income among affluent U.S. consumers enables greater spending on luxury goods, including fine jewelry, supporting market expansion as more individuals seek premium and exclusive products.
Demand for Personalized and Custom Jewelry
Consumers are increasingly seeking unique, custom-designed jewelry pieces that reflect their personal style, prompting brands to offer bespoke services and driving growth in the luxury segment.
Shift Toward Ethical and Sustainable Jewelry
Growing consumer awareness and preference for ethically sourced and sustainable materials are pushing brands to adopt transparent supply chains and eco-friendly practices, attracting socially conscious buyers.
Expansion of Online and E-Commerce Platforms
The proliferation of digital channels and e-commerce platforms has made luxury fine jewelry more accessible, allowing brands to reach a broader audience and providing consumers with convenient purchasing options.
Jewelry as an Investment Asset
There is a rising trend of consumers viewing high-end jewelry as a form of investment, particularly in precious metals and rare gemstones, which boosts demand for investment-grade pieces and supports market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the United States Luxury Fine Jewelry market?
What factors are driving the growth of the United States Luxury Fine Jewelry market?
What are some challenges faced by the United States Luxury Fine Jewelry market?
Who are the major players in the United States Luxury Fine Jewelry market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Rings
- 1.2.2 Necklaces
- 1.2.3 Earrings
- 1.2.4 Bracelets
- 1.2.5 Watches
- 1.3 By Material
- 1.3.1 Gold
- 1.3.2 Platinum
- 1.3.3 Diamonds
- 1.3.4 Colored Gemstones
- 1.3.5 Pearls
- 1.4 By Application
- 1.4.1 Personal Use
- 1.4.2 Gifting
- 1.4.3 Investment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,356.1 million → 2032: USD 23,210.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 United States Luxury Fine Jewelry Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 United States Luxury Fine Jewelry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 United States Luxury Fine Jewelry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 United States Luxury Fine Jewelry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 United States Luxury Fine Jewelry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 United States Luxury Fine Jewelry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 United States Luxury Fine Jewelry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 United States Luxury Fine Jewelry Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,356.1 million → 2032: USD 23,210.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 United States Luxury Fine Jewelry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Rings
- 12.3.7.2 Necklaces
- 12.3.7.3 Earrings
- 12.3.7.4 Bracelets
- 12.3.7.5 Watches
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gold
- 12.4.7.2 Platinum
- 12.4.7.3 Diamonds
- 12.4.7.4 Colored Gemstones
- 12.4.7.5 Pearls
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Personal Use
- 12.5.7.2 Gifting
- 12.5.7.3 Investment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 United States Luxury Fine Jewelry End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 United States Luxury Fine Jewelry Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 United States Luxury Fine Jewelry Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 United States Luxury Fine Jewelry Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tiffany & Co.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cartier
- 18.4 Harry Winston
- 18.5 Bvlgari
- 18.6 Van Cleef & Arpels
- 18.7 David Yurman
- 18.8 Mikimoto
- 18.9 Roberto Coin
- 18.10 Brilliant Earth
- 18.11 Blue Nile
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

