
Market Overview:
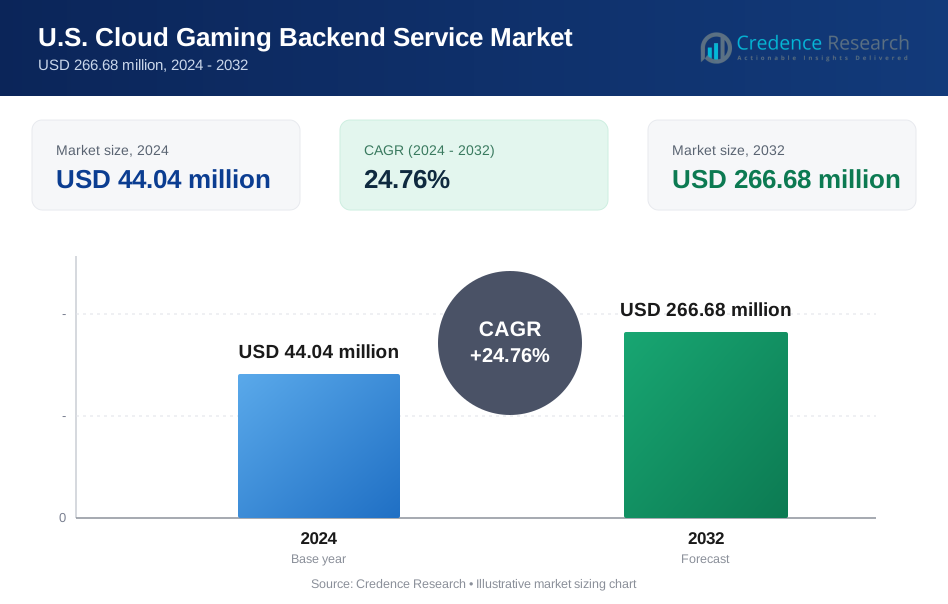
The U.S. Cloud Gaming Backend Service Market size was valued at USD 21.99 million in 2018 to USD 44.04 million in 2024 and is anticipated to reach USD 266.68 million by 2032, at a CAGR of 24.76% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Cloud Gaming Backend Service Market Size 2024 | USD 44.04 million |
| U.S. Cloud Gaming Backend Service Market, CAGR | 24.76% |
| U.S. Cloud Gaming Backend Service Market Size 2032 | USD 266.68 million |
The market is driven by the rising adoption of high-speed internet and the growing preference for low-latency gaming experiences. Increasing smartphone penetration and the popularity of multi-device compatibility further support demand. Developers focus on delivering scalable solutions and immersive experiences through cloud-based infrastructure. The demand for backend services grows as gaming companies aim to reduce hardware dependence and streamline game delivery across platforms. Advancements in 5G technology and the rise of subscription-based gaming models also enhance market growth prospects in the coming years.
Regionally, the U.S. dominates the cloud gaming backend service landscape due to its robust digital infrastructure and high adoption of advanced technologies. North America, particularly the U.S., leads with strong investments from tech giants and gaming studios. Europe follows as a key region, driven by increasing demand for cross-platform gaming. Meanwhile, Asia-Pacific is emerging rapidly due to expanding mobile gaming adoption and rising internet penetration in countries like India, South Korea, and China. These regions benefit from supportive demographics, growing digital ecosystems, and rising consumer interest in cloud-based entertainment solutions.

Market Insights:
- The U.S. Cloud Gaming Backend Service Market grew from USD 21.99 million in 2018 to USD 44.04 million in 2024 and is projected to reach USD 266.68 million by 2032, registering a CAGR of 24.76%.
- The Global Cloud Gaming Backend Service Market size was valued at USD 93.44 million in 2018 to USD 525.00 million in 2024 and is anticipated to reach USD 3,129.24 million by 2032, at a CAGR of 25.00% during the forecast period.
- The West holds the largest share at 40%, driven by advanced infrastructure and the presence of leading cloud providers. The South follows with 30% due to rising digital investments, while the Midwest contributes 17% with SME-led adoption.
- The Northeast accounts for 13% and continues to expand steadily, supported by financial hubs and strong tech talent pools, ensuring stable growth momentum.
- Professional Services dominated type segmentation with 35% share in 2024, driven by consulting, deployment, and integration requirements for cloud gaming platforms.
- Usage Analytics accounted for 25% in 2024, reflecting rising demand for real-time insights into player behavior and system performance.\
Market Drivers
Growing Penetration of High-Speed Internet Networks Enhancing Cloud Gaming Accessibility
The rapid growth of high-speed internet adoption is driving demand across the U.S. Cloud Gaming Backend Service Market. Expanding fiber optic networks and the accelerated rollout of 5G services ensure stable connectivity. These advancements reduce latency and improve response times, creating a seamless user experience. High-speed internet eliminates the need for expensive hardware by enabling smooth streaming of advanced titles. It allows users to engage in multiplayer and competitive gaming environments with improved efficiency. Affordable broadband packages make gaming services accessible to larger demographics. Backend providers optimize infrastructure to meet the rising connectivity expectations. It remains a core driver for sustaining long-term market adoption.
- For example, Verizon reported that its 5G Ultra Wideband network in the U.S. achieved average latency below 20 milliseconds in 2024. This performance enabled cloud gaming platforms to stream AAA titles with minimal lag and high-quality resolution.
Expanding Popularity of Cross-Platform Compatibility and Multi-Device Access
Cross-platform gaming continues to fuel significant growth for the U.S. Cloud Gaming Backend Service Market. Consumers demand uninterrupted gameplay across smartphones, PCs, consoles, and smart TVs. This flexibility encourages higher adoption among casual and professional gamers alike. Backend services enable real-time synchronization of game progress and in-game assets across devices. The ease of transitioning between platforms builds customer loyalty and drives subscription retention. Hardware limitations become less relevant as users access premium content without upgrades. Developers focus on delivering scalable backend frameworks to ensure performance consistency. It has emerged as a decisive factor in shaping consumer adoption rates.
Rising Focus on Subscription-Based Revenue Models Supporting Steady Growth
Subscription-based models have become a reliable revenue driver across the U.S. Cloud Gaming Backend Service Market. Players prefer affordable monthly or annual subscriptions instead of costly one-time purchases. These models provide unlimited access to broad gaming libraries, increasing user engagement. Service providers benefit from recurring cash flows, which support reinvestment in advanced backend infrastructure. Partnerships with telecom operators and media platforms enhance subscription bundling strategies. Growing adoption of subscriptions encourages developers to expand content offerings. Gamers appreciate flexible payment options that align with evolving entertainment preferences. It reinforces consistent market expansion while improving revenue predictability for service providers.
- For example, NVIDIA’s GeForce NOW hosts a library of over 2,000 games and serves millions of users streaming each month. The platform continues to expand through backend upgrades and regular new title integrations, supporting steady global engagement.
Accelerated Deployment of Advanced Cloud Infrastructure and Edge Computing Capabilities
The integration of advanced cloud infrastructure has become a critical growth driver. The U.S. Cloud Gaming Backend Service Market benefits from investments in data centers and edge computing solutions. These deployments reduce latency and provide optimized game performance in real time. Edge computing ensures closer data processing, which minimizes service interruptions during peak demand. Enhanced infrastructure attracts developers seeking reliable backend frameworks to host large-scale titles. Scalable platforms allow providers to adapt to growing user bases quickly. Gamers benefit from reduced delays, improved graphics, and better performance consistency. It strengthens the ecosystem by supporting next-generation gaming experiences at scale.
Market Trends
Integration of Artificial Intelligence and Machine Learning Enhancing Personalized Gameplay
The adoption of artificial intelligence and machine learning has become a strong trend in the U.S. Cloud Gaming Backend Service Market. These technologies enable real-time analytics that improve user experience and resource allocation. AI-driven tools optimize matchmaking and gameplay environments, enhancing competitive balance. Predictive models analyze gaming patterns to personalize recommendations for players. Backend systems use machine learning to manage server loads and prevent disruptions. It allows service providers to deliver adaptive content that meets individual player needs. Developers leverage AI insights to design more immersive and engaging experiences. This trend establishes a more intelligent and responsive backend ecosystem.
Expansion of Strategic Partnerships Between Gaming Platforms and Telecom Providers
Partnerships with telecom operators are transforming growth strategies across the U.S. Cloud Gaming Backend Service Market. Telecom providers integrate cloud gaming services into broadband and mobile packages. This collaboration enhances customer acquisition and broadens accessibility. The combination of 5G infrastructure with gaming solutions strengthens service quality. It creates mutual benefits by improving customer retention for telecoms and expanding user bases for gaming platforms. Joint marketing initiatives increase visibility for subscription models. Developers also gain infrastructure support that reduces deployment costs. This trend reinforces industry growth through strategic and scalable collaborations.
Growing Demand for Cloud-Based Esports Infrastructure and Competitive Gaming Platforms
Esports expansion has created demand for reliable backend solutions in the U.S. Cloud Gaming Backend Service Market. Large-scale tournaments require low latency and stable platforms to support high performance. Cloud backend services provide the scalability to handle large concurrent audiences. Service providers optimize infrastructure to deliver seamless live streaming of competitive events. The increasing popularity of online tournaments and leagues further accelerates demand. Backend frameworks also support player data management, security, and analytics. It aligns with the growing professionalization of esports as a mainstream entertainment sector. This trend underscores the critical role of backend services in competitive gaming.
- For example, Riot Games partners with AWS to power its esports backend, using cloud infrastructure to scale globally. Riot leverages AWS Local Zones and other services to reduce latency and improve gameplay performance for players worldwide. AWS also supports Riot’s Kubernetes-based infrastructure for managing deployments and scaling game services in real time.
Incorporation of Cloud Gaming in Smart Devices and Connected Ecosystems
The integration of cloud gaming into smart TVs, set-top boxes, and IoT devices is gaining momentum. The U.S. Cloud Gaming Backend Service Market adapts to support device ecosystems beyond PCs and consoles. Smart device manufacturers collaborate with gaming platforms to expand consumer reach. It allows users to enjoy console-quality experiences without hardware investments. The trend encourages developers to design interfaces optimized for diverse device categories. Increased device compatibility broadens market accessibility and reduces adoption barriers. Service providers align backend infrastructure to handle dynamic device integrations. This trend redefines the gaming experience by linking cloud platforms with connected households.
- For example, Sony’s 2024 BRAVIA TVs support PS Remote Play, enabling users to stream PlayStation games directly to their TV. These models also include HDMI 2.1 support, allowing gameplay at up to 4K resolution and 120fps. Input lag is minimized, with Sony citing as low as 8.5 milliseconds on certain BRAVIA models, making them optimized for competitive gaming.

Market Challenges Analysis
High Infrastructure Costs and Latency Issues Restricting Wider Market Expansion
The deployment of advanced cloud infrastructure remains capital intensive, creating barriers for new entrants. The U.S. Cloud Gaming Backend Service Market requires continuous investment in servers, data centers, and edge computing nodes. High infrastructure costs limit smaller developers from competing effectively against established providers. Latency concerns still challenge user satisfaction, especially in regions with uneven internet penetration. Service interruptions and delays undermine the seamless experiences demanded by gamers. It forces providers to commit significant resources to maintain performance standards. Balancing scalability with affordability remains a critical challenge for sustainable growth. This issue creates operational complexities that slow market penetration.
Intellectual Property Concerns and Data Security Risks Impacting Industry Confidence
Data security has emerged as a major concern for service providers and consumers alike. The U.S. Cloud Gaming Backend Service Market faces risks involving data breaches and unauthorized access. Backend systems store sensitive player data, in-game assets, and subscription details. Intellectual property concerns also arise with the distribution of licensed content through cloud platforms. Providers must comply with regulatory standards to protect consumer trust. Security lapses can damage brand reputation and limit adoption rates. It compels developers to invest in stronger encryption and monitoring frameworks. Addressing these concerns remains essential for maintaining confidence in the industry.
Market Opportunities
Rising Expansion of 5G Connectivity Unlocking New Possibilities for Cloud Gaming Adoption
The deployment of 5G networks across the U.S. provides a strong opportunity for the U.S. Cloud Gaming Backend Service Market. Ultra-low latency and higher bandwidth open new possibilities for advanced multiplayer experiences. Telecom integration ensures broader accessibility for mobile gamers in urban and rural areas. It enables the smooth delivery of high-definition graphics without device limitations. Providers can build innovative services that rely on real-time responsiveness. New customer segments emerge as mobile-based gaming becomes more viable. Subscription models aligned with 5G rollouts create attractive growth potential. This opportunity supports the acceleration of next-generation gaming experiences nationwide.
Emergence of Smart Device Ecosystems and Expanding Consumer Demographics Driving Growth
The growing integration of smart devices into households enhances adoption opportunities. The U.S. Cloud Gaming Backend Service Market benefits from the expanding user base across connected platforms. Smart TVs, tablets, and IoT devices provide new avenues for consumer engagement. It reduces hardware costs while making cloud services accessible to non-traditional gamers. The demographic shift includes younger audiences and older consumers seeking casual experiences. Service providers can design inclusive offerings that capture diverse interests. Partnerships with device manufacturers expand visibility and strengthen distribution networks. This opportunity drives the market toward greater consumer inclusivity and growth scalability.
Market Segmentation Analysis:
By Type, the U.S. Cloud Gaming Backend Service Market shows strong adoption across professional services, support and maintenance, access and identity management, usage analytics, and others. Professional services hold significant importance, offering customized integration, consulting, and deployment support for gaming platforms. Support and maintenance services ensure consistent uptime, performance optimization, and technical assistance for cloud-based operations. Access and identity management is vital for secure logins, multi-device access, and data protection in gaming environments. Usage analytics plays a growing role by enabling real-time monitoring of player activity, user engagement, and system performance. Other services cater to niche requirements, including API management and billing integration, supporting the broader ecosystem.
- For instance, Amazon Web Services (AWS) offers professional services that include customized integration and deployment support specifically tailored for gaming platforms, supporting seamless game launches for studios like Ubisoft.
By End-User, the U.S. Cloud Gaming Backend Service Market caters to small and medium enterprises alongside large enterprises. Small and medium enterprises leverage backend solutions to reduce hardware costs and deliver flexible gaming experiences without investing in extensive infrastructure. It enables them to compete with larger firms by accessing scalable, cloud-based services. Large enterprises dominate demand through heavy investment in advanced platforms, cloud infrastructure, and wide gaming portfolios. They rely on backend services for managing high player volumes, security compliance, and performance reliability. Both segments collectively drive market expansion, supported by rising demand for scalable and cost-efficient gaming solutions.
- For example, small and medium gaming developers using Unity’s backend services gain scalable cloud infrastructure reducing their dependency on costly hardware, allowing them to deploy multiplayer features rapidly and compete with bigger studios.

Segmentation:
By Type
- Professional Services
- Support and Maintenance
- Access and Identity Management
- Usage Analytics
- Others
By End-User
- Small and Medium Enterprises
- Large Enterprises
Regional Analysis:
Regional Analysis
The U.S. Cloud Gaming Backend Service Market shows clear dominance by the West region, holding 40% of the market share. Strong technology infrastructure, early adoption of 5G networks, and the presence of leading gaming and cloud service providers contribute to this position. The West benefits from established innovation hubs and strong investment activity, creating an ecosystem conducive to cloud gaming growth. Major companies in California and Washington actively deploy backend frameworks to strengthen scalability. The concentration of skilled developers also supports the region’s leadership. It continues to be the center of innovation and high-value adoption.
The South holds 30% of the market share, driven by rapid expansion of digital infrastructure and rising consumer demand. States like Texas and Florida are emerging as key contributors due to increasing investment in cloud technologies and gaming adoption. Strong growth in esports and the availability of affordable broadband packages strengthen the regional outlook. The South also benefits from its growing population base that contributes to rising subscription uptake. Gaming startups and mid-sized enterprises rely heavily on backend services to scale cost-efficiently. It has emerged as a fast-growing hub for both consumers and developers.
The Midwest and Northeast collectively account for 30% of the U.S. Cloud Gaming Backend Service Market, with the Midwest at 17% and the Northeast at 13%. The Midwest sees growth fueled by adoption among small and medium enterprises seeking affordable solutions. Infrastructure expansion in states like Illinois and Ohio improves latency and service quality. The Northeast benefits from established financial hubs that encourage partnerships and investment in gaming platforms. Educational institutions and tech talent pools in the region also contribute to adoption. It shows steady demand across enterprise and consumer segments. These subregions strengthen the nationwide footprint of backend gaming services.
Key Player Analysis:
- Microsoft Azure
- Amazon Web Services (AWS)
- Google Cloud Platform
- NVIDIA GeForce Now
- IBM Cloud
- Unity Technologies (Parsec)
- LiquidSky Software
- Vortex
- Shadow
- Back4App
Competitive Analysis:
The U.S. Cloud Gaming Backend Service Market is defined by intense competition among global technology leaders and specialized service providers. Companies such as Microsoft Azure, Amazon Web Services, and Google Cloud dominate with extensive infrastructure, robust scalability, and strategic partnerships with developers. NVIDIA GeForce Now differentiates its presence through direct-to-consumer offerings while integrating backend solutions for gaming platforms. IBM Cloud and Unity Technologies (Parsec) enhance their positions by focusing on secure, developer-centric frameworks. Emerging players like LiquidSky, Vortex, Shadow, and Back4App target niche markets with tailored solutions, creating competitive diversity. It benefits from a competitive environment where firms emphasize innovation, latency reduction, and multi-device accessibility. Leaders invest in artificial intelligence, machine learning, and edge computing to strengthen backend efficiency. Mergers, acquisitions, and product launches remain critical strategies to expand portfolios and retain market share. Competitive intensity pushes companies to align pricing strategies with consumer demand for affordable, scalable services.
Recent Developments:
- In September 2025, NVIDIA launched the Blackwell RTX upgrade for GeForce NOW, bringing RTX 5080-class power streaming to the cloud. This update enables higher gaming resolutions and frame rates, new competitive high-performance modes, and access to over 2,200 titles, further solidifying NVIDIA's presence in the North American cloud gaming backend service market.
- In June 2025, NVIDIA entered additional publisher partnerships that added over 25 new titles to GeForce NOW in North America, reflecting the company's continued collaboration-oriented growth in the backend gaming service space.
- In March 2025, Xsolla and AWS entered into a key partnership designed to empower game developers with the latest advancements in cloud gaming and LiveOps solutions. The collaboration leverages AWS’s cloud infrastructure and Xsolla’s developer platform to create scalable, flexible backend solutions, further strengthening their positions in the expanding global cloud gaming backend service sector.
- In July 2024, Xsolla announced the acquisition of LF.Group to enhance gaming connectivity and commerce, empower creators, and improve user engagement across multiple platforms. This strategic move aims to give Xsolla a stronger foothold in the global cloud gaming backend service market by integrating LF.Group's technology stack and community features into its existing offerings, driving forward innovation in backend solutions for cloud gaming environments.
Report Coverage:
The research report offers an in-depth analysis based on type and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of 5G networks will enhance low-latency performance and attract new user segments.
- Demand for cross-platform gaming will accelerate adoption across mobile, PC, and smart TV ecosystems.
- Subscription-based models will dominate revenue generation, driving consistent market expansion.
- AI and machine learning integration will personalize experiences and optimize backend resource management.
- Esports growth will increase reliance on scalable, high-performance backend solutions.
- Strategic partnerships between telecom operators and gaming providers will strengthen market reach.
- Smart device integration will expand gaming accessibility beyond traditional platforms.
- Rising cloud infrastructure investments will improve service quality and scalability.
- Data security and compliance innovation will enhance consumer confidence in cloud services.
- Competition among established players and startups will drive faster innovation and better pricing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Penetration of High-Speed Internet Networks
The rapid expansion of fiber optic and 5G networks in the U.S. is enabling stable, low-latency connections essential for cloud gaming, making advanced gaming experiences accessible to a wider audience and reducing reliance on expensive hardware.
Expansion of Cross-Platform and Multi-Device Compatibility
Consumers increasingly expect seamless gameplay across smartphones, PCs, consoles, and smart TVs, driving demand for backend services that synchronize game progress and assets in real time and support flexible, device-agnostic gaming experiences.
Rising Adoption of Subscription-Based Revenue Models
Affordable monthly or annual subscriptions are replacing one-time purchases, providing users with access to large gaming libraries and generating predictable, recurring revenue streams for service providers, which supports ongoing investment in backend infrastructure.
Deployment of Advanced Cloud Infrastructure and Edge Computing
Investments in data centers and edge computing nodes are reducing latency and improving real-time game performance, attracting developers and enabling scalable, high-quality gaming experiences for large and geographically dispersed user bases.
Integration of AI and Machine Learning for Personalization and Optimization
AI and machine learning technologies are being used to personalize gameplay, optimize server loads, and enhance matchmaking, resulting in more engaging user experiences and more efficient backend resource management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Cloud Gaming Backend Service Market, and what is its projected size in 2032?
Which U.S. Cloud Gaming Backend Service Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Cloud Gaming Backend Service Market?
Which region commanded the largest share of the U.S. Cloud Gaming Backend Service Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Professional Services
- 1.2.2 Support and Maintenance
- 1.2.3 Access and Identity Management
- 1.2.4 Usage Analytics
- 1.2.5 Others
- 1.3 By End-User
- 1.3.1 Small and Medium Enterprises
- 1.3.2 Large Enterprises
- 1.4 By Application
- 1.4.1 Multiplayer Game Hosting
- 1.4.2 Esports Platforms
- 1.4.3 Game Analytics
- 1.4.4 Cross-Platform Game Delivery
- 1.5 By Region (U.S.)
- 1.5.1 West
- 1.5.2 South
- 1.5.3 Midwest
- 1.5.4 Northeast
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44.04 million → 2032: USD 266.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Cloud Gaming Backend Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Cloud Gaming Backend Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 U.S. Cloud Gaming Backend Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 U.S. Cloud Gaming Backend Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Cloud Gaming Backend Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Cloud Gaming Backend Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Cloud Gaming Backend Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Cloud Gaming Backend Service Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44.04 million → 2032: USD 266.68 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Cloud Gaming Backend Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Professional Services
- 12.3.6.2 Support and Maintenance
- 12.3.6.3 Access and Identity Management
- 12.3.6.4 Usage Analytics
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Small and Medium Enterprises
- 12.4.6.2 Large Enterprises
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Multiplayer Game Hosting
- 12.5.6.2 Esports Platforms
- 12.5.6.3 Game Analytics
- 12.5.6.4 Cross-Platform Game Delivery
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Region (U.S.) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 West
- 12.6.6.2 South
- 12.6.6.3 Midwest
- 12.6.6.4 Northeast
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Cloud Gaming Backend Service End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Cloud Gaming Backend Service Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Cloud Gaming Backend Service Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Cloud Gaming Backend Service Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Azure
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Amazon Web Services (AWS)
- 18.4 Google Cloud Platform
- 18.5 NVIDIA GeForce Now
- 18.6 IBM Cloud
- 18.7 Unity Technologies (Parsec)
- 18.8 LiquidSky Software
- 18.9 Vortex
- 18.10 Shadow
- 18.11 Back4App
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

