
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
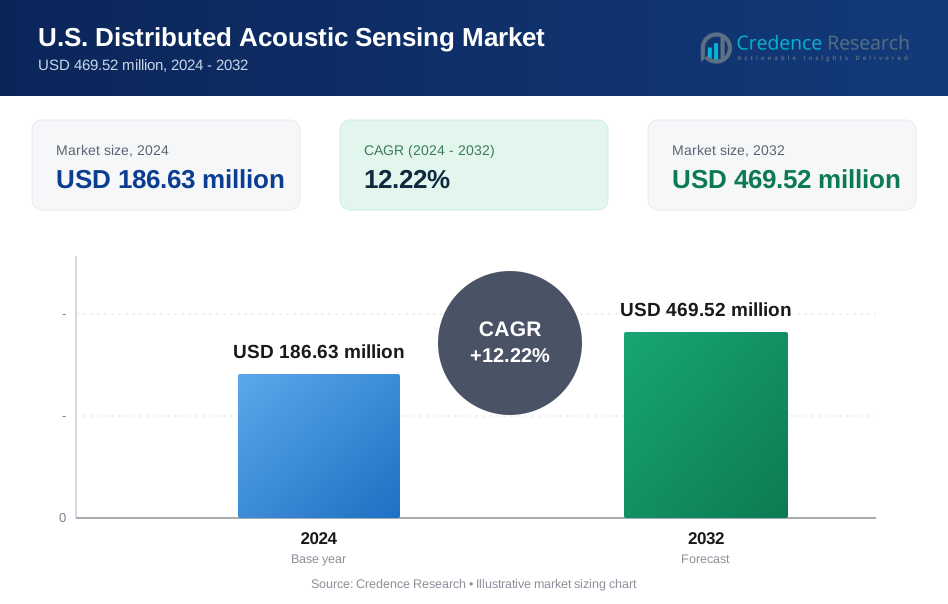
| U.S. Distributed Acoustic Sensing Market Size 2024 | USD 186.63 million |
| U.S. Distributed Acoustic Sensing Market, CAGR | 12.22% |
| U.S. Distributed Acoustic Sensing Market Size 2032 | USD 469.52 million |
Market Overview:
The U.S. Distributed Acoustic Sensing Market is projected to grow from USD 186.63 million in 2024 to an estimated USD 469.52 million by 2032, with a compound annual growth rate (CAGR) of 12.22% from 2024 to 2032.
Several factors are propelling the growth of the U.S. DAS market. Foremost is the heightened need for real-time monitoring and enhanced security measures in critical infrastructure. DAS technology offers continuous, long-distance sensing capabilities along fiber optic cables, providing a cost-effective and efficient solution for monitoring pipelines, power lines, and transportation networks. Advancements in fiber optic technology and signal processing have significantly improved the performance and accuracy of DAS systems, making them more reliable for detecting and analyzing acoustic signals. Additionally, the integration of artificial intelligence (AI) and machine learning (ML) algorithms enhances data analysis, enabling predictive maintenance and early detection of anomalies. These technological advancements, coupled with the growing emphasis on infrastructure security and operational efficiency, are driving the adoption of DAS solutions across various industries.
Within the U.S., the adoption of DAS technology varies across regions, influenced by the concentration of industry activities and infrastructure development. The Western region, including states like California and Texas, is a significant hub for energy and infrastructure projects, leading to increased demand for DAS solutions in oil and gas pipelines and power transmission lines. The Eastern region, encompassing states such as New York and Pennsylvania, has a high density of critical infrastructure and transportation networks, resulting in greater adoption of DAS for security and surveillance applications. This regional distribution underscores the versatility of DAS technology in addressing diverse monitoring and security needs across the country
Market Insights:
- The U.S. Distributed Acoustic Sensing Market is projected to grow from USD 186.63 million in 2024 to an estimated USD 469.52 million by 2032, with a compound annual growth rate (CAGR) of 12.22% from 2024 to 2032.
- The Global Distributed Acoustic Sensing Market is projected to grow from USD 639.45 million in 2024 to an estimated USD 1596.46 million by 2032, with a compound annual growth rate (CAGR) of 12.12% from 2024 to 2032.
- DAS technology offers a cost-effective and efficient solution for monitoring critical infrastructure like pipelines, power lines, and transportation networks, ensuring operational reliability.
- Technological advancements in fiber optic technology and signal processing are improving the performance and sensitivity of DAS systems, allowing for more accurate anomaly detection.
- The integration of AI and machine learning in DAS systems is enhancing data analysis, enabling predictive maintenance and early identification of potential issues.
- The market is experiencing growing adoption of DAS in smart transportation and rail monitoring, as it provides cost-effective, non-intrusive, and scalable solutions for infrastructure management.
- The Western U.S. region, including states like California and Texas, is a key hub for DAS adoption due to its energy and infrastructure projects, particularly in oil and gas.
- Despite the promising growth, challenges such as high initial investment costs, data interpretation complexities, and a shortage of skilled professionals hinder broader adoption of DAS technology.
Report scope
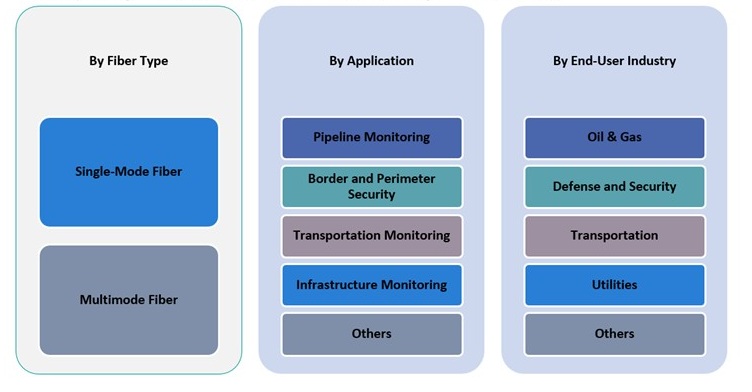
This report segments the U.S. Distributed Acoustic Sensing Market as follow
Market Drivers:
Expansion of Critical Infrastructure and Pipeline Monitoring
The rapid expansion and modernization of critical infrastructure in the United States significantly drive the demand for distributed acoustic sensing technology. As aging pipelines and energy transmission lines become increasingly susceptible to failures, operators are prioritizing proactive monitoring solutions to mitigate risks. DAS systems provide continuous, real-time surveillance along the length of fiber optic cables, allowing for early detection of anomalies such as pipeline leaks, intrusions, or mechanical stress. For example, DAS systems can monitor the entire length of oil and gas pipelines using telecommunications-grade fiber optic cables that stretch thousands of kilometers, offering resilience in harsh environments. This capability aligns with the growing emphasis on safety and regulatory compliance, particularly in the oil and gas sector, where environmental and financial consequences of undetected faults can be severe. Consequently, DAS technology has become integral to enhancing operational reliability and reducing downtime in large-scale infrastructure projects.
Rising Emphasis on Border Security and Surveillance
The heightened focus on national security and border surveillance further propels the adoption of DAS solutions in the U.S. market. DAS enables long-distance intrusion detection through underground and fence-mounted fiber optics, making it highly suitable for securing perimeters in remote or sensitive locations. Government agencies and defense contractors are increasingly deploying DAS systems to monitor border zones, power substations, and military installations. These systems offer a non-intrusive and efficient method of detecting vibrations caused by unauthorized movements or tampering, providing actionable data in real time. For instance, Sintela's ONYX™ DAS platform has been successfully deployed for the U.S. border Linear Ground Detection System (LGDS), enhancing perimeter security by detecting unauthorized activities such as digging or climbing. The growing need for robust, scalable, and minimally invasive surveillance systems enhances the role of DAS in safeguarding strategic national assets.
Technological Advancements in Fiber Optics and Signal Processing
Continuous innovation in fiber optic technology and acoustic signal processing has significantly improved the performance, accuracy, and sensitivity of DAS systems. These advancements have enabled broader application across industries that demand real-time data insights and minimal operational interruptions. Enhanced sensitivity allows DAS systems to distinguish between various acoustic events such as footsteps, vehicular movements, or leaks, facilitating more informed decision-making. Furthermore, the integration of machine learning and artificial intelligence in DAS platforms enables automatic pattern recognition, anomaly detection, and predictive maintenance. As the U.S. industrial sector accelerates digital transformation, the role of advanced sensing technologies like DAS becomes increasingly central to enabling smarter infrastructure management.
Growing Adoption in Smart Transportation and Rail Monitoring
The adoption of DAS in smart transportation networks, particularly in rail monitoring applications, is a key driver in the U.S. market. Rail operators are leveraging DAS technology to monitor rail tracks, detect wheel flats, track obstructions, and identify structural issues without requiring physical sensors along the rails. This capability reduces maintenance costs and enhances passenger safety by providing early warnings of potential failures. As urban mobility and public transportation networks expand, especially in metropolitan regions, the demand for non-invasive, scalable, and accurate monitoring tools is rising. DAS technology meets these needs effectively, offering a valuable solution for transportation agencies aiming to improve service reliability and asset longevity.
Market Trends:
Integration of DAS with AI-Driven Analytics Platforms
A growing trend in the U.S. Distributed Acoustic Sensing market is the integration of DAS systems with advanced analytics platforms powered by artificial intelligence (AI) and machine learning (ML). Operators are increasingly deploying AI-enabled DAS solutions to process vast volumes of acoustic data in real time. These platforms not only enhance event classification and pattern recognition but also allow for adaptive learning over time, improving accuracy with prolonged use. This trend supports a shift toward intelligent sensing networks, where predictive maintenance and automated alerts reduce manual intervention and enhance operational efficiency. As data-driven decision-making becomes more prevalent across industrial sectors, AI-integrated DAS systems are gaining traction as essential components of digital infrastructure.
Shift Toward Cloud-Based Monitoring Solutions
Another prominent trend in the market is the shift toward cloud-based DAS monitoring systems. Companies across sectors are adopting cloud infrastructure to centralize data management, improve accessibility, and facilitate remote monitoring. Cloud-enabled DAS platforms offer scalability, faster data processing, and seamless integration with enterprise resource planning (ERP) systems and other industrial Internet of Things (IIoT) devices. For example, organizations leveraging cloud-enabled DAS platforms have reported benefits such as reduced deployment timelines and improved scalability for managing dispersed assets. This transformation aligns with broader digitalization efforts across industries such as energy, transportation, and utilities, where remote diagnostics and centralized data access are becoming critical for managing geographically dispersed assets. The transition to cloud-based solutions also reduces upfront capital expenditure and accelerates deployment timelines, further boosting market adoption.
Expansion of DAS Applications in Renewable Energy Projects
The rise of renewable energy infrastructure, particularly in wind and solar projects, is creating new avenues for the application of DAS technology in the U.S. DAS systems are increasingly being deployed to monitor the structural integrity and cable health of wind farms and solar panel installations. These projects, often located in remote or environmentally sensitive areas, benefit from DAS’s ability to deliver real-time insights without requiring intrusive installation methods. For instance, federal clean energy initiatives have driven the adoption of DAS for optimizing maintenance schedules and reducing downtime, thereby supporting ambitious sustainability goals. This trend reflects a broader push toward sustainability and innovation in infrastructure monitoring.
Growing Demand from the Telecommunications Sector
The U.S. telecommunications sector is also emerging as a key adopter of DAS solutions due to the increasing reliance on fiber optic networks. With the nationwide rollout of 5G and the expansion of broadband infrastructure, service providers are turning to DAS technology to monitor and protect fiber optic lines from physical threats such as digging, environmental damage, and vandalism. DAS systems offer continuous monitoring capabilities that help identify and localize potential disruptions before they affect service delivery. As the demand for uninterrupted high-speed connectivity continues to grow, telecommunications providers are incorporating DAS into their network protection strategies to ensure resilience and quality of service.
Market Challenges Analysis:
High Initial Investment and Deployment Complexity
One of the primary restraints affecting the growth of the U.S. Distributed Acoustic Sensing market is the high initial investment required for system deployment. While DAS technology leverages existing fiber optic infrastructure, retrofitting legacy systems or laying new fiber cables for sensing purposes can incur significant costs. For instance, DAS interrogators, essential components of these systems, can cost over $100,000, making them a significant expense for organizations. This financial barrier is particularly challenging for small and medium-sized enterprises (SMEs) that may lack the capital for large-scale implementation. Additionally, the integration of DAS systems into existing networks often involves complex calibration and customization, requiring skilled technical personnel and extended deployment timelines.
Data Interpretation and False Positives
Another critical challenge is the complexity of interpreting acoustic data and managing false positives. Although DAS systems provide vast amounts of real-time data, accurately distinguishing between relevant signals—such as leak detection or intrusion—and benign environmental noise remains difficult. The presence of false alarms can lead to operational inefficiencies and reduce trust in the system’s reliability. While advancements in machine learning are addressing this issue, the accuracy of signal classification still depends heavily on system configuration, environmental factors, and historical data availability.
Lack of Standardization and Regulatory Uncertainty
The absence of universal standards for DAS technology presents an additional challenge in the U.S. market. Different vendors offer proprietary systems with varying protocols, sensor sensitivities, and integration capabilities, which can complicate interoperability and limit scalability. Moreover, regulatory frameworks related to data privacy, especially in applications involving security and surveillance, remain fragmented and continue to evolve. This uncertainty may deter broader adoption, especially in sectors with stringent compliance requirements.
Skilled Workforce Shortage
Finally, the limited availability of professionals skilled in fiber optic sensing, data analytics, and signal processing poses a challenge to widespread DAS implementation. Organizations may struggle to recruit or train personnel capable of managing and interpreting DAS systems, delaying adoption and reducing system effectiveness.
Market Opportunities:
The U.S. Distributed Acoustic Sensing market presents significant growth opportunities, particularly in industries focused on critical infrastructure monitoring and security. As aging infrastructure, such as pipelines, power lines, and transportation networks, becomes more vulnerable to failures, DAS technology offers an effective and cost-efficient solution for continuous monitoring. The growing emphasis on predictive maintenance and early detection of anomalies creates an opportunity for DAS systems to expand across sectors like oil and gas, utilities, and transportation. With the increasing need for robust and reliable monitoring, especially in remote or hazardous environments, DAS provides a scalable solution that reduces operational risks and enhances asset longevity.
Moreover, the integration of DAS with advanced technologies like artificial intelligence (AI) and machine learning (ML) opens up new avenues for data-driven decision-making and real-time analytics. As industries continue to digitize their operations, the demand for smart monitoring solutions will rise. In particular, applications in renewable energy, such as wind farms and solar energy infrastructure, offer a promising opportunity for DAS technology to monitor and optimize performance in remote locations. The rise of 5G infrastructure and fiber optic networks also presents a fertile ground for DAS adoption in the telecommunications sector, as service providers seek more efficient ways to monitor network performance and protect against potential disruptions. These evolving trends provide a substantial market opportunity for DAS technology to play a central role in next-generation infrastructure monitoring and security systems.
Market Segmentation Analysis:
The U.S. Distributed Acoustic Sensing (DAS) market is segmented based on fiber type, application, and end-user industry, each contributing to the growth and adoption of DAS technology across various sectors.
By Fiber Type
The DAS market is divided into Single-Mode Fiber (SMF) and Multimode Fiber (MMF). Single-Mode Fiber is predominantly used in long-distance monitoring due to its high sensitivity and ability to cover vast areas with minimal signal loss. It is highly favored in applications such as pipeline monitoring and long-range infrastructure surveillance. On the other hand, Multimode Fiber, with its ability to transmit multiple light modes, is typically used for shorter-range applications. Although it has a higher loss over long distances, it remains a cost-effective option for localized monitoring in environments like transportation and smaller infrastructure projects.
By Application
The DAS market is categorized into Pipeline Monitoring, Transportation Monitoring, Border and Perimeter Security, Infrastructure Monitoring, and Other applications. Pipeline monitoring is a key segment, driven by the need for real-time surveillance of oil, gas, and water pipelines to detect leaks and other disruptions. Transportation monitoring, particularly for rail networks, is also growing, as DAS systems are used to track track conditions and vehicle movements. Border and perimeter security is expanding due to the increasing demand for surveillance systems in remote locations. Infrastructure monitoring, covering energy transmission lines and critical facilities, is another prominent application, ensuring system integrity and early detection of faults.
By End-User Industry
The DAS market serves various industries, including Oil & Gas, Defense and Security, Transportation, Utilities, and others. The Oil & Gas industry is the largest end-user due to its significant need for pipeline surveillance. Defense and security also contribute heavily, especially in border security applications. The transportation sector, particularly rail and roadways, is adopting DAS for monitoring transportation infrastructure, while utilities are leveraging DAS for power line surveillance and grid management. These sectors continue to drive demand for DAS systems due to their ability to provide reliable, real-time data in challenging environments.
Segmentation:
By Fiber Type:
- Single-Mode Fiber
- Multimode Fiber
By Application:
- Pipeline Monitoring
- Transportation Monitoring
- Border and Perimeter Security
- Infrastructure Monitoring
- Others
By End-User Industry:
- Oil & Gas
- Defense and Security
- Transportation
- Utilities
- Others
Regional Analysis:
The U.S. Distributed Acoustic Sensing (DAS) market is influenced by the geographic distribution of key industries, including oil and gas, utilities, transportation, and defense, which have distinct regional footprints. The market is segmented into key regions, each driving the demand for DAS technology based on its unique infrastructure needs and industrial presence.
Western U.S.
The Western U.S., particularly states like California, Texas, and Alaska, holds a significant market share in the DAS market. These regions are home to substantial oil and gas reserves, with extensive pipeline networks requiring constant monitoring to prevent leaks and disruptions. The Western U.S. also leads in renewable energy production, including wind and solar, where DAS is increasingly deployed for monitoring infrastructure in remote areas. The market share in this region is estimated to account for around 35% of the total U.S. DAS market. Additionally, the growing focus on infrastructure modernization and the expansion of smart cities in cities like San Francisco and Los Angeles contribute to the region’s strong DAS adoption.
Northeastern U.S.
The Northeastern U.S. is another prominent region for DAS adoption, particularly in industries such as transportation and utilities. States like New York and Pennsylvania have extensive transportation networks, including rail systems, which rely on DAS technology for monitoring track conditions and detecting anomalies. The Northeast’s urbanization and critical infrastructure further fuel the demand for DAS solutions in areas such as border security and infrastructure monitoring. This region holds approximately 25% of the overall U.S. DAS market share. The significant presence of utilities, including electric grids and water pipelines, also drives the need for continuous monitoring solutions in this region.
Southern U.S.
The Southern U.S., including states like Louisiana, Mississippi, and Florida, plays a key role in the U.S. DAS market, particularly within the oil and gas industry. The region’s extensive offshore and onshore pipelines require robust, real-time monitoring systems, making DAS an essential tool for leak detection and maintenance. Additionally, the transportation sector in states like Texas drives further adoption in applications such as highway monitoring and traffic flow analysis. The Southern U.S. holds a market share of approximately 20%, reflecting the critical role of energy and transportation in the region’s economy.
Midwestern U.S.
The Midwestern U.S. also contributes to the overall DAS market, particularly in the utilities and infrastructure sectors. States like Illinois, Ohio, and Michigan have dense utility grids and transportation networks that benefit from the deployment of DAS systems. This region’s market share is estimated at 15%. The Midwestern U.S. is seeing increased adoption of DAS in power transmission lines, industrial facilities, and large-scale infrastructure projects, driven by the need for enhanced monitoring and predictive maintenance.
Southern and Pacific Coast Regions
The Pacific Coast and Southern regions, with major cities like Seattle, San Diego, and Houston, continue to embrace DAS for diverse applications, including border security, transportation, and critical infrastructure monitoring. The demand for DAS systems is driven by the regions' expanding economies and growing infrastructure projects. These areas collectively contribute about 5% of the U.S. DAS market.
Key Player Analysis:
- Schlumberger Limited
- Baker Hughes Company
- Halliburton Company
- Silixa Ltd.
- Hifi Engineering Inc.
- OFS Fitel LLC
- AP Sensing GmbH
- Future Fibre Technologies
- OZ Optics Ltd.
- GEOSpace Technologies
Competitive Analysis:
The U.S. Distributed Acoustic Sensing (DAS) market is highly competitive, with key players focusing on technological innovation and strategic partnerships to strengthen their market position. Leading companies such as OptaSense, Fotech Solutions, AP Sensing, and Silixa dominate the market by offering advanced DAS systems that integrate with fiber optic networks to provide real-time monitoring and data analysis. These players invest heavily in research and development to enhance the sensitivity and accuracy of their systems, making them suitable for a wide range of applications, from pipeline monitoring to transportation security. Moreover, companies are increasingly leveraging AI and machine learning to offer predictive analytics, improving the value proposition of their products. Additionally, the market features a mix of regional players providing specialized solutions for specific industries, creating a dynamic competitive landscape. Strategic collaborations with utility, energy, and security providers further strengthen these companies' market presence.
Recent Developments:
- In early 2025, Fotech Solutions Ltd. expanded its DAS offerings specifically for pipeline monitoring in offshore oil and gas applications. This move strengthens its market presence by addressing the growing demand for reliable and efficient monitoring solutions in challenging environments.
- In January 2025, OFS Fitel introduced AcoustiSens Wideband Single-Mode Optical Fibers designed for DAS systems. These fibers improve optical signal-to-noise ratio (OSNR) and are compatible with existing DAS interrogators, making them ideal for applications such as pipeline monitoring, rail monitoring, and smart city projects.
- In September 2023, researchers from the University of New Mexicoand Sandia National Laboratories developed a novel method to monitor local sea ice in Alaska using Distributed Acoustic Sensing (DAS) technology. By leveraging a telecommunications fiber optic cable combined with machine learning algorithms, the team analyzed ground vibrations caused by ocean waves to detect sea ice coverage and strength.
- In December 2023, Luna Innovations Inc. acquired Silixa Ltd., a UK-based leader in distributed fiber optic sensing solutions. This strategic acquisition enhanced Luna’s capabilities in distributed acoustic sensing (DAS), distributed temperature sensing (DTS), and distributed strain sensing (DSS), enabling improved performance for applications in energy, natural environments, mining, and defense.
Market Concentration & Characteristics:
The U.S. Distributed Acoustic Sensing (DAS) market exhibits moderate concentration, with a mix of established global players and regional companies dominating the landscape. Major players like OptaSense, Fotech Solutions, AP Sensing, and Silixa hold substantial market shares due to their advanced product offerings and extensive industry experience. These companies lead in innovation, offering cutting-edge DAS solutions that incorporate AI and machine learning for enhanced data analytics and predictive maintenance. The market is characterized by high technological specialization, with a focus on continuous research and development to improve the sensitivity, accuracy, and integration of DAS systems. The competitive environment encourages strategic partnerships, acquisitions, and collaborations to expand product offerings and strengthen regional presence. While the market is primarily driven by large enterprises, there is also room for niche players to cater to specific industry needs, such as transportation, utilities, and defense. This fosters a dynamic and evolving market structure.
Report Coverage:
The research report offers an in-depth analysis based on Fiber Type, Application and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. Distributed Acoustic Sensing market is poised for continued growth, driven by rising demand for real-time monitoring solutions.
- The integration of AI and machine learning will significantly enhance the capabilities of DAS systems, improving anomaly detection and predictive maintenance.
- The oil and gas industry will continue to be a key adopter of DAS technology, particularly for pipeline monitoring and leak detection.
- The telecommunications sector will increasingly rely on DAS to protect fiber optic networks and ensure network reliability.
- The expansion of renewable energy projects, such as wind and solar farms, will create new opportunities for DAS in monitoring remote infrastructure.
- Cloud-based DAS solutions will become more popular, offering scalable, cost-effective, and remote monitoring options.
- Border security and transportation applications will drive growth in DAS adoption as security and infrastructure surveillance become more critical.
- Evolving data privacy and security regulations will influence DAS deployment strategies and market dynamics.
- A growing focus on predictive analytics will spur demand for DAS systems that provide proactive monitoring and early fault detection.
- The market is expected to see increased fragmentation as specialized players emerge to meet the unique needs of different industries and applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Distributed Acoustic Sensing Market?
What factors are driving the growth of the U.S. Distributed Acoustic Sensing Market?
What are some challenges faced by the U.S. Distributed Acoustic Sensing Market?
Who are the major players in the U.S. Distributed Acoustic Sensing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Distributed Acoustic Sensing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Distributed Acoustic Sensing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 186.63 million → 2032: USD 469.52 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Distributed Acoustic Sensing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Distributed Acoustic Sensing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Distributed Acoustic Sensing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Distributed Acoustic Sensing Market Drivers
- 3.3 U.S. Distributed Acoustic Sensing Market Restraints & Challenges
- 3.4 U.S. Distributed Acoustic Sensing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Distributed Acoustic Sensing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Distributed Acoustic Sensing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Distributed Acoustic Sensing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Distributed Acoustic Sensing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Distributed Acoustic Sensing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Distributed Acoustic Sensing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Distributed Acoustic Sensing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Distributed Acoustic Sensing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Distributed Acoustic Sensing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Distributed Acoustic Sensing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Distributed Acoustic Sensing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Distributed Acoustic Sensing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Distributed Acoustic Sensing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Distributed Acoustic Sensing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Distributed Acoustic Sensing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Distributed Acoustic Sensing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Distributed Acoustic Sensing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Distributed Acoustic Sensing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Distributed Acoustic Sensing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
