
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Vaccine Technologies Market Size 2024 | USD 45,405 Million |
| Vaccine Technologies Market, CAGR | 11% |
| Vaccine Technologies Market Size 2032 | USD 104,636.38 Million |
Market Overview
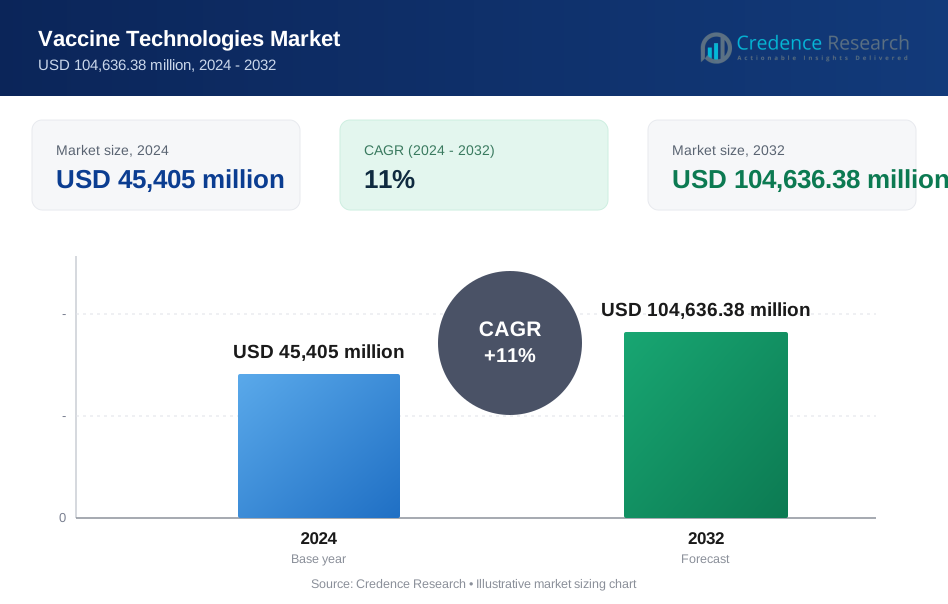
The Vaccine Technologies Market is projected to grow from USD 45,405 million in 2024 to USD 104,636.38 million by 2032, at a compound annual growth rate (CAGR) of 11%.
The vaccine technologies market is driven by advancements in biotechnology, increasing demand for immunization due to rising prevalence of infectious diseases, and growing government investments in healthcare infrastructure. Technological innovations such as mRNA vaccines and improved vaccine delivery systems are fueling market growth. Additionally, heightened awareness of preventive healthcare and the global push for pandemic preparedness further accelerate adoption. The expansion of vaccination programs in emerging economies and strategic collaborations between pharmaceutical companies are key trends shaping the market, ensuring a sustained increase in research and development activities to meet evolving healthcare needs.
The Vaccine Technologies market is driven by significant contributions from key players across various regions. Pfizer Inc. (US), Serum Institute of India Pvt Ltd (India), and Bharat Biotech (India) lead advancements in Asia and the US, while GSK plc (UK), AstraZeneca (UK), and Sanofi (France) dominate in Europe. Inovio Pharmaceuticals (US) and Novavax (US) play a vital role in North American innovations, alongside Mitsubishi Tanabe Pharma Corporation (Japan) in Asia-Pacific. Sinovac (China) is prominent in China’s vaccine landscape, positioning the region as a key player in vaccine distribution and development globally.
Market Drivers
Increasing Prevalence of Infectious Diseases
he emergence of new pathogens such as SARS-CoV-2 (COVID-19) and the Zika virus has underscored the need for rapid vaccine development. These emerging diseases highlight the critical role vaccines play in controlling global health crises. For instance, the Centers for Disease Control and Prevention (CDC) reported that the number of new tuberculosis cases in the U.S. was 8,916 in 2019. Additionally, resurgent diseases like measles and pertussis are making a comeback in certain regions, largely due to declining vaccination rates. This resurgence amplifies the demand for robust immunization efforts and effective vaccine technologies to mitigate the spread of these once-contained diseases.
Rising Awareness of Immunization Benefits
Public health campaigns led by governments and healthcare organizations are driving greater awareness of the benefits of immunization. These campaigns emphasize the importance of vaccination in preventing diseases and safeguarding public health. For instance, the World Health Organization (WHO) states that immunization currently prevents 3.5 million to 5 million deaths every year from diseases like diphtheria, tetanus, pertussis, influenza, and measles. Social media platforms like Twitter and Facebook have become key tools in disseminating accurate information about vaccines, helping to counteract misinformation. This increased visibility is encouraging higher vaccination rates, contributing to the overall growth of the vaccine technologies market.
Advancements in Vaccine Technology
Recent advancements in vaccine technology, particularly the success of mRNA vaccines during the COVID-19 pandemic, have transformed the landscape of vaccine development. mRNA vaccines offer rapid development timelines and the ability to customize vaccines to target specific pathogens. Additionally, innovations in nanotechnology are enhancing vaccine delivery systems, improving efficacy, and reducing the potential for side effects. These technological breakthroughs are accelerating the pace of vaccine research and expanding the range of diseases that can be effectively targeted.
Government Support and Global Health Initiatives
Governments worldwide are investing heavily in immunization programs to ensure widespread access to vaccines, especially in lower-income regions. Funding for research and development is also on the rise, supporting the exploration of new vaccine platforms and technologies. Global health initiatives, such as those led by the World Health Organization (WHO) and the Global Alliance for Vaccines and Immunization (GAVI), play an instrumental role in coordinating international vaccination efforts and providing financial assistance to ensure equitable access to vaccines across the globe.
Market Trends
Advancements in Vaccine Technology and Personalized Vaccines
Recent technological advancements have revolutionized vaccine development and delivery. The success of mRNA vaccines during the COVID-19 pandemic has significantly boosted interest in their application for other diseases, as they offer rapid development and customization to address emerging health threats. For instance, the Coalition for Epidemic Preparedness Innovations (CEPI) launched a call for proposals seeking innovative RNA platforms that could offer improvements over existing mRNA vaccine technology. Recombinant vaccines, produced using genetically engineered organisms, present a safer and more efficient alternative to traditional vaccines, reducing the risks associated with live attenuated viruses. Additionally, nanotechnology is being incorporated to improve vaccine stability, delivery, and efficacy, enhancing the overall performance of immunization efforts. Digital health integration is further reshaping the vaccine landscape, with platforms being utilized to track vaccination records, manage supply chains, and streamline vaccine education, improving overall efficiency in immunization programs.
Global Health Initiatives and Consumer-Centric Approaches
Global health initiatives continue to play a pivotal role in expanding vaccine access and improving health outcomes in low-income countries. Organizations like the World Health Organization (WHO) and the Global Alliance for Vaccines and Immunization (GAVI) are working to enhance vaccine distribution through partnerships, funding, and improved supply chain management. For instance, the COVID-19 Vaccine Delivery Partnership, a collective international effort, focuses on 34 low coverage countries to accelerate COVID-19 vaccination. These efforts are crucial for combating vaccine inequality and preventing the spread of infectious diseases in underprivileged regions. Additionally, vaccines remain a cornerstone of global efforts to eradicate diseases like polio and measles, highlighting their ongoing importance in achieving worldwide public health goals.
Market Challenges Analysis
Vaccine Hesitancy, Misinformation, and Regulatory Hurdles
Vaccine hesitancy has emerged as a significant market challenge, largely fueled by the spread of misinformation and conspiracy theories propagated by the anti-vaccine movement. Social media platforms such as Facebook and Twitter have become breeding grounds for the dissemination of false information about vaccine safety and efficacy, which undermines public trust and causes a resurgence of hesitancy in various regions. For instance, a survey by the Kaiser Family Foundation found that a significant portion of adults are either taking a “wait and see” approach to vaccinations or already plan to not get vaccinated. Combatting this misinformation is an ongoing struggle for healthcare authorities and governments, who must work diligently to promote accurate information about vaccines to restore public confidence.
Supply Chain Issues, Cost, and Emerging Threats
Supply chain issues, particularly around manufacturing capacity and cold chain management, pose serious challenges in meeting global vaccine demand. Manufacturing capacity is often strained during pandemics or public health crises, as seen during the COVID-19 pandemic, where global demand for vaccines far exceeded available production. For instance, the U.S. Government Accountability Office (GAO) reported that the federal response to the COVID-19 pandemic highlighted critical gaps in the medical supply chain. Ensuring that manufacturing facilities are adequately equipped to scale up production quickly is crucial for maintaining vaccine supply. Moreover, cold chain management, which involves maintaining the required temperatures for vaccine storage and transportation, is essential for preserving vaccine efficacy. For instance, the WHO emphasized that inadequate storage, transportation, and personnel capacity led to major bottlenecks and the discarding of many vaccine doses. This is particularly difficult in regions with limited infrastructure, where lapses in cold chain management can result in wasted vaccines and delayed immunization efforts.
Market Segmentation Analysis:
By Technology:
The vaccine technologies market is segmented by technology and type, each contributing uniquely to the overall growth. By technology, conjugate vaccines, recombinant vaccines, inactivated and subunit vaccines, live attenuated vaccines, toxoid vaccines, and other vaccine technologies are the primary categories. Conjugate vaccines, which combine antigens with proteins to improve immune response, are widely used in preventing bacterial infections, while recombinant vaccines, produced using genetic engineering, offer a safer and more efficient alternative to traditional vaccines. Inactivated and subunit vaccines, utilizing killed or protein-based components of pathogens, are favored for their safety profile. Live attenuated vaccines, made from weakened pathogens, provide long-lasting immunity but may pose risks for immunocompromised individuals. Toxoid vaccines target diseases caused by bacterial toxins, such as tetanus and diphtheria.
By Type:
The market is divided into monovalent and multivalent vaccines. Monovalent vaccines target a single pathogen or strain, offering focused immunization, while multivalent vaccines protect against multiple diseases or strains in a single dose, simplifying immunization schedules and increasing adherence. Both types play critical roles in enhancing immunization coverage across different population segments.
Segments:
Based on Technology
- Conjugate Vaccines
- Recombinant Vaccines
- Inactivated and Subunit Vaccines
- Live Attenuated Vaccines
- Toxoid Vaccines
- Other Vaccine Technologies
Based on Type
- Monovalent Vaccines
- Mulitvalent Vaccines
Based on Disease Indication
- Pneumococcal Disease
- Influenza
- Combination Vaccines
- HPV
- Meningococcal Disease
- Herpes Zoster
- Rotavirus
- MMR
- Varicella
- Hepatitis
- DTP
- Polio
- RSV
- Other Disease Indications
Based on Route of Administration
- Intramuscular & Subcutaneous
- Oral
- Other Route of Administration
Based on End User
- Pediatric Vaccine
- Adult Vaccine
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share, accounting for over 35% of the global vaccine technologies market. This dominance is driven by the region’s advanced healthcare infrastructure, cutting-edge research and development (R&D) capabilities, and strong governmental support. The U.S. plays a central role, with major pharmaceutical and biotech firms investing heavily in new vaccine technologies like mRNA and recombinant vaccines. For instance, the U.S. government invested at least $31.9 billion to develop, produce, and purchase mRNA COVID-19 vaccines, including sizeable investments in the three decades before the pandemic through March 2022. In addition, government initiatives such as Operation Warp Speed, which fast-tracked COVID-19 vaccine development, further solidified North America's leadership in the global market. The region’s strong focus on immunization programs and personalized vaccines is expected to sustain its position in the coming years.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the vaccine technologies market, currently holding a market share of around 25%. The region’s growth is fueled by increasing government investments in healthcare, expanding immunization programs, and rising awareness of vaccine benefits. Countries such as China and India are driving demand due to their large populations and growing healthcare infrastructure. Furthermore, local manufacturing capabilities are being enhanced through government support and partnerships with global pharmaceutical companies. With an increasing focus on affordable and accessible vaccines for lower-income populations, Asia-Pacific is poised to increase its market share significantly in the near future.
Key Player Analysis
- Pfizer Inc (US)
- Serum Institute of India Pvt Ltd (India)
- Sanofi (France)
- AstraZeneca (UK)
- Mitsubishi Tanabe Pharma Corporation (Japan)
- Inovio Pharmaceuticals (US)
- GSK plc (UK)
- Sinovac (China)
- Bharat Biotech (India)
- Novavax (US)
- VBI Vaccines Inc.
Competitive Analysis
The Vaccine Technologies market is highly competitive, characterized by rapid advancements and strategic positioning among key players such as Pfizer Inc., Serum Institute of India Pvt Ltd, Sanofi, AstraZeneca, Mitsubishi Tanabe Pharma Corporation, Inovio Pharmaceuticals, GSK plc, Sinovac, Bharat Biotech, and Novavax. Leading firms are focusing on advanced technologies, such as mRNA and viral vector platforms, which gained significant traction during the COVID-19 pandemic, setting new benchmarks in vaccine development. The emphasis on research and development is critical, as companies aim to improve vaccine efficacy, safety, and accessibility. Strategic collaborations and partnerships are increasingly common, allowing firms to combine expertise and resources to expedite the development process. The emergence of novel players alongside established companies is reshaping the market, intensifying competition and driving continuous advancements. Regulatory frameworks and public health demands further influence the landscape, compelling companies to remain agile and responsive. This dynamic environment fosters innovation and ultimately enhances global public health efforts by improving vaccine availability and effectiveness.
Recent Developments
- In April 2024, VBI Vaccines Inc. expanded its stratergic collaboration with government of Canada to accelerate development proprietary MLE platform, enveloped virus-like particle vaccine technology that enables the coding of eVLPs using mRNA.
- In April 2024, Bharat Biotech and Bilthoven Biologicals B.V. entered into a collaboration to produce and supply oral polio vaccines.
- In January 2024, Indian Immunologicals Ltd (IIL), launched India’s ‘first’ indigenously developed Hepatitis A vaccine, Havisure.
- In August 2023, Pfizer Inc., received US FDA approval for ABRYSVO (Respiratory Syncytial Virus Vaccine) for the prevention of LRTD and severe LRTD caused by RSV in infants from birth up to six months of age by active immunization of pregnant individuals at 32 through 36 weeks gestational age.
- In May 2023, GSK plc, received US FDA approval for Arexvy (respiratory syncytial virus vaccine, adjuvanted) for the prevention of lower respiratory tract disease (LRTD) caused by respiratory syncytial virus (RSV) in individuals 60 years of age and older.
Market Concentration & Characteristics
The Vaccine Technologies market exhibits moderate to high market concentration, driven by a few dominant players that significantly influence pricing and innovation. Established companies invest heavily in research and development, leading to advanced technologies such as mRNA and viral vector vaccines. This concentration allows for rapid advancements, particularly in response to public health crises like the COVID-19 pandemic. However, the market also features a growing number of smaller firms and startups that introduce novel technologies and approaches, contributing to a diverse landscape. Key characteristics include a strong emphasis on regulatory compliance, as companies must navigate complex approval processes to ensure safety and efficacy. Additionally, partnerships and collaborations between industry leaders and academic institutions are common, fostering innovation and accelerating product development. Overall, the Vaccine Technologies market is dynamic, characterized by a blend of established expertise and emerging innovation, ultimately enhancing global healthcare outcomes.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type, Disease Indication, Route of Administration, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Vaccine Technologies market will continue to evolve, driven by advancements in biotechnology and increased investment in research and development.
- mRNA technology is expected to gain further prominence, paving the way for rapid vaccine development against emerging pathogens.
- Personalized vaccines will emerge as a significant trend, tailoring immunizations to individual genetic profiles and health needs.
- Increased collaboration between pharmaceutical companies and biotechnology firms will foster innovation and expedite product development timelines.
- Global health initiatives will prioritize equitable access to vaccines, promoting the development of affordable and accessible solutions.
- The market will likely see an increase in combination vaccines, offering broader protection against multiple diseases in a single dose.
- Enhanced focus on vaccine delivery systems, including microneedles and oral vaccines, will improve patient compliance and ease of administration.
- Continued surveillance and rapid response mechanisms will be essential for addressing future pandemics and vaccine-preventable diseases.
- Regulatory agencies will adapt to the fast-paced nature of vaccine development, streamlining approval processes while maintaining safety standards.
- The integration of digital health technologies will facilitate better monitoring of vaccination programs and patient engagement strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Infectious Diseases
The emergence and resurgence of infectious diseases such as COVID-19, tuberculosis, and measles have highlighted the urgent need for rapid vaccine development and robust immunization programs, directly fueling demand for advanced vaccine technologies.
Advancements in Vaccine Technology
Breakthroughs such as mRNA vaccines, recombinant platforms, and nanotechnology-enhanced delivery systems have accelerated vaccine development timelines, improved efficacy, and expanded the range of preventable diseases, making vaccine technologies more attractive to healthcare providers and governments.
Rising Awareness of Immunization Benefits
Public health campaigns and global initiatives have increased awareness of the life-saving benefits of vaccines, leading to higher vaccination rates and greater acceptance of new vaccine technologies, especially in emerging economies.
Government Support and Global Health Initiatives
Significant investments by governments and organizations like WHO and GAVI in immunization infrastructure, R&D, and equitable vaccine access are driving market growth by supporting innovation and expanding vaccination coverage worldwide.
Expansion of Vaccination Programs in Emerging Markets
Growing healthcare infrastructure and government-backed immunization initiatives in countries such as China and India are increasing vaccine uptake, boosting demand for both established and next-generation vaccine technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vaccine Technologies market?
What factors are driving the growth of the Vaccine Technologies market?
What are the key segments within the Vaccine Technologies market?
What are some challenges faced by the Vaccine Technologies market?
Who are the major players in the Vaccine Technologies market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Monovalent Vaccines
- 1.2.2 Multivalent Vaccines
- 1.3 By Technology
- 1.3.1 Conjugate Vaccines
- 1.3.2 Recombinant Vaccines
- 1.3.3 Inactivated and Subunit Vaccines
- 1.3.4 Live Attenuated Vaccines
- 1.3.5 Toxoid Vaccines
- 1.3.6 Other Vaccine Technologies
- 1.4 By Disease Indication
- 1.4.1 Pneumococcal Disease
- 1.4.2 Influenza
- 1.4.3 HPV
- 1.4.4 Meningococcal Disease
- 1.4.5 Hepatitis
- 1.4.6 Other Disease Indications
- 1.5 By Route of Administration
- 1.5.1 Intramuscular & Subcutaneous
- 1.5.2 Oral
- 1.5.3 Other Route of Administration
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 45,405 million → 2032: USD 104,636.38 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vaccine Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vaccine Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vaccine Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vaccine Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vaccine Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vaccine Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vaccine Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vaccine Technologies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 45,405 million → 2032: USD 104,636.38 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vaccine Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Monovalent Vaccines
- 12.3.7.2 Multivalent Vaccines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conjugate Vaccines
- 12.4.7.2 Recombinant Vaccines
- 12.4.7.3 Inactivated and Subunit Vaccines
- 12.4.7.4 Live Attenuated Vaccines
- 12.4.7.5 Toxoid Vaccines
- 12.4.7.6 Other Vaccine Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Disease Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pneumococcal Disease
- 12.5.7.2 Influenza
- 12.5.7.3 HPV
- 12.5.7.4 Meningococcal Disease
- 12.5.7.5 Hepatitis
- 12.5.7.6 Other Disease Indications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Intramuscular & Subcutaneous
- 12.6.7.2 Oral
- 12.6.7.3 Other Route of Administration
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vaccine Technologies Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Vaccine Technologies Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Vaccine Technologies Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer Inc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Serum Institute of India Pvt Ltd
- 17.4 Sanofi
- 17.5 AstraZeneca
- 17.6 Mitsubishi Tanabe Pharma Corporation
- 17.7 Inovio Pharmaceuticals
- 17.8 GSK plc
- 17.9 Sinovac
- 17.10 Bharat Biotech
- 17.11 Novavax
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

