
Market Overview
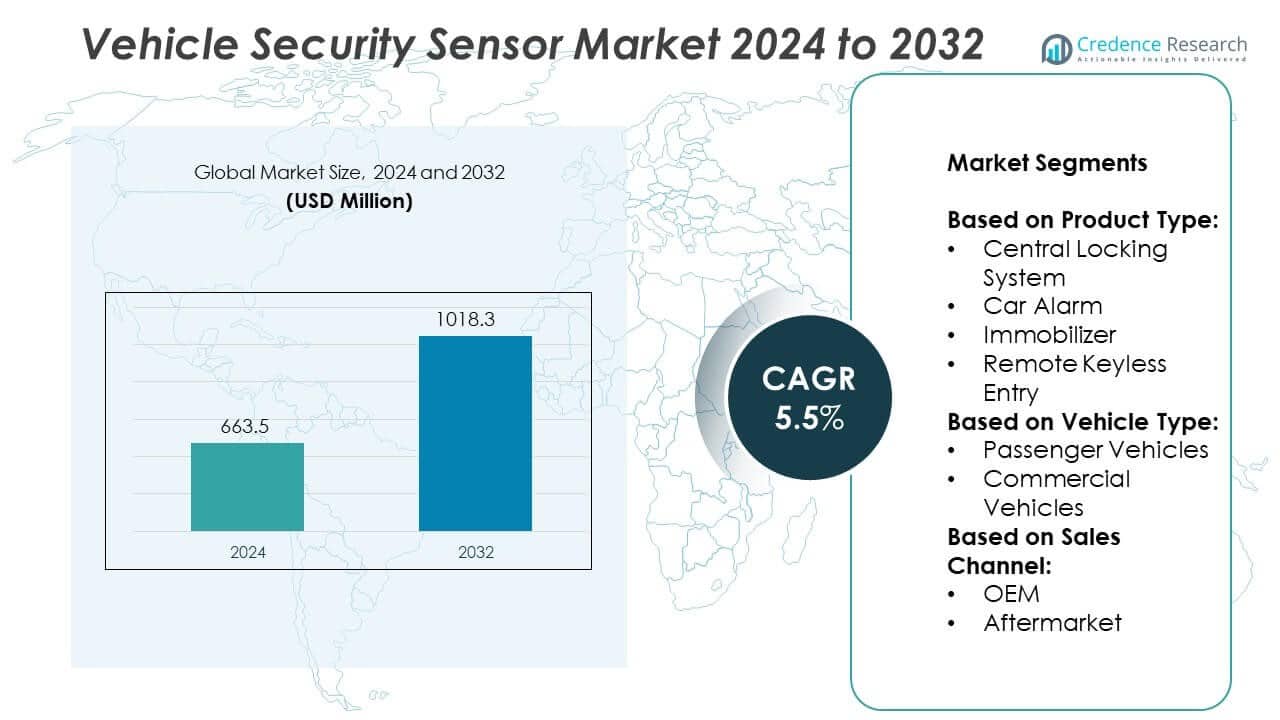
Vehicle Security Sensor Market size was valued at USD 663.5 million in 2024 and is anticipated to reach USD 1018.3 million by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vehicle Security Sensor Market Size 2024 | USD 663.5 Million |
| Vehicle Security Sensor Market, CAGR | 5.5% |
| Vehicle Security Sensor Market Size 2032 | USD 1018.3 Million |
The Vehicle Security Sensor market grows on the back of rising vehicle theft incidents, increasing consumer awareness, and demand for integrated safety features in both passenger and commercial vehicles. Automakers adopt advanced sensors such as immobilizers, motion detectors, and keyless entry systems to meet evolving security expectations. The market also benefits from technological trends including AI-driven threat detection, IoT-based remote monitoring, and biometric access systems. These innovations enhance real-time responsiveness, enable predictive alerts, and support seamless user control.
The Vehicle Security Sensor market shows strong regional presence across North America, Europe, and Asia-Pacific, supported by high automotive production, rising theft concerns, and growing adoption of smart vehicle technologies. North America leads in advanced security integration, while Europe focuses on regulatory compliance and OEM innovation. Asia-Pacific sees rapid growth driven by expanding vehicle ownership and smart mobility initiatives in countries like China and India. Key players shaping this market include Infineon Technologies AG, NXP Semiconductors N.V., and Allegro MicroSystems, Inc., known for their sensor innovations and collaborations with global automakers to enhance vehicle security capabilities.
Market Insights
- The Vehicle Security Sensor market was valued at USD 663.5 million in 2024 and is expected to reach USD 1018.3 million by 2032, growing at a CAGR of 5.5% during the forecast period.
- Rising vehicle theft cases and increasing awareness of in-vehicle security drive the demand for advanced sensors, especially in urban and high-risk regions.
- Integration of IoT, AI, and biometric technologies in modern vehicles is reshaping security systems, enabling real-time alerts, predictive threat detection, and remote access features.
- Companies like Infineon Technologies AG, NXP Semiconductors N.V., and Allegro MicroSystems, Inc. lead the competitive landscape with strong OEM partnerships and sensor innovations.
- High cost of advanced security sensors and challenges in integrating these systems into entry-level vehicles restrict widespread adoption in developing markets.
- North America leads in adoption due to advanced infrastructure and strong OEM presence, while Asia-Pacific shows the fastest growth with rising automotive production and smart vehicle demand.
- The market continues to evolve with growing investment in fleet protection, aftermarket sensor solutions, and vehicle cybersecurity integration to meet emerging safety standards globally.
Market Drivers
Rising Global Vehicle Theft Incidents Fueling Demand for Advanced Security Solutions
The growing incidence of vehicle theft globally drives demand for robust in-vehicle security systems. Increasing awareness among consumers about the vulnerabilities of standard locking mechanisms pushes adoption of advanced sensor-based deterrents. Manufacturers integrate features like ultrasonic sensors, tilt sensors, and motion detectors to strengthen vehicle protection. Insurance companies also promote installation of these systems by offering lower premiums. Governments in several countries mandate the use of anti-theft technologies, further supporting growth. The Vehicle Security Sensor market benefits from this trend by offering layered protection mechanisms that improve theft prevention across personal and commercial vehicles.
- For instance, Avital Inc. reported over 3 million installations of its advanced vehicle alarm systems with integrated tilt and motion sensors across North America.
Increasing Production and Sales of Passenger and Commercial Vehicles Globally
The steady growth in global vehicle production directly influences demand for factory-installed security systems. Automakers equip new vehicles with advanced sensors to comply with rising consumer expectations and competitive benchmarks. Security sensors now form a standard part of vehicle electronics in premium and mid-range segments. It increases system volume sales across original equipment manufacturers (OEMs). Rising urbanization and improving road infrastructure support this expansion in developing economies. The Vehicle Security Sensor market gains traction as a core component of modern automotive design across both light and heavy-duty vehicle classes.
- For instance, NXP Semiconductors N.V. supplied over 150 million automotive transponder ICs used in immobilizer systems for global OEMs in one year.
Technological Advancements in Sensor Capabilities and Smart Integration
Rapid innovation in sensor technologies enhances performance, accuracy, and reliability in security applications. Miniaturization, wireless connectivity, and AI-based threat detection allow sensors to operate seamlessly within complex automotive networks. Integration with GPS, telematics, and mobile apps improves responsiveness and user control. It strengthens real-time alerts and remote diagnostics, which align with smart mobility trends. Automakers increasingly collaborate with sensor manufacturers to embed advanced safety layers into vehicle architecture. The Vehicle Security Sensor market benefits from these developments that elevate the intelligence and adaptability of automotive security systems.
Growing Consumer Preference for Connected and Smart Vehicle Features
Shifting consumer expectations toward connected vehicle experiences influences sensor adoption. Buyers increasingly seek enhanced safety features, including real-time threat detection and mobile-controlled locking systems. Automakers integrate security sensors with infotainment systems, IoT platforms, and voice-activated controls. It enables a seamless user interface and builds trust in safety technologies. Connected features also support fleet management, enabling remote monitoring and theft recovery. The Vehicle Security Sensor market aligns with these consumer preferences by delivering embedded security capabilities that extend beyond conventional alarm systems.
Market Trends
Integration of IoT and Telematics for Real-Time Security Monitoring
The integration of IoT and telematics platforms into vehicle security systems is reshaping how threats are detected and addressed. Manufacturers embed sensors with real-time communication features, enabling instant alerts via mobile devices and cloud-based platforms. This trend supports remote locking, location tracking, and tamper detection. It increases end-user control and reduces the risk of theft through proactive threat identification. Automakers collaborate with connectivity providers to embed these features into factory systems. The Vehicle Security Sensor market reflects this shift through growing demand for intelligent, networked security modules.
- For instance, Analog Devices, Inc. introduced automotive-grade inertial sensors with sub-0.1°/s noise density, enabling precise motion detection in anti-theft systems.
Rising Popularity of Biometric and Keyless Entry Systems
Consumers increasingly adopt biometric authentication and keyless entry solutions in premium and mid-range vehicles. Fingerprint, facial recognition, and voice-activated systems enhance access control while offering a seamless user experience. These systems require advanced security sensors to validate identity and detect unauthorized access attempts. It expands the scope of sensor functionality beyond conventional perimeter defense. Automakers prioritize such integrations to align with evolving expectations around personalization and convenience. The Vehicle Security Sensor market responds by adapting sensors for multimodal authentication environments.
- For instance, Firstech LLC’s DroneMobile platform connects with over 800,000 Compustar alarm and GPS units to deliver mobile security alerts.
Emphasis on Multi-Layered Security Architecture in Electric Vehicles (EVs)
The growth of electric vehicles introduces unique challenges that demand enhanced sensor-based protection. EVs often store high-value batteries and advanced electronics, making them attractive targets for tampering and theft. Security sensors are now critical to protecting both physical components and software systems. It includes monitoring for battery compartment breaches, cable tampering, and software intrusion attempts. Manufacturers implement layered sensor arrays to protect high-voltage zones and ensure safety compliance. The Vehicle Security Sensor market adapts to this requirement by expanding its role in EV-specific architecture.
Expansion of Aftermarket Solutions for Older and Budget Vehicles
Demand for affordable retrofit security solutions is rising among owners of older vehicle models. Aftermarket suppliers offer modular sensor kits that integrate with basic locking systems and mobile apps. These kits often include motion detectors, glass-break sensors, and tilt sensors. It allows consumers to enhance vehicle safety without purchasing a new model. Increasing availability through e-commerce and retail networks accelerates adoption across emerging markets. The Vehicle Security Sensor market finds new growth potential in this expanding aftermarket segment.
Market Challenges Analysis
High Cost and Complexity of Advanced Sensor Integration in Entry-Level Vehicles
The high cost of integrating advanced security sensors poses a barrier for mass adoption, particularly in entry-level vehicle segments. Manufacturers face difficulties balancing affordability with the inclusion of premium sensor technologies. Complex sensor systems often require specialized electronic control units, software interfaces, and robust calibration protocols. It increases development time and manufacturing cost, impacting the price competitiveness of budget vehicles. Smaller OEMs and Tier-2 suppliers struggle with the investment required to develop and support these solutions. The Vehicle Security Sensor market experiences slower growth in cost-sensitive regions where affordability outweighs feature richness.
Susceptibility to Cybersecurity Threats and System Tampering
Growing connectivity and software-based control systems introduce cybersecurity vulnerabilities in sensor-based security modules. Hackers exploit weak communication protocols or outdated firmware to disable alarms or bypass access restrictions. It reduces the reliability of even sophisticated vehicle security frameworks. Manufacturers must invest in secure coding practices, regular over-the-air updates, and encryption layers to mitigate risks. These requirements place pressure on engineering teams and increase the operational burden on OEMs and suppliers. Ensuring end-to-end protection across sensor hardware and digital interfaces remains a persistent challenge for the industry.
Market Opportunities
Growing Demand for Smart Mobility and Fleet Management Solutions
The rapid expansion of shared mobility, ride-hailing, and logistics fleets creates new opportunities for sensor-driven vehicle security systems. Fleet operators prioritize asset protection, real-time tracking, and driver behavior monitoring to improve operational efficiency. Security sensors integrated with telematics platforms support centralized control, route surveillance, and theft deterrence. It allows businesses to reduce downtime and ensure vehicle integrity across large-scale operations. OEMs and technology providers collaborate to offer bundled security packages tailored for fleet applications. The Vehicle Security Sensor market leverages this demand to expand its presence in commercial mobility ecosystems.
Adoption of AI-Enabled Threat Detection and Predictive Maintenance
Artificial intelligence enhances the capabilities of vehicle security sensors through advanced pattern recognition and threat prediction. AI-enabled systems analyze behavioral data to detect anomalies, unauthorized access attempts, or sensor malfunctions. It supports proactive maintenance, early alert generation, and better response coordination during security breaches. Manufacturers incorporate AI modules into security architecture to differentiate their offerings and strengthen customer value. This trend fosters innovation in sensor software, data analytics, and embedded intelligence. The Vehicle Security Sensor market finds growth potential in AI-driven solutions that elevate security beyond passive monitoring.
Market Segmentation Analysis:
By Product Type:
Central locking systems dominate the market due to their widespread adoption across vehicle categories and ease of integration with other security modules. These systems offer basic protection and user convenience, forming a standard feature in most modern vehicles. Car alarms hold a significant share owing to their strong deterrent effect and low cost, particularly in aftermarket applications. Immobilizers gain traction due to their ability to prevent unauthorized ignition, making them essential in theft-prone regions. Remote keyless entry systems continue to expand with rising demand for contactless access, especially in premium and mid-range passenger vehicles. The Vehicle Security Sensor market benefits from this product diversity by catering to varying protection needs across consumer and commercial segments.
- For instance, Fortin Electronic Systems developed the EVO-START platform, now deployed in over 200,000 connected vehicles, offering real-time control and alerts.
By Vehicle Type:
Passenger vehicles account for the majority share driven by high production volume and consumer focus on safety and convenience. Rising urbanization, disposable income, and vehicle ownership rates strengthen this trend in both developed and emerging economies. Commercial vehicles follow with growing demand for fleet security and asset protection, particularly in logistics, ride-hailing, and public transport sectors. It supports adoption of advanced sensors linked to centralized monitoring and telematics platforms. Both segments increasingly rely on multi-layered sensor integration to prevent theft and ensure driver accountability.
- For instance, Infineon Technologies AG delivered over 90 million security microcontrollers used in EV battery management and intrusion detection systems.
By Sales Channel:
OEMs lead due to built-in security solutions offered at the manufacturing stage, often embedded into vehicle design and electronics. Automakers collaborate with sensor manufacturers to ensure compliance with safety standards and consumer expectations. The aftermarket channel grows steadily with rising demand for retrofitting solutions in older vehicles. It addresses budget-conscious buyers and regions with high vehicle theft rates. The Vehicle Security Sensor market expands its reach through this dual-channel approach, enhancing accessibility and long-term product lifecycle.
Segments:
Based on Product Type:
- Central Locking System
- Car Alarm
- Immobilizer
- Remote Keyless Entry
Based on Vehicle Type:
- Passenger Vehicles
- Commercial Vehicles
Based on Sales Channel:
- OEM
- Aftermarket
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for the largest share in the Vehicle Security Sensor market, contributing 32.4% of the global revenue in 2024. The region maintains a mature automotive ecosystem with high adoption of advanced safety and security technologies. The presence of leading automakers and technology innovators such as General Motors, Ford, and Tesla ensures strong demand for sensor-based vehicle protection systems. Growing concerns over vehicle theft, particularly in urban centers, fuel investment in immobilizers, remote keyless entry systems, and biometric access controls. Insurance firms in the United States incentivize owners to install certified security features, further pushing sensor adoption. Canada follows a similar trajectory, with rising consumer awareness and a regulatory framework that supports vehicular safety advancements. The aftermarket segment in North America also contributes significantly due to the large volume of aging vehicles and high-value automotive assets requiring retrofit solutions.
Europe
Europe holds the second-largest share of the Vehicle Security Sensor market, representing 27.8% in 2024. The region benefits from a strong regulatory environment, including mandates on anti-theft devices in new vehicles under European Union directives. Germany, France, and the United Kingdom lead adoption through their robust automotive manufacturing bases and premium vehicle exports. European consumers prioritize vehicle safety and are early adopters of keyless entry, alarm systems, and smart immobilizers. Automakers such as BMW, Mercedes-Benz, and Volkswagen incorporate integrated sensor systems as part of their standard offerings. It drives growth in both OEM and aftermarket channels. The push for electrification and connected vehicles in Europe also opens opportunities for cybersecurity-enhanced sensor systems that protect both hardware and digital assets.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the Vehicle Security Sensor market and currently holds a 22.1% market share in 2024. The region benefits from the expanding automotive production in countries like China, India, Japan, and South Korea. Rising vehicle ownership, urban congestion, and theft incidents in densely populated areas increase the need for reliable in-vehicle security. China dominates with rapid integration of smart vehicle technologies and government-backed efforts to improve road safety. Japan and South Korea contribute with strong technological capabilities and innovation in automotive electronics. India sees rising demand in the mid-range segment, driven by affordability and awareness campaigns. The market in Asia-Pacific grows due to a combination of domestic consumption and export-focused vehicle manufacturing, supported by improving infrastructure and rising income levels.
Latin America
Latin America contributes 9.1% to the global Vehicle Security Sensor market in 2024. High vehicle theft rates, particularly in Brazil, Mexico, and Argentina, create strong demand for basic and advanced vehicle protection systems. Consumers in the region prioritize cost-effective security options such as central locking and entry-level alarms. OEM presence is growing, though the aftermarket dominates due to a high number of used and imported vehicles. Governments and insurers support theft prevention initiatives, influencing market penetration of sensors. Despite economic volatility, the region presents opportunities in large urban markets where demand for secure transportation is rising.
Middle East & Africa
The Middle East & Africa holds a relatively smaller share of 8.6% in the Vehicle Security Sensor market in 2024. The market remains in the early stages of development but shows signs of steady growth due to rising vehicle ownership and luxury vehicle imports, particularly in Gulf countries. UAE and Saudi Arabia lead adoption due to consumer preference for high-end vehicles equipped with integrated security systems. In Africa, demand grows gradually with the expansion of transportation infrastructure and rising security concerns in urban centers. The region relies more on the aftermarket due to lower penetration of OEM-installed systems. It represents a long-term growth opportunity as governments prioritize vehicle safety and smart mobility solutions.
Key Player Analysis
- Clifford Inc.
- Infineon Technologies AG
- Avital Inc.
- Allegro MicroSystems, Inc.
- NXP Semiconductors N.V.
- Fortin Electronic Systems
- TDK Corporation
- Firstech, LLC (Compustar)
- Amphenol Corporation
- Analog Devices, Inc.
Competitive Analysis
The Vehicle Security Sensor market features strong competition driven by technology innovation, strategic collaborations, and OEM integration. Key players include Infineon Technologies AG, NXP Semiconductors N.V., Allegro MicroSystems, Inc., Analog Devices, Inc., Amphenol Corporation, and TDK Corporation.These companies focus on enhancing sensor accuracy, reliability, and miniaturization to meet growing demand for intelligent security systems. Leading firms invest in R&D to develop solutions compatible with keyless entry, immobilizers, and biometric access control. They also form strategic partnerships with automakers to integrate sensors at the design level, ensuring long-term supply agreements. Several players expand their product lines to include AI-enabled threat detection and real-time monitoring capabilities.The competitive landscape is marked by constant upgrades in sensor interface protocols, cybersecurity features, and compliance with global automotive safety standards. Mergers, acquisitions, and technology licensing are common approaches used to strengthen product portfolios and expand geographic reach. Market leaders maintain strong distribution networks and capitalize on the rising demand for both OEM and aftermarket applications. New entrants face high barriers due to the complexity of automotive safety certifications and the dominance of established sensor suppliers. Competitive advantage hinges on technical expertise, innovation speed, and deep integration into automotive manufacturing ecosystems.
Recent Developments
- In May, 2025, Denso Corporation (Japan) confirmed the expansion of its blind-spot detection systems with integrated anti-intrusion alerts and remote security notifications, focusing on the Asia-Pacific and North American markets.
- In January 2025, Honeywell and NXP Semiconductors announced a collaboration at CES 2025 aimed at optimizing energy sensing and control in commercial buildings. This partnership involved integrating NXP's neural network-enabled applications processors into Honeywell's Building Management Systems (BMS). The goal was to leverage advanced AI and ML to enhance building autonomy, improve energy efficiency, and guide service technicians.
- In February 2024, Goodyear, a tire manufacturer, partnered with TDK to accelerate the development and adoption of intelligent hardware and software for tires & vehicle ecosystems. Through this collaboration, Goodyear and TDK will work on integrating advanced sensor components into tires to provide real-time data & insights. The goal is to digitize the connection between the tire, vehicle, and road conditions to optimize vehicle performance & safety.
Market Concentration & Characteristics
The Vehicle Security Sensor market exhibits moderate concentration, with a handful of global players holding significant technological and supply chain advantages. It is characterized by strong OEM partnerships, a high degree of product standardization, and growing integration with intelligent automotive systems. Leading companies focus on sensor innovation, cybersecurity readiness, and multi-functional capabilities to address evolving security demands across vehicle categories. The market favors players with advanced R&D capabilities, regulatory compliance expertise, and established relationships with automakers. Entry barriers remain high due to certification requirements, long design-in cycles, and the need for precise engineering. The market also shows characteristics of rapid technological evolution, where AI, IoT, and cloud integration play key roles in differentiating offerings. Demand shifts from standalone components to fully integrated systems that enhance theft prevention, access control, and remote monitoring. It supports sustained investment in hardware-software co-development, making agility and innovation critical to competitiveness. The Vehicle Security Sensor market continues to evolve with increased adoption in connected and electric vehicles, where data-driven and real-time protective mechanisms form a vital part of vehicle architecture.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced vehicle security sensors will rise with increasing vehicle theft and owner awareness.
- Integration of AI and machine learning will enhance real-time threat detection and predictive analytics.
- OEMs will prioritize embedded security solutions in new vehicle models to meet safety standards.
- Biometric access systems such as fingerprint and facial recognition will gain traction in premium segments.
- Aftermarket sales will grow due to rising need for retrofitting security in older and entry-level vehicles.
- Adoption of cloud-connected sensors will expand, enabling remote diagnostics and access control.
- Regulatory bodies will push for mandatory inclusion of security features in commercial and passenger vehicles.
- Electric and connected vehicles will drive demand for multi-layered sensor integration and cybersecurity protection.
- Companies will invest in miniaturized and multi-functional sensors to meet compact design requirements.
- Strategic partnerships between sensor manufacturers and automakers will shape long-term market dynamics.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vehicle Security Sensor market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vehicle Security Sensor Market projected to grow between 2025 and 2032?
Which Vehicle Security Sensor market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vehicle Security Sensor market?
Who are the leading companies in the Vehicle Security Sensor Market?
Which region commanded the largest share of the Vehicle Security Sensor market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vehicle Security Sensor Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vehicle Security Sensor Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 663.5 million → 2032: USD 1018.3 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vehicle Security Sensor Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vehicle Security Sensor Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vehicle Security Sensor Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vehicle Security Sensor Market Drivers
- 3.3 Vehicle Security Sensor Market Restraints & Challenges
- 3.4 Vehicle Security Sensor Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vehicle Security Sensor Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vehicle Security Sensor Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vehicle Security Sensor category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vehicle Security Sensor Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Vehicle Security Sensor Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Vehicle Security Sensor. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vehicle Security Sensor Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vehicle Security Sensor Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Vehicle Security Sensor Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vehicle Security Sensor (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Vehicle Security Sensor
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vehicle Security Sensor Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Vehicle Security Sensor Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vehicle Security Sensor Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vehicle Security Sensor Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vehicle Security Sensor Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vehicle Security Sensor Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vehicle Security Sensor Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vehicle Security Sensor Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
