
Market Overview:
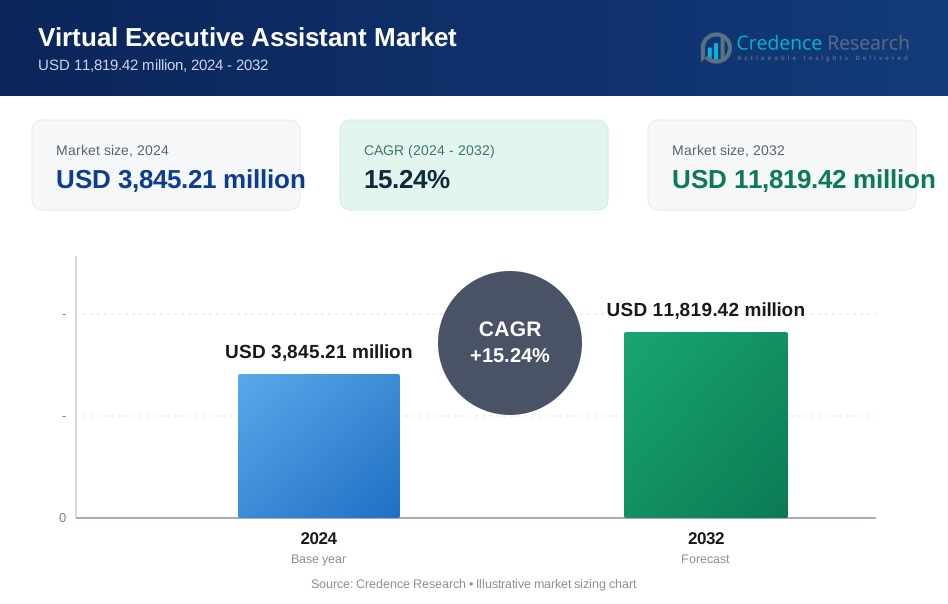
The Virtual Executive Assistant Market size was valued at USD 2,500.00 million in 2018 to USD 3,845.21 million in 2024 and is anticipated to reach USD 11,819.42 million by 2032, at a CAGR of 15.24% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Virtual Executive Assistant Market Size 2024 | USD 3,845.21 million |
| Virtual Executive Assistant Market, CAGR | 15.24% |
| Virtual Executive Assistant Market Size 2032 | USD 11,819.42 million |
The market is growing due to the rising adoption of AI-powered assistants that streamline administrative tasks and enhance productivity. Businesses are increasingly integrating virtual executive assistants to handle scheduling, communication, data entry, and project coordination, reducing the workload on professionals. Cost efficiency, scalability, and the ability to provide round-the-clock support further drive demand. The trend toward remote work and hybrid business models has accelerated adoption, as organizations seek tools that ensure seamless workflow, improved efficiency, and better time management across distributed teams.
Geographically, North America leads the market due to its advanced digital infrastructure and early adoption of AI-driven technologies, with the U.S. being the key hub. Europe follows, supported by strong enterprise investments in automation and productivity solutions. The Asia-Pacific region is emerging rapidly, driven by growing digital transformation initiatives in countries like India, China, and Japan, along with rising demand from SMEs. Latin America and the Middle East are gradually adopting virtual executive assistants, supported by expanding IT services and the need for cost-effective business solutions.

Market Insights:
- The Virtual Executive Assistant Market size was valued at USD 2,500.00 million in 2018, grew to USD 3,845.21 million in 2024, and is anticipated to reach USD 11,819.42 million by 2032, at a CAGR of 15.24%.
- North America led with 36.0% share in 2024, supported by strong digital infrastructure; Asia Pacific held 29.3%, driven by rapid SME adoption; Europe captured 21.6%, led by enterprise automation investments.
- Asia Pacific is the fastest-growing region with a 16.5% CAGR and a 29.3% share, fueled by digital transformation initiatives in China, India, Japan, and South Korea.
- Administrative services accounted for the largest share in 2024 at 32%, reflecting demand for task automation and executive workload reduction.
- Scheduling held the second-largest share at 27%, highlighting strong adoption across hybrid and remote workplace models to improve coordination.
Market Drivers:
Growing Demand for Productivity and Workflow Optimization in Enterprises
The Virtual Executive Assistant Market is witnessing strong demand as enterprises prioritize productivity and workflow optimization. Organizations across industries are under pressure to reduce time spent on repetitive tasks, making automation tools essential. Virtual executive assistants are deployed to handle scheduling, email management, travel coordination, and task prioritization with greater efficiency. Businesses find value in reducing administrative burdens on executives, allowing them to focus on strategic decisions. It offers seamless integration with communication platforms, providing real-time support and enhanced collaboration. The ability to deliver consistent performance without fatigue increases overall productivity. Enterprises recognize the return on investment in terms of time and cost savings. This driver continues to play a central role in market expansion globally.
Rising Adoption of Artificial Intelligence and Natural Language Processing Capabilities
The Virtual Executive Assistant Market is expanding due to rapid improvements in artificial intelligence and natural language processing technologies. Companies leverage these technologies to make assistants more intuitive and capable of handling complex queries. Virtual assistants now understand context better, providing accurate responses and reducing the need for manual oversight. It enhances decision-making support by analyzing data and delivering actionable insights to users. Enhanced language capabilities allow businesses to serve multilingual and diverse workforces effectively. Enterprises view AI-driven assistants as a way to stay competitive in the digital era. Strong vendor investments in AI capabilities drive more adoption across industries. Continuous innovation ensures assistants are evolving beyond basic scheduling tools to advanced productivity platforms.
- For example, Google Assistant uses Natural Language Processing (NLP) models, such as BERT, to enhance its conversational abilities. It has high recognition accuracy in English and supports a large number of languages.
Cost Efficiency and Scalability Benefits Attracting Small and Medium Enterprises
The Virtual Executive Assistant Market benefits significantly from its ability to provide cost-effective solutions to small and medium enterprises. Traditional executive support often requires high costs, while virtual assistants offer scalable and affordable alternatives. SMEs adopt these tools to access professional support without hiring full-time staff. It reduces operational costs by automating repetitive and time-consuming tasks. The flexibility of cloud-based platforms allows businesses to adjust usage levels based on demand. Enterprises value this scalability in competitive markets where resources must be optimized. Virtual assistants allow SMEs to focus on growth and innovation rather than administrative hurdles. Widespread digital adoption among SMEs continues to accelerate this driver globally.
- For instance, Clara Labs developed an AI-powered scheduling assistant designed to help SMEs cut administrative workloads and scale meeting coordination for growing organizations.
Impact of Remote and Hybrid Work on Market Expansion
The Virtual Executive Assistant Market is driven strongly by the widespread shift toward remote and hybrid work models. Organizations require reliable solutions to manage communication, scheduling, and collaboration across distributed teams. Virtual assistants bridge these gaps by providing always-available digital support. It helps maintain workflow continuity in remote environments where traditional in-office assistance is absent. Businesses recognize the necessity of virtual solutions to maintain efficiency outside traditional offices. Cloud-based platforms and mobile accessibility ensure executives stay productive from any location. Increased focus on work-life balance also fuels interest in automated solutions for routine tasks. This shift in workplace structures has transformed virtual assistants from optional tools into operational necessities.
Market Trends:
Expansion of Industry-Specific Virtual Assistant Solutions
The Virtual Executive Assistant Market is experiencing a rise in industry-specific solutions tailored to unique needs. Vendors design assistants that cater to healthcare, legal, financial, and education sectors. These specialized solutions streamline sector-specific tasks such as compliance reporting, document handling, or patient communication. It allows organizations to gain higher efficiency from assistants customized for their work environments. Enterprises increasingly prefer solutions aligned with industry regulations and workflows. The customization trend reflects a deeper focus on enhancing relevance for target users. Industry-specific deployments are shaping the evolution of virtual assistants into strategic digital partners. Such targeted approaches support higher adoption rates among professional services and regulated industries.
- For example, Nuance’s Dragon Medical platform is used by over 500,000 clinicians globally, with adoption across hundreds of healthcare organizations, and it is marketed as achieving over 99% recognition accuracy in clinical documentation.
Integration of Virtual Assistants with Collaboration and Workflow Platforms
The Virtual Executive Assistant Market is witnessing a trend where assistants are integrated directly with workflow management and collaboration tools. Vendors connect assistants with platforms such as Slack, Microsoft Teams, and project management software. This integration ensures executives have seamless support embedded within their daily digital environments. It eliminates the need to switch between tools, creating smoother user experiences. Enhanced compatibility with enterprise applications drives more consistent use across organizations. The push toward interconnected solutions reflects the importance of productivity ecosystems in modern workplaces. Companies value assistants that streamline both administrative and operational tasks within existing frameworks. Such integrations are expected to redefine how enterprises view digital assistance in collaborative spaces.
- For instance, Slack’s workflow automation and AI-powered assistant features have been extensively adopted in corporate environments: in 2025, Slack reported that its AI Workflow Builder drove a measurable increase in team efficiency by automating recurring channel summaries, huddle note organization, and project task assignments, improving collaboration and on-time project delivery as outlined by customer case studies in major enterprises.
Emergence of Voice-Activated and Multilingual Virtual Assistant Interfaces
The Virtual Executive Assistant Market is evolving with growing emphasis on voice-activated and multilingual capabilities. Voice technology provides faster, hands-free interactions that suit busy executive schedules. Multilingual support is increasingly critical in global enterprises with diverse workforces. It empowers organizations to ensure inclusivity and efficiency across borders. Vendors invest in advanced speech recognition to improve user experience and accuracy. Enterprises adopt these solutions to serve global clients and internal teams more effectively. The trend highlights the move toward accessibility and personalization in digital assistance. Voice and language advancements reinforce assistants as indispensable tools in multicultural and fast-paced business settings.
Growing Use of Analytics and Predictive Insights in Virtual Assistants
The Virtual Executive Assistant Market is shaped by the trend of embedding predictive analytics and insights into assistants. Businesses demand tools that not only execute tasks but also provide valuable foresight. Advanced assistants now anticipate scheduling needs, suggest task prioritization, and highlight performance bottlenecks. It allows executives to make informed decisions quickly. Enterprises find predictive insights critical for navigating competitive and fast-moving markets. Vendors emphasize building intelligence layers that transform assistants into proactive partners. The use of analytics enhances the strategic importance of virtual assistants beyond routine tasks. Predictive capabilities are becoming defining features that separate advanced solutions from basic offerings.

Market Challenges Analysis:
Addressing Data Security and Privacy Concerns in Adoption
The Virtual Executive Assistant Market faces challenges linked to data security and privacy risks. Executives handle sensitive corporate data, making protection of information a top concern. Enterprises remain cautious about integrating assistants with core systems due to breaches and unauthorized access risks. It raises issues about compliance with regulatory frameworks across industries and regions. Vendors are required to implement advanced encryption, authentication, and monitoring systems. Ensuring trust remains difficult when sensitive emails, calendars, and files are shared with assistants. Enterprises seek providers who demonstrate transparency and strong security certifications. Without proper safeguards, adoption rates may slow across highly regulated industries.
Managing User Expectations and Overcoming Integration Complexity
The Virtual Executive Assistant Market also encounters challenges related to user expectations and technical integration hurdles. Many enterprises expect assistants to deliver advanced functionality immediately, but solutions often require training and adaptation. Integration with existing platforms may be complex, particularly in legacy IT infrastructures. It creates frustration when promised efficiencies are delayed by customization needs. Enterprises often underestimate the cultural shift required for adoption among executives and staff. Vendors must balance usability with robust features to maintain customer satisfaction. Limited awareness about the true scope of virtual assistant capabilities further complicates acceptance. Overcoming these challenges will remain central to achieving sustained growth in global markets.
Market Opportunities:
Expanding Role of Virtual Assistants in Enterprise Digital Transformation Strategies
The Virtual Executive Assistant Market holds strong opportunities through alignment with enterprise digital transformation strategies. Organizations are investing heavily in automation and AI-driven tools to modernize operations. Virtual assistants serve as key enablers of smarter workflows and greater efficiency. It supports companies in enhancing productivity while reducing dependency on human labor. Cloud platforms expand the reach of assistants across global teams with minimal barriers. Enterprises view these tools as integral to reshaping the future of executive support. Vendors that align their solutions with transformation roadmaps can capture significant demand. Strong emphasis on long-term digital strategies ensures opportunities remain abundant.
Rising Adoption Across Emerging Economies and Small Enterprises Globally
The Virtual Executive Assistant Market is well-positioned for opportunities across emerging economies and small enterprises. Growing digital adoption in Asia-Pacific, Latin America, and Africa creates strong demand for affordable support solutions. SMEs in these regions are prioritizing cost-effective ways to improve productivity. It provides accessible alternatives to traditional staffing models, making digital assistants attractive to smaller firms. Vendors who offer localized solutions gain a competitive advantage in untapped markets. Expanding internet penetration and mobile-first business cultures further drive growth potential. The market is seeing accelerated adoption where digital transformation is moving at high speed. These dynamics strengthen opportunities for widespread global expansion.
Market Segmentation Analysis:
The Virtual Executive Assistant Market is segmented
By service type, covering administrative services, scheduling, communication management, and others. Administrative services hold a strong position as enterprises depend on task automation to reduce executive workloads. Scheduling solutions are gaining traction with the rise of hybrid work environments, while communication management supports collaboration across distributed teams. Other services address specialized tasks, offering flexibility for businesses seeking tailored support. It reflects a shift toward digital-first operations that emphasize efficiency and time savings for executives.
- For instance, enterprises integrating Slack with virtual assistants improved real-time team collaboration and streamlined customer interactions, leading to faster responses and stronger client engagement.
By industry vertical, the market serves healthcare, finance, IT and telecommunications, retail, and others. Healthcare and finance demand secure and reliable solutions to handle sensitive information, while IT and telecommunications drive adoption through continuous digital transformation. Retail focuses on customer engagement and back-office support, leveraging assistants for operational agility. Other sectors adopt virtual assistants to address cost pressures and productivity goals. The Virtual Executive Assistant Market caters to varied requirements, creating growth opportunities across multiple verticals.
- For example, Bank of America's virtual financial assistant, Erica, has exceeded 2 billion client interactions and is integrated into both its mobile and online banking platforms.
By end-user highlights strong adoption among small and medium enterprises due to cost efficiency and scalability. Large enterprises continue to invest in advanced tools to improve productivity across complex workflows. Others, including startups and niche firms, adopt these assistants to gain competitive advantages with minimal overhead. It demonstrates versatility across organizations of all sizes, reflecting broad-based market penetration.
By deployment mode analysis shows cloud-based solutions dominating due to accessibility, scalability, and integration capabilities. On-premises deployment remains relevant for enterprises prioritizing data control and security. Both models maintain demand, addressing distinct organizational needs.

Segmentation:
By Service Type
- Administrative Services
- Scheduling
- Communication Management
- Others
By Industry Vertical
- Healthcare
- Finance
- IT and Telecommunications
- Retail
- Others
By End-User
- Small and Medium Enterprises
- Large Enterprises
- Others
By Deployment Mode
- Cloud-Based
- On-Premises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Virtual Executive Assistant Market size was valued at USD 912.50 million in 2018 to USD 1,386.56 million in 2024 and is anticipated to reach USD 4,256.19 million by 2032, at a CAGR of 15.2% during the forecast period. North America accounts for 36.0% of the global share in 2024, making it the leading region. The Virtual Executive Assistant Market in North America benefits from advanced digital infrastructure, early adoption of AI, and a strong base of multinational enterprises. It is driven by the U.S., which shows high demand across healthcare, finance, and IT sectors. Organizations prioritize efficiency and productivity, leading to widespread adoption of cloud-based solutions. The region also benefits from a skilled workforce that integrates virtual assistants with enterprise platforms. Canada and Mexico are experiencing steady growth supported by digitalization initiatives. Strong vendor presence reinforces North America’s dominance in this market.
Europe
The Europe Virtual Executive Assistant Market size was valued at USD 566.25 million in 2018 to USD 831.61 million in 2024 and is anticipated to reach USD 2,390.51 million by 2032, at a CAGR of 14.3% during the forecast period. Europe holds 21.6% of the market share in 2024, reflecting its position as a mature but steadily expanding region. The Virtual Executive Assistant Market in Europe is supported by strong enterprise investments in automation and productivity solutions. It is led by the UK, Germany, and France, where companies adopt advanced tools to meet compliance and operational requirements. Growing emphasis on digital transformation and hybrid workplaces creates opportunities across sectors. Southern European markets such as Spain and Italy are expanding with increased SME adoption. The region also emphasizes secure deployment models to meet data protection standards. It continues to progress toward wider integration of assistants across business ecosystems.
Asia Pacific
The Asia Pacific Virtual Executive Assistant Market size was valued at USD 707.50 million in 2018 to USD 1,129.90 million in 2024 and is anticipated to reach USD 3,785.77 million by 2032, at a CAGR of 16.5% during the forecast period. Asia Pacific represents 29.3% of the global share in 2024, making it the fastest-growing region. The Virtual Executive Assistant Market in Asia Pacific is driven by rapid digital transformation and the expansion of SMEs. It is supported by strong adoption in China, India, Japan, and South Korea. Enterprises in these countries integrate virtual assistants to handle scheduling, communication, and workflow automation. Rising mobile penetration and cloud-first strategies accelerate demand across industries. Governments in the region promote AI adoption and smart workplace solutions. Australia and Southeast Asia also present strong opportunities due to rising IT investments. It reflects the shift toward scalable, cost-effective business solutions.
Latin America
The Latin America Virtual Executive Assistant Market size was valued at USD 130.00 million in 2018 to USD 197.61 million in 2024 and is anticipated to reach USD 553.98 million by 2032, at a CAGR of 13.9% during the forecast period. Latin America captures 5.1% of the global market share in 2024, reflecting steady but slower adoption compared to developed regions. The Virtual Executive Assistant Market in Latin America is supported by Brazil and Mexico, where enterprises are adopting digital solutions for cost reduction. It is influenced by rising adoption in finance, healthcare, and retail industries. SMEs find value in affordable virtual assistant services to improve competitiveness. Economic diversification policies in the region support technology-driven growth. Cloud-based deployments gain momentum due to flexibility and cost advantages. Regional growth faces challenges such as uneven infrastructure, but adoption continues to expand. It highlights the growing role of digital assistants in modernizing enterprises.
Middle East
The Middle East Virtual Executive Assistant Market size was valued at USD 120.00 million in 2018 to USD 175.32 million in 2024 and is anticipated to reach USD 497.66 million by 2032, at a CAGR of 14.1% during the forecast period. The Middle East holds 4.6% of the global market share in 2024, driven by adoption in GCC countries, Israel, and Turkey. The Virtual Executive Assistant Market in this region benefits from ongoing digital transformation programs. Enterprises in finance, government, and telecom sectors are early adopters of virtual assistants. It reflects regional priorities in efficiency and automation across high-growth industries. Cloud adoption continues to expand, supported by regional investments in infrastructure. Israel demonstrates strong innovation, integrating AI-based solutions in enterprises. Turkey and GCC nations invest in advanced workplace technologies to meet modernization goals. The Middle East shows long-term potential with growing enterprise automation needs.
Africa
The Africa Virtual Executive Assistant Market size was valued at USD 63.75 million in 2018 to USD 124.22 million in 2024 and is anticipated to reach USD 335.31 million by 2032, at a CAGR of 13.0% during the forecast period. Africa accounts for 2.9% of the global share in 2024, making it the smallest but emerging region. The Virtual Executive Assistant Market in Africa is shaped by growing digital adoption in South Africa, Egypt, and Nigeria. It is driven by expanding IT services and increasing demand for cost-effective solutions. SMEs are adopting virtual assistants to reduce administrative burdens and support scalability. Limited infrastructure remains a restraint but improving connectivity fosters adoption. Cloud-based solutions dominate due to their affordability and accessibility. Enterprises across healthcare, retail, and education sectors are exploring deployment for efficiency gains. Africa remains an untapped region with high potential for long-term growth.
Key Player Analysis:
- Amazon Web Services (AWS)
- Google LLC
- Microsoft Corporation
- IBM Corporation
- Oracle Corporation
- Apple Inc.
- com, Inc.
- Zoho Corporation
- Slack Technologies, Inc.
- Asana, Inc.
- Smartsheet Inc.
- Wrike, Inc.
- ClickUp
- Trello (Atlassian Corporation Plc)
Competitive Analysis:
The Virtual Executive Assistant Market is highly competitive, with global technology leaders and specialized providers driving innovation. Major players such as Amazon Web Services, Google, Microsoft, IBM, and Oracle dominate through AI integration, cloud platforms, and enterprise-focused solutions. It is further shaped by companies like Apple, Salesforce, Zoho, and Slack, which enhance collaboration and productivity capabilities. Emerging firms including Asana, Smartsheet, Wrike, ClickUp, and Trello expand adoption through flexible task management and integration features. Competition centers on AI-driven personalization, secure data handling, and seamless workflow integration. Vendors invest in mergers, acquisitions, and product launches to strengthen portfolios and expand regional presence. It reflects a market where both established corporations and agile startups create dynamic growth, with differentiation relying on innovation, scalability, and alignment with enterprise digital transformation strategies.
Recent Developments:
- In March 2025, Microsoft introduced Copilot, a specialized voice-activated AI executive assistant designed for healthcare professionals. Copilot can generate clinical notes, summaries, and referrals through natural language processing, with U.S. and Canadian deployments starting in May. This launch represents Microsoft's drive to tailor executive virtual assistants for specific industries.
- In February 2025, Amazon introduced Alexa+, a next-generation AI-powered virtual assistant leveraging generative AI to provide more personalized, conversational, and intelligent support for users. This rollout includes enhanced task management, smart device integration, and contextual navigation, made available for Prime members and marking a significant leap in executive assistant technology.
- In early 2025, IBM’s Apptio unit announced the near-term rollout of a new virtual assistant aimed at helping corporate finance leaders manage cloud-related costs more efficiently. The beta product is expected to reach general availability by late 2025, offering targeted responses using AI for enterprise financial decision-makers.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Industry Vertical, End-User and Deployment Mode. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Virtual Executive Assistant Market will expand as enterprises accelerate adoption of AI-powered automation to streamline executive tasks.
- Integration with advanced collaboration platforms will strengthen, enabling seamless scheduling, communication, and workflow management across distributed teams.
- Voice-enabled and multilingual capabilities will gain importance, ensuring accessibility for global workforces and diverse user groups.
- Predictive analytics will become central, with assistants offering proactive insights, task prioritization, and data-driven recommendations for executives.
- Cloud-based deployment will dominate growth, supported by flexibility, scalability, and easy integration with enterprise applications.
- Large enterprises will continue investing in advanced assistants, while SMEs will drive demand through cost-effective and scalable solutions.
- Industry-specific solutions tailored for healthcare, finance, and IT will expand, addressing compliance and sector-driven operational needs.
- Security and privacy will remain critical, with vendors prioritizing encryption, compliance frameworks, and trusted platforms to increase adoption.
- Emerging economies will drive growth through rising digital transformation initiatives, increased internet penetration, and adoption by SMEs.
- Continuous innovation from global technology leaders and startups will foster a competitive environment, advancing market maturity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Virtual Executive Assistant Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Virtual Executive Assistant Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Virtual Executive Assistant Market?
Who are the leading companies in the Virtual Executive Assistant Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Virtual Executive Assistant Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Virtual Executive Assistant Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,845.21 million → 2032: USD 11,819.42 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Virtual Executive Assistant Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Virtual Executive Assistant Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Virtual Executive Assistant Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Virtual Executive Assistant Market Drivers
- 3.3 Virtual Executive Assistant Market Restraints & Challenges
- 3.4 Virtual Executive Assistant Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Virtual Executive Assistant Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Virtual Executive Assistant Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Virtual Executive Assistant category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Virtual Executive Assistant Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Virtual Executive Assistant Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Virtual Executive Assistant market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Virtual Executive Assistant Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Virtual Executive Assistant Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Virtual Executive Assistant Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Virtual Executive Assistant (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Virtual Executive Assistant Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Virtual Executive Assistant Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Virtual Executive Assistant Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Virtual Executive Assistant Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Virtual Executive Assistant Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Virtual Executive Assistant Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Virtual Executive Assistant Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Virtual Executive Assistant Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Virtual Executive Assistant Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
