
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI in Computer Vision Market Size 2024 | USD 16,995 Million |
| AI in Computer Vision Market, CAGR | 20.98% |
| AI in Computer Vision Market Size 2032 | USD 77,988.36 Million |
Market Overview:
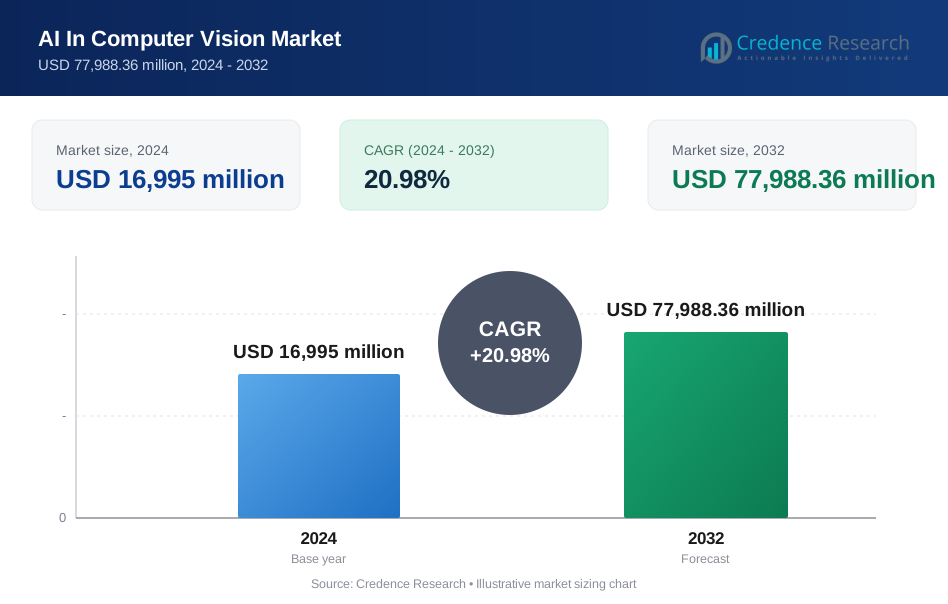
The AI in Computer Vision Market is projected to grow from USD 16,995 million in 2024 to an estimated USD 77,988.36 million by 2032, with a compound annual growth rate (CAGR) of 20.98% from 2024 to 2032.
Key drivers of the computer vision AI market include the increasing adoption of artificial intelligence technologies across various industries, such as healthcare, automotive, retail, and manufacturing. The growing need for automation and enhanced efficiency in these sectors is driving demand for computer vision solutions. Additionally, advancements in deep learning, machine learning, and neural networks are enabling more accurate and real-time image and video analysis, further boosting the market's growth. In the healthcare sector, computer vision is being used for medical imaging, diagnostics, and robotic surgery, improving patient outcomes and operational efficiency. The automotive industry is increasingly adopting computer vision technologies for autonomous vehicles, improving safety features and enabling driver assistance systems. In retail, computer vision is being utilized for inventory management, checkout automation, and personalized customer experiences. The integration of AI with edge computing and cloud platforms is expanding the reach of computer vision applications, making them more accessible and scalable. The rise of smart cities, facial recognition technologies, and security surveillance systems is also contributing to the growing demand for computer vision solutions.
Regionally, North America and Europe are at the forefront of the computer vision AI market, driven by technological advancements, strong industry presence, and increasing investments in AI research and development. In Asia Pacific, countries like China, Japan, and South Korea are witnessing rapid growth in the adoption of AI-powered computer vision solutions, fueled by strong industrialization and government support for AI initiatives. The increasing use of computer vision technologies in sectors such as manufacturing, automotive, and e-commerce is further accelerating market growth in the region. The Latin American and Middle East & Africa regions are also emerging as potential markets, with expanding adoption in sectors like retail, healthcare, and security.
Market insights:
- AI in Computer Vision Market is projected to grow from USD 16,995 million in 2024 to USD 77,988.36 million by 2032, with a CAGR of 20.98%.
- Key drivers include the rising demand for automation, advancements in AI technologies like deep learning, and increased adoption across sectors such as healthcare, automotive, and retail.
- High demand for real-time image and video analysis in industries like manufacturing and security further propels market growth.
- Market restraints include challenges related to data privacy concerns, high implementation costs, and the complexity of AI systems integration.
- North America and Europe are leading regions, supported by strong technological infrastructure, a high concentration of industry players, and government investments in AI research.
- The Asia Pacific region is rapidly growing, driven by industrial expansion and government support for AI initiatives, particularly in China, Japan, and South Korea.
- Emerging markets in Latin America and the Middle East & Africa are witnessing increased adoption, especially in sectors like retail, healthcare, and security surveillance.
Market Drivers:
Increasing Demand for Automation Across Industries:
The adoption of artificial intelligence (AI) and computer vision technologies is becoming a key driver for automation in industries such as manufacturing, healthcare, retail, and automotive. Automation allows companies to improve efficiency, reduce human error, and optimize workflows. For instance, the International Labour Organization (ILO) reported that automation in manufacturing has led to an increase in productivity by up to 30% in certain sectors, enhancing the industry's competitiveness globally. In healthcare, AI-powered imaging solutions enable faster diagnosis, improving the speed and quality of patient care. AI-based diagnostic systems are now routinely used to assist with medical imaging, as highlighted by research from the World Health Organization (WHO). These systems have proven to reduce diagnostic times by over 50%, allowing healthcare providers to handle a higher volume of patients.
Technological Advancements in AI and Machine Learning:
Continuous advancements in AI and machine learning (ML) algorithms, particularly in deep learning and neural networks, are significantly enhancing the capabilities of computer vision systems. These advancements enable more precise image recognition, object detection, and pattern recognition in real-time, leading to better outcomes in industries like automotive and security. For instance, according to the World Economic Forum (WEF), AI-driven vehicle safety systems have reduced accident rates by as much as 40% in certain regions, enhancing safety and reliability. The U.S. National Science Foundation (NSF) has highlighted that AI research funding has grown by over 35% from 2020 to 2023, accelerating the development of advanced AI applications.
Growing Need for Security and Surveillance:
Security concerns, both physical and digital, are pushing the demand for computer vision technologies in surveillance and monitoring systems. Governments and private entities are increasingly investing in AI-driven surveillance tools for threat detection, facial recognition, and anomaly detection. For example, the U.S. Department of Homeland Security (DHS) has allocated more than $100 million to develop AI-based security systems that enhance public safety. According to the European Commission, AI-powered surveillance systems have shown a 25% improvement in detecting suspicious activities compared to traditional methods.
Expansion of Smart Cities and IoT Integration:
The rise of smart cities and the integration of the Internet of Things (IoT) are major drivers for the increased adoption of computer vision. As cities become smarter, computer vision is essential for traffic management, infrastructure monitoring, and public safety. For instance, the World Bank has highlighted that smart city initiatives can lead to an estimated 15% reduction in urban traffic congestion through AI-powered traffic flow management systems. According to the United Nations (UN), by 2025, approximately 68% of the world’s population will live in urban areas, further intensifying the need for intelligent systems that improve quality of life and resource management.
Market Trends:
AI Integration in Healthcare:
The integration of AI and computer vision technologies in healthcare is becoming increasingly prevalent, with significant benefits for diagnostic imaging and medical research. The World Health Organization (WHO) has reported that AI systems are now used to assist in detecting abnormalities in medical images, such as X-rays and MRIs, improving diagnostic accuracy. For instance, the U.S. Department of Health and Human Services (HHS) allocated substantial funding in 2022 for AI initiatives to enhance patient care through advanced diagnostics. This move is expected to support the adoption of AI technologies in hospitals, particularly in diagnostic imaging systems. The global AI healthcare market is projected to grow as hospitals integrate more computer vision technologies into their workflow, leading to better health outcomes and improved operational efficiency.
Government Investment in Smart Cities:
Government initiatives worldwide are driving the development of smart cities, where AI and computer vision play a pivotal role in improving infrastructure and public safety. For example, the U.S. Department of Transportation (DOT) has committed significant funds in grants from 2020 to 2023 to support smart city projects aimed at improving traffic flow through AI and computer vision solutions. These funds are being used for the implementation of intelligent traffic systems, automated surveillance, and enhanced urban mobility solutions. As governments focus on urban modernization, computer vision technologies are becoming essential in creating safer, more efficient, and sustainable cities.
Autonomous Vehicles and Safety Regulations:
Autonomous vehicles are one of the fastest-growing sectors utilizing computer vision technologies. The National Highway Traffic Safety Administration (NHTSA) has emphasized the need for AI-driven systems to enhance vehicle safety through real-time object detection, pedestrian recognition, and hazard avoidance. For instance, the U.S. government has invested substantial funding from 2020 to 2023 on autonomous vehicle research, aiming to improve the safety of self-driving systems. These investments are critical to reducing road accidents and fatalities, and they position AI-powered vehicle technologies as a major trend in transportation safety.
AI in Public Safety and Surveillance:
AI-driven computer vision technologies are increasingly used in public safety and surveillance systems. Governments are integrating these technologies into their security infrastructure to improve crime detection, border control, and crowd monitoring. For example, the European Union (EU) allocated significant funds in 2021 to enhance border security through advanced AI-powered surveillance systems that utilize facial recognition and real-time video analytics. These initiatives are part of broader efforts to improve public safety and ensure national security.
Market Challenge Analysis:
High Implementation Costs and Complex Integration:
One of the primary challenges in the computer vision AI market is the high initial implementation costs. Developing and deploying AI-driven computer vision systems require substantial investment in both hardware and software infrastructure. Small and medium-sized enterprises (SMEs) often face financial barriers when trying to adopt these technologies. Additionally, integrating computer vision solutions into existing workflows can be complex, requiring specialized expertise and time-consuming adjustments. For instance, according to the International Monetary Fund (IMF), the cost of integrating AI technologies into manufacturing systems can account for up to 20% of total capital expenditure for many businesses. This cost can be a deterrent for organizations with limited resources, even though the long-term benefits in terms of productivity and efficiency are significant.
Data Privacy and Ethical Concerns:
Another significant challenge is the growing concerns around data privacy and ethical implications of AI technologies, particularly in surveillance and facial recognition applications. Many governments and regulatory bodies are imposing stricter data protection regulations, which complicate the deployment of computer vision systems. For example, the European Union's General Data Protection Regulation (GDPR) has established stringent guidelines on data collection and usage, directly impacting the deployment of AI-powered surveillance systems in public spaces. Furthermore, ethical concerns about biased algorithms and privacy violations continue to raise alarms. The United Nations (UN) has called for international collaboration to establish standardized guidelines for AI technologies, emphasizing the need to address the potential risks related to personal data misuse and discrimination. For instance, a study by the UN revealed that AI systems used in facial recognition technologies had an error rate of up to 35% for individuals of certain ethnicities, raising concerns about fairness and equity in AI applications. These challenges underline the need for responsible development and governance in the AI industry.
Market Opportunities:
The computer vision AI market presents significant opportunities, particularly in industries like healthcare, automotive, and retail, where the potential for transformative change is substantial. In healthcare, AI-driven imaging systems are revolutionizing diagnostics, improving accuracy, and reducing time-to-diagnosis. The growing demand for personalized medicine and the expansion of telemedicine further increase the need for computer vision applications in clinical settings. For instance, AI can enhance the precision of medical imaging, providing doctors with more detailed and accurate analyses, leading to better patient outcomes. As healthcare systems around the world continue to digitize, the need for advanced AI solutions will likely expand, creating substantial growth opportunities.
In the automotive sector, the rise of autonomous vehicles represents another promising opportunity for computer vision technologies. As vehicles become increasingly automated, the demand for computer vision systems to enable features like obstacle detection, pedestrian recognition, and real-time traffic analysis is accelerating. In addition, smart city initiatives are fostering the growth of AI technologies for traffic management, public safety, and urban planning. With urbanization continuing at a rapid pace, especially in emerging markets, the demand for AI-powered smart city solutions will increase significantly. These advancements provide a wealth of opportunities for businesses to develop and deploy AI-driven solutions that improve safety, efficiency, and the overall quality of life in urban environments. The ongoing investments in AI research and development by government entities and private organizations are expected to fuel innovation and open new market avenues in the coming years.
Market Segmentation Analysis:
Based on Component, the market is divided into hardware, software, and services. Hardware includes processors and accelerators essential for running AI algorithms. Software solutions, such as analytics platforms and simulation tools, dominate this segment due to their ability to optimize chemical processes. Services, including consulting and implementation, are also gaining traction as companies seek to integrate AI into their operations.
Based on Function, AI applications in the chemical industry include production optimization, predictive maintenance, and new material discovery. Production optimization leverages AI to enhance efficiency, reduce waste, and improve energy utilization. Predictive maintenance minimizes downtime by identifying potential equipment failures. New material discovery uses AI-driven simulations to accelerate the development of innovative chemical compounds.
Based on Machine Learning Models, the market is segmented into supervised learning, unsupervised learning, and reinforcement learning. Supervised learning is widely used for quality control and demand forecasting. Unsupervised learning aids in identifying patterns in complex datasets, while reinforcement learning is applied in process automation and optimization.
Segmentation:
Based on Component
- Hardware: Processor (CPU, GPU, ASIC, FPGA), Memory, Storage
- Software: Platform, Solution
Based on Function
- Training
- Inference
Based on Machine Learning Models
- Supervised Learning
- Unsupervised Learning
- Reinforcement Learning
Based on Application
- Industrial: 2D Machine Vision, 3D Machine Vision, Quality Assurance & Inspection
- Non-industrial: Various applications outside the industrial sector
Based on End-Use Industry
- Automotive
- Consumer Electronics
- Healthcare
- Retail
- Security & Surveillance
- Manufacturing
- Agriculture
- Transportation & Logistics
- Others
Based on Regions Covered
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a dominant position in the AI and computer vision market, accounting for the largest share in terms of both market size and technological advancement. The region benefits from robust investments in research and development (R&D) from leading tech companies like Intel, Microsoft, and NVIDIA, who are pioneers in AI and computer vision technologies. The U.S. government has also been a key player, supporting AI innovations through funding initiatives such as those by the U.S. Department of Energy and the National Science Foundation (NSF). For instance, the U.S. Department of Transportation allocated significant funds for smart city initiatives, fostering the use of AI and computer vision in urban infrastructure. Moreover, sectors like automotive, healthcare, and manufacturing are rapidly adopting computer vision solutions for applications such as autonomous vehicles, diagnostic imaging, and quality control.
Asia Pacific
Asia Pacific is experiencing significant growth in the AI and computer vision market, driven primarily by China, Japan, and India. The region is home to a rapidly expanding manufacturing base and a growing demand for smart technologies, particularly in industries like automotive, retail, and security. Governments in the region are investing heavily in AI initiatives, such as China's "Made in China 2025" plan, which focuses on the development of AI and smart manufacturing technologies. Japan's government has also been supporting initiatives aimed at enhancing industrial automation and developing AI-based solutions for sectors like healthcare and transportation. For instance, in 2023, Japan’s Ministry of Economy, Trade, and Industry allocated substantial funding to promote AI-driven technologies in manufacturing.
Europe
Europe remains a strong player in the AI and computer vision market, with countries like Germany, the United Kingdom, and France leading the charge. Europe’s industrial sector, particularly in manufacturing and automotive, has long been at the forefront of adopting automation technologies. The European Union (EU) has supported AI research and development through funding programs like Horizon 2020, which has encouraged the implementation of AI and computer vision in sectors ranging from automotive to healthcare. The region's focus on sustainability and smart city development is further propelling the demand for AI technologies, especially in areas such as traffic management, infrastructure monitoring, and environmental surveillance. For instance, the European Commission has committed significant resources to enhancing border security and improving public safety through AI-powered surveillance systems
Key Player Analysis:
- NVIDIA Corporation
- Microsoft Corporation
- Intel Corporation
- Alphabet Inc.
- Amazon.com, Inc.
- Cognex Corporation
- Qualcomm Technologies, Inc.
- Sony Group Corporation
- OMRON Corporation
- KEYENCE CORPORATION
- SICK AG
- Teledyne Technologies
- Texas Instruments Incorporated
- Basler AG
- Hailo Technologies Ltd.
Competitive Analysis:
The computer vision AI market is highly competitive, with key players continuously advancing their technologies to maintain market leadership. Major companies like NVIDIA, Intel, and Microsoft are driving innovation through strategic investments in AI research and development, leveraging their strong hardware and software capabilities. These companies focus on enhancing the performance of computer vision systems by incorporating deep learning algorithms, enabling real-time image processing and accurate object detection. Additionally, emerging startups are contributing innovative solutions, particularly in specialized sectors such as healthcare and autonomous vehicles. Strategic partnerships and acquisitions are also common as companies look to expand their portfolios and enhance capabilities in AI and machine learning. Regulatory compliance, particularly regarding data privacy, remains a critical challenge, requiring companies to adapt their solutions to meet evolving legal standards. Overall, the market is dynamic, with intense competition pushing continuous technological advancements and improvements in AI-powered computer vision applications.
Recent Developments:
- In November 2024, Intel Corporation launched Intel OpenVINO 2024.5, a new version designed to advance AI in computer vision. This release optimizes runtimes for Intel hardware and enhances support for large language models, enabling efficient AI deployment across edge, cloud, and local environments for vision applications.
- Also, in November 2024, Texas Instruments Incorporated introduced the TMS320F28P55x and F29H85x microcontroller series. These microcontrollers integrate edge AI and advanced real-time control capabilities, improving fault detection accuracy, decision-making speed, and safety compliance for automotive and industrial applications, further enhancing system efficiency and sustainability.
- In October 2024, Teledyne FLIR LLC unveiled Prism AIMMGen, an ITAR-free AI model generation service. This tool automates the creation of AI and machine learning models using synthetically generated data, significantly reducing costs and development timelines. It can generate millions of annotated synthetic images, enabling rapid fine-tuning of models for commercial, defense, and first-response applications.
- In September 2024, Basler AG launched pylon AI, an innovative AI image analysis software aimed at precise and efficient applications. With features like performance benchmarking and no programming requirements, pylon AI simplifies the entry into advanced image analysis for various industries.
- In June 2024, Intel Corporation released an updated version of its AI vision software, Intel® Geti™ 2.0.0. The new version includes enhanced features for data labeling, model training, and inferencing, streamlining computer vision development. Existing customers can also upgrade to take advantage of the latest advancements in Vision AI software.
Market Concentration & Characteristics:
The computer vision AI market exhibits moderate to high concentration, with a few large players dominating the landscape while numerous smaller companies focus on niche applications. Leading technology giants like NVIDIA, Intel, and Google leverage their substantial resources and research capabilities to drive innovation and maintain competitive advantages in hardware, software, and AI integration. These companies typically target broad markets, including healthcare, automotive, and security, offering end-to-end solutions. However, smaller firms and startups are increasingly carving out opportunities by specializing in specific use cases, such as medical imaging or industrial automation, where tailored solutions can provide a competitive edge. The market is characterized by rapid technological advancements, with companies investing heavily in deep learning and machine learning models to enhance the accuracy and efficiency of computer vision systems. Additionally, partnerships and collaborations between industry leaders and start-ups are common, fueling continuous innovation and expanding the market’s overall scope.
Report Coverage:
The research report offers an in-depth analysis based on By Component, By Machine Learning Models, By application, By Function, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Computer vision AI will continue to experience widespread adoption across various industries, particularly healthcare, automotive, and retail.
- Advancements in deep learning algorithms will drive more accurate and real-time image processing, enhancing AI's capabilities.
- Integration with IoT systems will expand, creating more opportunities for smart cities and industrial automation applications.
- Increased investments in AI research and development by government bodies and private companies will foster innovation in the market.
- Autonomous vehicles will heavily rely on computer vision technologies for enhanced safety features and driver assistance systems.
- The growth of e-commerce will boost the demand for computer vision in retail, enabling improved inventory management and personalized shopping experiences.
- The healthcare sector will increasingly leverage AI-powered computer vision systems for medical imaging, diagnostics, and robotic surgery.
- Data privacy and regulatory concerns will drive the development of more secure and compliant AI solutions.
- The market will see the emergence of new players, focusing on niche applications such as facial recognition and biometric security systems.
- AI-powered solutions will continue to improve productivity and operational efficiency in sectors like manufacturing and logistics, driving further market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automation Across Industries
The need for automation in sectors such as manufacturing, healthcare, and automotive is accelerating the adoption of AI-powered computer vision, enabling improved efficiency, reduced human error, and optimized workflows.
Advancements in Deep Learning and AI Algorithms
Continuous improvements in deep learning, neural networks, and machine learning models are making computer vision systems more accurate and capable of real-time image and video analysis, expanding their applicability across industries.
Expansion of Smart Cities and IoT Integration
The proliferation of smart city initiatives and IoT devices is driving demand for computer vision solutions in traffic management, infrastructure monitoring, and public safety, as cities seek to enhance urban efficiency and security.
Rising Security and Surveillance Needs
Growing concerns over physical and digital security are prompting governments and enterprises to invest in AI-driven surveillance and facial recognition systems, which offer superior threat detection and monitoring capabilities.
Healthcare Imaging and Diagnostics
The integration of AI in medical imaging and diagnostics is improving the speed and accuracy of patient care, with computer vision enabling faster, more precise analysis of medical images and supporting the expansion of telemedicine.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the AI in computer vision market?
What factors are driving the AI in computer vision market?
What are the key segments within the AI in computer vision market?
What are some challenges faced by the AI in computer vision market?
Who are the major players in the AI in computer vision market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Function
- 1.2.1 Training
- 1.2.2 Inference
- 1.3 By Component
- 1.3.1 Hardware (Processor, Memory, Storage)
- 1.3.2 Software (Platform, Solution)
- 1.3.3 Services
- 1.4 By End-Use Industry
- 1.4.1 Automotive
- 1.4.2 Healthcare
- 1.4.3 Retail
- 1.4.4 Manufacturing
- 1.4.5 Security & Surveillance
- 1.4.6 Consumer Electronics
- 1.4.7 Agriculture
- 1.4.8 Transportation & Logistics
- 1.5 By Machine Learning Model
- 1.5.1 Supervised Learning
- 1.5.2 Unsupervised Learning
- 1.5.3 Reinforcement Learning
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16,995 million → 2032: USD 77,988.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global AI In Computer Vision Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global AI In Computer Vision Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global AI In Computer Vision Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global AI In Computer Vision Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global AI In Computer Vision Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global AI In Computer Vision Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global AI In Computer Vision Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global AI In Computer Vision Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16,995 million → 2032: USD 77,988.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global AI In Computer Vision Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Function - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Training
- 12.3.7.2 Inference
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware (Processor, Memory, Storage)
- 12.4.7.2 Software (Platform, Solution)
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Healthcare
- 12.5.7.3 Retail
- 12.5.7.4 Manufacturing
- 12.5.7.5 Security & Surveillance
- 12.5.7.6 Consumer Electronics
- 12.5.7.7 Agriculture
- 12.5.7.8 Transportation & Logistics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Machine Learning Model - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Supervised Learning
- 12.6.7.2 Unsupervised Learning
- 12.6.7.3 Reinforcement Learning
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global AI In Computer Vision End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global AI In Computer Vision Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global AI In Computer Vision Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global AI In Computer Vision Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 NVIDIA Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 Intel Corporation
- 18.5 Alphabet Inc.
- 18.6 Amazon.com, Inc.
- 18.7 Cognex Corporation
- 18.8 Qualcomm Technologies, Inc.
- 18.9 Sony Group Corporation
- 18.10 OMRON Corporation
- 18.11 KEYENCE CORPORATION
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

