
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Dealer Management System Market Size 2023 | USD 4,953.00 million |
| Automotive Dealer Management System Market, CAGR | 8.80% |
| Automotive Dealer Management System Market Size 2032 | USD 9,725.22 million |
Market Overview
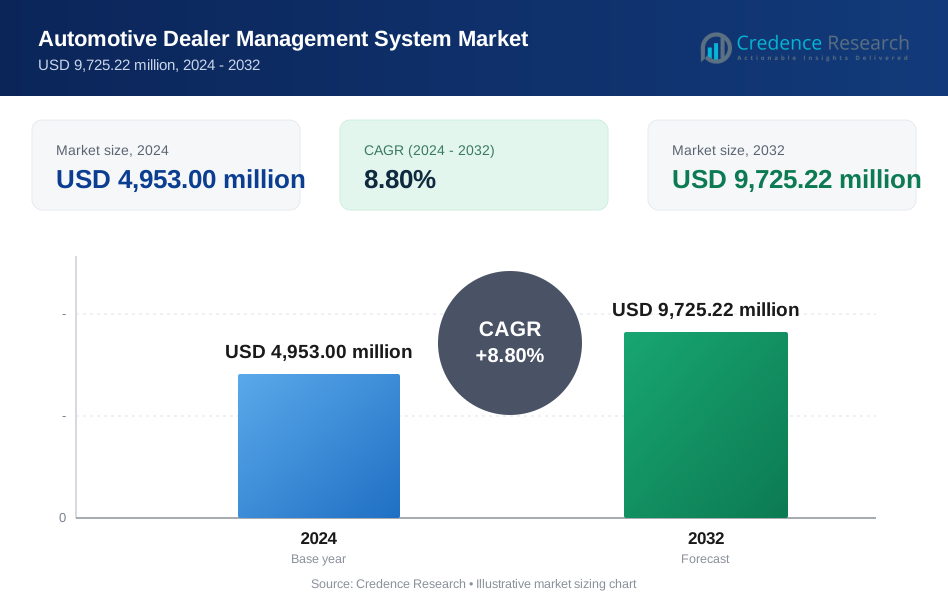
The Automotive Dealer Management System Market is projected to grow from USD 4,953.00 million in 2024 to USD 9,725.22 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.80%.
The Automotive Dealer Management System Market is driven by the increasing need for streamlined dealership operations, enhanced customer experience, and improved inventory management. The growing adoption of cloud-based solutions and the integration of advanced technologies such as AI and machine learning are further fueling market growth. Additionally, the shift towards digital retailing and the rising demand for data-driven decision-making tools are key trends shaping the market. These factors, combined with the automotive industry's ongoing digital transformation, are propelling the adoption of dealer management systems across the globe.
The Automotive Dealer Management System (DMS) Market exhibits significant geographical diversity, with North America leading due to the high adoption of advanced automotive technologies and strong presence of key players like CDK Global and Dealertrack, Inc. Europe follows closely, driven by the growing demand for digital solutions in the automotive industry, with companies like Gemini Computer Systems Ltd and Irium Software making notable contributions. The Asia-Pacific region is rapidly expanding, fueled by the increasing automotive sales and digital transformation initiatives in countries like China and India, where local players such as Excellon Software Pvt. Ltd. are gaining traction.
Market Drivers
Increasing Need for Operational Efficiency in Dealerships
The Automotive Dealer Management System (DMS) Market is driven by the growing demand for operational efficiency within dealerships. DMS solutions enable streamlined processes, reducing operational costs and boosting productivity across various dealership functions. For instance, a survey found that 85% of dealerships reported improved operational efficiency after implementing a DMS. The impact is particularly notable in inventory management, where effective DMS use has been shown to reduce carrying costs by up to 20% according to industry reports. One of the key areas of impact is inventory management, where effective control and optimization of stock levels ensure that dealerships maintain the right balance of vehicles and parts, minimizing excess inventory and avoiding shortages. Additionally, DMS supports efficient management of sales, service, and parts operations, enabling dealerships to handle these critical functions more effectively and ultimately enhance overall business performance.
Adapting to Digital Sales Channels and Regulatory Compliance
The shift towards digital sales channels is another key trend in the DMS market, as more dealerships embrace online platforms for vehicle sales and customer interactions. DMS solutions support this transition by efficiently managing online inventory and fulfillment, ensuring that digital sales channels operate smoothly. The shift towards digital sales channels is accelerating, with the NADA reporting a 30% increase in online vehicle sales in 2023 compared to the previous year. Additionally, the integration of CRM in digital channels helps build and maintain strong customer relationships in an increasingly online environment. At the same time, regulatory compliance remains a critical consideration for dealerships, with DMS platforms ensuring adherence to data privacy laws, financial reporting standards, and industry-specific regulations. This combination of digital transformation and regulatory compliance enables dealerships to remain competitive and responsive to market demands.
Enhancing Customer Experience through CRM Integration
Another significant driver is the need for enhanced customer experiences, facilitated by the integration of customer relationship management (CRM) tools within DMS platforms. This integration allows dealerships to offer personalized services tailored to individual customer preferences, derived from data-driven insights. Furthermore, digital engagement is becoming increasingly important, with dealerships offering online tools and services that enhance customer interactions. By leveraging these digital tools, dealerships can provide seamless, personalized experiences that build customer loyalty and satisfaction, which are crucial in a competitive market.
Growing Importance of Data Analytics in Decision-Making
The rise of data analytics is transforming the way dealerships operate, with DMS playing a pivotal role in harnessing business intelligence for informed decision-making. By analyzing sales performance, dealerships can identify trends and opportunities that drive growth. Additionally, insights into customer behavior allow dealerships to better understand customer preferences and needs, enabling more targeted marketing and sales strategies. The use of data analytics in DMS not only improves operational efficiency but also enhances the ability to anticipate market demands and adjust strategies accordingly.
Market Trends
Cloud-Based DMS Solutions and AI Integration Driving Market Evolution
The shift towards cloud-based Dealer Management Systems (DMS) is revolutionizing the automotive industry by offering increased flexibility, scalability, and accessibility to dealerships of all sizes. For instance, a recent shift towards cloud-based Dealer Management Systems (DMS) was observed when Tata Motors migrated their entire DMS to Oracle Cloud Infrastructure. This migration was aimed at boosting the operational efficiencies of Tata Motors with deeper business insights, greater security, increased flexibility, and cost optimization. Additionally, these platforms offer enhanced data security, with cloud providers implementing advanced protection measures to safeguard sensitive dealership and customer data. Alongside cloud adoption, the integration of Artificial Intelligence (AI) and Machine Learning (ML) into DMS platforms is enhancing predictive analytics capabilities. AI-driven predictive analytics allow dealerships to forecast sales trends, manage inventory levels more effectively, and understand customer behavior with greater accuracy. Moreover, AI enables advanced customer segmentation, allowing dealerships to identify specific customer groups and tailor marketing campaigns to meet their needs. The integration of AI also plays a critical role in fraud detection, helping to prevent fraudulent activities and protect dealership assets.
Mobile Optimization and Enhanced Customer Experience Transforming Dealership Interactions
Mobile optimization is becoming increasingly important in the DMS market, as dealerships seek to enhance both dealer and customer accessibility. Mobile-enabled DMS functionalities allow dealers to manage service appointments, technician schedules, and sales operations on the go, significantly improving field service management and salesforce productivity. This mobile-first approach ensures that dealerships can operate efficiently in real-time, regardless of location, and provides a seamless experience for both employees and customers. Concurrently, the focus on enhancing customer experience is driving the adoption of omnichannel platforms within DMS. These platforms provide a consistent and seamless experience across multiple channels, from in-person visits to online interactions. Personalized marketing, supported by data analytics, allows dealerships to deliver targeted messages that resonate with individual customer preferences, further enhancing engagement. Additionally, digital showroom capabilities are becoming a key feature, enabling dealerships to offer virtual vehicle tours and online purchasing options, catering to the growing demand for digital retail experiences. As these trends converge, they are reshaping the way dealerships operate, interact with customers, and compete in a rapidly evolving market landscape.
Market Challenges Analysis
Data Security, Integration, and Implementation Challenges Impacting Market Adoption
Data security and privacy are paramount concerns in the Automotive Dealer Management System (DMS) Market, as dealerships handle vast amounts of sensitive customer and operational data. Protecting this data from cyberattacks is critical, particularly as cyber threats become more sophisticated. According to a report by the National Automobile Dealers Association (NADA), the average dealership spends approximately 8.5% of its total expenses on IT-related costs, including DMS implementation and maintenance. Compliance with data privacy regulations such as GDPR and CCPA adds another layer of complexity, requiring dealerships to implement stringent data protection measures. Ensuring data security is not just a regulatory requirement but also essential for building and maintaining customer trust. However, the challenges extend beyond data security to the integration of DMS with other dealership systems, such as CRM, inventory management, and finance. Achieving seamless integration is often difficult due to the need for consistency and accuracy across multiple systems. The integration process itself can be time-consuming and resource-intensive, making it a significant hurdle for dealerships looking to modernize their operations. Additionally, the high upfront costs of implementing a DMS, along with ongoing maintenance expenses, can be a deterrent for some dealerships. Demonstrating a clear return on investment (ROI) is crucial to justify these expenditures, yet the complexity of quantifying the benefits of a DMS can make this challenging.
Resistance to Change, Customization Needs, and Competitive Pressures in the DMS Market
Resistance to change within dealerships is another critical challenge in the adoption of DMS solutions. Employees may be reluctant to embrace new technology and processes, requiring significant investment in training and change management strategies to ensure effective usage of the DMS. Overcoming this resistance is essential for the successful implementation and operation of the system. Moreover, the need for customization and flexibility within DMS platforms poses additional challenges. Each dealership has unique operational needs, and the ability of a DMS to meet these requirements while remaining adaptable to changing market conditions is crucial. Balancing the need for customization with the efficiency of standardized processes can be difficult, particularly in a market where differentiation is key to competitive advantage. The DMS market is highly competitive, with numerous providers vying for market share. This intense competition leads to pricing pressure, forcing providers to reduce prices to remain competitive, which can erode profit margins. Differentiating offerings in such a crowded market requires DMS providers to continuously innovate and highlight unique selling points that resonate with dealerships looking to optimize their operations.
Market Segmentation Analysis:
By Component:
The Automotive Dealer Management System (DMS) Market is segmented by component into automotive dealer management solutions and services. The solutions segment forms the core of the market, offering dealerships comprehensive software platforms that integrate various operational functions such as sales, service, inventory management, and customer relationship management. This segment is essential for enhancing operational efficiency and improving customer interactions. On the services side, the market is further divided into professional services and managed services. Professional services include consulting, implementation, and training, which are crucial for the successful deployment and optimization of DMS solutions. Managed services, on the other hand, provide ongoing support and maintenance, ensuring that dealerships can continuously operate their DMS with minimal disruption. The combination of these components allows dealerships to adopt a holistic approach to managing their operations, making them more competitive in a rapidly evolving market.
By Deployment:
In terms of deployment, the Automotive DMS Market is segmented into cloud-based and on-premises solutions. Cloud-based deployment is increasingly popular due to its scalability, flexibility, and lower upfront costs. This deployment model allows dealerships to access their DMS from any location, providing real-time data and enhancing operational agility. Additionally, cloud-based solutions offer enhanced data security and reduce the need for significant IT infrastructure investments, making them an attractive option for dealerships of all sizes. On-premises deployment, while offering greater control over the system, typically requires higher initial investment and ongoing maintenance. It is often preferred by larger dealerships with the resources to manage their own IT infrastructure. As the market evolves, cloud-based solutions are expected to continue gaining traction, driven by their ability to support remote operations and adapt to the changing needs of the automotive industry.
Segments:
Based on Component:
- Automotive Dealer Management Solution
- Services
- Professional Services
- Managed Services
Based on Deployment:
- Cloud-Based
- On-Premises
Based on Application:
- Customer Relationship Management
- Dealer Tracking
- Inventory Management
- Finance
- Sales
- Others
Based on End-use Industry:
- Automotive
- Marine & Motorsports
- Oil & Gas
- Transportation and Logistics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the market with a substantial 40% share, primarily due to its advanced automotive retail sector and early adoption of digital technologies. The United States dominates this segment, benefiting from a large network of dealerships and a strong emphasis on customer relationship management. The region's market is characterized by high demand for cloud-based DMS solutions that offer integrated modules for inventory management, sales, finance, and after-sales service. Canada follows suit, with increasing adoption of DMS platforms that comply with stringent data privacy regulations. The North American market also benefits from continuous innovations in AI-powered analytics and predictive maintenance features, enhancing dealership efficiency and customer experience.
Europe
Europe holds the second-largest market share at 30%, with countries like Germany, the United Kingdom, and France leading in DMS adoption. The European market is driven by stringent regulations on data protection and a growing focus on omnichannel retail experiences in the automotive sector. For instance, the advent of Digital Transformation has emerged as a significant catalyst propelling the market forward. The region has seen significant investments in DMS platforms that support electric vehicle (EV) sales and service operations, aligning with the rapid growth of the EV market.
Key Player Analysis
- PBS Systems, Inc.
- Blue Skies Business Solutions Inc.
- XAPT Corporation
- BiT Dealership Software, Inc.
- Quorum Information Technologies
- Elva DMS
- Ideal Computer Systems
- Adam Systems
- Gemini Computer Systems Ltd
- Irium Software
- Excellon Software Pvt. Ltd.
- CDK Global
- Dealertrack, Inc.
Competitive Analysis
In the highly competitive Automotive Dealer Management System (DMS) Market, leading players such as CDK Global, Dealertrack, Inc., and PBS Systems, Inc. dominate by offering comprehensive, integrated solutions that cater to the diverse needs of automotive dealerships. CDK Global stands out with its robust platform that covers every aspect of dealership operations, from sales and service to inventory management and customer relationship management. Dealertrack, Inc. is recognized for its advanced digital retailing tools and seamless integration with other dealership systems, making it a preferred choice for many large dealerships. PBS Systems, Inc. differentiates itself by providing highly customizable DMS solutions that allow dealerships to tailor the software to their specific operational needs. These companies are continuously innovating, enhancing their platforms with features like cloud deployment, AI-driven analytics, and mobile accessibility. The intense competition in the market drives these leading players to focus on customer satisfaction, system flexibility, and technological advancements to maintain and grow their market share.
Recent Developments
- In April 2024, Quorum released its 2022 inaugural Sustainability Statement and a new mobile Sales Customer Relationship (“CRM”) application.
- In January 2023, CDK Global, Inc., based in Illinois, launched Neuron, an open, intelligent data platform integrated with the Fortellis Automotive Commerce Exchange. This new solution is designed to transform large volumes of industry data into clear, actionable insights for OEMs, dealers, and third-party software developers.
- In June 2024, CDK Global faced a significant cybersecurity incident that severely impacted its dealer management system.
Market Concentration & Characteristics
The Automotive Dealer Management System (DMS) Market exhibits a moderate to high level of market concentration, with a few key players such as CDK Global, Dealertrack, Inc., and PBS Systems, Inc. dominating the industry. These companies leverage their extensive experience, robust product offerings, and strong customer relationships to maintain a significant share of the market. The market is characterized by its rapid technological advancements, with a strong emphasis on integrating digital tools like AI, cloud-based solutions, and mobile accessibility to meet the evolving needs of automotive dealerships. Despite the dominance of large players, the market also features a variety of smaller, specialized companies that cater to niche segments, offering highly customizable and region-specific solutions. This blend of major and emerging players creates a dynamic competitive environment where continuous innovation, customer service excellence, and adaptability are crucial for success and growth.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment, Application, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Automotive Dealer Management System Market is expected to continue growing, driven by increasing digitalization in the automotive industry.
- Cloud-based DMS solutions will gain more traction due to their scalability, flexibility, and lower costs.
- Integration of artificial intelligence and machine learning will enhance predictive analytics, improving decision-making processes in dealerships.
- Mobile optimization will become a critical focus, enabling greater accessibility and efficiency for both dealers and customers.
- The rise of electric vehicles will necessitate DMS platforms that support EV-specific inventory and service management.
- Data security and privacy will remain paramount, with ongoing investments in cybersecurity measures to protect sensitive information.
- Growing competition will push DMS providers to innovate continuously, offering more customizable and user-friendly solutions.
- Expansion into emerging markets, particularly in Asia-Pacific, will present significant growth opportunities for DMS providers.
- Regulatory compliance will become increasingly complex, requiring DMS platforms to adapt and ensure adherence to new standards.
- Strategic partnerships and acquisitions will shape the market as companies seek to expand their capabilities and global reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Need for Operational Efficiency in Dealerships
Dealerships are adopting DMS solutions to streamline processes, reduce operational costs, and improve productivity across sales, service, and inventory management, enabling them to remain competitive and profitable.
Adoption of Cloud-Based and AI-Integrated Solutions
The shift to cloud-based DMS platforms and the integration of AI and machine learning provide dealerships with scalable, flexible, and secure systems that enhance predictive analytics, inventory management, and customer insights.
Shift Toward Digital Sales Channels and Omnichannel Retailing
As more vehicle sales and customer interactions move online, DMS platforms enable dealerships to efficiently manage digital inventory, online transactions, and provide seamless omnichannel experiences, supporting the industry's digital transformation.
Growing Importance of Data Analytics in Decision-Making
DMS platforms equipped with advanced analytics empower dealerships to make data-driven decisions, optimize marketing and sales strategies, and better understand customer preferences, leading to improved business outcomes.
Regulatory Compliance and Data Security Requirements
Stringent data privacy laws and industry regulations are driving dealerships to implement DMS solutions that ensure compliance and robust data protection, safeguarding sensitive customer and operational information.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Dealer Management System Market?
What factors are driving the growth of the Automotive Dealer Management SystemMarket?
What are the key segments within the Automotive Dealer Management System Market?
Who are the major players in the Automotive Dealer Management System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Automotive Dealer Management Solution
- 1.2.2 Professional Services
- 1.2.3 Managed Services
- 1.3 By Deployment
- 1.3.1 Cloud-Based
- 1.3.2 On-Premises
- 1.4 By Application
- 1.4.1 Customer Relationship Management
- 1.4.2 Dealer Tracking
- 1.4.3 Inventory Management
- 1.4.4 Finance
- 1.4.5 Sales
- 1.4.6 Others
- 1.5 By End-use Industry
- 1.5.1 Automotive
- 1.5.2 Marine & Motorsports
- 1.5.3 Oil & Gas
- 1.5.4 Transportation and Logistics
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,953.00 million → 2032: USD 9,725.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Dealer Management System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Dealer Management System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Dealer Management System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Dealer Management System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Dealer Management System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Dealer Management System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Dealer Management System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Dealer Management System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,953.00 million → 2032: USD 9,725.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Dealer Management System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive Dealer Management Solution
- 12.3.7.2 Professional Services
- 12.3.7.3 Managed Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cloud-Based
- 12.4.7.2 On-Premises
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Customer Relationship Management
- 12.5.7.2 Dealer Tracking
- 12.5.7.3 Inventory Management
- 12.5.7.4 Finance
- 12.5.7.5 Sales
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive
- 12.6.7.2 Marine & Motorsports
- 12.6.7.3 Oil & Gas
- 12.6.7.4 Transportation and Logistics
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Dealer Management System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Dealer Management System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Dealer Management System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Dealer Management System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CDK Global
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dealertrack, Inc.
- 18.4 PBS Systems, Inc.
- 18.5 Quorum Information Technologies
- 18.6 XAPT Corporation
- 18.7 Gemini Computer Systems Ltd
- 18.8 Irium Software
- 18.9 Excellon Software Pvt. Ltd.
- 18.10 BiT Dealership Software, Inc.
- 18.11 Adam Systems
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

