
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Door Hinges Market Size 2024 | USD 7444 Million |
| Automotive Door Hinges Market, CAGR | 4.1% |
| Automotive Door Hinges Market Size 2032 | USD 10266.2 Million |
Market Overview:
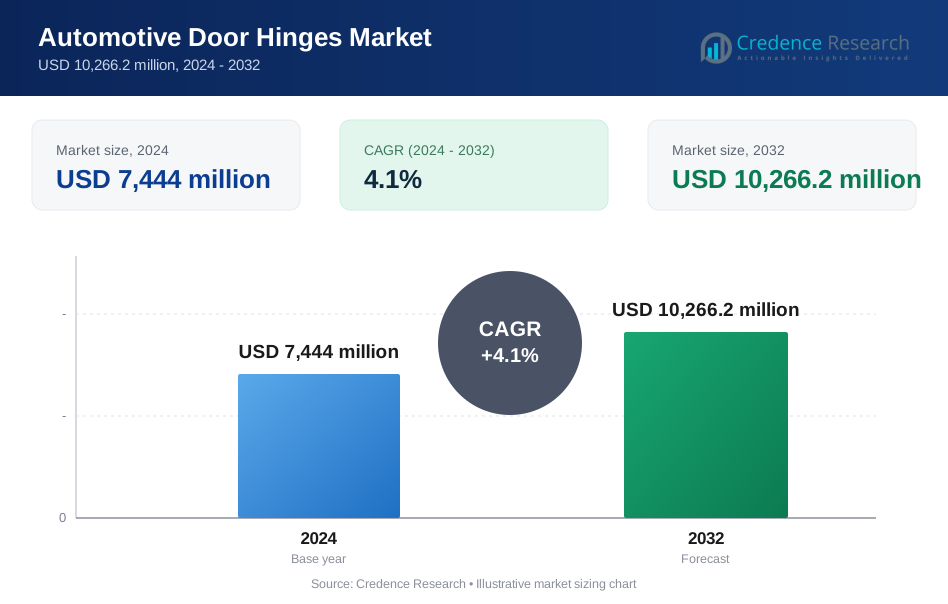
The Automotive Door Hinges Market is projected to grow from USD 7444 million in 2024 to an estimated USD 10266.2 million by 2032, with a compound annual growth rate (CAGR) of 4.1% from 2024 to 2032.
Several key drivers are fueling this growth. First, the global rise in vehicle production, particularly in emerging economies such as India, China, and Brazil, is creating substantial demand for automotive components, including door hinges. Secondly, automakers are increasingly adopting lightweight materials like aluminum and high-strength steel in hinges to reduce vehicle weight and improve fuel efficiency, especially in electric vehicles (EVs). Furthermore, innovations such as self-lubricating hinges, anti-corrosion coatings, and modular hinge designs are improving both performance and lifespan, making these components more attractive to OEMs. The growing popularity of luxury and customized vehicles is also driving demand for premium and aesthetic hinge designs. In addition, aging vehicle fleets in mature markets are boosting the aftermarket segment, where consumers seek replacement parts and performance upgrades. Government regulations aimed at reducing vehicle emissions are indirectly promoting the use of advanced lightweight hinge systems, further contributing to market expansion.
Regionally, Asia-Pacific holds the largest share of the automotive door hinges market, driven by high vehicle production rates, rising domestic demand, and expanding EV adoption in countries like China, Japan, South Korea, and India. This region is expected to maintain its dominance through the forecast period, owing to its strong manufacturing infrastructure and cost-effective production capabilities. Europe is another significant market, supported by stringent environmental regulations, technological innovation, and the presence of leading automotive OEMs in Germany, France, and Italy. North America also contributes significantly, with steady demand from both OEMs and the replacement market, particularly in the United States and Canada. Meanwhile, Latin America and the Middle East & Africa represent emerging markets with moderate growth prospects, driven by growing urbanization, industrial development, and regional assembly initiatives, despite challenges such as economic instability and supply chain limitations. Together, these regional dynamics highlight a diverse but optimistic growth landscape for the global automotive door hinges market.
Market Insights:
- The automotive door hinges market is projected to grow from USD 7,444 million in 2024 to USD 10,266.2 million by 2032, registering a compound annual growth rate (CAGR) of 4.1% over the forecast period.
- Strong growth in global vehicle production, particularly in emerging economies such as China, India, and Brazil, is increasing the demand for door hinges, driven by rising passenger and commercial vehicle output.
- Automakers are increasingly shifting toward lightweight materials like aluminum and high-strength steel for door hinges to reduce vehicle weight, enhance fuel efficiency, and meet performance standards in electric vehicle (EV) platforms.
- Advancements in hinge technologies such as self-lubricating mechanisms, noise-reduction coatings, multi-stage functionality, and anti-corrosion features are elevating product quality and positioning hinges as critical safety and convenience components.
- A growing aftermarket driven by aging vehicle fleets in North America and Europe presents significant opportunities for replacement hinges, with customers seeking both functional upgrades and custom design options.
- The market faces challenges due to raw material price volatility and ongoing supply chain disruptions, which impact production costs, inventory planning, and pricing strategies for manufacturers.
- Regionally, Asia-Pacific leads the market in volume and growth, supported by strong automotive production capabilities and EV demand, followed by Europe with its regulatory push and OEM presence, and North America, which shows steady aftermarket and OEM demand.
Market Drivers:
Rising Global Vehicle Production Accelerates Demand for Door Hinges:
The consistent increase in global vehicle production is a primary driver of the automotive door hinges market. Both passenger and commercial vehicle segments are expanding in response to growing urbanization, rising disposable incomes, and industrial development in emerging economies. OEMs are ramping up production to meet local and export demand, directly increasing the consumption of mechanical components such as door hinges. These hinges are critical for vehicle structure, occupant safety, and accessibility, ensuring they remain indispensable in both standard and specialized vehicle designs. With the automotive industry expected to maintain a stable output trajectory, the requirement for high-performance, durable, and cost-effective hinges continues to rise. The automotive door hinges market benefits from this baseline growth in production volumes across all vehicle categories.
- For instance, Gestamp Automoción S.A. specializes in tailor-made steel hinges for structural applications, leveraging modular systems for high-volume production and supplying the global market in 2024.
Light weighting Trends Support Innovation in Materials and Design:
OEMs and suppliers are increasingly focused on lightweight materials in response to regulatory pressures and energy efficiency targets. The shift toward fuel efficiency and electric vehicle (EV) performance has elevated the role of components like door hinges in overall weight management. Automakers are replacing conventional steel hinges with those made of aluminum alloys, high-strength steel, and composite materials to reduce curb weight without compromising structural integrity. These advanced materials offer corrosion resistance and longer life cycles, aligning with the industry’s evolving durability standards. The automotive door hinges market supports this transformation by introducing lighter, high-performance alternatives that improve fuel economy and battery range in EVs. It continues to evolve through material innovation and design optimization.
- For instance, Magna International’s lightweight hinge solutions are designed specifically for electric vehicles and luxury models, aligning with stricter CO₂ emission targets—particularly in Europe, where aluminum hinge adoption is highest.
Technological Advancements Elevate Hinge Functionality and Safety:
Beyond structural performance, hinge technology is advancing to meet consumer expectations and OEM requirements for comfort, quiet operation, and vehicle safety. Features such as multi-stage hinges, anti-pinch functions, noise-reduction coatings, and automated soft-close mechanisms are becoming standard in premium segments. These innovations improve door operation, reduce wear and tear, and contribute to overall user experience. Advanced hinge systems also enhance side-impact protection and passenger safety during collisions. The automotive door hinges market is responding with solutions that integrate precision engineering and mechanical reliability to meet new design and regulatory benchmarks. It enables manufacturers to differentiate vehicle platforms while ensuring long-term operational stability.
Aftermarket Growth and Customization Trends Enhance Market Appeal:
The aging vehicle fleet across mature economies is fueling demand for replacement parts, creating robust opportunities in the aftermarket. Consumers seek durable, easy-to-install door hinges that restore or upgrade vehicle function, often looking for performance enhancements or aesthetic upgrades. E-commerce platforms and expanded distribution networks have made it easier for consumers and repair professionals to access specialized hinge types. Customization trends, particularly in off-road, vintage, and performance vehicles, are boosting interest in stylized or heavy-duty hinges. The automotive door hinges market supports this shift by offering a wide range of aftermarket solutions tailored to various vehicle models and performance expectations. It reinforces the market’s relevance beyond initial OEM applications.
Market Trends:
Integration of Smart and Electronic Hinges in High-End Vehicle Platforms:
Automotive manufacturers are increasingly integrating smart hinge technologies in premium and next-generation vehicles. These hinges incorporate electronic components that enable features such as power-assisted opening and closing, door position memory, and programmable operation settings. Smart hinges also support applications like automatic door alignment, obstacle detection, and remote control via mobile devices or key fobs. These innovations enhance convenience, accessibility, and user safety, particularly in luxury and electric vehicles. The automotive door hinges market is seeing growing demand for such advanced systems as automakers look to differentiate their offerings through digital and electromechanical integration. It is enabling a new category of intelligent hinge solutions that align with the automotive sector’s shift toward automation and user-centric design.
- For instance, Magna International also emphasizes advanced electronic latching and smart hinge integration for next-generation vehicles.
Rise of Flush-Mount and Concealed Hinges for Aesthetic Appeal:
Automakers are adopting flush-mount and concealed hinge systems to achieve cleaner exterior profiles and enhance vehicle aerodynamics. These hinges are designed to remain hidden from view when doors are closed, allowing for seamless surface transitions and improved styling. The trend aligns with consumer demand for minimalist and futuristic vehicle designs, especially in electric and crossover segments. Flush-mounted hinges also contribute to reduced wind resistance and noise levels, supporting both aesthetic and performance goals. The automotive door hinges market is seeing increased investment in compact, high-strength designs that can support the structural demands of these installations without compromising safety. It is adapting to accommodate the engineering complexity of invisible hinge applications across various vehicle categories.
- For instance, Multimatic Inc. develops custom flush-mount hinge systems for performance and luxury vehicles, prioritizing both aesthetics and structural performance.
Adoption of Modular and Pre-Assembled Hinge Units for Manufacturing Efficiency:
Vehicle manufacturers are streamlining assembly processes by using modular, pre-assembled hinge units that integrate mounting brackets, fasteners, and seals. These ready-to-install components reduce labor time, improve installation consistency, and minimize alignment errors during production. Tier-1 suppliers are expanding their modular hinge product lines to offer OEMs greater flexibility and production efficiency. These units also allow for easier standardization across multiple vehicle platforms, reducing inventory complexity and enhancing scalability. The automotive door hinges market is advancing to support this shift, with precision-manufactured components that meet diverse OEM specifications while maintaining high durability. It is reinforcing its role as a strategic partner in automotive manufacturing and platform development.
Sustainability-Focused Design and Use of Recyclable Materials:
Environmental concerns are influencing product design across the automotive sector, including door hinge systems. Manufacturers are increasingly using recyclable and environmentally friendly materials such as high-grade aluminum, reinforced polymers, and low-emission coatings. Sustainability is becoming a key factor in supplier selection, particularly among OEMs committed to reducing the carbon footprint of their supply chains. Innovations include hinges designed for easy disassembly and recyclability at end-of-life, supporting circular economy goals. The automotive door hinges market is aligning with these trends by offering eco-conscious product lines that meet performance standards without compromising environmental responsibility. It is reinforcing its position in a market where regulatory compliance and sustainability are becoming competitive differentiators.
Market Challenges Analysis:
Raw Material Price Volatility and Supply Chain Disruptions Impact Cost Structures:
Fluctuations in the prices of raw materials such as steel, aluminum, and specialty alloys present a significant challenge to hinge manufacturers. These materials account for a major portion of production costs, and any sudden price spikes or shortages can compress profit margins and affect delivery schedules. Supply chain disruptions caused by geopolitical tensions, trade restrictions, and logistics bottlenecks further exacerbate production uncertainty. OEMs expect suppliers to maintain both price stability and delivery consistency, which becomes difficult during periods of market volatility. The automotive door hinges market is exposed to these external risks, especially in a globalized sourcing environment. It requires robust procurement strategies and diversified supply networks to manage costs and ensure operational continuity.
High Customization Demands and Design Complexity Increase Engineering Burden:
Modern vehicle platforms often require highly specialized door hinge designs tailored to unique body styles, materials, and door mechanisms. This high level of customization introduces engineering challenges related to structural integrity, fatigue resistance, and fitment precision. Designing hinges that meet both aesthetic and performance specifications without increasing weight or manufacturing complexity is difficult. The need to comply with global safety regulations and evolving crash standards adds further constraints to hinge development. The automotive door hinges market must continuously invest in advanced simulation tools, prototyping, and testing to meet OEM expectations. It faces growing pressure to deliver innovative, application-specific solutions within tight development timelines and cost parameters.
Market Opportunities:
Growing Electric Vehicle Production Creates New Design and Supply Needs:
The rapid expansion of the electric vehicle (EV) segment presents a significant opportunity for hinge manufacturers to develop lightweight, high-performance components tailored to new vehicle architectures. EV platforms often demand compact, efficient, and quieter hinge mechanisms that align with their unique structural layouts and cabin configurations. Automakers seek advanced hinges that reduce door effort, enhance aerodynamics, and support innovative door formats such as suicide, butterfly, and gullwing designs. The automotive door hinges market can capitalize on this shift by offering EV-specific solutions that integrate functionality, safety, and aesthetics. It opens avenues for high-margin products and long-term supplier partnerships with emerging EV brands and established OEMs transitioning their portfolios.
Expanding Aftermarket Potential in Aging Vehicle Fleets:
Rising average vehicle age in key markets such as North America and Europe is fueling demand for high-quality replacement parts, including door hinges. Consumers increasingly look for durable, easy-to-install components that restore functionality or upgrade vehicle appearance. E-commerce platforms and digital catalogs make it easier for consumers and service centers to identify and purchase compatible hinges. The automotive door hinges market has an opportunity to strengthen its aftermarket presence by offering value-added products, bundled kits, and customizable options. It can grow revenue by addressing both functional repairs and personalization trends in older vehicle segments.
Market Segmentation Analysis:
By Product Type
Front door hinges account for the largest share due to their universal application across all vehicle types. Rear door hinges follow closely, particularly in passenger vehicles and SUVs. Tailgate hinges show strong demand in pickups and utility vehicles. Bonnet (hood) hinges maintain steady growth, supported by design enhancements in engine access systems.
- For instance, Aisin Seiki Co., Ltd. reported in 2024 that its latest front door hinge series, used in Toyota and Lexus models.
By Hinge Type
Butt hinges dominate the automotive door hinges market because of their widespread use in standard vehicle doors. Multi-leaf hinges are gaining traction in heavier applications such as trucks and SUVs due to their strength and load-bearing capabilities. Latch hinges and strap hinges hold niche roles in specialized and performance-oriented models.
- For instance, Multi-leaf hinges are gaining traction in heavier applications such as trucks and SUVs due to their strength and load-bearing capabilities. Latch hinges and strap hinges hold niche roles in specialized and performance-oriented models.
By Material
Steel remains the most widely used material for hinges, offering durability and cost-effectiveness. Aluminum is expanding its market share due to its lightweight properties and corrosion resistance, especially in EVs. Composite materials are gaining attention for premium and high-performance vehicles. Brass/bronze sees limited use in custom or specialized applications.
By Vehicle Type
Passenger cars lead the market owing to their high production volumes. Light commercial vehicles contribute significantly through utility applications, while heavy commercial vehicles require reinforced hinges, driving multi-leaf hinge adoption.
By Sales Channel
OEMs hold the majority share, driven by integration at the manufacturing stage. The aftermarket is growing steadily, supported by rising vehicle replacement and customization trends.
Segmentation:
By Product Type
- Front Door Hinges
- Rear Door Hinges
- Tailgate Hinges
- Bonnet (Hood) Hinges
By Hinge Type
- Butt Hinges
- Latch Hinges
- Multi-leaf Hinges
- Strap Hinges
By Material
- Steel
- Aluminum
- Composite Materials
- Brass/Bronze
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)
By Sales Channel
- OEM (Original Equipment Manufacturer)
- Aftermarket
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia Pacific – Largest and Fastest-Growing Market
Asia Pacific dominates the automotive door hinges market with a market share of over 45% in 2024, driven by high vehicle production and strong domestic demand in China, India, Japan, and South Korea. It benefits from large-scale automotive manufacturing hubs, favorable government policies, and rising electric vehicle adoption. China leads the region, supported by its robust supply chain and strong presence of global and local OEMs. India is experiencing rapid growth due to expanding middle-class income and increasing urbanization. Japan and South Korea contribute with advanced automotive technologies and a strong export base. The region continues to attract investments in lightweight components and automated production technologies, which sustain its leadership in hinge manufacturing.
Europe – Innovation and Regulatory Compliance Drive Demand
Europe holds around 25% of the automotive door hinges market, supported by strong regulatory frameworks and a focus on sustainable mobility solutions. Countries like Germany, France, and Italy lead in hinge innovation, lightweight materials adoption, and premium vehicle production. The region enforces strict CO₂ emission regulations, which push OEMs to integrate advanced, lightweight hinge systems. European manufacturers are also early adopters of smart and flush-mounted hinges for aerodynamic and design improvements. Demand for high-end vehicles and commercial vans further supports the market. OEM partnerships with Tier-1 suppliers foster continuous innovation in both materials and hinge mechanisms.
North America, Latin America, and Middle East & Africa – Steady and Emerging Opportunities
North America represents roughly 18% of the global market, with stable demand from both OEM and aftermarket sectors. The United States is the key contributor, supported by a mature automotive industry and high vehicle ownership rates. Latin America holds around 7% market share, showing gradual growth due to increasing industrialization, fleet expansion, and regional manufacturing initiatives, particularly in Brazil and Mexico. The Middle East & Africa account for nearly 5% of the market and remain at a nascent stage. Economic diversification, infrastructure development, and growing vehicle demand in Gulf countries and parts of Africa create moderate but promising opportunities. The automotive door hinges market in these regions is expected to grow steadily with rising investments in vehicle assembly operations.
Key Player Analysis:
- Magna International Inc.
- Aisin Seiki Co., Ltd.
- Gestamp Automoción S.A.
- Multimatic Inc.
- Dura Automotive LLC
- Brano Group
- Omax Autos Ltd.
- DEE Emm Giken
- ER Wagner
- Kiekert AG
Competitive Analysis:
The automotive door hinges market features a moderately consolidated competitive landscape, with leading players focusing on material innovation, production efficiency, and strategic partnerships. Key companies such as Magna International Inc., Aisin Seiki Co., Ltd., Gestamp Automoción S.A., and Multimatic Inc. maintain strong relationships with global OEMs by offering reliable, high-performance hinge systems. These firms invest heavily in R&D to support light weighting goals and meet evolving safety standards. Emerging players like DEE Emm Giken and Omax Autos Ltd. are expanding their presence through regional manufacturing and cost-competitive solutions. The market is witnessing a shift toward advanced hinge technologies, including flush-mounted and smart hinges, prompting established companies to enhance their product portfolios. The automotive door hinges market is competitive on both pricing and customization, with suppliers differentiating through precision engineering, corrosion resistance, and lifecycle performance. It continues to attract innovation-focused investment aimed at supporting electric vehicle integration and aftermarket expansion.
Recent Developments:
- In March 2025, Magna International Inc. announced a strategic partnership with NVIDIA to advance next-generation automotive technologies, including the integration of smart mechatronic systems for vehicle doors. Magna’s latest hinge technologies now feature lighter, high-strength alloys and are engineered to support advanced electronic locking and flush handle integration, aligning with the needs of EVs and luxury vehicles.
- In 2024, Gestamp Automoción S.A. expanded its manufacturing footprint by opening three new facilities and launching a new production line in India, one of the largest automotive markets globally. The company’s ongoing R&D investments have led to the introduction of tailor-made steel hinge systems designed for modular vehicle architectures and scalable production for both compact and heavy-duty vehicles.
Market Concentration & Characteristics:
The automotive door hinges market exhibits moderate concentration, with a mix of global Tier-1 suppliers and regional manufacturers competing across OEM and aftermarket channels. Leading players control a significant share through long-term contracts, technical expertise, and vertically integrated operations. The market favors companies with strong design capabilities, material science knowledge, and the ability to scale production efficiently. It is characterized by high entry barriers due to stringent quality standards, safety compliance, and the need for continuous innovation. The market demands product reliability, lightweight construction, and corrosion resistance, particularly in the context of electric vehicle platforms. Customization, cost optimization, and localized manufacturing also influence supplier selection, giving competitive advantage to firms that can balance performance with affordability. The automotive door hinges market remains stable, with innovation and platform-specific engineering shaping differentiation.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Hinge Type, By Material, By Vehicle Type, By Sales Channel and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The automotive door hinges market is expected to witness steady growth through 2032, driven by consistent global vehicle production.
- Lightweight material adoption will accelerate, with aluminum and composites gaining share in response to EV efficiency targets.
- OEM demand for flush-mounted and smart hinge technologies will rise, especially in luxury and electric vehicle segments.
- Aftermarket expansion will continue, fueled by aging vehicle fleets and increasing customization preferences.
- Asia Pacific will maintain its lead, supported by manufacturing scale, cost advantages, and growing regional demand.
- Europe will see innovation-led growth, with emphasis on sustainability, crash performance, and design integration.
- North America will remain stable, with a focus on high-strength hinge solutions and robust aftermarket activity.
- Stringent global safety and emissions regulations will influence hinge design, materials, and compliance costs.
- Supply chain resilience and raw material sourcing will remain strategic priorities for hinge manufacturers.
- Strategic partnerships and investments in automation will shape competitiveness and production efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Door Hinges Market?
What factors are driving the growth of the Automotive Door Hinges Market?
What are the key segments within the Automotive Door Hinges Market?
What are some challenges faced by the Automotive Door Hinges Market?
Who are the major players in the Automotive Door Hinges Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Door Hinges Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Door Hinges Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,444 million → 2032: USD 10,266.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Door Hinges Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Door Hinges Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Door Hinges Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Door Hinges Market Drivers
- 3.3 Automotive Door Hinges Market Restraints & Challenges
- 3.4 Automotive Door Hinges Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Door Hinges Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Door Hinges Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Door Hinges category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Door Hinges Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Door Hinges Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Door Hinges market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Door Hinges Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Door Hinges Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Door Hinges Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Door Hinges (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Door Hinges Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Door Hinges Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Door Hinges Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Door Hinges Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Door Hinges Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Door Hinges Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Door Hinges Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Door Hinges Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Door Hinges Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
