
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
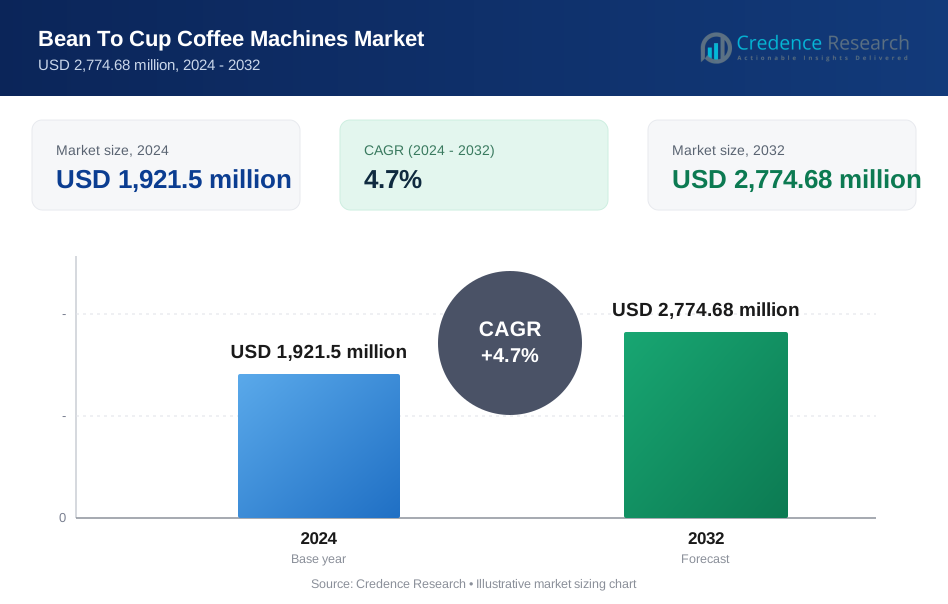
| Bean to Cup Coffee Machines Market Size 2024 | USD 1,921.5 Million |
| Bean to Cup Coffee Machines Market, CAGR | 4.7% |
| Bean to Cup Coffee Machines Market Size 2032 | USD 2,774.68 Million |
Market Overview
The Bean to Cup Coffee Machines Market is projected to grow from USD 1,921.5 million in 2024 to USD 2,774.68 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.7%.
The Bean to Cup Coffee Machines market is driven by the increasing demand for convenience and quality in coffee preparation, as consumers seek barista-style beverages at home. Rising coffee consumption, particularly among millennials and working professionals, fuels this trend. Additionally, advancements in technology, such as automated brewing processes and smart connectivity features, enhance user experience and product appeal. The growing focus on sustainability also encourages manufacturers to develop eco-friendly machines that utilize recyclable materials. Moreover, the expanding café culture and specialty coffee trends further support the market's growth, as consumers increasingly value high-quality, freshly brewed coffee.
The geographical analysis of the Bean to Cup Coffee Machines market reveals a robust demand across North America and Europe, collectively accounting for over 60% of the global market share. North America is driven by a strong coffee culture and preference for premium machines, while Europe emphasizes innovation and sustainability. Key players in the market include Jura Elektroapparate AG, DeLonghi S.p.A, and Nestle Nespresso S.A., which lead in technology and design. Additionally, Siemens AG and Electrolux AB contribute to market competitiveness through diverse product offerings and eco-friendly initiatives, catering to evolving consumer preferences.
Market Drivers
Growing Coffee Culture
The global rise in coffee consumption has significantly fueled demand for convenient and high-quality brewing solutions. As consumers become more discerning about their coffee, there is an increasing desire for machines that can replicate the quality of barista-made beverages. For instance, a survey by the National Coffee Association found that a significant number of millennials and working professionals prefer high-quality coffee machines that can deliver café-like experiences at home. This trend is particularly evident among millennials and working professionals, who seek the rich flavors and experiences typically found in cafés, driving the popularity of bean-to-cup coffee machines.
Convenience and Ease of Use
Bean-to-cup machines provide a seamless brewing experience with one-touch operation, requiring just a single button press to produce coffee. This convenience appeals to busy consumers who appreciate a hassle-free way to enjoy their favorite beverages. For example, consumer feedback highlights the ease of use and minimal maintenance as key factors in the growing adoption of these machines. Additionally, these machines significantly reduce the time and effort needed for cleaning and maintenance, making them ideal for both home and commercial environments.
Customization and Variety
Many bean-to-cup machines offer diverse beverage options, allowing users to prepare a wide range of drinks, including espresso, cappuccino, and lattes. The ability to customize settings further enhances the user experience, as individuals can tailor their coffee according to personal preferences, adjusting factors like strength, temperature, and grind size. This level of personalization caters to the growing trend of coffee connoisseurship, where consumers seek unique and tailored coffee experiences.
Technological Advancements
The integration of smart features in bean-to-cup machines marks a significant advancement in coffee brewing technology. These machines can connect with smart home devices and mobile apps, enabling remote control and the creation of personalized brewing profiles. Additionally, precision brewing technologies ensure consistent and optimal extraction, resulting in superior coffee quality. This blend of convenience and innovation drives the growing appeal of bean-to-cup coffee machines in both residential and commercial settings.
Market Trends
Premiumization and Customization
The trend towards premiumization in the bean-to-cup coffee machine market reflects consumers' increasing investment in high-end models that offer a wider variety of specialty drinks and advanced features. These premium machines are designed to meet the sophisticated tastes of coffee enthusiasts, allowing them to enjoy café-quality beverages at home. For instance, a survey by CoffeeBI highlighted that a significant number of consumers are willing to invest in high-end coffee machines that offer a variety of specialty drinks and advanced customization option. Customization is a key aspect of this trend, with many machines providing users with the ability to adjust settings such as strength, temperature, and grind size. This level of personalization caters to individual preferences, enabling consumers to create coffee that aligns perfectly with their tastes and desired experiences. As more people become coffee connoisseurs, the demand for machines that offer both premium features and customizable options continues to grow, reinforcing the trend of treating coffee preparation as an artisanal process rather than a routine chore.
Smart Technology Integration and Sustainability
The integration of smart technology into bean-to-cup machines is reshaping the way consumers interact with their coffee makers. Features such as smart home connectivity allow users to control their machines remotely, enabling them to schedule brewing times and adjust settings from their smartphones. Additionally, mobile apps provide personalized brewing profiles, real-time machine status updates, and maintenance alerts, enhancing the overall user experience. Alongside these technological advancements, there is a growing emphasis on sustainability within the industry. Manufacturers are increasingly developing energy-efficient models that minimize environmental impact while still delivering exceptional performance. The use of recyclable materials in machine construction is also gaining importance, reflecting consumer preferences for eco-friendly options. This focus on sustainability not only meets the demand for responsible consumerism but also positions brands favorably in a market that values environmental consciousness.
Market Challenges Analysis
Initial Cost and Consumer Education
One of the significant challenges in the bean-to-cup coffee machine market is the initial cost associated with high-quality machines. These premium models, which promise advanced features and superior coffee quality, can be prohibitively expensive, limiting access for a broader consumer base. For instance, a survey by the Specialty Coffee Association found that the high cost of premium coffee machines is a major barrier for many consumers. This financial barrier may discourage potential buyers who are unable to justify the investment, especially when considering the availability of more affordable brewing alternatives. Additionally, many consumers lack familiarity with the intricacies of bean-to-cup machines, leading to difficulties in effective usage. This gap in knowledge can result in frustration and dissatisfaction, ultimately diminishing the overall coffee experience. To address these issues, manufacturers are focusing on developing more budget-friendly models and providing comprehensive educational resources. By offering detailed user manuals, online tutorials, and customer support, they aim to enhance consumer confidence and ensure that users can maximize the potential of their machines.
Maintenance, Freshness, and Environmental Concerns
Another challenge for bean-to-cup coffee machines lies in the ongoing maintenance and cleaning required to ensure optimal performance and longevity. Regular upkeep is essential, as neglecting this aspect can lead to a decline in coffee quality and machine efficiency. The need for specific cleaning solutions and time-consuming procedures can deter some users, particularly those with busy lifestyles. Furthermore, maintaining the freshness of coffee beans presents its own set of hurdles. For infrequent users, improper storage can result in a significant decline in flavor, which diminishes the overall coffee experience. Users must also contend with hygiene concerns related to milk systems, as regular cleaning is necessary to prevent bacteria growth and maintain milk quality. These factors can be perceived as hassles for some consumers, particularly those who value convenience. Environmental impact is another pressing issue, particularly concerning energy consumption and waste generated by single-use pods. As more consumers become environmentally conscious, there is an increasing demand for sustainable practices. To counter these challenges, manufacturers are investing in smart technology to optimize bean freshness and milk quality, simplifying maintenance procedures, and developing eco-friendly designs that reduce energy consumption and promote sustainability. Through these efforts, they aim to create a more user-friendly and environmentally responsible coffee-making experience, catering to the evolving preferences of consumers.
Market Segmentation Analysis:
By Type:
The bean-to-cup coffee machine market can be segmented by type into fully automatic, super-automatic, and semi-automatic machines. Fully automatic coffee machines are designed for convenience, enabling users to brew their favorite coffee with minimal effort. These machines handle the entire brewing process, from grinding the beans to frothing milk, making them ideal for busy households and office environments. In contrast, super-automatic coffee machines provide advanced features, including programmable settings and customizable drink options, catering to coffee enthusiasts who desire a high degree of personalization. These machines appeal to consumers looking for premium coffee experiences without the need for extensive barista skills. Lastly, semi-automatic coffee machines require more user involvement in the brewing process, appealing to individuals who enjoy hands-on coffee preparation and seek to refine their brewing techniques. This segmentation highlights the diverse preferences among consumers, enabling manufacturers to target specific market niches effectively.
By Application:
The bean-to-cup coffee machine market is also segmented based on application into household and commercial sectors. In the household segment, the rising coffee culture and increasing consumer demand for convenience drive the adoption of bean-to-cup machines. Consumers are increasingly investing in these machines to replicate café-quality coffee at home, enhancing their daily coffee ritual. This segment benefits from trends such as premiumization, where consumers seek high-quality coffee experiences. On the other hand, the commercial segment includes restaurants, cafés, and office settings where efficiency and consistency are paramount. Bean-to-cup machines streamline operations, allowing establishments to serve high-quality coffee quickly while reducing labor costs. The need for consistent beverage quality in commercial applications further supports the growth of this segment. As both segments evolve, manufacturers are focusing on developing tailored solutions to meet the unique demands of household and commercial users, ultimately expanding their market reach and enhancing customer satisfaction.
Segments:
Based on Type:
- Fully Automatic Coffee Machine
- Super-Automatic Coffee Machine
- Semi-Automatic Coffee Machine
Based on Application:
- Household
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the bean-to-cup coffee machine market, accounting for approximately 35%. The increasing coffee culture, particularly in the United States and Canada, is a primary driver of this growth. Consumers in this region are increasingly seeking high-quality coffee experiences at home, leading to a surge in demand for convenient brewing solutions. Furthermore, the proliferation of specialty coffee shops and a growing preference for premium products contribute to the region's market expansion. Manufacturers are responding to these trends by offering advanced features such as customizable settings and smart technology integration, appealing to the discerning tastes of North American consumers. The presence of key players and innovative product launches also bolster the region's position in the global market.
Europe
Europe represents another crucial market for bean-to-cup coffee machines, holding a market share of approximately 30%. The region's rich coffee culture and tradition of high-quality espresso consumption drive the demand for sophisticated brewing solutions. European consumers are increasingly investing in premium coffee machines that offer various drink options and customizable features, aligning with the trend of premiumization. Moreover, the rise of compact and stylish designs caters to urban living spaces, further enhancing market growth. The commercial segment is also significant in Europe, with cafés and restaurants adopting bean-to-cup machines to provide consistent and high-quality coffee to their customers. The focus on sustainability and eco-friendly practices is also shaping the market, as manufacturers introduce energy-efficient models and recyclable materials in machine construction. This emphasis on quality and sustainability positions Europe as a leader in the bean-to-cup coffee machine market.
Key Player Analysis
- Electrolux AB
- Jura Elektroapparate AG
- DeLonghi S.p.A
- Melitta
- Siemens AG
- Gaggia
- Schaerer Ltd.
- Robert Bosch GmbH
- Panasonic Corporation
- Koninklijke Philips N.V.
- Krups
- Russell Hobbs
- Nestle Nespresso S.A.
Competitive Analysis
The competitive landscape of the Bean to Cup Coffee Machines market is characterized by innovation, product differentiation, and strategic partnerships among leading players. Jura Elektroapparate AG, DeLonghi S.p.A, Krups, Robert Bosch GmbH, Electrolux AB, Panasonic Corporation, Siemens AG, Koninklijke Philips N.V., Melitta, Nestle Nespresso S.A, Schaerer Ltd., Gaggia, and Russell Hobbs are at the forefront, each leveraging unique strengths. Companies are focusing on enhancing user experience through advanced features, such as smart technology integration and customizable brewing options. The emphasis on sustainability is growing, with many manufacturers prioritizing eco-friendly materials and energy-efficient designs to meet environmentally conscious consumer demands. Additionally, the market is witnessing aggressive marketing strategies and increasing investments in research and development to capture a larger market share. This dynamic environment requires adaptability and a commitment to customer-centric innovation, as companies strive to provide high-quality coffee solutions that cater to evolving consumer preferences.
Recent Developments
- In June 2024, Philips introduced the new Barista Brew Semi-Automatic Espresso Machine and expanded its LatteGo Full-Automatic Machine lineup with the 4400 and 5500 models.
Market Concentration & Characteristics
The market concentration of Bean to Cup Coffee Machines reflects a competitive landscape where a few key players dominate, yet a diverse range of brands contribute to overall market dynamics. Major manufacturers focus on product innovation, offering advanced features such as smart connectivity, customizable brewing options, and eco-friendly designs to differentiate their offerings. As consumer preferences evolve towards premium and convenient coffee solutions, companies are increasingly investing in research and development to enhance product functionality and quality. Additionally, the market exhibits a trend towards premiumization, with consumers willing to pay a higher price for machines that deliver barista-quality beverages at home. This concentration also encourages collaboration among companies, leading to strategic partnerships and mergers that can enhance market share and resource sharing. Consequently, the Bean to Cup Coffee Machines market is characterized by continuous innovation, a focus on sustainability, and an ongoing commitment to meeting the diverse needs of coffee enthusiasts.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Bean to Cup Coffee Machines market is expected to witness significant growth, driven by increasing coffee consumption globally.
- Consumers will continue to prioritize convenience, leading to higher demand for user-friendly, fully automated machines.
- Advanced features, such as smart home integration and app-based controls, will become standard in new models.
- There will be a growing trend towards premium and customizable coffee solutions to cater to discerning coffee enthusiasts.
- Manufacturers will focus on sustainability by developing energy-efficient machines and using eco-friendly materials.
- The market will see increased competition, encouraging innovation and diversification of product offerings.
- Subscription services for coffee beans and pods will become more prevalent, ensuring a consistent supply for consumers.
- Educational resources and tutorials will be essential in helping consumers navigate the complexities of Bean to Cup machines.
- The commercial sector will adopt these machines for enhanced operational efficiency and consistent beverage quality.
- Emerging markets in Asia and Africa will present new opportunities for growth as coffee culture expands in these regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bean to Cup Coffee Machines?
What factors are driving the growth of the Bean to Cup Coffee Machines?
What are the key segments within the Bean to Cup Coffee Machines?
What are some challenges faced by the Bean to Cup Coffee Machines?
Who are the major players in the Bean to Cup Coffee Machines?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bean To Cup Coffee Machines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bean To Cup Coffee Machines Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,921.5 million → 2032: USD 2,774.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bean To Cup Coffee Machines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bean To Cup Coffee Machines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bean To Cup Coffee Machines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bean To Cup Coffee Machines Market Drivers
- 3.3 Bean To Cup Coffee Machines Market Restraints & Challenges
- 3.4 Bean To Cup Coffee Machines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bean To Cup Coffee Machines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bean To Cup Coffee Machines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bean To Cup Coffee Machines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bean To Cup Coffee Machines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bean To Cup Coffee Machines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bean To Cup Coffee Machines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bean To Cup Coffee Machines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bean To Cup Coffee Machines Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bean To Cup Coffee Machines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bean To Cup Coffee Machines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bean To Cup Coffee Machines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bean To Cup Coffee Machines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bean To Cup Coffee Machines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bean To Cup Coffee Machines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bean To Cup Coffee Machines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bean To Cup Coffee Machines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bean To Cup Coffee Machines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bean To Cup Coffee Machines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bean To Cup Coffee Machines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
