
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Brazil Occupational Health Market Size 2023 | USD 7,327.22 Million |
| Brazil Occupational Health Market, CAGR | 6.33% |
| Brazil Occupational Health Market Size 2032 | USD 12,963.73 Million |
Market Overview
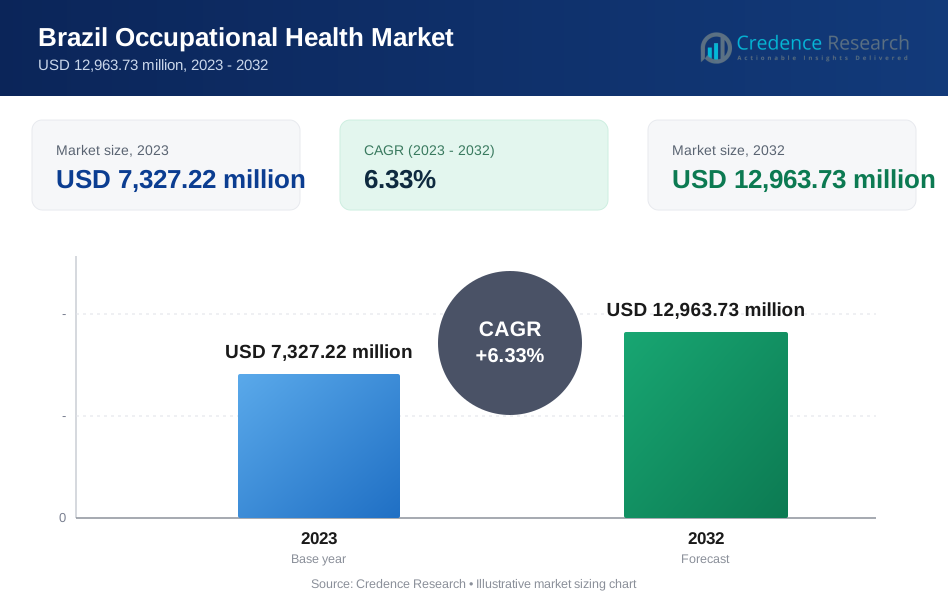
The Brazil Occupational Health Market is projected to grow from USD 7,327.22 million in 2023 to an estimated USD 12,963.73 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 6.33% during the forecast period from 2024 to 2032. This growth underscores the increasing importance of occupational health services in ensuring employee well-being and compliance with workplace safety regulations.
Key drivers of the Brazil Occupational Health market include stringent government regulations mandating employee health and safety standards, increasing awareness of workplace wellness, and a rise in chronic diseases linked to occupational hazards. Emerging trends such as the integration of digital technologies in health monitoring, the adoption of preventive healthcare measures, and a focus on mental health services are shaping the industry's evolution. The shift towards comprehensive occupational health solutions is also driving investments in this sector.
Geographically, major urban and industrial hubs such as São Paulo and Rio de Janeiro dominate the market due to high workplace concentrations and greater adoption of occupational health programs. However, growth opportunities are emerging in smaller cities and rural areas driven by expanding industrial activities. Key players in the market include Grupo Fleury, Qualicorp Consultoria e Corretora de Seguros S.A., Intermédica Saúde, and Amil Assistência Médica Internacional S.A., which are actively enhancing service portfolios and expanding their reach to meet the growing demand.
Market Drivers
Stringent Government Regulations and Workplace Safety Standards
One of the primary drivers of the Brazil Occupational Health market is the enforcement of stringent government regulations aimed at ensuring employee health and workplace safety. Brazil's labor laws, such as the Consolidation of Labor Laws (CLT), mandate that companies implement comprehensive occupational health and safety programs. Employers are required to comply with legal standards for periodic health evaluations, risk assessments, and medical exams to prevent workplace accidents and illnesses. For instance, in 2022, Brazil recorded approximately 50,493,061 beneficiaries of supplementary health services, highlighting the extensive reach of these regulations and their role in shaping workplace safety standards across various industries. The regulatory environment compels organizations to invest in robust occupational health solutions to avoid penalties and legal liabilities. Additionally, increasing inspections by labor authorities reinforce adherence to workplace safety norms. Between 2010 and 2022, there was a 233% increase in reported cases of intoxications related to occupational exposure to pesticides, emphasizing the need for compliance and proactive adoption of occupational health programs to mitigate such risks. These measures not only enhance employee well-being but also foster a culture of safety across industries, fueling market growth.
Increasing Incidence of Work-Related Illnesses and Chronic Conditions
The rising prevalence of work-related illnesses and chronic conditions among Brazil's workforce significantly drives the demand for occupational health services. Industrial and manufacturing sectors expose employees to occupational hazards such as noise pollution, chemical exposure, and ergonomic risks, contributing to illnesses like respiratory disorders, hearing loss, and musculoskeletal issues. Moreover, the sedentary nature of work in corporate settings has led to an increase in lifestyle-related chronic diseases such as diabetes, hypertension, and cardiovascular conditions. Employers are recognizing the financial and operational impact of such health issues, which include decreased productivity and increased absenteeism. Consequently, organizations are proactively adopting occupational health programs to mitigate risks, promote early diagnosis, and implement preventive measures to enhance workforce well-being.
Rising Awareness of Workplace Wellness and Mental Health
There is a growing awareness of the importance of workplace wellness programs, particularly those addressing mental health challenges. Employees increasingly demand healthier work environments that prioritize both physical and mental well-being. Stress, burnout, and anxiety-exacerbated by demanding work schedules and economic pressures-have become critical concerns in Brazil.Organizations are responding by integrating mental health services into their occupational health offerings. This includes counseling sessions, stress management workshops, and mental health awareness campaigns. Notably, 1 in 7 workers in Brazil is covered by social security benefits related to work-related disabilities, indicating a growing recognition of the importance of mental and physical well-being in the workplace. The emphasis on a holistic approach to employee health has spurred the adoption of preventive healthcare strategies, shifting the focus from reactive treatment to proactive wellness initiatives. This trend aligns with global best practices and contributes to the expanding scope of occupational health services in Brazil.
Technological Advancements and Digital Integration in Occupational Health
The adoption of advanced technologies and digital solutions is transforming the occupational health landscape in Brazil. Companies are increasingly leveraging telemedicine, wearable devices, and health monitoring apps to enhance the delivery of occupational health services. Telemedicine platforms facilitate remote consultations, reducing barriers to access and enabling timely health assessments. Wearable technologies, such as fitness trackers and biosensors, provide real-time data on employee health metrics, allowing organizations to implement data-driven preventive measures. Moreover, the integration of artificial intelligence (AI) and big data analytics is helping employers predict health trends, identify high-risk employees, and design personalized health programs. These innovations not only improve the efficiency of occupational health services but also make them more accessible and cost-effective, further boosting market growth.
Market Trends
Integration of Digital Technologies and Telemedicine in Occupational Health
One of the most prominent trends in the Brazil Occupational Health market is the widespread adoption of digital technologies and telemedicine services. Companies are increasingly integrating advanced tools such as wearable health devices, mobile health applications, and telemedicine platforms into their occupational health programs. These technologies enable real-time monitoring of employees' health metrics, ensuring early detection of potential issues and promoting preventive care. For instance, the Brazilian Unified Health System (SUS) has implemented the Telehealth program, which facilitates remote consultations and enhances access to healthcare services across the country. This initiative has enabled healthcare professionals to provide support through video calls and messaging, significantly improving service delivery, especially in remote areas where access to specialists is limited. During the COVID-19 pandemic, telemedicine usage surged as a response to public health needs. A study indicated that teleconsultations became a vital part of healthcare delivery, with institutions like HCFMUSP converting a significant portion of in-person visits to teleconsultations. In 2021 alone, they achieved a conversion rate of 15% for face-to-face consultations to teleconsultations, demonstrating the effectiveness of this approach in maintaining patient care while adhering to safety protocols.Telemedicine has become a key component, offering remote consultations that reduce the need for in-person visits while increasing accessibility, particularly in remote and underserved areas. Employers are leveraging artificial intelligence (AI) and big data analytics to analyze health patterns, predict workplace health risks, and customize wellness initiatives for employees. This trend not only enhances the efficiency and scalability of occupational health services but also aligns with the growing demand for technology-driven healthcare solutions in Brazil.
Rising Focus on Mental Health and Holistic Workplace Wellness Programs
The increasing recognition of mental health as a critical component of employee well-being is reshaping occupational health services in Brazil. Employers are expanding their focus from purely physical health to holistic wellness programs that address mental and emotional health challenges. Initiatives such as stress management workshops, employee assistance programs, and mental health awareness campaigns are becoming integral to workplace health strategies.This shift is particularly relevant as organizations adapt to hybrid work models that have emerged post-pandemic, emphasizing the need for comprehensive mental health support. Companies are increasingly recognizing the importance of addressing mental well-being alongside physical health. For instance, many organizations are incorporating mental health services into their occupational health offerings to foster a supportive work environment, boost employee morale, and enhance productivity. This evolving focus reflects a global trend and underscores the changing priorities of the Brazilian workforce and employers alike.
Market Restraints and Challenges
High Costs of Implementing Comprehensive Occupational Health Programs
The significant financial investment required to implement and maintain occupational health programs is a major restraint in the Brazil Occupational Health market. Many small and medium-sized enterprises (SMEs), which constitute a large portion of Brazil's economic landscape, struggle to allocate sufficient budgets for these services. Costs associated with regular health evaluations, advanced diagnostic technologies, and compliance with stringent government regulations can be prohibitive for businesses with limited resources. Additionally, the adoption of digital health technologies, such as wearable devices and telemedicine platforms, requires substantial upfront investment in infrastructure and training, which poses a challenge for companies with constrained financial capabilities. These cost barriers limit the widespread adoption of comprehensive occupational health initiatives, particularly in smaller cities and rural areas, impeding the market’s growth potential.
Limited Awareness and Cultural Barriers
Despite growing recognition of workplace health and safety, a lack of awareness about the importance of occupational health persists among certain segments of employers and employees in Brazil. In industries with a predominantly informal workforce, occupational health and safety are often deprioritized, leading to insufficient implementation of health programs. Additionally, cultural attitudes that view occupational health as a compliance requirement rather than a strategic investment in workforce productivity hinder the market’s progression. Resistance to change, particularly in traditional industries, further complicates the adoption of innovative health and safety practices. Moreover, employees may hesitate to participate in wellness programs due to privacy concerns or fear of stigmatization, particularly in mental health-related initiatives. These challenges highlight the need for targeted awareness campaigns and cultural shifts to foster a more proactive approach to occupational health in Brazil.
Market Segmentation Analysis
By Product
The Product segment in the Brazil Occupational Health market is driven by diverse needs across industries. Personal Protective Equipment (PPE) holds a significant share, propelled by stringent workplace safety regulations and demand in high-risk sectors like construction and mining. The use of safety signage is growing as businesses prioritize regulatory compliance and accident prevention. First aid kits remain a universal requirement across industries, providing essential immediate care for workplace injuries. Meanwhile, the demand for ergonomic furniture and equipment is rising in corporate offices due to increased awareness of workplace ergonomics. Additionally, concerns about airborne pollutants in sectors such as manufacturing and oil and gas are boosting the adoption of respiratory protection equipment, further diversifying the product landscape.
By Service
Occupational health services in Brazil are increasingly diverse, addressing critical workplace needs. Employers are investing in pre-employment health screenings to ensure workforce fitness and regulatory compliance, while health surveillance and monitoring play a crucial role in identifying occupational hazards and safeguarding long-term employee safety. Health risk assessments enable organizations to evaluate workplace risks and implement preventive measures. The growing emphasis on employee well-being has fueled demand for health promotion and wellness programs, including mental health support initiatives. Additionally, the enduring impact of the COVID-19 pandemic has highlighted the significance of vaccination and immunization services, which continue to be integral to workplace health strategies.
Segments
Based on Type
- Product
- Services
Based on Product
- Personal Protective Equipment (PPE)
- Safety Signage
- First Aid Kits
- Ergonomic Furniture and Equipment
- Respiratory Protection Equipment
Based on Service
- Pre-Employment Health Screening
- Health Surveillance and Monitoring
- Health Risk Assessment
- Health Promotion and Wellness Programs
- Vaccination and Immunization Services
Based on Vertical
- Manufacturing and Construction
- Healthcare
- Oil and Gas and Mining
Based on Enterprise Size
- Large Enterprises
- SMEs
Based on Region
- Southeast Region
- South Region
- Northeast Region
- Midwest Region
- North Region
Regional Analysis
Southeast Region (45%)
The Southeast region accounts for the largest share of the Brazil Occupational Health market, contributing approximately 45% of the total market. This dominance is attributed to its industrialized economy, high concentration of manufacturing and corporate offices, and stringent adherence to occupational health regulations. São Paulo and Rio de Janeiro, in particular, are economic powerhouses where organizations prioritize employee well-being to meet compliance standards and enhance productivity. The region's advanced healthcare infrastructure further supports the development and delivery of occupational health services.
South Region (25%)
The South region holds around 25% of the market share, driven by its well-established industrial base, particularly in manufacturing, agribusiness, and automotive sectors. Companies in this region are proactive in adopting occupational health programs to reduce workplace hazards and ensure employee safety. The strong presence of SMEs in this region has also contributed to the increasing demand for affordable and scalable health solutions.
Key players
- MedSal
- PLBrasil Group
- Occucare
- Nexo CS
Competitive Analysis
The Brazil Occupational Health market is highly competitive, with key players focusing on expanding their service offerings, enhancing technology integration, and complying with stringent regulatory requirements. MedSal, a leading player, leverages its comprehensive product portfolio and strategic business approach to maintain its strong market position. PLBrasil Group and Occucare emphasize customer-centric solutions, offering tailored health and safety services to diverse industries. Nexo CS stands out for its innovative use of technology, such as digital platforms for health monitoring and compliance management. Other players contribute to market dynamics by addressing niche demands and penetrating underserved regions. The competitive landscape is shaped by ongoing investments in research and development, partnerships, and geographic expansion. Companies that prioritize cost-effective and scalable solutions, particularly for SMEs, are well-positioned to capitalize on emerging growth opportunities in the Brazil Occupational Health market.
Recent Developments
- In March 2024, the Brazilian Federal Council of Medicine (CFM) issued a resolution mandating the registration of occupational health services. This regulation emphasizes the need for accountability and quality in occupational health practices, which MedSal is expected to align with as it enhances its service offerings in compliance with these new guidelines.
- In September 2022, PLBrasil Group launched a new telemedicine platform designed specifically for occupational health. This platform aims to facilitate remote consultations and health monitoring for employees, thereby improving access to healthcare services in corporate environments. The initiative aligns with the CFM's recent authorization of telemedicine in occupational health settings.
- In early 2023, Occucare announced an expansion of its telehealth services to include mental health support as part of its occupational health programs. This expansion reflects a growing recognition of the importance of mental well-being in workplace health strategies, particularly as organizations adapt to hybrid work models post-pandemic.
- In January 2024, Nexo CS introduced a comprehensive wellness program that integrates digital health solutions with traditional occupational health services. This program focuses on preventive care and employee engagement, leveraging data analytics to tailor wellness initiatives to specific workforce needs.
Market Concentration and Characteristics
The Brazil Occupational Health market exhibits a moderately fragmented concentration, characterized by the presence of several established players alongside emerging local and regional service providers. Larger companies, such as MedSal and PLBrasil Group, dominate the market with extensive service portfolios, advanced technological integration, and strong geographic reach, particularly in industrialized regions. However, smaller players and niche providers cater to specific industries or regional demands, fostering competition and innovation. The market is driven by the need for compliance with stringent labor laws, increasing awareness of workplace safety, and the adoption of preventive healthcare solutions. A key characteristic of this market is the growing focus on digitalization, such as telemedicine and wearable technologies, to improve service delivery. The market also reflects a shift towards holistic health programs, addressing both physical and mental well-being, further enhancing its competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Service, Vertical, Enterprise Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook
- The Brazil Occupational Health market is expected to grow significantly, reaching USD 12,963.73 million by 2032, driven by a CAGR of 6.33% from 2024 to 2032.
- The integration of telemedicine, wearable devices, and AI-driven health analytics will continue transforming occupational health services, enhancing accessibility and efficiency.
- Rising awareness of mental health in workplaces will drive the adoption of wellness programs focusing on stress management, emotional well-being, and employee assistance initiatives.
- Government regulations mandating stricter compliance with workplace safety and health standards will compel businesses to invest more in occupational health solutions.
- Small and medium enterprises will increasingly adopt cost-effective and scalable occupational health programs, supported by government incentives and affordable digital solutions.
- Organizations will prioritize preventive healthcare measures, such as regular health risk assessments and early diagnostics, to reduce employee absenteeism and enhance productivity.
- Emerging regions like the Midwest and Northeast will witness increased adoption of occupational health services due to industrial expansion and improved healthcare infrastructure.
- Sectors such as construction, mining, and oil and gas will drive significant demand for specialized health solutions to mitigate workplace hazards and ensure compliance.
- Occupational health companies will partner with technology providers to deliver innovative solutions, such as predictive health analytics and customized wellness platforms.
- The market will evolve to offer holistic programs addressing both physical and mental health, aligning with global trends and improving employee well-being and satisfaction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Government Regulations and Workplace Safety Standards
Brazil's labor laws require companies to implement comprehensive occupational health and safety programs, including regular health evaluations and risk assessments. This regulatory environment compels organizations to invest in occupational health solutions to avoid penalties and legal liabilities, driving market growth.
Increasing Incidence of Work-Related Illnesses and Chronic Conditions
The rise in occupational hazards and chronic diseases among Brazil's workforce, particularly in industrial and manufacturing sectors, is prompting employers to adopt occupational health programs for early diagnosis and prevention, thereby boosting demand for these services.
Rising Awareness of Workplace Wellness and Mental Health
Growing recognition of the importance of both physical and mental well-being in the workplace is leading organizations to expand their occupational health offerings to include mental health support, stress management, and holistic wellness programs.
Technological Advancements and Digital Integration
The adoption of telemedicine, wearable devices, and AI-driven analytics is transforming occupational health service delivery in Brazil, making it more accessible, efficient, and cost-effective, and encouraging broader adoption across regions and enterprise sizes.
Expansion of Industrial Activities in Emerging Regions
Industrial growth in Brazil's Midwest and Northeast regions is creating new demand for occupational health services, as companies in these areas seek to comply with regulations and protect employee health in expanding industrial hubs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Brazil Occupational Health market in 2023 and 2032, and what is its CAGR?
What are the key factors driving the growth of the Brazil Occupational Health market?
How is technology impacting the Brazil Occupational Health market?
Which regions in Brazil dominate the Occupational Health market?
What role do mental health services play in the Brazil Occupational Health market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Product
- 1.2.2 Services
- 1.3 By Product
- 1.3.1 Personal Protective Equipment (PPE)
- 1.3.2 Safety Signage
- 1.3.3 First Aid Kits
- 1.3.4 Ergonomic Furniture and Equipment
- 1.3.5 Respiratory Protection Equipment
- 1.4 By Service
- 1.4.1 Pre-Employment Health Screening
- 1.4.2 Health Surveillance and Monitoring
- 1.4.3 Health Risk Assessment
- 1.4.4 Health Promotion and Wellness Programs
- 1.4.5 Vaccination and Immunization Services
- 1.5 By Vertical
- 1.5.1 Manufacturing and Construction
- 1.5.2 Healthcare
- 1.5.3 Oil and Gas and Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7,327.22 million → 2032: USD 12,963.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Brazil Occupational Health Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Brazil Occupational Health Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Brazil Occupational Health Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Brazil Occupational Health Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Brazil Occupational Health Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Brazil Occupational Health Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Brazil Occupational Health Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Brazil Occupational Health Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,327.22 million → 2032: USD 12,963.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Brazil Occupational Health Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Product
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Protective Equipment (PPE)
- 12.4.7.2 Safety Signage
- 12.4.7.3 First Aid Kits
- 12.4.7.4 Ergonomic Furniture and Equipment
- 12.4.7.5 Respiratory Protection Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pre-Employment Health Screening
- 12.5.7.2 Health Surveillance and Monitoring
- 12.5.7.3 Health Risk Assessment
- 12.5.7.4 Health Promotion and Wellness Programs
- 12.5.7.5 Vaccination and Immunization Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vertical - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Manufacturing and Construction
- 12.6.7.2 Healthcare
- 12.6.7.3 Oil and Gas and Mining
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Brazil Occupational Health End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Brazil Occupational Health Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Brazil Occupational Health Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Brazil Occupational Health Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 MedSal
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PLBrasil Group
- 18.4 Occucare
- 18.5 Nexo CS
- 18.6 Grupo Fleury
- 18.7 Qualicorp Consultoria e Corretora de Seguros S.A.
- 18.8 Intermédica Saúde
- 18.9 Amil Assistência Médica Internacional S.A.
- 18.10 Unimed
- 18.11 Allianz Partners Brazil
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

