
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chip Resistor Market Size 2024 | USD 2,103.63 million |
| Chip Resistor Market, CAGR | 7.27% |
| Chip Resistor Market Size 2032 | USD 500.86 million |
Market Overview:
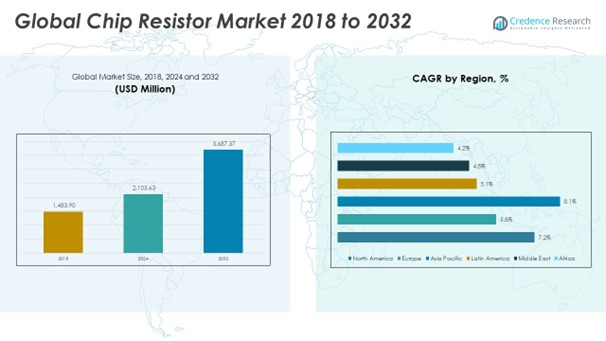
The Global Chip Resistor Market size was valued at USD 1,483.90 million in 2018 to USD 2,103.63 million in 2024 and is anticipated to reach USD 3,687.37 million by 2032, at a CAGR of 7.27% during the forecast period.
Several factors are propelling the growth of the chip resistor market. The proliferation of consumer electronics, including smartphones, laptops, and wearable devices, necessitates the integration of chip resistors to manage and control electrical currents efficiently. In the automotive sector, the shift towards electric and autonomous vehicles has increased the reliance on electronic components, thereby boosting the demand for chip resistors. Furthermore, the expansion of 5G networks and the Internet of Things (IoT) ecosystem requires robust electronic infrastructures, where chip resistors play a critical role in ensuring device reliability and performance. The miniaturization of electronic devices is driving the need for compact resistors with enhanced thermal stability and precision. Additionally, industrial automation and smart manufacturing systems rely heavily on chip resistors to maintain circuit accuracy and equipment safety.
Regionally, Asia-Pacific dominates the chip resistor market, accounting for a significant portion of the global demand. This dominance is attributed to the region's robust electronics manufacturing industry, particularly in countries like China, Japan, and South Korea. The presence of major consumer electronics manufacturers and the rapid adoption of electric vehicles in these countries contribute significantly to the market's growth. North America and Europe also hold substantial market shares, driven by technological advancements and the presence of key automotive and industrial players. The Middle East and Africa, along with Latin America, are emerging markets with growing potential, fueled by increasing investments in infrastructure and technology. Government initiatives supporting domestic electronics production and the rise of local component manufacturers further strengthen regional growth dynamics. Strategic partnerships and supply chain expansions across these regions are also reshaping the competitive landscape.
Market Insights:
- The market is projected to grow from USD 2,103.63 million in 2024 to USD 3,687.37 million by 2032, registering a CAGR of 7.27%.
- Rising demand for smartphones, laptops, and wearables is driving adoption of compact and thermally stable chip resistors.
- The shift to electric and autonomous vehicles is increasing the use of chip resistors in powertrains, battery systems, and safety electronics.
- 5G rollout and IoT expansion require high-frequency-capable resistors to ensure stable signal performance in connected devices.
- Industrial automation and smart manufacturing are fueling demand for precision resistors in control systems and robotics.
- Raw material price volatility remains a key challenge, impacting production costs and pricing flexibility across manufacturers.
- Asia-Pacific leads the market with strong manufacturing presence, while North America and Europe show stable demand from advanced automotive and industrial sectors.
Market Drivers:
Rising Demand for Consumer Electronics Fuels Market Expansion
The growing use of consumer electronics is a major driver of the Global Chip Resistor Market. Smartphones, tablets, laptops, gaming consoles, and wearable devices require precise voltage regulation and current flow control, which chip resistors provide. The trend toward smaller, lighter, and more power-efficient devices has increased the demand for compact resistors with high reliability and thermal stability. Manufacturers are optimizing resistor designs to fit into increasingly miniaturized circuit boards without compromising performance. This demand aligns with the continuous rollout of smart devices in both developed and emerging markets. The surge in personal electronics ownership has created a consistent need for large-scale production of chip resistors across supply chains.
Growth in Automotive Electronics Boosts Integration Needs
The transition toward electric vehicles (EVs) and advanced driver assistance systems (ADAS) is accelerating the use of electronic components in the automotive industry. Chip resistors support a wide range of automotive applications including battery management, motor control units, infotainment systems, and braking systems. The harsh operational environment within vehicles requires resistors with high-temperature tolerance, low TCR (temperature coefficient of resistance), and long-term durability. The Global Chip Resistor Market benefits from this shift, as it supports the increasing electrification and automation of vehicles. Automakers are pushing for more integrated and compact electronics, leading to greater adoption of high-precision resistors. The need for advanced circuit protection and stability in automotive platforms further fuels this growth.
- For instance, Bourns’ CRT-A Series offers tight resistance tolerance and low TCR in an SMD package, meeting AEC-Q200 standards and providing enhanced signal quality in space-constrained automotive modules such as DDR memory and camera systems.
Expansion of 5G Networks and IoT Drives High-Frequency Application Growth
The deployment of 5G infrastructure and the proliferation of Internet of Things (IoT) devices are transforming connectivity demands across industries. These technologies require reliable and high-frequency-compatible components, placing chip resistors at the core of network equipment and smart devices. In 5G base stations, routers, and consumer electronics, chip resistors help stabilize signals and ensure proper impedance matching. IoT applications in smart homes, healthcare, agriculture, and logistics rely on stable and energy-efficient circuitry enabled by resistors. The Global Chip Resistor Market supports this digital ecosystem by supplying components that meet stringent performance and miniaturization criteria. This trend will continue as smart device integration expands across urban and industrial environments.
Industrial Automation and Smart Manufacturing Elevate Market Relevance
The industrial sector is embracing automation, robotics, and smart manufacturing practices to improve productivity and operational efficiency. Chip resistors play a critical role in industrial control systems, sensors, and power management modules, ensuring precise functionality in automated processes. These components are integral to maintaining circuit stability in harsh industrial settings, where temperature fluctuations and vibrations are common. The demand for reliable electronics in factories, warehouses, and energy plants is rising, contributing to the growth of the Global Chip Resistor Market. Manufacturers are investing in high-performance resistor technologies to meet the evolving needs of Industry 4.0. This shift is reshaping production strategies and enhancing the importance of passive electronic components in complex industrial environments.
- For instance, Samsung’s high-power chip resistors provide approximately three times the power capability of general products, supporting power management modules and control systems in automated factories.
Market Trends:
Miniaturization of Electronic Components Accelerates Design Innovation
The continuous push toward smaller and more efficient electronic devices is shaping trends across the Global Chip Resistor Market. Consumer and industrial applications demand compact, high-performance components that occupy minimal space on circuit boards. Manufacturers are developing resistors with tighter tolerance, higher power density, and improved thermal performance to support this trend. Thin-film and thick-film chip resistors are gaining traction due to their ability to handle miniaturized layouts without compromising reliability. These innovations help meet the needs of modern electronic design, where space constraints are critical. The trend is particularly prominent in smartphones, medical devices, and wearable electronics where compactness is non-negotiable.
- For instance, ROHM’s MCRx family of chip resistors, including the high-power MCRS series and low-resistance MCRL series, are engineered for miniaturization and enhanced performance.
High-Reliability Resistors Gain Prominence in Critical Applications
Market demand for high-reliability chip resistors is increasing across sectors that require consistent performance under harsh conditions. Aerospace, automotive, and industrial automation sectors rely on resistors that can maintain electrical integrity across extreme temperatures, humidity, and vibration levels. Manufacturers are responding by introducing resistors with enhanced load life, moisture resistance, and failure-rate reduction features. The Global Chip Resistor Market supports this demand by offering components built to meet rigorous safety and quality standards. This shift toward high-reliability designs reflects growing concerns about system failures in mission-critical applications. It also reinforces the role of chip resistors in enabling long-term operational stability.
- For instance, YAGEO’s VT Series, developed automotive-grade thin-film chip resistors that feature high voltage tolerance, precision, and stability. These resistors incorporate a unique laser trimming design for superior voltage endurance and consistent resistance stability, and are AEC-Q200 qualified for use in demanding automotive, telecom, industrial, and medical applications.
Integration of Smart Features Drives Functional Advancements
The trend toward smart electronics is encouraging the integration of multifunctional passive components. Chip resistors are increasingly engineered to offer more than resistance-they also contribute to temperature sensing, surge protection, and noise suppression. This convergence of functionality helps reduce part count on circuit boards while maintaining performance and cost efficiency. It aligns with broader industry efforts to streamline product design and reduce assembly complexity. The Global Chip Resistor Market is adapting to these changes by investing in advanced materials and production technologies. This evolution supports the development of next-generation electronic systems with higher intelligence and lower power consumption.
Surging Demand from Renewable Energy and EV Sectors Shapes Product Development
Renewable energy systems and electric vehicles are reshaping the demand landscape for chip resistors. In solar inverters, battery management systems, and EV powertrains, resistors must handle high voltage and fluctuating current loads. Manufacturers are focusing on developing resistors with high energy handling capability, pulse durability, and thermal stability to serve these applications. The Global Chip Resistor Market is responding with innovations tailored to clean energy and sustainable transportation systems. The rise of green technology investments globally is accelerating this trend, pushing producers to meet the requirements of power electronics. It is positioning chip resistors as essential components in building a resilient and energy-efficient infrastructure.
Market Challenges Analysis:
Price Volatility of Raw Materials Impacts Production Stability
Fluctuations in the prices of raw materials, such as metal oxides and precious metals used in chip resistor manufacturing, pose a consistent challenge to producers. These materials directly influence production costs, impacting profit margins for manufacturers across different regions. The dependency on global metal supply chains exposes the industry to disruptions caused by geopolitical tensions, mining restrictions, and trade policies. Smaller manufacturers in particular face difficulty absorbing sudden price hikes, which may lead to production delays or reduced output. The Global Chip Resistor Market remains sensitive to these cost variables, which can affect pricing strategies and overall competitiveness. Managing this volatility requires strategic sourcing and long-term supplier agreements, which not all companies can secure.
Technological Complexity Limits Standardization Across Applications
The rapid evolution of electronics technologies presents difficulties in maintaining standardized resistor designs across industries. Each application, whether in automotive, telecommunications, or consumer electronics, demands specific tolerance levels, temperature coefficients, and power ratings. This need for customization complicates mass production and increases the cost of R&D. Manufacturers must invest in advanced testing and quality assurance to meet varied specifications, which may slow time-to-market for new products. The Global Chip Resistor Market faces challenges in balancing customization with scalability, especially under increasing demand pressure. This fragmentation of design requirements often leads to inefficiencies in production and inventory management.
- For instance, Panasonic’s ERA-3A Series thin-film chip resistors are offered in highly precise variants (such as 10ppm, 0.05% tolerance in the 0603 case size) specifically to serve demanding automotive environments, where high reliability and accuracy are essential.
Market Opportunities:
The development of smart cities and the digitization of infrastructure create new opportunities for chip resistor manufacturers. Smart grids, intelligent traffic systems, surveillance networks, and automated public services depend on reliable electronic components. These applications require chip resistors with high endurance, precision, and compact design to support continuous operation in diverse environments. Governments and private sectors are investing heavily in digital infrastructure, which broadens the application base for resistors. The Global Chip Resistor Market benefits from this trend by aligning product innovation with the needs of urban connectivity and automation. It supports long-term adoption in civic, environmental, and industrial monitoring systems.
The increasing demand for portable medical electronics and health monitoring devices opens a promising avenue for resistor integration. Wearables, diagnostic tools, and implantable devices rely on ultra-small, highly reliable resistors that operate without failure in critical use cases. The rise of remote healthcare and telemedicine strengthens the need for accurate, energy-efficient components. Manufacturers have the opportunity to develop specialized resistors tailored to stringent healthcare standards. The Global Chip Resistor Market can leverage this momentum by enhancing its presence in regulated, high-margin medical segments. It enables growth beyond traditional electronics markets into more specialized, technology-driven applications.
Market Segmentation Analysis:
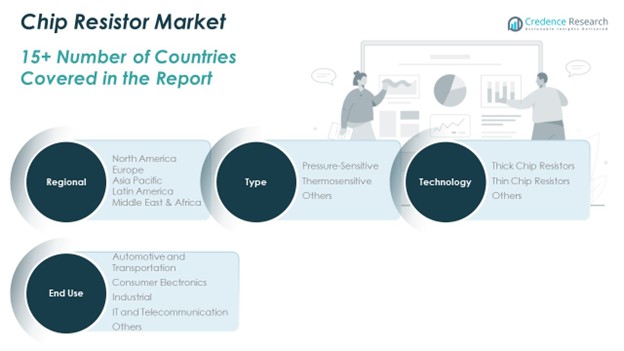
The Global Chip Resistor Market is segmented by type, technology, and end-use.
By type segment, pressure-sensitive chip resistors hold a dominant share due to their versatility and responsiveness in dynamic circuit conditions. Thermosensitive variants follow, offering temperature-dependent resistance changes for applications requiring thermal feedback and control. The "others" category includes niche resistor types used in specialized functions.
By technology, thick chip resistors lead the market due to their cost-effectiveness, durability, and widespread use in standard electronic applications. Thin chip resistors are gaining traction in high-precision devices that require tighter tolerances and compact designs, especially in medical and communication equipment. The others segment consists of emerging or hybrid technologies suited for specific advanced applications.
By end-use, the consumer electronics segment drives significant demand, supported by rising production of smartphones, wearables, and smart appliances. Automotive and transportation applications contribute strongly, driven by the shift to electric vehicles and advanced driver-assistance systems. The Global Chip Resistor Market also sees stable growth from industrial, IT, and telecommunication sectors that rely on resistors for process control and connectivity.
Segmentation:
By Type:
- Pressure-Sensitive
- Thermosensitive
- Others
By Technology:
- Thick Chip Resistors
- Thin Chip Resistors
- Others
By End-Use:
- Automotive and Transportation
- Consumer Electronics
- Industrial
- IT and Telecommunication
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Resistor Market size was valued at USD 577.37 million in 2018 to USD 808.96 million in 2024 and is anticipated to reach USD 1,422.42 million by 2032, at a CAGR of 7.2% during the forecast period. North America holds a 29% share of the Global Chip Resistor Market, driven by advancements in automotive electronics, aerospace, and industrial automation. The United States leads the region with a strong base of semiconductor manufacturers and electronic component suppliers. The growing adoption of electric vehicles and renewable energy systems supports the need for precision resistors in power management and control applications. Companies in the region invest heavily in R&D to develop resistors with higher reliability and efficiency for mission-critical systems. Regulatory frameworks around energy efficiency and environmental standards also drive innovation in passive components. The region benefits from established infrastructure, skilled labor, and proximity to key consumer industries.
Asia Pacific
The Asia Pacific Chip Resistor Market size was valued at USD 523.43 million in 2018 to USD 775.98 million in 2024 and is anticipated to reach USD 1,462.10 million by 2032, at a CAGR of 8.1% during the forecast period. Asia Pacific dominates the Global Chip Resistor Market with a market share of 41%, supported by its extensive electronics manufacturing ecosystem. China, Japan, and South Korea account for the bulk of regional production and export of chip resistors. China’s national programs to strengthen domestic production capacity in semiconductors and electronics boost demand for passive components. Japan and South Korea contribute advanced technologies, especially in high-density chip resistor designs for compact electronic devices. The rapid expansion of consumer electronics, 5G infrastructure, and electric vehicles continues to elevate regional consumption. It remains a hub for both global supply and innovation in chip resistor technologies.
Europe
The Europe Chip Resistor Market size was valued at USD 262.03 million in 2018 to USD 349.96 million in 2024 and is anticipated to reach USD 554.43 million by 2032, at a CAGR of 5.8% during the forecast period. Europe contributes approximately 17% to the Global Chip Resistor Market, with strong demand from its automotive, industrial automation, and renewable energy sectors. Germany, France, and the UK lead in adoption of high-precision resistors for electric mobility and manufacturing systems. Regulatory standards in Europe promote energy-efficient electronics, prompting integration of advanced resistors in smart grids and EVs. The region’s focus on sustainability and digitization increases the application of passive components in low-emission technologies. Collaborative R&D efforts between local manufacturers and universities support technical innovation. It plays a vital role in high-quality, customized resistor solutions for niche industrial applications.
Latin America
The Latin America Chip Resistor Market size was valued at USD 56.39 million in 2018 to USD 78.71 million in 2024 and is anticipated to reach USD 118.19 million by 2032, at a CAGR of 5.1% during the forecast period. Latin America holds around 8% of the Global Chip Resistor Market, with growing demand from electronics assembly and automotive sectors. Brazil and Mexico are key contributors, supported by foreign investment in local production and assembly units. Expansion of smart home devices, mobile electronics, and industrial automation increases the consumption of chip resistors. Governments are promoting domestic technology capabilities, which encourages infrastructure upgrades and electronics sourcing. While the region faces challenges in component manufacturing, it serves as an important market for global suppliers. It is gradually enhancing its role in the regional value chain of passive electronic components.
Middle East
The Middle East Chip Resistor Market size was valued at USD 40.62 million in 2018 to USD 52.53 million in 2024 and is anticipated to reach USD 77.33 million by 2032, at a CAGR of 4.8% during the forecast period. The Middle East represents about 3% of the Global Chip Resistor Market, with demand linked to infrastructure modernization, telecom upgrades, and smart city projects. Countries like the UAE and Saudi Arabia are adopting advanced electronics in transportation, energy, and public services. Investments in digital transformation initiatives and renewable energy systems raise the need for reliable passive components. Regional reliance on imports continues, but the market is expanding through partnerships with international electronics suppliers. The increasing focus on IoT and automation supports steady growth in component integration. It holds strategic potential for long-term development in tech-enabled infrastructure.
Africa
The Africa Chip Resistor Market size was valued at USD 24.05 million in 2018 to USD 37.50 million in 2024 and is anticipated to reach USD 52.90 million by 2032, at a CAGR of 4.2% during the forecast period. Africa accounts for 2% of the Global Chip Resistor Market, with emerging opportunities driven by mobile connectivity and electrification efforts. Countries such as South Africa, Kenya, and Nigeria show increasing adoption of electronic systems in healthcare, telecommunications, and power distribution. The growth of off-grid solar energy and digital banking services expands the demand for durable and cost-effective resistors. Infrastructure gaps and supply chain limitations challenge consistent component availability. Regional governments are encouraging technology investments and partnerships to improve local electronics capabilities. It is positioned as a developing market with potential for future expansion in low-cost and energy-focused applications.
Key Player Analysis:
- Samsung
- Rohm Semiconductor
- YAGEO Corporation
- TE Connectivity
- Bourns, Inc.
- US Resistor, Inc.
- Caddock Electronics, Inc.
- Panasonic Industrial Devices
- Miba Resistors Austria GmbH
- Rutronik Elektronische Bauelemente GmbH
- Mouser Electronics Europe
- Eusemiconductors
- Hong Kong Resistors Manufactory
- RALEC
Competitive Analysis:
The Global Chip Resistor Market features a competitive landscape dominated by established players with strong manufacturing capabilities and global distribution networks. Key companies such as Yageo Corporation, Vishay Intertechnology, KOA Corporation, Panasonic Corporation, and ROHM Semiconductor lead the market with diverse product portfolios and focus on innovation. These firms invest in advanced materials, automation, and miniaturization to meet evolving design requirements. It reflects intense competition driven by price sensitivity, quality standards, and supply chain resilience. New entrants face high barriers due to technological complexity and the need for compliance with strict industry specifications. Strategic partnerships, mergers, and capacity expansions continue to shape competitive dynamics. The Global Chip Resistor Market rewards players that balance cost efficiency with product reliability, especially in high-demand sectors like automotive, telecommunications, and consumer electronics. Continuous R&D and customer-centric customization remain critical for sustaining market leadership and expanding global presence.
Recent Developments:
- In April 2023, YAGEO Group, a prominent global producer of passive components, launched its VT Series of automotive-grade chip resistors. This new product line is designed to meet the stringent requirements of modern automotive applications, offering enhanced reliability and performance for high-stress environments. The introduction of the VT Series underscores YAGEO’s commitment to innovation and its strategic focus on supporting the rapidly evolving automotive electronics sector, where robust and precise chip resistors are increasingly in demand due to the rise of electric and hybrid vehicles.
- On February 12, 2025, ROHM Semiconductor announced the expansion of its MCRx family of general-purpose chip resistors. The new lineup includes the high-power MCRS series and the low-resistance, high-power MCRL series, both designed for greater miniaturization and enhanced performance. These resistors feature improved rated power and temperature coefficient characteristics, enabling compact, efficient circuit designs for automotive, industrial, and communications infrastructure.
- On April 1, 2025, TE Connectivity completed the acquisition of Richards Manufacturing Co., a North American leader in utility grid products. This acquisition is set to enhance TE’s capabilities in serving the energy sector and utility customers, complementing its broad portfolio of connectors, sensors, and passive components, including chip resistors. TE also continues to innovate with new high-power SMD resistor families, such as the 3522 series, which offer significantly increased power-to-size ratios for more compact and capable PCB designs.
Market Concentration & Characteristics:
The Global Chip Resistor Market exhibits moderate to high market concentration, with a few major players accounting for a significant share of global production. It is characterized by high-volume manufacturing, cost competitiveness, and strong technical specifications demanded across end-use sectors. The market favors companies with vertically integrated operations and global logistics capabilities. Product differentiation is limited, making performance reliability, miniaturization, and precision key competitive factors. It remains sensitive to raw material prices and requires consistent investment in automation and quality control. Regulatory compliance and ability to meet custom design needs define supplier selection in sectors like automotive, aerospace, and telecommunications.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology and End-Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of electric vehicles will drive demand for high-reliability chip resistors in power management systems.
- Miniaturization of consumer electronics will increase the need for compact, precision resistors with improved thermal stability.
- Expansion of 5G and IoT infrastructure will create long-term opportunities in telecommunications and smart devices.
- Medical electronics and wearable health devices will boost demand for ultra-small resistors with strict performance standards.
- Industrial automation and robotics will accelerate integration of chip resistors in control systems and sensor networks.
- Investment in renewable energy systems will require resistors capable of withstanding high voltage and fluctuating currents.
- Regional manufacturing expansions in Asia and Eastern Europe will enhance production capacity and supply chain resilience.
- Technological innovation in thin-film and thick-film resistor materials will improve efficiency and reliability.
- Strategic mergers and acquisitions will consolidate market presence and expand product portfolios.
- Regulatory focus on energy efficiency and emissions will influence product development and material selection.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Consumer Electronics
The rapid increase in production and adoption of smartphones, laptops, wearables, and smart home devices is driving demand for compact, reliable chip resistors that can manage current and voltage in miniaturized circuits.
Electrification and Automation in Automotive Sector
The shift toward electric vehicles and advanced driver-assistance systems (ADAS) is boosting the integration of chip resistors in automotive electronics, where they are essential for battery management, powertrains, and safety systems.
Expansion of 5G Networks and IoT Ecosystem
The rollout of 5G infrastructure and the growth of IoT devices require high-frequency, stable chip resistors to ensure signal integrity and device reliability in connected environments.
Growth in Industrial Automation and Smart Manufacturing
Increasing adoption of automation, robotics, and smart manufacturing systems is fueling demand for precision chip resistors that maintain circuit accuracy and equipment safety in harsh industrial settings.
Miniaturization and High-Reliability Requirements
The ongoing trend toward smaller, more efficient electronic devices and the need for components that can withstand extreme conditions are pushing manufacturers to develop chip resistors with enhanced thermal stability, tighter tolerances, and higher reliability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Chip Resistor Market?
What factors are driving the growth of the Global Chip Resistor Market?
What are some challenges faced by the Global Chip Resistor Market?
Who are the major players in the Global Chip Resistor Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pressure-Sensitive
- 1.2.2 Thermosensitive
- 1.2.3 Others
- 1.3 By End-Use
- 1.3.1 Automotive and Transportation
- 1.3.2 Consumer Electronics
- 1.3.3 Industrial
- 1.3.4 IT and Telecommunication
- 1.3.5 Others
- 1.4 By Technology
- 1.4.1 Thick Chip Resistors
- 1.4.2 Thin Chip Resistors
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,103.63 million → 2032: USD 3,687.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chip Resistor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chip Resistor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chip Resistor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chip Resistor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chip Resistor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chip Resistor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chip Resistor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chip Resistor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,103.63 million → 2032: USD 3,687.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chip Resistor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pressure-Sensitive
- 12.3.7.2 Thermosensitive
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive and Transportation
- 12.4.7.2 Consumer Electronics
- 12.4.7.3 Industrial
- 12.4.7.4 IT and Telecommunication
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Thick Chip Resistors
- 12.5.7.2 Thin Chip Resistors
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chip Resistor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Chip Resistor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Chip Resistor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Chip Resistor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 YAGEO Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ROHM Semiconductor
- 18.4 Samsung
- 18.5 Panasonic Industrial Devices
- 18.6 TE Connectivity
- 18.7 Bourns, Inc.
- 18.8 Vishay Intertechnology
- 18.9 KOA Corporation
- 18.10 Caddock Electronics, Inc.
- 18.11 Rutronik Elektronische Bauelemente GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

