
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Artificial Intelligence in Retail Market Size 2024 | USD 494.55 million |
| Germany Artificial Intelligence in Retail Market, CAGR | 31.93% |
| Germany Artificial Intelligence in Retail Market Size 2032 | USD 5988.14 million |
Market Overview:
The Germany Artificial Intelligence in Retail Market is projected to grow from USD 494.55 million in 2023 to an estimated USD 5988.14 million by 2032, with a compound annual growth rate (CAGR) of 31.93% from 2023 to 2032.
Several factors are propelling the adoption of AI in Germany's retail industry. Retailers are increasingly leveraging AI technologies such as machine learning, natural language processing, and predictive analytics to enhance customer engagement, optimize inventory management, and streamline supply chain operations. The rise of e-commerce and the demand for personalized shopping experiences have further accelerated AI integration. Additionally, advancements in AI-driven automation and chatbots are improving customer interactions, while AI-based recommendation systems are enhancing product discovery. These innovations are enabling retailers to make data-driven decisions, improve operational efficiency, and meet evolving consumer expectations. AI is also being integrated into fraud detection systems and dynamic pricing models, enabling retailers to respond to market changes in real time. Moreover, the increased availability of big data and cloud computing platforms is further empowering AI applications across both physical and digital retail environments.
Regionally, major German cities such as Berlin, Munich, Hamburg, and Frankfurt are at the forefront of AI adoption in retail. These urban centers host leading retailers and technology companies that are actively implementing AI solutions to improve customer experiences, supply chain efficiency, and marketing strategies. Germany accounted for 7.6% of the global AI in retail market revenue in 2024 and is projected to lead the European market in terms of revenue by 2030. The country's strong digital infrastructure, skilled workforce, and supportive regulatory environment contribute to its prominent position in the AI retail landscape. Government initiatives such as the “Digital Strategy 2025” and increased funding for AI startups are also accelerating innovation and deployment. Furthermore, collaborations between academic institutions and retail businesses are fostering a strong ecosystem for continuous AI research and development in the country.
Market Insights:
- The Germany Artificial Intelligence in Retail Market is expected to grow at a CAGR of 31.93% from 2023 to 2032, driven by rapid digital transformation in retail.
- AI adoption is rising due to increasing demand for personalized shopping experiences, real-time engagement, and tailored marketing efforts.
- Retailers use AI for predictive analytics, demand forecasting, inventory management, and supply chain optimization to improve efficiency.
- AI technologies such as fraud detection, dynamic pricing, and product recommendation engines are enhancing operational decision-making.
- Government initiatives like “Digital Strategy 2025” and funding for AI startups support the country’s AI infrastructure and retail innovation.
- Data privacy concerns and high implementation costs remain key barriers to adoption, especially for small and mid-sized retailers.
- Major cities like Berlin, Munich, Hamburg, and Frankfurt lead AI integration in retail, benefiting from a strong tech ecosystem and skilled workforce.
Report scoope
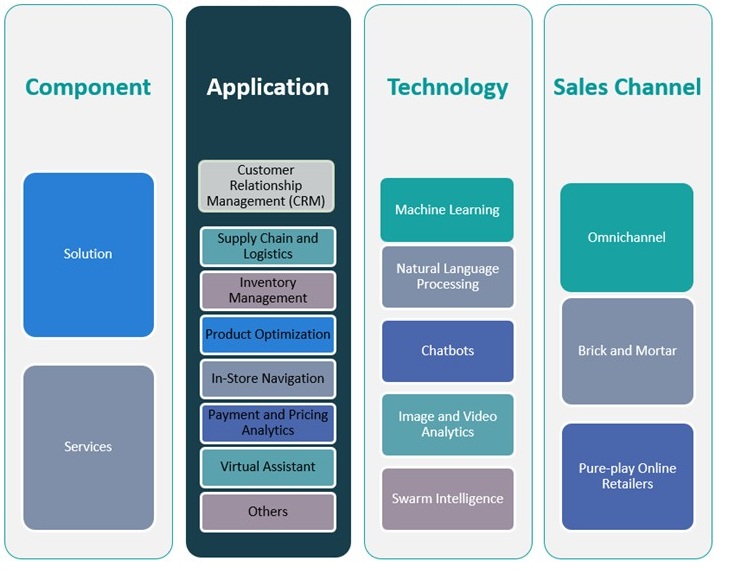
This report segments the Germany Artificial Intelligence in Retail Market as follow
Market Drivers:
Rising Demand for Hyper-Personalized Shopping Experiences Is Accelerating AI Integration
Retailers in Germany are adopting artificial intelligence to deliver highly personalized shopping journeys. Consumers increasingly expect tailored product recommendations, dynamic pricing, and targeted promotions. AI enables real-time customer segmentation based on purchasing behavior, demographics, and browsing patterns. Retailers use this data to design marketing campaigns that resonate with specific customer profiles. The Germany Artificial Intelligence in Retail Market benefits from the need to create frictionless and engaging customer experiences. It also supports omni-channel personalization, ensuring consistent interaction across mobile apps, websites, and physical stores. This strategic use of AI enhances customer loyalty and improves conversion rates.
Operational Efficiency and Inventory Optimization Remain Central to Retail AI Adoption
Retailers are deploying AI solutions to improve internal operations and reduce inefficiencies. AI-powered demand forecasting tools help businesses optimize stock levels, reducing overstock and stockouts. Machine learning models identify patterns in historical sales data to support procurement planning and replenishment cycles. The Germany Artificial Intelligence in Retail Market is driven by the push to increase operational accuracy and lower supply chain costs. Retailers also implement AI for warehouse automation, workforce scheduling, and route optimization in logistics. These applications reduce human error, improve resource utilization, and accelerate delivery timelines.
- Siemens, for instance, has implemented AI-driven predictive maintenance algorithms in its manufacturing operations, allowing it to foresee equipment failures and reduce downtime, which in turn streamlines supply chain operations and ensures optimal inventory levels.
AI Enhances Fraud Detection, Price Optimization, and Real-Time Decision Making
Retailers in Germany rely on AI to detect fraudulent transactions and secure customer data. AI models analyze transaction patterns to flag unusual activities and prevent revenue losses. It also supports real-time pricing strategies by evaluating competitor pricing, inventory status, and consumer demand. The Germany Artificial Intelligence in Retail Market is evolving to enable smarter decision making across key retail functions. AI tools help retailers test and implement optimal pricing schemes based on margin goals and customer behavior. It also assists in identifying underperforming products and locations, allowing faster corrective actions.
Supportive Government Initiatives and Tech Ecosystem Strengthen Market Growth
Government-backed digitalization strategies and funding for AI research create a favorable environment for retail innovation. Programs like "Digital Strategy 2025" aim to foster AI development and adoption across industries, including retail. Germany hosts several AI-focused startups and research institutes that collaborate with retailers to develop custom solutions. The Germany Artificial Intelligence in Retail Market benefits from this ecosystem by accelerating innovation and reducing implementation barriers. Policymakers are working to ensure data security, ethical AI use, and transparency, which enhances consumer trust. These structural advantages contribute to the steady growth and long-term viability of AI in Germany’s retail sector.
- For instance, the Schwarz Group, owner of Lidl and Kaufland, has opened fully automated stores (store.box and shop.box) that use AI for inventory management, replenishment, and autonomous checkout, demonstrating the innovative environment fostered by supportive policies and collaborations.
Market Trends:
Growing Use of AI-Powered Visual Search and Augmented Reality in Customer Engagement
Retailers are integrating AI-driven visual search tools and augmented reality (AR) into customer interfaces to enhance shopping experiences. These technologies allow consumers to search for products using images, try virtual outfits, or visualize furniture in real-world spaces. The Germany Artificial Intelligence in Retail Market reflects this trend through investments in AI-enabled mobile apps and virtual fitting rooms. It helps retailers reduce product return rates and increase buyer confidence, especially in fashion, cosmetics, and furniture sectors. Visual search also shortens the path to purchase by eliminating keyword dependencies. AR integration improves brand perception and drives higher engagement.
- For example, H&M’s mobile app uses visual search to let shoppers discover similar products by uploading images; the AI matches these images to H&M’s catalog within seconds, and the app’s AI styling tools suggest outfits based on individual tastes and purchase history.
Proliferation of AI Chatbots and Voice Assistants in Retail Customer Service
AI chatbots and voice-based assistants are becoming key tools for delivering fast, personalized customer service. Retailers deploy them on websites, apps, and messaging platforms to handle order tracking, product inquiries, and post-sale support. The Germany Artificial Intelligence in Retail Market is witnessing increased adoption of multilingual and context-aware chatbots. It helps reduce response times, minimize support costs, and improve customer satisfaction. Voice assistants are being used for hands-free shopping, enabling customers to browse and order using smart devices. These technologies streamline service delivery and support 24/7 operations.
- For instance, Deutsche Telekom’s award-winning chatbot "Ask Magenta" enables intuitive, multilingual support across channels, and their smart speaker allows hands-free control of services like EntertainTV and Magenta SmartHome, supporting secure, GDPR-compliant voice interactions.
Shift Toward Predictive Analytics for Demand Planning and Merchandising
Retailers are adopting predictive analytics to align inventory levels with consumer demand and optimize merchandising strategies. AI tools analyze historical sales, seasonal trends, and external factors such as weather or holidays. The Germany Artificial Intelligence in Retail Market is advancing in its use of predictive insights for product placement and assortment decisions. It allows retailers to improve shelf availability and reduce markdowns. Merchandising teams rely on AI to test different layouts and determine optimal product mixes for each location. These insights drive sales growth while minimizing waste and lost opportunities.
Integration of AI with IoT and Cloud Infrastructure to Improve Agility
Retailers are combining AI with Internet of Things (IoT) devices and cloud platforms to enhance operational agility. Smart shelves, connected sensors, and real-time tracking systems generate large volumes of data that AI tools process instantly. The Germany Artificial Intelligence in Retail Market continues to evolve through this convergence of technologies. It allows businesses to monitor stock levels, foot traffic, and in-store behavior in real time. Cloud-based platforms ensure scalability and flexibility, making it easier to deploy AI across multiple store locations. This integration empowers retailers to respond quickly to market changes and customer needs.
Market Challenges Analysis:
Data Privacy Concerns and Regulatory Compliance Limit AI Adoption in Retail
Retailers face growing scrutiny around data collection, processing, and storage practices. Consumers are increasingly aware of how their personal information is used, prompting stricter expectations for transparency and control. The Germany Artificial Intelligence in Retail Market must navigate the complexities of GDPR and evolving data protection frameworks. It forces companies to invest in robust cybersecurity measures and compliance protocols, which can slow down AI deployment. Misuse or mishandling of consumer data can lead to reputational damage and legal consequences. Retailers also struggle to maintain data accuracy across multiple channels, which impacts AI model performance and trustworthiness.
- For example, Zalando, one of Europe’s largest online fashion retailers headquartered in Berlin, had to overhaul its data management systems to comply with GDPR requirements, investing in advanced encryption and automated consent management tools.
High Implementation Costs and Technical Skill Gaps Hinder Market Growth
AI solutions require significant capital investment in infrastructure, tools, and training. Many small and mid-sized retailers hesitate to adopt AI due to high upfront costs and uncertain returns. The Germany Artificial Intelligence in Retail Market faces challenges in scaling AI solutions across diverse retail formats. It often lacks access to skilled professionals who can manage and fine-tune AI systems for real-world retail scenarios. The complexity of integrating AI with legacy IT systems creates further technical barriers. Without clear guidance or internal expertise, many retailers struggle to realize the full potential of AI initiatives.
Market Opportunities:
The growing accessibility of cloud-based AI solutions creates fresh opportunities for small and medium-sized retailers. These businesses can now deploy cost-effective tools for customer insights, inventory planning, and personalized marketing. The Germany Artificial Intelligence in Retail Market stands to benefit from this democratization of technology. It enables a wider range of retailers to compete with larger players on operational efficiency and customer experience. Partnerships with AI startups and SaaS providers can accelerate adoption in this segment. Early adopters gain competitive advantages by responding faster to consumer behavior shifts.
Consumers in Germany increasingly prioritize sustainability in their purchasing decisions. Retailers can use AI to minimize waste, optimize energy usage, and track carbon footprints across the supply chain. The Germany Artificial Intelligence in Retail Market can grow by supporting environmentally responsible operations. It also creates opportunities to introduce AI-powered solutions for ethical sourcing, packaging efficiency, and returns management. Retailers that align AI investments with sustainability goals can improve brand reputation and meet emerging regulatory standards. This alignment opens doors to long-term customer loyalty and new green retail models.
Market Segmentation Analysis:
The Germany Artificial Intelligence in Retail Market is segmented by component, application, technology, and sales channel, reflecting its diverse range of use cases and deployment models.
By component, the market is divided into solutions and services, with AI-based solutions leading demand due to their ability to automate workflows and improve customer insights. Services support implementation, training, and maintenance, ensuring operational continuity and ROI realization.
By application, customer relationship management (CRM), supply chain and logistics, and inventory management dominate usage. These areas benefit most from predictive analytics and automation. Product optimization, in-store navigation, payment and pricing analytics, and virtual assistants are gaining adoption as retailers focus on personalization and efficiency. The “others” segment includes emerging uses like fraud detection and returns management.
By technology, machine learning holds the largest share, followed by natural language processing and chatbots. Image and video analytics are becoming essential for visual search and in-store monitoring, while swarm intelligence remains niche.
By sales channel, omnichannel retailers drive most AI investments, followed by brick and mortar and pure-play online retailers, each adapting AI to their customer engagement strategies.
Segmentation:
By Component
- Solution
- Services
By Application
- Customer Relationship Management (CRM)
- Supply Chain and Logistics
- Inventory Management
- Product Optimization
- In-Store Navigation
- Payment and Pricing Analytics
- Virtual Assistant
- Others
By Technology
- Machine Learning
- Natural Language Processing
- Chatbots
- Image and Video Analytics
- Swarm Intelligence
By Sales Channel
- Omnichannel
- Brick and Mortar
- Pure-play Online Retailers
Regional Analysis:
Berlin and Munich Lead AI Retail Innovation with Strong Startup Ecosystems Berlin and Munich serve as central hubs for AI-driven retail transformation in Germany. Berlin hosts approximately 54% of the nation's AI startups, fostering a vibrant ecosystem that supports rapid innovation in retail applications. Munich complements this with its strong industrial base and academic institutions, attracting significant investments in AI technologies. The Germany Artificial Intelligence in Retail Market benefits from the synergy between these cities' technological advancements and retail sector demands. This concentration of AI expertise and entrepreneurial activity positions both cities at the forefront of retail digitalization efforts. Their collaborative environments encourage the development and deployment of cutting-edge AI solutions tailored to retail needs.
Frankfurt and Hamburg Drive AI Adoption Through Financial and Commercial Strengths Frankfurt and Hamburg contribute significantly to the adoption of AI in retail through their economic and commercial infrastructures. Frankfurt, as a financial powerhouse, provides the necessary capital and investment opportunities for AI initiatives in retail. Hamburg's status as a major port and logistics center facilitates the integration of AI into supply chain and inventory management systems. The Germany Artificial Intelligence in Retail Market leverages these cities' strengths to enhance operational efficiencies and customer experiences. The presence of multinational corporations and a skilled workforce in both cities supports the scaling of AI solutions across various retail formats. Their strategic roles in finance and commerce make them pivotal in the nationwide expansion of AI technologies in retail.
Rhine-Main-Neckar Region Emerges as a Strategic AI and Retail Technology Cluster The Rhine-Main-Neckar region, often referred to as the "Silicon Valley of Germany," is emerging as a strategic cluster for AI and retail technology. This area encompasses cities like Darmstadt and Mannheim, which host leading research institutions and technology companies. The region's focus on IT and high-tech industries creates a conducive environment for the development of AI applications in retail. The Germany Artificial Intelligence in Retail Market capitalizes on the region's robust infrastructure and innovation capacity to drive advancements in retail technologies. Collaborations between academia and industry in this cluster facilitate the translation of research into practical retail solutions. The region's emphasis on digital transformation positions it as a key player in shaping the future of AI in retail across Germany.
Key Player Analysis:
- SAP SE
- Oracle Corporation
- Intel Corporation
- Salesforce, Inc.
- IBM Corporation
Competitive Analysis:
The Germany Artificial Intelligence in Retail Market features strong competition among global tech giants, regional AI firms, and specialized solution providers. Leading players such as IBM, Microsoft, SAP SE, Google, and Amazon Web Services drive innovation by offering scalable AI platforms tailored to retail operations. It also includes domestic firms and startups that focus on niche applications like visual recognition, customer analytics, and predictive merchandising. These companies compete on factors such as data integration capabilities, implementation speed, and return on investment. Strategic collaborations between technology providers and retail chains are accelerating AI adoption and enabling customized solutions. The market rewards players that combine technical expertise with a deep understanding of retail workflows. Competitive dynamics continue to evolve as vendors introduce AI tools that address specific operational challenges, from personalized marketing to real-time inventory tracking. Continuous investment in R&D, local partnerships, and platform flexibility remains essential for gaining market share.
Recent Developments:
- In February 2025, x-hoppers, an AI-powered retail communication platform, officially expanded into the German market following a successful showcase at EuroCIS 2025 in Düsseldorf. x-hoppers’ entry aims to address significant challenges in Germany’s retail sector, such as annual theft losses exceeding €4.1 billion and high employee turnover. The company’s AI-driven solutions include theft detection, hands-free staff communication, and smart customer assistance tools, all intended to improve operational efficiency and workforce retention for German retailers.
- In July 2024, Schwarz Group, the parent company of Lidl and Kaufland, began deploying artificial intelligence in inventory management across its retail operations. This initiative is part of a broader trend in the German retail sector, where companies are increasingly leveraging AI for logistics, supply chain management, marketing, and self-service checkout solutions. Notably, Netto introduced an autonomous shopping experience in its Regensburg store, using AI-driven technology for cashless payments and real-time basket creation without requiring customer registration or smartphones.
Market Concentration & Characteristics:
The Germany Artificial Intelligence in Retail Market exhibits moderate to high market concentration, with a few dominant global players supported by a growing number of regional firms and startups. It features a blend of mature technology providers and agile innovators, each offering AI tools for customer engagement, supply chain optimization, and sales forecasting. The market favors companies with strong data analytics capabilities, integration support, and scalable cloud infrastructure. It remains characterized by rapid technological change, short innovation cycles, and increasing demand for customized AI solutions. Competitive differentiation often hinges on data privacy compliance, ease of deployment, and ability to deliver measurable ROI. The market structure continues to shift as retailers seek flexible, modular platforms that align with evolving consumer preferences and operational demands.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, Technology and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outllook:
- AI adoption in retail will expand beyond large enterprises, reaching small and mid-sized retailers through cloud-based platforms.
- Retailers will invest in AI to enhance customer experience through hyper-personalization and real-time interaction tools.
- Predictive analytics will become central to inventory planning, pricing strategies, and product assortment decisions.
- Voice and visual search technologies will gain traction, reshaping how consumers interact with digital retail platforms.
- AI-enabled automation will streamline logistics, warehousing, and checkout processes, reducing operational costs.
- Demand for ethical and explainable AI will grow, driven by regulatory standards and consumer expectations.
- Retailers will integrate AI with IoT devices to enable smart stores and real-time inventory visibility.
- AI-driven sustainability tools will support waste reduction, energy management, and eco-conscious supply chains.
- Strategic partnerships between AI providers and retailers will accelerate solution customization and deployment.
- Germany will continue to lead in AI retail innovation within Europe, supported by strong infrastructure and policy backing.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Hyper-Personalized Shopping Experiences
German retailers are rapidly adopting AI to deliver tailored product recommendations, dynamic pricing, and targeted promotions, meeting consumer expectations for seamless, personalized engagement across digital and physical channels.
Operational Efficiency and Inventory Optimization
AI-powered demand forecasting, warehouse automation, and logistics optimization are enabling retailers to reduce costs, minimize stockouts and overstock, and streamline supply chain operations, driving widespread AI adoption.
Advancements in AI-Driven Automation and Customer Interaction
The integration of AI chatbots, voice assistants, and recommendation engines is enhancing customer service, reducing response times, and supporting 24/7 operations, which improves customer satisfaction and operational agility.
Supportive Government Initiatives and Robust Tech Ecosystem
Government programs like 'Digital Strategy 2025' and increased funding for AI startups, combined with strong digital infrastructure and academic-industry collaborations in cities like Berlin and Munich, are accelerating AI innovation and deployment in retail.
Integration of AI with IoT and Cloud Platforms
The convergence of AI with IoT devices and scalable cloud infrastructure allows real-time data processing, smart store management, and rapid deployment of AI solutions across multiple retail locations, boosting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Artificial Intelligence in Retail market?
What factors are driving the growth of the Germany Artificial Intelligence in Retail market?
What are the key segments within the Germany Artificial Intelligence in Retail market?
What are some challenges faced by the Germany Artificial Intelligence in Retail market?
Who are the major players in the Germany Artificial Intelligence in Retail market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solution
- 1.2.2 Services
- 1.3 By Technology
- 1.3.1 Machine Learning
- 1.3.2 Natural Language Processing
- 1.3.3 Chatbots
- 1.3.4 Image and Video Analytics
- 1.3.5 Swarm Intelligence
- 1.4 By Application
- 1.4.1 Customer Relationship Management (CRM)
- 1.4.2 Supply Chain and Logistics
- 1.4.3 Inventory Management
- 1.4.4 Product Optimization
- 1.4.5 In-Store Navigation
- 1.4.6 Payment and Pricing Analytics
- 1.4.7 Virtual Assistant
- 1.4.8 Others
- 1.5 By Sales Channel
- 1.5.1 Omnichannel
- 1.5.2 Brick and Mortar
- 1.5.3 Pure-play Online Retailers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 494.55 million → 2032: USD 5,988.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Germany Artificial Intelligence in Retail Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Germany Artificial Intelligence in Retail Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Germany Artificial Intelligence in Retail Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Germany Artificial Intelligence in Retail Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Germany Artificial Intelligence in Retail Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Germany Artificial Intelligence in Retail Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Germany Artificial Intelligence in Retail Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Germany Artificial Intelligence in Retail Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 494.55 million → 2032: USD 5,988.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Germany Artificial Intelligence in Retail Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solution
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Machine Learning
- 12.4.7.2 Natural Language Processing
- 12.4.7.3 Chatbots
- 12.4.7.4 Image and Video Analytics
- 12.4.7.5 Swarm Intelligence
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Customer Relationship Management (CRM)
- 12.5.7.2 Supply Chain and Logistics
- 12.5.7.3 Inventory Management
- 12.5.7.4 Product Optimization
- 12.5.7.5 In-Store Navigation
- 12.5.7.6 Payment and Pricing Analytics
- 12.5.7.7 Virtual Assistant
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Omnichannel
- 12.6.7.2 Brick and Mortar
- 12.6.7.3 Pure-play Online Retailers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Germany Artificial Intelligence in Retail End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Germany Artificial Intelligence in Retail Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Germany Artificial Intelligence in Retail Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Germany Artificial Intelligence in Retail Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SAP SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Corporation
- 18.4 Intel Corporation
- 18.5 Salesforce, Inc.
- 18.6 IBM Corporation
- 18.7 Microsoft Corporation
- 18.8 Google LLC
- 18.9 Amazon Web Services
- 18.10 Siemens AG
- 18.11 Zalando SE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

