
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Glass Bottle Packaging Market Size 2023 | USD 26154.2 Million |
| Glass Bottle Packaging Market, CAGR | 4.00% |
| Glass Bottle Packaging Market Size 2032 | USD 37225.58 Million |
Market Insights
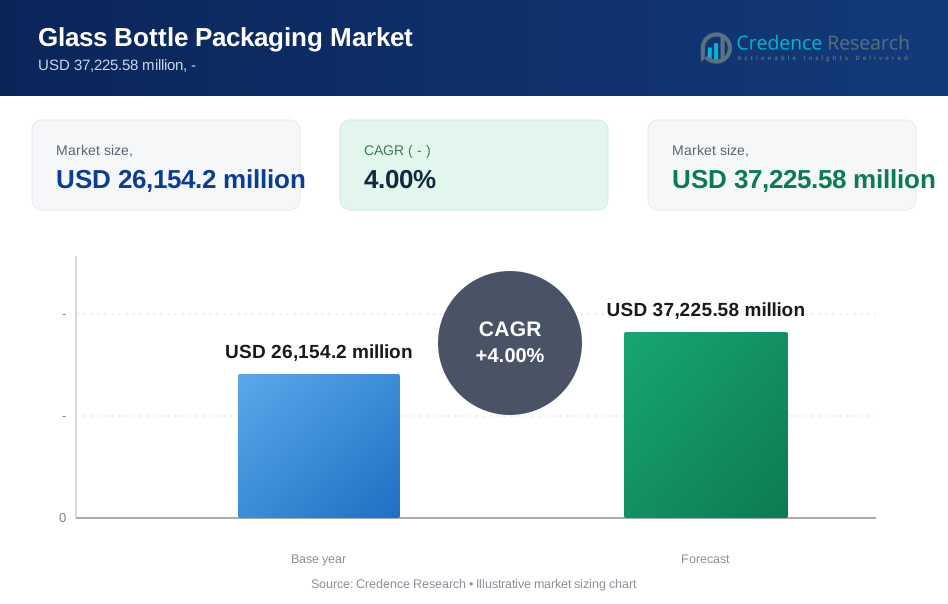
- The global market for glass bottle packaging is expected to grow from its estimated USD 26154.2 million in 2023 to USD 37225.58 million in 2032 at a compound annual growth rate (CAGR) of 4.00% between 2024 and 2032.
- The significant category is clear glass bottles. On the other hand, amber glass bottles are expected to grow at a strong CAGR.
- The leading shape and design segment is standard round bottles.
- The CAGR for crown caps is expected to be the highest during the projection period.
- The small bottles (e.g., miniatures) segment will have the highest CAGR throughout the prediction period.
- Alcoholic beverages are estimated to have the greatest CAGR during the forecast period.
- The food and beverage industry is predicted to grow fastest over the projection period.
- Asia Pacific dominated the glass bottle packaging market.
- Regarding the glass bottle packaging market share, Europe is expected to come second.
- North America is anticipated to grow fastest in the glass bottle packaging market.
- Globally rising consumption of both alcoholic and non-alcoholic beverages and consumers' growing awareness of and preference for eco-friendly packaging solutions are the main factors driving the market.
- A number of factors, such as the expanding demand for high-quality bottled water, developments in glass recycling technology, and the growing demand for high-end and luxury goods, which encourage the use of glass packaging to project a sophisticated image, are driving the glass bottle packaging market.
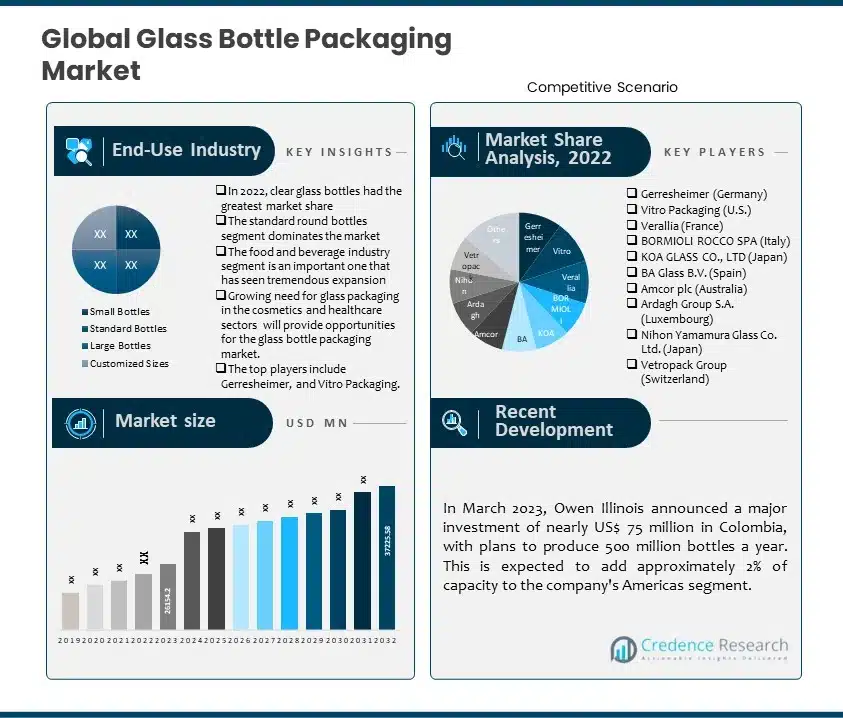
Executive Summary
Market Definition
The market for glass bottle packaging is the packaging business area devoted to the manufacture, sale, and use of glass bottles for a range of goods in diverse industries. This market includes the production of glass bottles, jars, and containers for use in packaging food products (like sauces, condiments, and preserved foods), pharmaceuticals, cosmetics, and other consumer goods, as well as drinks (alcoholic and non-alcoholic).
Market Overview
The glass bottle packaging sector is estimated to develop at a 4.00% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will keep developing, rising from its estimated value of USD 26154.2 million in 2023 to USD 37225.58 million in 2032.
The glass bottle packaging market is driven primarily by the increasing consumer demand for safe and healthy packaging options. Consumer preferences and concerns about sustainability, environmental consciousness, and health are the main drivers of this trend. The possible health hazards linked to specific packaging materials, like plastics that could leak dangerous chemicals into the contents, are drawing more and more attention from consumers. Glass is thought to be a safer choice because it is inert and doesn't react with the products it holds, protecting the products' integrity and purity when they are packaged. Because it is non-reactive and impermeable, glass is the perfect material to keep food and drinks fresh and high-quality. Because it doesn't absorb flavors or odors, the packaged goods keep their original flavor and aroma. This is especially crucial for sauces, drinks, and other consumables.
Glass is extremely recyclable, and recycling uses less energy than making new glass. Recyclable and environmentally friendly packaging options are becoming more and more popular as consumers become more aware of the environment. This sustainability trend is supported by glass bottles, which are generally considered a more environmentally friendly choice. Glass packaging is frequently linked to premium quality and an image of a higher-end product. Positive brand perception may result from consumers viewing products packaged in glass bottles as more wealthy and sophisticated. This belief can shape consumer behavior and support the need for glass packaging across various sectors.
Segmentation by Type of Glass
- Clear glass bottles dominated the market. A visually appealing way to highlight the products inside clear glass bottles is to use them. This is particularly significant for drinks like water, juices, and some alcoholic ones, where the liquid's color and clarity affect the overall experience for the drinker.
- The amber glass bottles category will exhibit a sizable CAGR during the projected period. Since amber glass doesn't deteriorate easily from light, it's especially good at keeping contents potent and fresh. Because of this, products that must maintain their chemical composition over time and are sensitive to light can be packaged in amber glass bottles.
- Other types of glass, such as green, blue, and other colored glass bottles, additionally support the need for glass bottle packaging.
Segmentation by Shape and Design
- The main shape and design are standard round bottles. The needs of the food and beverage, pharmaceutical, personal care, and other industries may impact the demand for standard round bottles in glass packaging.
- The square or rectangular bottles category will likely register a significant CAGR during forecasting. Square or rectangular bottles take up less room than cylindrical ones. They can be crammed tightly together with minimal space in between. This is especially advantageous for storage and transportation because it makes the best use of the available space.
- Other shapes and designs, such as oval bottles, specialty-shaped bottles (e.g., flask-shaped, vintage-style), and customized designs, also contribute to the demand for glass bottle packaging.
Segmentation by Closure Type
- The crown caps category is projected to grow at the fastest rate over the projection period. Crown caps are usually circular and made of metal, most commonly aluminum. A liner, typically composed of rubber or plastic, lines the inside of the cap and creates a seal with the bottle's rim.
- The need for glass bottle packaging is also influenced by other closure types, including corks, screw caps, swing tops, ropp (roll-on pilfer proof) caps, and others.
Segmentation by Capacity/Volume
- The small bottles (e.g., miniatures) segment will likely have the highest CAGR during the projection period. Because of their portability and convenience, miniature glass bottles are frequently chosen. Due to their small size, they are convenient to transport, store, and eat. They are, therefore, perfect for single-serving portions, traveling, and on-the-go consumption.
- Other capacity/volumes, such as standard bottles (e.g., 250ml, 500ml, 750ml), large bottles (e.g., magnums, jugs), and customized sizes, also contribute to the demand for glass bottle packaging.
Segmentation by Application
- Alcoholic beverages will be expected to have the foremost CAGR during the prediction period. Because glass is impermeable and inert, it helps keep alcoholic beverages' flavor and quality intact. The taste will not change over time since it doesn't chemically react with the ingredients. Because of this, glass bottles are the recommended option for upscale and premium alcoholic beverages.
- Other applications, such as non-alcoholic beverages, food products, pharmaceuticals, cosmetics, and personal care, also contribute to the demand for glass bottle packaging.
Segmentation by End-Use Industry
- The food and beverage industry will be expected to have the foremost CAGR during the prediction period. The market sector that deals with the manufacturing, distribution, and packaging of food and beverage products, especially those packaged in glass bottles, is known as the food and beverage industry in the glass bottle packaging market. A common and conventional technique for presenting and preserving different kinds of food and drink products is glass bottle packaging.
- Other end-use industries, such as the pharmaceuticals, cosmetics and personal care, and household products industries, also contribute to the demand for glass bottle packaging.
Segmentation by Region
- Asia Pacific leads the glass bottle packaging market. The Asia Pacific industries of healthcare, food & beverage, and cosmetics have increased their use of glass, which is responsible for its rapid growth.
- Europe is estimated to rank second in market size for glass bottle packaging.
- North America will witness the most rapid growth in the glass bottle packaging market.
- Regions such as Africa, the Middle East, and Latin America cover the remaining requirement for glass bottle packaging.
The market is expected to grow more quickly due to rising demand from the food and beverage, personal care, and cosmetics industries. One of the main reasons driving the growth of the worldwide market is the rising consumer demand for safe and healthful packaging options.
The Asia Pacific region holds a dominant position in the glass bottle packaging market. The area has seen significant economic growth, raising consumer demand for a range of goods, including packaged goods and beverages frequently sold in glass bottles. Production activities have increased across a range of sectors as a result of the rapid industrialization that has occurred in many Asia Pacific countries. Glass bottle packaging is often used in the food and beverage, pharmaceutical, and cosmetic industries due to its strength, quality, and capacity to keep contents fresh. Glass bottles are among the packaging solutions that are in greater demand as industrialization advances.
Throughout the forecast, North America's glass bottle packaging market is anticipated to expand fastest. North American consumers are increasingly gravitating toward branded, high-end goods. Glass bottles are a popular option for businesses trying to raise the perceived value of their products because they are frequently connected with superior quality and high-end packaging. Enhancements in the recycling infrastructure can additionally bolster the expansion of the glass packaging industry. Because glass packaging can be recycled, businesses may be encouraged to use it if North America has made strides in recycling infrastructure and technology. Consumer preferences for premium may drive glass packaging demand, healthier products like specialty foods, organic juices, and craft beverages. Glass is frequently regarded as a safer and more inert material because it doesn't leach dangerous substances while maintaining the taste and quality of the contents.
Key Highlights of the Report
The global glass bottle packaging market is segmented by type of glass, shape and design, closure type, capacity/volume, application, end-use industry, and region. Clear glass bottles are the market spearhead. Standard round bottles are the top category. The crown caps category is anticipated to increase at the highest CAGR throughout the projection period. The small bottles (e.g., miniatures) segment will experience the highest CAGR during the forecast period. The glass bottle packaging market is expanding mostly in Asia Pacific.
Customers are looking for packaging options that are more environmentally friendly and sustainable. Because glass bottles are recyclable and their contents don't absorb dangerous chemicals, they are considered more environmentally friendly than plastic bottles. This is in line with the rising demand from customers for goods packaged in materials that are thought to be more environmentally friendly and safe. The strict legal requirements for food and beverage packaging are frequently met by glass packaging. Companies in the food and beverage (F&B) sector may use glass bottles as packaging material regulations become more stringent to assure compliance and show a dedication to quality and safety.
The Asia Pacific is expected to account for the largest portion of the global glass bottle packaging market. The quickly expanding healthcare and cosmetics sectors are anticipated to drive demand in the Asia Pacific region. The growth in the Asia Pacific region is also due to the rising adoption of luxury manufacturers constantly developing creative packaging to grab consumers' attention. The North American region is also assumed to have the market's sharpest growth. Leading companies in every sector are paving the way for advancement by implementing environmentally friendly packaging, and glass makes for great packaging material. North America has been working hard to develop and implement glass packaging to compete with major global manufacturing hubs like China and Japan.
Which Key Factors Are Driving The Global Glass Bottle Packaging Market?
The market for glass bottle packaging is driven by several factors, including the growing popularity of craft beverages that frequently use glass bottles for a premium presentation, the expansion of the wine industry, and consumer preference for glass in wine packaging.
What Are The Main Challenges Confronting The Glass Bottle Packaging Market Globally?
The growth of the glass bottle packaging industry is being hindered by several issues, including the higher production and transportation costs of glass compared to other packaging materials like plastic or aluminum, inadequate recycling infrastructure, or low recycling rates.
What Market Opportunities Exist For Glass Bottle Packaging Globally?
The factors creating opportunities for the glass bottle packaging market include growing consumer consciousness and the need for eco-friendly packaging materials, growing market demand for packaged natural and alternative medicine products, and growing demand for glass packaging in the beauty and personal care industries.
Market Drivers
Multiple factors propel the glass bottle packaging industry across the globe. The primary factors propelling the global glass bottle packaging market are as follows:
Growing Need for Glass Packaging in the Cosmetics and Healthcare Sectors
The global market is driven by the expansion of healthcare facilities and the existence of the cosmetics industry. The safe storage, distribution, and handling of medicinal goods depend heavily on the design and production of appropriate packaging. The most common material used in healthcare product packaging is glass. Furthermore, it is widely used in the healthcare and cosmetic industries and produces a variety of ampoules, including glass dropper bottles, vials, and other glass products. The number of high-end cosmetic packages using glass-based cosmetic containers is growing quickly. It makes a further contribution to the market's expansion. Various dispensing options, including nozzles, foaming caps, spray nozzles, drip inserts, and pump heads, are also used with glass containers, such as jars and bottles. It is significant because, among other things, it keeps cosmetic containers from absorbing materials from the product-for example, moisture from the cream within. Consequently, as glass is used more often in cosmetics, there will be a greater need for glass packaging, propelling market expansion.
Market Restraints
There are several obstacles that the global glass bottle packaging market must overcome to continue growing. Among them are the following:
Increased Expenses For Both Production And Transportation
The main ingredients used to make glass bottles are sand, soda ash, limestone, and additional additives. The cost of producing glass bottles is directly impacted by an increase in the price of these raw materials. The production of glass involves high-temperature procedures that demand large energy inputs. Increasing energy costs may result in higher production costs for glass bottles. Adding innovations and technologies to the manufacturing process may incur extra costs. Higher initial costs may result from equipment upgrades or the adoption of greener practices. Trucks, ships, and other forms of transportation are used in the transportation of glass bottles. Fuel price fluctuations have a direct effect on transportation costs, which raises the total cost of shipping glass bottles to various markets.
Opportunities
There are plenty of potential prospects in the global glass bottle packaging industry. Among these are the following:
Growing Consumer Demand For High-End And Upscale Goods
Glass packaging is frequently connected by consumers to superior quality and a feeling of luxury. Prestige products, including fine wines, fragrances, and skincare items, are thought to be of higher caliber when they are packaged in glass bottles. Glass is transparent, so customers can see the product inside, highlighting its high-end features. Customers are looking for environmentally friendly packaging options as environmental issues are becoming more and more apparent. Glass is a very recyclable material that appeals to consumers who care about the environment because of its green qualities. Glass bottle packaging is an effective tool for brands that emphasize sustainability to draw in and keep consumers who value eco-friendly behaviors. Because glass is non-reactive and impermeable, it's a great material to keep expensive products fresh and intact. Over time, it aids in preserving the flavor, aroma, and quality of wines, oils, and other high-end products. This feature is essential for products expected to provide customers with an exceptional experience and at a premium price. Consumers are increasingly influenced by lifestyle selections and the total product experience when purchasing. Luxurious products presented in glass bottles add to the exclusivity and sophistication of the product and improve the consumer experience. This suits the tastes of customers who want a more affluent and sophisticated way of living.
Competitive Landscape
Key Players
There are several major competitors in the fiercely competitive global glass bottle packaging market. The following are a few of the leading market participants and their market shares:
- Gerresheimer (Germany)
- Vitro Packaging (U.S.)
- Verallia (France)
- BORMIOLI ROCCO SPA (Italy)
- KOA GLASS CO., LTD (Japan)
- BA Glass B.V. (Spain)
- Amcor plc (Australia)
- Ardagh Group S.A. (Luxembourg)
- Nihon Yamamura Glass Co. Ltd. (Japan)
- Vetropack Group (Switzerland)
- Heinz-Glass GmbH & Co. KGaA (Germany)
- Others
These companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions to remain competitive.
The largest suppliers in the global glass bottle packaging market continuously work to keep one step ahead of the competition by developing innovative concepts and products.
In February 2023, APC Packaging, a leader in global packaging solutions, announced that the Exploratorium at the 2023 Luxe Pack in Los Angeles will host the debut of its new line of double-walled glass jars. The glass jars, which have 30 and 50 milliliter capacities, are entirely made of sustainable materials. They are specifically made for personal care and cosmetics products.
In December 2022, Simonds Farsons Cisk, a PepsiCo partner based in Malta, announced the launch of new refillable glass bottles for Pepsi Cola, Pepsi Max, 7Up, and Mirinda. The recently introduced glass bottle design, which provides a tactile and visible bottle experience, embodies the brand's youthful energy.
Summary of Key Findings
- During the projected period, growing e-commerce trends and the need for durable and secure packaging are expected to boost market expansion.
- The market is segmented by type of glass, shape and design, closure type, capacity/volume, application, end-use industry, and region.
- The most popular type of glass in the market is clear glass bottles.
- Standard round bottles are the foremost category.
- Regarding CAGR, crown caps are expected to grow fastest during the forecast period.
- The category for alcoholic beverages will likely see the highest CAGR during the anticipated time frame.
- Asia Pacific is leading market development; the market is highly competitive with key players including Gerresheimer (Germany), Vitro Packaging (U.S.), Verallia (France), BORMIOLI ROCCO SPA (Italy), KOA GLASS CO., LTD (Japan), BA Glass B.V. (Spain), Amcor plc (Australia), Ardagh Group S.A. (Luxembourg), Nihon Yamamura Glass Co. Ltd. (Japan), Vetropack Group (Switzerland), Heinz-Glass GmbH & Co. KGaA (Germany), and Others.
Future Outlook
- The glass bottle packaging industry is expected to increase significantly in Asia Pacific and has a positive outlook worldwide.
- The craft beer and spirits trend is predicted to accelerate the growth of the glass bottle packaging market.
- During the forecast duration, one of the main challenges expected to impede the growth of the glass bottle packaging market is the limited design flexibility.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Glass Bottle Packaging Market Report
CXOs may get a detailed picture of the market in the Credence Research Glass Bottle Packaging Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global glass bottle packaging market size, segmented by type of glass, shape and design, closure type, capacity/volume, application, end-use industry, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for glass bottle packaging into segments based on the type of glass, shape and design, closure type, capacity/volume, application, end-use industry, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the glass bottle packaging industry, including information on their business plans, line of product, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the market for glass bottle packaging. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Glass Bottle Packaging Market Report to:
- Identify growth opportunities: This analysis may help CXOs identify new growth opportunities in the glass bottle packaging sector. For example, the report identifies the growing demand for glass bottle packaging from the food and beverage industry as a key opportunity.
- Make informed investment decisions: The report helps CXOs choose glass bottle packaging wisely. For example, the research study provides information on the critical factors to consider while selecting glass bottle packaging solutions and evaluating glass bottle packaging suppliers.
- Develop competitive strategies: CXOs can use the research report to develop competitive strategies for their glass bottle packaging businesses. For example, the research paper outlines the main strategies suppliers utilize to differentiate themselves from competitors.
- Track market developments: This research report may help CXOs stay ahead of the curve by tracking market developments. For instance, it offers insights into the most recent developments and trends in the market for glass bottle packaging.
In general, CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Glass Bottle Packaging Market Report useful.
Segmentation
- By Type of Glass
- Clear Glass Bottles
- Amber Glass Bottles
- Green Glass Bottles
- Blue Glass Bottles
- Other Colored Glass Bottles
- By Shape and Design
- Standard Round Bottles
- Square or Rectangular Bottles
- Oval Bottles
- Specialty-Shaped Bottles (e.g., flask-shaped, vintage-style)
- Customized Designs
- By Closure Type
- Crown Caps
- Corks
- Screw Caps
- Swing Tops
- ROPP (Roll-On Pilfer Proof) Caps
- Others
- By Capacity/Volume
- Small Bottles (e.g., miniatures)
- Standard Bottles (e.g., 250ml, 500ml, 750ml)
- Large Bottles (e.g., magnums, jugs)
- Customized Sizes
- By Application
- Alcoholic beverages
- Wine Bottles
- Spirits Bottles (e.g., whiskey, vodka, rum)
- Beer Bottles
- Non-Alcoholic Beverages
- Bottled Water
- Carbonated Soft Drinks
- Juice and Fruit Drinks
- Cold Brew Coffee and Tea
- Food Products
- Sauces and Condiments
- Oils and Vinegars
- Pickles and Preserves
- Jams and Jellies
- Honey
- Pharmaceuticals
- Prescription Medicines
- Over-the-counter (OTC) Medicines
- Dietary Supplements
- Cosmetics and Personal Care
- Perfumes and Fragrances
- Skincare Products
- Haircare Products
- Body Lotions and Oils
- Others
- By End-Use Industry
- Food and Beverage Industry
- Pharmaceuticals Industry
- Cosmetics and Personal Care Industry
- Household Products Industry
- Others
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainability and Eco-Friendly Packaging Demand
Consumers and brands are increasingly seeking packaging solutions that are recyclable and have minimal environmental impact. Glass bottles, being highly recyclable and non-reactive, are favored as a sustainable alternative to plastics, driving adoption across industries.
Premiumization and Brand Differentiation
Glass packaging is associated with premium quality and luxury, making it the preferred choice for high-end beverages, cosmetics, and specialty foods. Brands leverage glass bottles to enhance product image and appeal to consumers seeking upscale experiences.
Health and Safety Concerns
Growing awareness of the potential health risks associated with plastic packaging, such as chemical leaching, is prompting consumers and manufacturers to shift toward glass bottles, which are inert and preserve product purity and taste.
Growth in Food & Beverage and Healthcare Sectors
The expanding food & beverage and pharmaceutical industries, especially in emerging markets, are increasing the demand for safe, durable, and high-quality packaging. Glass bottles are widely used for alcoholic beverages, bottled water, medicines, and personal care products due to their protective properties.
Advancements in Glass Recycling and Manufacturing
Improvements in glass recycling infrastructure and manufacturing technologies are reducing production costs and energy consumption, making glass bottle packaging more economically viable and attractive for large-scale adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for glass bottle packaging?
What is the projected growth rate of the glass bottle packaging market between 2024 and 2032?
In terms of the type of glass, which market category is leading?
Which capacity/volume segment is estimated to have the highest CAGR throughout the forecast period?
Who are the main players in the global glass bottle packaging industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Alcoholic Beverages
- 1.2.2 Non-Alcoholic Beverages
- 1.2.3 Food Products
- 1.2.4 Pharmaceuticals
- 1.2.5 Cosmetics and Personal Care
- 1.3 By Closure Type
- 1.3.1 Crown Caps
- 1.3.2 Corks
- 1.3.3 Screw Caps
- 1.3.4 Swing Tops
- 1.3.5 ROPP (Roll-On Pilfer Proof) Caps
- 1.3.6 Others
- 1.4 By Type of Glass
- 1.4.1 Clear Glass Bottles
- 1.4.2 Amber Glass Bottles
- 1.4.3 Green Glass Bottles
- 1.4.4 Blue Glass Bottles
- 1.4.5 Other Colored Glass Bottles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 26,154.2 million → 2032: USD 37,225.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Glass Bottle Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Glass Bottle Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Glass Bottle Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Glass Bottle Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Glass Bottle Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Glass Bottle Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Glass Bottle Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Glass Bottle Packaging Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 26,154.2 million → 2032: USD 37,225.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Glass Bottle Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alcoholic Beverages
- 12.3.7.2 Non-Alcoholic Beverages
- 12.3.7.3 Food Products
- 12.3.7.4 Pharmaceuticals
- 12.3.7.5 Cosmetics and Personal Care
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Closure Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Crown Caps
- 12.4.7.2 Corks
- 12.4.7.3 Screw Caps
- 12.4.7.4 Swing Tops
- 12.4.7.5 ROPP (Roll-On Pilfer Proof) Caps
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Glass - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Clear Glass Bottles
- 12.5.7.2 Amber Glass Bottles
- 12.5.7.3 Green Glass Bottles
- 12.5.7.4 Blue Glass Bottles
- 12.5.7.5 Other Colored Glass Bottles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Glass Bottle Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Glass Bottle Packaging Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Glass Bottle Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Glass Bottle Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gerresheimer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vitro Packaging
- 18.4 Verallia
- 18.5 BORMIOLI ROCCO SPA
- 18.6 KOA GLASS CO., LTD
- 18.7 BA Glass B.V.
- 18.8 Amcor plc
- 18.9 Ardagh Group S.A.
- 18.10 Nihon Yamamura Glass Co. Ltd.
- 18.11 Vetropack Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

