
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Latin America Wind Turbine Market Size 2024 | USD 5214.5 Million |
| Latin America Wind Turbine Market, CAGR | 4.5% |
| Latin America Wind Turbine Market Size 2032 | USD 7415.54 Million |
Market Overview:
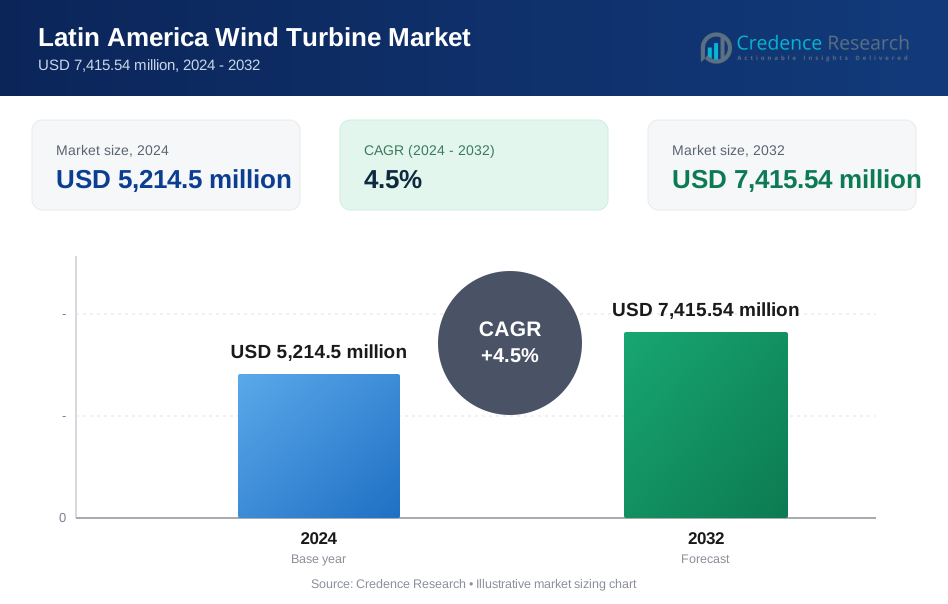
Latin America Wind Turbine Market size was valued at USD 5214.5 million in 2024 and is anticipated to reach USD 7415.54 million by 2032, at a CAGR of 4.5% during the forecast period (2024-2032).
Several key drivers are fueling the wind turbine market in Latin America. The region’s abundant wind resources make it an attractive location for wind power projects, with vast untapped potential in areas like Patagonia and the northern regions of Brazil. Additionally, the global push for clean energy alternatives and the declining cost of wind turbine technology have further accelerated market growth, enabling wind energy to compete with traditional energy sources on price. Governments in countries such as Brazil, Mexico, and Argentina are increasingly investing in wind energy infrastructure and establishing favorable regulatory frameworks to attract private investments, creating a more stable environment for long-term energy projects. The rising concern over energy security and the need for sustainable energy sources are also significant contributors to the growing wind energy adoption in the region, as countries aim to reduce reliance on fossil fuels and enhance grid resilience.
Regionally, Latin America’s wind turbine market is led by Brazil, which is the largest producer of wind energy in the region, accounting for a significant share of installed capacity and contributing to the country's ambitious renewable energy targets. Mexico and Argentina are also notable players, with both countries actively developing wind power projects to diversify their energy mix and reduce emissions. Other emerging markets like Chile and Uruguay are witnessing rapid growth in wind turbine installations, spurred by government initiatives and the increasing presence of international players in the renewable energy sector, signaling robust future growth prospects. The diverse geographical landscape and wind potential across Latin America provide ample opportunities for wind energy development, positioning the region as a key player in the global renewable energy landscape, attracting international partnerships and investments for large-scale projects.
Market Insights:
- Latin America’s wind turbine market is valued at USD 5,214.5 million in 2024 and is projected to reach USD 7,415.54 million by 2032.
- Brazil leads the market, accounting for over 60% of the total wind energy capacity in the region, driven by vast wind resources.
- Mexico holds a 20% share, with the Isthmus of Tehuantepec being a key area for wind energy development.
- Argentina contributes 10% of the market share, with the Patagonia region being a focal point for large-scale wind farm projects.
- Chile and Uruguay are emerging markets, contributing 5% and 3%, respectively, with strong growth prospects.
- Government policies and incentives, such as tax benefits and renewable energy contracts, play a crucial role in market expansion.
- The decline in wind turbine costs and technological advancements have enhanced the competitiveness of wind energy compared to traditional sources.
Market Drivers:
Abundant Wind Resources:
Latin America is endowed with vast and diverse wind resources, making it an attractive destination for wind power projects. Regions such as Patagonia in Argentina, northern Brazil, and coastal Mexico are known for their strong and consistent wind patterns. For instance, regions such as Patagonia in Argentina, northern Brazil, and coastal Mexico are known for their strong and consistent wind patterns, with average wind speeds exceeding 8 meters per second. These areas offer high wind speeds and long durations, ideal for the efficient generation of wind energy. The abundance of these natural resources supports the region’s efforts to scale up renewable energy production and reduce dependence on fossil fuels.
Government Support and Policy Framework:
Government policies and regulatory support are critical drivers of the wind turbine market in Latin America. For example, Brazil's National Energy Plan 2050 aims to increase the share of wind energy in the national grid, with incentives such as tax benefits and power purchase agreements. These measures have attracted both local and international investments, ensuring the growth of wind energy projects. Governments are also creating frameworks that offer financial and regulatory stability, which is essential for long-term infrastructure investments in the sector.
Declining Costs of Wind Turbine Technology:
A key factor accelerating the growth of wind energy in Latin America is the ongoing reduction in the cost of wind turbine technology. For instance, according to the International Renewable Energy Agency (IRENA), the cost of electricity from onshore wind has fallen by 23% since 2010. Advances in turbine efficiency, manufacturing techniques, and supply chain optimization have contributed to a significant decrease in the capital required to deploy wind power infrastructure. As the cost of installation continues to fall, wind energy is becoming increasingly competitive with other energy sources, encouraging more investments in the sector across the region.
Energy Security and Sustainability:
Energy security and the need for sustainable energy solutions are compelling drivers of wind energy adoption in Latin America. For example, Chile's National Energy Strategy aims to achieve 70% renewable energy by 2050, with wind energy playing a crucial role. Countries in the region are focused on diversifying their energy mix to reduce vulnerability to energy supply disruptions. Wind energy, being a reliable and renewable source, offers a sustainable solution to meet growing energy demand while addressing environmental concerns, including reducing greenhouse gas emissions.
Market Trends:
Expansion of Wind Farms:
A significant trend in the Latin America wind turbine market is the rapid expansion of large-scale wind farms across the region. Countries like Brazil, Mexico, and Argentina are focusing on the development of multi-megawatt wind farm projects to increase their renewable energy capacity. This trend is driven by the need to meet renewable energy targets, enhance energy security, and reduce carbon emissions. As a result, both onshore and offshore wind farms are becoming more prevalent, with numerous projects underway in key wind-rich regions.
Increasing Foreign Investments:
Foreign investments in Latin America’s wind energy sector have been growing steadily. International companies are increasingly involved in developing wind turbine projects, attracted by the region's favorable wind conditions, government incentives, and the potential for high returns. Several global players in the renewable energy industry have formed partnerships with local firms to develop and operate wind energy projects, signaling the strengthening of the region's wind energy infrastructure.
Technological Advancements:
Technological advancements in wind turbine design and efficiency are another key trend in the Latin American market. Modern turbines are larger, more efficient, and capable of generating more energy at lower costs. Innovations such as smart grids, energy storage systems, and predictive maintenance technologies are helping to enhance the performance of wind farms. These developments not only improve the cost-effectiveness of wind energy but also increase the reliability of wind power as a primary energy source.
Policy and Regulatory Evolution:
Government policies in Latin America are evolving to further support wind energy development. In response to growing environmental concerns and international climate commitments, governments are introducing more robust renewable energy regulations and frameworks. This includes streamlined permitting processes, more attractive incentives, and measures to integrate wind energy into national grids, ensuring the sector's continued growth and sustainability.
Market Challenges Analysis:
High Initial Capital Investment:
A significant barrier in the Latin American wind turbine market is the high initial capital required for wind farm development. Despite decreasing turbine costs, the financial burden for infrastructure, including land acquisition and grid connection, remains substantial. This is particularly challenging for smaller developers and emerging economies with limited access to capital. Even though government incentives help, large-scale projects often require considerable external financing.
Grid Integration and Infrastructure Limitations:
Another key challenge is the integration of wind energy into existing power grid infrastructure. Many regions in Latin America lack the necessary grid capacity and technology to accommodate large-scale renewable energy. Wind power’s intermittent nature demands enhanced grid stability. Additionally, inadequate transmission networks, particularly in rural areas, complicate the distribution of electricity generated by wind turbines to urban centers with higher demand. Upgrading the grid is vital but requires significant investment.
Environmental and Regulatory Hurdles:
Environmental and regulatory challenges are also prevalent. Wind power projects often face land-use restrictions, local environmental regulations, and community opposition, especially in ecologically sensitive areas. The permitting process can be lengthy and complex, further delaying the development of wind energy projects. The regulatory frameworks across Latin American countries vary, adding further complexity to project timelines and approvals.
Competition from Other Renewable Energy Sources:
The wind turbine market in Latin America also faces competition from other renewable energy sources, especially solar power. The rapid decline in the costs of solar photovoltaic (PV) technology, combined with the region’s favorable solar conditions, has led to a shift in investments towards solar energy. This competition diverts resources and financing from wind energy, impacting the growth of the wind turbine sector in the region.
Market Opportunities:
The Latin America wind turbine market presents significant opportunities driven by the region's vast and untapped wind resources. Countries like Brazil, Mexico, and Argentina possess some of the world’s strongest and most consistent wind patterns, particularly in regions such as Patagonia, northern Brazil, and the Isthmus of Tehuantepec. These areas offer immense potential for large-scale wind power projects, providing opportunities for global players to expand their operations. Additionally, the growing emphasis on clean energy and the region’s commitment to reducing carbon emissions are fueling investments in renewable energy infrastructure. As governments continue to establish favorable regulatory frameworks and offer financial incentives, the market is becoming more attractive to both local and international investors, creating a stable environment for long-term projects.
Furthermore, the continued decline in wind turbine technology costs offers a significant opportunity for the region to enhance the competitiveness of wind energy. Technological advancements, including larger turbines, higher efficiency, and improved manufacturing techniques, are making wind energy more cost-effective, thereby encouraging further investments. The integration of energy storage systems and smart grids will also enhance grid stability, enabling more reliable wind energy generation and distribution. With countries like Chile and Uruguay witnessing rapid growth in wind installations, these emerging markets represent substantial opportunities for further expansion. The combined geographical advantages, policy support, and advancements in technology position Latin America as a key player in the global renewable energy transition.
Market Segmentation Analysis:
By Axis Type
The Latin American wind turbine market is primarily segmented by axis type into horizontal-axis wind turbines (HAWTs) and vertical-axis wind turbines (VAWTs). Horizontal-axis turbines dominate the market due to their higher efficiency and better performance in areas with strong wind conditions. HAWTs are commonly used for large-scale, utility-driven projects across the region. Vertical-axis turbines, though less efficient, are gaining attention in small-scale or urban applications due to their ability to operate in turbulent wind conditions.
By Capacity
The market is also segmented by capacity, with turbines typically categorized into small (less than 100 kW), medium (100 kW to 1 MW), and large (over 1 MW) capacities. Large-capacity turbines are the most commonly deployed in Latin America, particularly in utility-scale wind farms. These turbines offer higher energy output and cost efficiency, making them ideal for large-scale renewable energy projects aimed at meeting national energy demands.
By Location of Deployment
Wind turbines in Latin America are deployed primarily onshore and offshore. Onshore wind turbines account for the majority of the market share, with favorable conditions in regions like Patagonia in Argentina and the northeastern coast of Brazil. Offshore wind turbine projects are emerging but still in the early stages of development due to higher initial costs and technological challenges.
By End-Use
The end-use segments of the Latin American wind turbine market include industrial, commercial, and residential applications. Industrial applications dominate the market, particularly in large-scale energy production projects. However, commercial and residential sectors are also growing, particularly with the rise in small-scale, distributed generation systems aimed at reducing energy costs.
Segmentations:
By Axis Type
- Horizontal-Axis Wind Turbines (HAWTs)
- Vertical-Axis Wind Turbines (VAWTs)
By Capacity
- Small (less than 100 kW)
- Medium (100 kW to 1 MW)
- Large (over 1 MW)
By Location of Deployment
- Onshore
- Offshore
By End-Use
- Industrial
- Commercial
- Residential
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Brazil
Brazil leads the Latin American wind turbine market, commanding the largest market share in the region. As of recent reports, Brazil accounts for over 60% of the total wind energy capacity in Latin America. The country’s vast wind resources, particularly in the northeastern coastal regions, provide a strong foundation for wind energy development. The Brazilian government has been proactive in supporting the sector through favorable policies, including auctions for renewable energy contracts, tax incentives, and a well-established grid infrastructure. These initiatives have attracted both local and international investments, positioning Brazil as a regional leader in wind energy production. The country's significant focus on renewable energy is further supported by its ambitious targets to increase the share of wind energy in its power mix, driving market growth.
Mexico
Mexico holds the second-largest market share in the Latin American wind turbine market, contributing 20% to the region's total capacity. The country’s wind potential is particularly high in the Isthmus of Tehuantepec, one of the windiest areas in the world. Mexico has made considerable strides in its renewable energy policy framework, particularly since the 2012 Energy Reform, which opened up opportunities for private investments in the wind sector. The country has developed several large-scale wind farms, which have contributed significantly to its renewable energy capacity. Mexico’s commitment to reducing carbon emissions and its growing energy demand continue to drive the expansion of wind energy projects across the country.
Argentina
Argentina accounts for 10% of the total wind turbine market share in Latin America. The country has abundant wind resources, particularly in the Patagonia region, which has become a key area for wind energy development. Argentina has made significant progress in attracting international investments through competitive renewable energy auctions, which have led to the installation of large-scale wind farms. The Argentine government’s continued focus on diversifying its energy mix and meeting environmental goals has fostered a favorable market environment for wind energy development.
Chile and Uruguay
Chile and Uruguay each represent smaller yet growing markets, with shares 5% and 3%, respectively. Chile’s wind energy sector is expanding rapidly, driven by high wind potential in regions like the Atacama Desert and Patagonian coast. Uruguay has also been successful in integrating wind energy into its grid, achieving over 30% of its electricity generation from wind power. Both countries are making substantial progress in meeting renewable energy targets, contributing to the overall growth of the Latin American wind turbine market.
Key Player Analysis:
- Iberdrola SA
- Colbun SA
- Enel SpA
- Vestas Wind Systems A/S
- Siemens Gamesa Renewable Energy SA
- Latin America Power S.A. (LAP)
- Acciona SA
- Suzlon Energy Limited
- GE Renewable Energy
- Nordex SE
Competitive Analysis:
The Latin American wind turbine market is highly competitive, with a mix of global and regional players. Key international companies such as Siemens Gamesa, Vestas, GE Renewable Energy, and Nordex dominate the market, leveraging their technological expertise, large-scale production capabilities, and extensive experience in wind energy projects. For instance, Siemens Gamesa has installed over 107 GW of wind power capacity globally. These players benefit from established global supply chains and strong financial backing, enabling them to secure major contracts across the region.
Regional companies, including Iberdrola and Acciona, have also solidified their positions in the market by focusing on local projects and expanding their footprint in emerging markets. The competition is further intensified by the increasing participation of private investors and emerging players who focus on cost-effective solutions and innovative technologies. As the demand for wind energy grows, the competition will likely escalate, driving further technological advancements and pricing strategies to gain market share.
Recent Developments:
- In January 2025, Vestas Wind Systems A/S secured a 384 MW order for the second phase of DTEK’s Tyligulska project in Ukraine, which will contribute to the project's total capacity of 498 MW.
- In January 2025, Chile inaugurated the second largest wind farm in Latin America, the Horizonte Wind Farm, with an installed capacity of 816 MW, constructed by Colbun SA.
- In January 2024, Iberdrola SA's global renewable energy capacity exceeded 42 GW, with a notable increase in onshore wind capacity in Brazil and other markets.
- In December 2024, Vestas Wind Systems A/S received a 99 MW repowering order from Iberdrola in Spain, which includes the supply and installation of 22 new wind turbines to replace 139 legacy models, increasing energy output by around 30 percent.
Market Concentration & Characteristics:
The Latin American wind turbine market exhibits moderate concentration, with a few large players dominating the landscape. Companies like Siemens Gamesa, Vestas, GE Renewable Energy, and Nordex account for a significant share of the market, leveraging their global presence and technological capabilities to secure major contracts. These key players benefit from economies of scale, established supply chains, and strong financial resources, allowing them to lead large-scale wind farm projects. However, the market also features regional players such as Iberdrola, Acciona, and other emerging local firms, which are capitalizing on favorable government policies and incentives. The market is characterized by high competition, technological innovation, and a focus on cost reduction. As the demand for renewable energy increases, the market will likely experience a more diversified competitive landscape, with both multinational and regional players vying for market share in emerging economies.
Report Coverage:
The research report offers an in-depth analysis based on Axis Type, Capacity, Location of Deployment, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Brazil will continue to lead the Latin American wind turbine market, driving much of the region’s wind energy growth due to its vast wind resources.
- Mexico's wind energy sector is expected to expand significantly, especially in the Isthmus of Tehuantepec, due to its favorable wind conditions.
- Argentina’s renewable energy initiatives will foster increased investments in wind turbine projects, particularly in the wind-rich Patagonia region.
- Chile and Uruguay are poised to grow their wind energy capacities, with Uruguay focusing on achieving a higher share of wind in its energy mix.
- Technological advancements in turbine design, including improved efficiency and larger capacity, will drive cost reductions and make wind energy more competitive.
- The increasing integration of energy storage solutions will enhance grid stability, facilitating higher wind energy penetration in national grids.
- Government policies and incentives across the region will continue to support the growth of wind energy, fostering a favorable investment climate.
- Public-private partnerships will play a key role in the development of large-scale wind farms across Latin America.
- Off-shore wind energy projects are expected to gain momentum as technological challenges decrease and cost structures improve.
- The growing focus on energy security, sustainability, and carbon reduction targets will push Latin American countries to accelerate wind energy adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Wind Turbine Market?
What is the projected market size of the Latin America Wind Turbine Market by 2032?
What is the expected growth rate of the Latin America Wind Turbine Market?
What are the key drivers of growth in the Latin America Wind Turbine Market?
Which countries are leading the Latin America Wind Turbine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Latin America Wind Turbine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Latin America Wind Turbine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,214.5 million → 2032: USD 7,415.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Latin America Wind Turbine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Latin America Wind Turbine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Latin America Wind Turbine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Latin America Wind Turbine Market Drivers
- 3.3 Latin America Wind Turbine Market Restraints & Challenges
- 3.4 Latin America Wind Turbine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Latin America Wind Turbine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Latin America Wind Turbine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Latin America Wind Turbine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Latin America Wind Turbine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Latin America Wind Turbine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Latin America Wind Turbine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Latin America Wind Turbine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Latin America Wind Turbine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Latin America Wind Turbine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Latin America Wind Turbine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Latin America Wind Turbine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Latin America Wind Turbine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Latin America Wind Turbine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Latin America Wind Turbine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Latin America Wind Turbine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Latin America Wind Turbine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Latin America Wind Turbine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Latin America Wind Turbine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Latin America Wind Turbine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
