
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
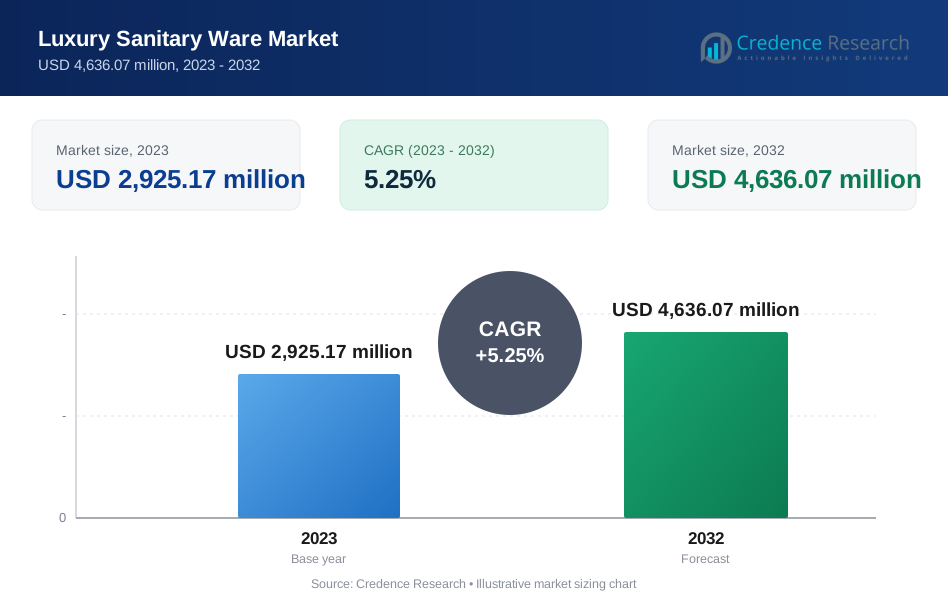
| Luxury Sanitary Ware Market Size 2023 | USD 2,925.17 Million |
| Luxury Sanitary Ware Market, CAGR | 5.25% |
| Luxury Sanitary Ware Market Size 2032 | USD 4,636.07 Million |
Market Overview
The Global Luxury Sanitary Ware Market is projected to witness substantial growth, with its value expected to surge from USD 2,925.17 million in 2023 to USD 4,636.07 million by 2032, representing a compound annual growth rate of 5.25%.
The Global Luxury Sanitary Ware Market is being propelled by several key drivers and trends. Increasing consumer preference for premium bathroom solutions, driven by rising disposable incomes and a growing focus on aesthetics and hygiene, is a primary driver. Additionally, technological advancements such as smart toilets and sensor-based faucets are reshaping the market landscape, offering convenience and efficiency. Moreover, sustainability initiatives and the demand for eco-friendly materials in sanitary ware production are gaining traction, reflecting evolving consumer preferences towards environmentally conscious products. These factors collectively contribute to the dynamic growth trajectory of the global luxury sanitary ware market.
Geographical analysis reveals a diverse landscape in the Global Luxury Sanitary Ware Market, with regions such as Asia Pacific witnessing rapid growth attributed to urbanization and increasing disposable incomes. Europe and North America remain prominent markets, driven by a penchant for high-end bathroom solutions. Key players such as TOTO, Roca, Villeroy & Boch, and Dornbracht dominate the market with their innovative product offerings, strategic partnerships, and expansion initiatives. Their focus on product differentiation, technological innovation, and customer-centric approaches solidify their positions in the competitive luxury sanitary ware market globally.
Market Drivers
Rising Disposable Income and Aspiration for Luxurious Lifestyle
A growing affluent class across the globe, particularly in developing economies like China and India, has more disposable income to spend on high-end products and experiences. By 2022, for example, China’s middle-class population is projected to exceed 550 million, while India’s will reach around 580 million. These numbers reflect a broader trend where consumers are willing to allocate approximately 30% of their renovation budget to bathroom upgrades. Moreover, a survey revealed that 60% of homeowners in urban areas of developing countries prioritize bathroom renovations to incorporate luxury features. This shift towards opulence in personal spaces underscores the increasing demand for high-quality, aesthetically pleasing sanitary products that offer both comfort and a touch of elegance. This includes a desire for luxurious bathrooms that elevate the aesthetics and functionality of their living spaces. As people seek to enhance their quality of life, they are increasingly investing in premium sanitary ware that reflects their status and taste.
Increasing Urbanization and Premium Housing Developments
The rapid urbanization trend worldwide is fueling the construction of luxury apartments, villas, and hotels. These developments incorporate high-quality, design-oriented sanitary ware to match the overall luxurious feel. In the US, the demand for high-end apartments remains strong, with luxury rentals in cities like San Francisco costing up to $10,000 per month. The construction of luxury apartment units hit a record with 200,000 units built in the first half of 2023, surpassing the previous six-month record by 25,000 units. Urbanization’s economic impact on the construction industry is significant, as it leads to an increase in construction activities to meet the demand for housing and infrastructure in urban areas. However, it also poses challenges such as limited land availability and environmental concerns. The construction industry is adapting by incorporating sustainable building practices and innovative construction methods like modular construction and 3D printing to address these challenges. With urban areas becoming hubs of economic activity and cultural exchange, there is a growing demand for sophisticated bathroom solutions that not only provide comfort but also contribute to the overall ambiance of modern living spaces.
Growing Focus on Wellness and Bathroom as a Sanctuary
The bathroom is increasingly seen as a place for relaxation and rejuvenation, not just a utilitarian space. For instance, a recent study revealed that nearly 3 in 5 bathrooms (59%) measure 100 square feet or more after renovation, with more than 3 in 5 homeowners (61%) increasing the size of their shower. This expansion often includes luxury features such as rain showers, which are becoming increasingly popular. In fact, 20% of homeowners go significantly larger, increasing the shower size by more than 50%. This trend is driving demand for spa-like features in luxury sanitary ware, such as rain showers, heated towel rails, and whirlpool bathtubs. As individuals prioritize self-care and well-being, they are willing to invest in products that transform their bathrooms into personal sanctuaries, fostering a sense of tranquility and escape from the stresses of daily life.
Evolving Consumer Preferences for Sustainability and Customization
Luxury sanitary ware manufacturers are increasingly using sustainable materials and eco-friendly practices to meet consumer demands for responsible products. Additionally, customization options in terms of finishes, materials, and designs are also a major driver as homeowners seek to create unique and personalized bathroom experiences. By offering environmentally conscious and customizable solutions, luxury sanitary ware brands are aligning with the evolving preferences of discerning consumers who value both style and sustainability in their homes.
Market Trends
Design and Material Innovation Redefining Luxury
Luxury sanitary ware is no longer just functional; it's a design statement. Sleek, minimalist lines, geometric shapes, and unique finishes are in high demand. For instance, the trend towards sleek, minimalist lines and geometric shapes is evident in the increasing popularity of freestanding bathtubs, which have seen a surge in demand by 35% in the past year. Vessel sinks, another embodiment of this trend, are chosen by 40% of homeowners undertaking bathroom renovations. High-design faucets, particularly those with unique finishes, are a key element in luxury bathroom design. For example, faucets with gold finishes have experienced a 50% increase in sales, while those with chrome finishes are not far behind at 45%. These fixtures not only serve their functional purpose but also act as focal points that enhance the overall decor.
When it comes to materials, natural stone is a preferred choice for 30% of luxury bathroom countertops, with granite being the most popular option. Stainless steel is also gaining traction, especially in modern and industrial-style bathrooms, accounting for 25% of the material choice for fixtures.
Integration of Technology and Sustainable Practices
Smart features are becoming a hallmark of luxury sanitary ware. This includes voice-activated controls for showers and toilets, touchless faucets for improved hygiene, and heated towel racks for added comfort. Voice-activated controls for showers and toilets are part of this advancement, with a 20% increase in installations over the past year. Touchless faucets, which contribute to improved hygiene, have seen a 30% rise in consumer demand, while heated towel racks have become a standard feature in 25% of luxury bathroom renovations. Looking to the future, integrated entertainment systems and personalized settings are expected to become more prevalent, with a projected 40% of luxury bathrooms to include such smart features by 2030.Expect even more advanced features to emerge in the future, such as integrated entertainment systems and personalized settings tailored to individual preferences. By embracing technology, luxury sanitary ware manufacturers are enhancing convenience and comfort in the bathroom, meeting the expectations of modern consumers seeking intelligent solutions for their homes. Eco-conscious consumers are driving the demand for sustainable practices in luxury sanitary ware production. Manufacturers are using recycled materials, water-saving technologies, and energy-efficient processes to create luxurious products with minimal environmental impact. From eco-friendly manufacturing practices to water-efficient fixtures, sustainability is becoming synonymous with luxury in the bathroom industry.
Market Challenges Analysis
High Price Point and Economic Fluctuations:
Luxury sanitary ware comes with a hefty price tag. Economic downturns or volatile raw material prices can significantly impact consumer spending on non-essential luxury items. The challenge lies in maintaining demand during economic uncertainties while ensuring that pricing remains competitive without compromising on the perceived value of luxury. Manufacturers must adopt flexible pricing strategies and cost-effective production methods to mitigate the effects of economic fluctuations and sustain market growth amidst varying financial climates.
Fierce Competition and Counterfeits:
The market is becoming increasingly competitive, with established players and new entrants vying for market share. Additionally, counterfeits imitating luxury designs can pose a threat, impacting brand value and customer trust. To address this challenge, luxury sanitary ware brands must focus on innovation, quality assurance, and brand integrity. Implementing stringent intellectual property protection measures and collaborating with regulatory authorities to combat counterfeiting are essential steps in safeguarding brand reputation and maintaining consumer confidence. Moreover, differentiation through unique designs, superior craftsmanship, and exceptional customer service can help luxury brands stand out in a crowded marketplace and deter counterfeiters.
Market Segmentation Analysis:
By Type:
The Global Luxury Sanitary Ware Market is segmented by type, catering to diverse consumer preferences and spatial requirements. The segment includes Cisterns, Toilet Sinks, Pedestals, and Wash Basins. Cisterns, essential for flushing mechanisms, are available in various designs to complement bathroom aesthetics. Toilet Sinks, combining functionality with space-saving features, appeal to consumers seeking compact yet elegant solutions. Pedestals, known for their classic charm, add a touch of sophistication to traditional bathroom settings. Wash Basins, available in a range of sizes and shapes, offer versatility and style to modern bathrooms. This segmentation allows manufacturers to tailor their product offerings to different consumer needs, ensuring a comprehensive range of luxury sanitary ware options for discerning buyers.
By Product Type:
Luxury sanitary ware products are categorized into Ceramic, Acrylic Plastic, Pressed Metal, and Others. Ceramic remains a popular choice due to its durability, versatility, and timeless appeal, suitable for both contemporary and traditional bathroom designs. Acrylic Plastic, prized for its lightweight nature and affordability, appeals to consumers seeking cost-effective luxury solutions without compromising on quality. Pressed Metal, known for its intricate detailing and vintage charm, adds a unique touch of elegance to upscale bathrooms. Additionally, the "Others" category encompasses innovative materials and unconventional designs, catering to niche preferences and pushing the boundaries of luxury sanitary ware innovation. This segmentation facilitates a nuanced understanding of market dynamics and consumer preferences, enabling manufacturers to develop targeted marketing strategies and product innovations that resonate with diverse customer segments.
Segments:
Based on Type
- Cistern
- Toilet Sink
- Pedestal
- Wash Basin
Based on Product Type
- Ceramic
- Acrylic Plastic
- Pressed Metal
- Others
Based on End-user
- Residential
- Commercial
Based on the Geography:
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Europe
- Germany
- Italy
- France
- The United Kingdom
- Spain
- NORDICS
- BENELUX
- Russia
- Rest of Europe
- East Asia
- China
- Japan
- South Korea
- South Asia Pacific
- India
- ASEAN
- ANZ (Australia and New Zealand)
- Rest of South Asia Pacific
- The Middle East and Africa
- GCC Countries
- Turkey
- North Africa
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently holds the largest market share, accounting for approximately 30% of the global revenue. This dominance can be attributed to the region's well-established luxury housing market, the presence of major luxury sanitary ware brands, and the high disposable incomes of consumers. The United States and Canada are key contributors, with their thriving construction and renovation sectors fueling the demand for high-end bathroom fixtures and fittings.
Europe
Europe follows closely, capturing a market share of around 25%. The region's strong emphasis on design and aesthetics, coupled with the growing trend of luxury home renovations, have fueled the demand for luxury sanitary ware products. Major economies such as Germany, the United Kingdom, and France significantly contribute to the market's growth through their affluent consumer base and the presence of renowned luxury bathroom brands.
Key Player Analysis
- HSIL
- Roca
- Villeroy & Boch
- Queo Bathrooms
- Artize, Grotto
- Jado, Maison Valentina
- Dornbracht
- TOTO
- VITRA
Competitive Analysis
In the competitive landscape of the Global Luxury Sanitary Ware Market, several leading players vie for market dominance, each bringing unique strengths and strategies to the forefront. HSIL, known for its premium Hindware brand, emphasizes innovation and design excellence, catering to diverse consumer preferences. Roca, a global leader in bathroom solutions, boasts a wide product portfolio characterized by superior craftsmanship and technological innovation. Villeroy & Boch stands out for its timeless elegance and commitment to sustainability, offering luxury sanitary ware products crafted with precision and eco-friendly materials. Queo Bathrooms distinguishes itself through avant-garde designs and bespoke solutions, catering to discerning customers seeking personalized luxury experiences. TOTO, renowned for its cutting-edge technologies and Japanese craftsmanship, sets industry standards for performance and durability. This competitive analysis underscores the dynamic nature of the luxury sanitary ware market, where leading players continually strive to innovate, differentiate, and capture market share through superior product offerings and strategic positioning.
Recent Developments
In February 2022, Kohler had collaborated with Daniel Arsham to manufacture a unique type of one-of-a-kid 3D sink, with better features that could attract more consumers in upcoming period.
Market Concentration & Characteristics
The Global Luxury Sanitary Ware Market exhibits characteristics of moderate to high market concentration, with a few key players dominating significant market shares. These leading companies leverage their extensive product portfolios, brand recognition, and distribution networks to establish strong footholds in the industry. Market concentration is driven by factors such as technological advancements, design innovations, and strategic acquisitions, which enable established players to maintain competitive advantages and expand their market presence. Additionally, the luxury sanitary ware market is characterized by intense competition, as manufacturers continually strive to differentiate their offerings through premium quality, unique designs, and sustainability initiatives. Despite the presence of dominant players, the market also accommodates niche brands and emerging players, contributing to a diverse and dynamic competitive landscape. Overall, market concentration in the luxury sanitary ware segment reflects a balance between established industry leaders and emerging challengers vying for market share and consumer attention.
Report Coverage
The research report offers an in-depth analysis based on Type, Product Type, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The Global Luxury Sanitary Ware Market is expected to witness sustained growth driven by rising disposable incomes and urbanization trends.
- Technological Integration: Increasing adoption of smart features such as touchless controls and self-cleaning mechanisms will redefine luxury sanitary ware.
- Sustainable Practices: Environmental concerns will drive demand for eco-friendly materials and manufacturing processes in luxury sanitary ware production.
- Personalization: Customization options will become increasingly prevalent, allowing consumers to tailor their bathroom fixtures to their individual preferences.
- Focus on Wellness: Demand for spa-like features such as chromatherapy lighting and massage systems will continue to grow as consumers prioritize relaxation and well-being.
- Emerging Markets: Developing economies will present lucrative opportunities for market expansion, fueled by rapid urban development and growing affluence.
- Design Innovation: Manufacturers will focus on sleek, minimalist designs and geometric shapes to meet evolving aesthetic preferences.
- Premiumization: Luxury sanitary ware brands will introduce high-end products with premium materials and exclusive features to cater to discerning consumers.
- Digital Marketing: Adoption of digital platforms and online sales channels will increase, facilitating greater accessibility and convenience for consumers.
- Strategic Partnerships: Collaborations between luxury sanitary ware manufacturers and interior designers/architects will drive innovation and enhance brand visibility in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Luxury Sanitary Ware Market?
What factors are driving the growth of the Global Luxury Sanitary Ware Market?
What are the key segments within the Global Luxury Sanitary Ware Market?
What are some challenges faced by the Global Luxury Sanitary Ware Market?
Who are the major players in the Global Luxury Sanitary Ware Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Luxury Sanitary Ware Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Luxury Sanitary Ware Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,925.17 million → 2032: USD 4,636.07 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Luxury Sanitary Ware Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Luxury Sanitary Ware Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Luxury Sanitary Ware Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Luxury Sanitary Ware Market Drivers
- 3.3 Luxury Sanitary Ware Market Restraints & Challenges
- 3.4 Luxury Sanitary Ware Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Luxury Sanitary Ware Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Luxury Sanitary Ware Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Luxury Sanitary Ware category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Luxury Sanitary Ware Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Luxury Sanitary Ware Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Luxury Sanitary Ware. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Luxury Sanitary Ware Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Luxury Sanitary Ware Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Luxury Sanitary Ware Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Luxury Sanitary Ware (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Luxury Sanitary Ware
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Luxury Sanitary Ware Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Luxury Sanitary Ware Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Luxury Sanitary Ware Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Luxury Sanitary Ware Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Luxury Sanitary Ware Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Luxury Sanitary Ware Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Luxury Sanitary Ware Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Luxury Sanitary Ware Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
