
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
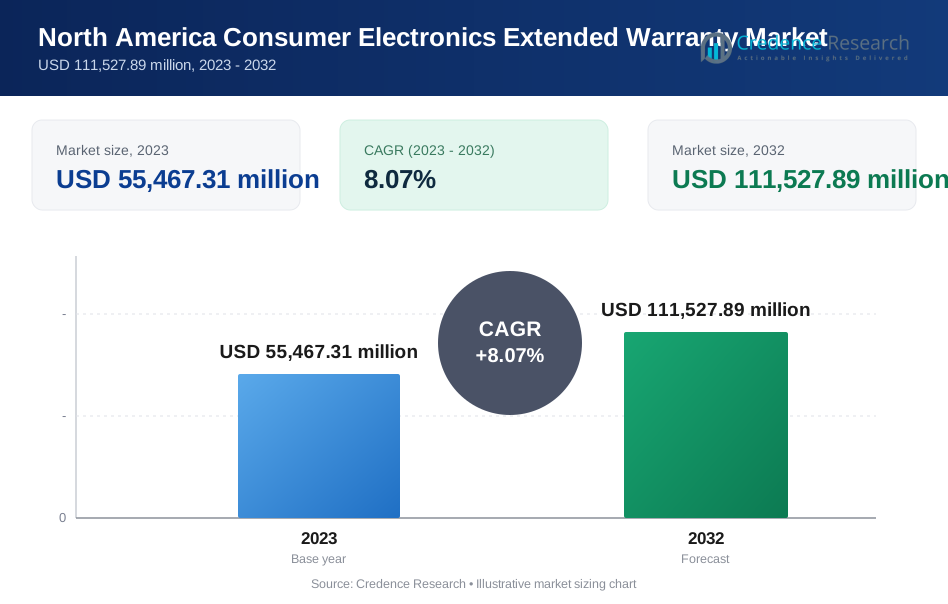
| North America Consumer Electronics Extended Warranty Market Size 2023 | USD 55,467.31 Million |
| North America Consumer Electronics Extended Warranty Market , CAGR | 8.07% |
| North America Consumer Electronics Extended Warranty Market Size 2032 | USD 111,527.89 Million |
Market Overview
The North America Consumer Electronics Extended Warranty Market is on a trajectory of significant growth, with market size poised to expand from USD 55,467.31 million in 2023 to an estimated USD 111,527.89 million by 2032. This robust expansion reflects a compound annual growth rate (CAGR) of 8.07% over the forecast period from 2024 to 2032. The increasing valuation of this market underscores the growing consumer demand for extended warranties, which are seen as a method to safeguard their investments in electronic devices against unforeseen repair costs post the manufacturer's warranty expiry.
Driving this market are several key factors, including the rapid technological advancements in consumer electronics that often bring complex functionalities, making repairs expensive and technical support crucial. There is also a notable rise in the consumer preference for extended coverage plans due to the increasing costs associated with electronic device repairs and replacements. Moreover, the growing penetration of smartphones, tablets, and large home appliances with higher price tags has significantly contributed to the market's growth. Additionally, trends such as the integration of AI and machine learning in customer service for warranty management are enhancing customer experience, further propelling market growth.
Geographically, the United States holds a dominant position in the North America Consumer Electronics Extended Warranty Market, driven by high consumer electronics ownership rates and greater consumer awareness about the benefits of warranty extensions. Canada and Mexico also contribute to the regional market growth, with increasing electronic sales and expanding retail sectors. Major players operating in this market include Asurion, LLC, SquareTrade, Inc., and Best Buy Co., Inc., among others. These companies are intensively focusing on expanding their service offerings and improving customer service to capitalize on the market opportunities. The competitive landscape is characterized by strategic alliances, technological innovations, and customer-centric service enhancements, which are crucial for maintaining market share in this evolving industry.
Market Drivers
Increasing Complexity and Cost of Consumer Electronic:
As consumer electronics continue to evolve, incorporating advanced technologies and features, they also become more complex and expensive to repair. Modern devices such as smartphones, laptops, and smart home systems integrate delicate components and sophisticated software that can be costly to fix if damaged. For instance, the average repair cost of a smartphone can range from $100 to $200 depending on the model and the type of damage. This rise in potential repair costs makes extended warranties an attractive option for consumers seeking to protect their investments beyond the standard warranty period.
High Replacement Costs of Electronics:
Today’s consumer electronics market features devices with high acquisition costs. The financial impact of replacing these devices in the event of a malfunction can be significant. Extended warranties offer a safety net by covering repair or replacement costs, thus providing peace of mind to consumers. For example, a high-end laptop can cost upwards of $1,000. The financial impact of replacing these devices in the event of a malfunction can be significant. Extended warranties offer a safety net by covering repair or replacement costs, thus providing peace of mind to consumers. This security is particularly appealing in a market where new models of electronics are frequently released at premium price points, encouraging consumers to opt for warranty extensions to safeguard their purchases.
Consumer Demand for Hassle-Free Service:
In our fast-paced world, consumers value convenience and are increasingly willing to pay for services that simplify their lives. Extended warranties often come with features such as no-cost repairs, home service, and quick replacements, which are highly valued. For instance, a survey showed that 70% of consumers would prefer a warranty plan that offers home service. The hassle-free service provided under these plans enhances consumer satisfaction and loyalty, acting as a significant market driver. This trend is supported by a customer service infrastructure that leverages technology such as artificial intelligence and online platforms to streamline claim processes and improve service delivery.
Growth in Sales of Consumer Electronics:
The continuous growth in the sales of consumer electronics fundamentally drives the demand for extended warranties. With each purchase, there is a potential addition to the market for extended warranties. Factors such as rising disposable incomes, the proliferation of high-tech gadgets, and lifestyle shifts that prioritize tech connectivity stimulate the sales of these devices. The consistent release of innovative products that attract tech-savvy consumers and gadget enthusiasts further fuels this trend, thereby broadening the base of consumers likely to seek extended warranty services.
Market Trends
Integration of Artificial Intelligence (AI):
Extended warranty providers are increasingly incorporating AI into their service offerings. For instance, AI technologies can reduce claim processing times by up to 50%, leading to faster response times and improved customer satisfaction. This integration helps in personalizing the warranty offerings based on user behavior and product usage patterns, significantly enhancing the consumer experience.
Rise of Online Warranty Registrations and Claims:
The shift towards digital platforms for warranty registrations and claims submission is a notable trend. For example, a recent survey showed that 80% of consumers prefer managing their warranties online, including the ability to register products, file claims, and track repair status in real-time. This digital shift is facilitated by the development of dedicated mobile apps and customer portals by warranty providers.
Expansion of Coverage Options:
There is a growing trend towards offering more comprehensive and flexible warranty plans. These plans are becoming increasingly tailored, covering a broad range of incidents from mechanical breakdowns to accidental damage. For instance, a study found that 60% of consumers would be more likely to purchase an extended warranty if it included coverage for theft and loss.
Preventative Maintenance Services:
Warranty providers are now offering services that go beyond traditional coverage; they include preventative maintenance to enhance the longevity of products. This proactive approach not only improves the lifespan of consumer electronics but also ensures better functionality over time. For example, regular preventative maintenance can reduce the overall cost of ownership for consumers by up to 30%.
Partnerships with Retailers and Manufacturers:
Extended warranty firms are strengthening partnerships with electronics manufacturers and retailers to offer warranty products at the point of sale. This collaboration benefits all parties involved—consumers receive seamless coverage options, while retailers and manufacturers enhance their value proposition and customer loyalty.
Customer Education and Transparency:
Providers are focusing on educating consumers about the benefits and terms of extended warranties. This increased transparency helps in building trust and clarifies what consumers can expect from their coverage. Clear communication regarding what is and isn't covered under a warranty plan is essential for customer satisfaction and retention.
Sustainability and Eco-friendly Repairs:
With growing environmental concerns, there is a rising trend in promoting repairs over replacements. Extended warranties are supporting sustainability by encouraging and facilitating eco-friendly repair options. This not only aligns with the environmental values of consumers but also positions companies as responsible corporate citizens.
Market Restraints and Challenges
Consumer Skepticism and Trust Issues:
One of the primary challenges facing the extended warranty market is consumer skepticism. Many consumers are wary of the actual value of extended warranties, often perceiving them as unnecessary or overly expensive relative to the benefits they offer. This skepticism is compounded by instances where claims processes are perceived as cumbersome or when consumers encounter hidden exclusions that limit claim payouts. Building consumer trust remains a fundamental challenge for warranty providers.
Regulatory Scrutiny and Compliance:
The extended warranty sector is subject to significant regulatory oversight, which varies widely across different jurisdictions in North America. Compliance with these regulations can be costly and complex, particularly for companies that operate across state or national borders. Ensuring that warranty terms and marketing practices comply with legal standards to avoid penalties is a continuous challenge that requires diligent legal oversight and adaptability to changing laws.
Intense Competition from Third-party Providers and Retailers:
The market is highly competitive, with numerous players including OEMs (Original Equipment Manufacturers), retailers, and independent warranty providers. This competition often leads to price wars and necessitates substantial marketing expenditure to stand out in a crowded market. Companies must innovate continuously, not only in their service offerings but also in customer service and technological integration to retain a competitive edge.
Economic Downturns:
Economic instability or downturns can significantly impact consumer spending on non-essential goods and services, including extended warranties. In times of economic uncertainty, consumers tend to prioritize basic needs and might view extended warranties as an expendable expense. This sensitivity to economic cycles can lead to fluctuations in market growth, posing a challenge for steady revenue streams.
Technological Disruptions:
Rapid technological advancements can both drive and hinder the extended warranty market. While new tech features in electronics can increase the demand for warranties, faster innovation cycles can shorten the lifespan of products, thereby diminishing the perceived need for extended protection. Additionally, tech-savvy consumers might utilize self-service options or third-party repair services that can be more cost-effective than official repair services under extended warranties.
Market Segmentation Analysis
By Product Type
Smartphones and tablets command a substantial market share in the extended warranty sector due to their high repair costs and vulnerability to damage. Similarly, the consistent demand for extended warranties for computers and laptops is driven by their crucial role in both personal and professional settings. Furthermore, as home appliances become more expensive and complex, consumer interest in securing extended warranty protection for these items also rises.
By Coverage Type
Standard Protection Plans, which cover basic issues such as mechanical failures and electrical problems, are popular for their affordability. Meanwhile, Accidental Protection Plans are gaining favor, especially for portable electronics like smartphones and laptops, as they provide coverage for damage resulting from accidents.
By Distribution Channel
Many consumers choose to purchase extended warranties directly from Original Equipment Manufacturers (OEMs) at the point of sale, enticed by the promise of brand-specific service and support. Large electronics retailers complement this by offering extended warranties that include additional benefits like in-store repair services, catering to consumers who appreciate the tangible aspects of physical retail experiences. Furthermore, the convenience of online shopping continues to permeate the warranty sector, with consumers increasingly gravitating towards digital platforms for their competitive pricing and simplified purchasing processes.
Segments
Based on Product Type
- Smartphones and Tablets
- Computers and Laptops
- Home Appliances
Based on Coverage Type
- Standard Protection Plans
- Accidental Protection Plans
Based on Distribution Channel
- OEMs (Original Equipment Manufacturers)
- Retailers
- Online Providers
Regional Analysis
United States (75%):
Holding the largest share of the market at approximately 75%, the United States dominates the North America Consumer Electronics Extended Warranty Market. The U.S. market is propelled by high consumer spending power and a strong propensity for adopting the latest technological innovations. Americans tend to purchase high-end electronics frequently, and the high cost associated with these devices drives the demand for extended warranties. Moreover, the presence of major electronics manufacturers and retailers who actively promote these services enhances market penetration. The sophisticated consumer awareness regarding the benefits of warranty extensions also significantly contributes to this dominance.
Canada (15%):
Canada accounts for about 15% of the market share and displays a robust growth trajectory similar to the United States. Canadian consumers are similarly tech-savvy and exhibit a growing preference for safeguarding their electronic investments. The market is bolstered by a stable economic environment and a high standard of living, which supports discretionary expenditures like extended warranties. Retail channels are particularly strong in Canada, with big-box electronics stores and online platforms playing significant roles in distributing these warranty services. Furthermore, the country’s focus on consumer rights and protections ensures that warranty providers maintain high standards of service quality.
Mexico (10%):
Mexico, while smaller in comparison, holds around 10% of the market share but is rapidly expanding due to increasing penetration of consumer electronics in urban and rural areas alike. The growth in Mexico is fueled by improving economic conditions and a youthful demographic that is increasingly adopting mobile devices and other electronics. The market here is also driven by the rising awareness among consumers about the benefits of extended warranties, which are becoming more accessible through expanding retail networks and digital sales platforms.
Key players
- Warranty Life
- Upsie
- Assurant Solutions
- com Inc.
- Protect Your Bubble
- SquareTrade
Competitive Analysis
In the competitive landscape of the North America Consumer Electronics Extended Warranty Market, these key players are intensifying their strategies to capitalize on the growing demand for extended warranties. Companies like Assurant Solutions and SquareTrade are renowned for their comprehensive coverage options and customer-centric services, appealing to a wide consumer base. Newer entrants such as Upsie are disrupting the market by offering transparent, user-friendly warranty products at competitive prices, challenging traditional market norms. Amazon.com Inc. leverages its vast distribution network and customer reach to push its warranty services, often bundling them with electronics sales. Meanwhile, specialized providers like Warranty Life and Protect Your Bubble focus on niche marketing strategies and personalized plans to differentiate themselves in a crowded market. Together, these companies are continually evolving, employing innovative tactics to enhance customer experience and expand their market presence.
Recent Developments
In January 2023, Voltas and OneDios joined forces to roll out a nationwide extended warranty program, empowering customers to purchase extended warranties for Voltas and Voltas Beko products via the OneDios app. This collaboration ensures access to brand-authorized services, original spare parts, and competitive pricing, while the app simplifies warranty claims and enables users to lodge complaints in under 60 seconds.
In February 2024, AmTrust disclosed adjustments in automotive warranty program claim severity amidst shifting industry dynamics. Concurrently, the company intensified its focus on engaging with past customers, aiming to bolster customer satisfaction and retention.
In March 2024, ASSURANT Inc. unveiled an innovative AI-powered claims chatbot designed to facilitate swift and hassle-free claims processing for customers, enhancing overall service efficiency and customer experience.
By April 2024, Asurion had forged a partnership with electric scooter manufacturer Okinawa Autotech to introduce an extended warranty initiative in India, covering essential powertrain components. This collaboration aims to provide Okinawa Autotech customers with added peace of mind and confidence in their electric scooter ownership experience.
Market Concentration and Characteristics
The North America Consumer Electronics Extended Warranty Market is moderately concentrated, characterized by the presence of a few major players alongside numerous smaller companies competing for market share. This concentration enables dominant firms such as Assurant Solutions, SquareTrade, and Amazon.com Inc. to exert significant influence over market trends and pricing strategies. However, the market also shows characteristics of competitiveness due to the entry of innovative players like Upsie, which challenge the status quo with transparent pricing and customer-friendly policies. The market's dynamics are further shaped by technological advancements and evolving consumer expectations, which demand continual adaptation and enhancement of warranty products. This results in a vibrant market environment where companies must remain agile and consumer-focused to maintain and grow their market positions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Coverage Type, Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As consumer electronics become increasingly sophisticated, the demand for extended warranties to cover these high-tech investments will continue to grow.
- Increased consumer education about the benefits of extended warranties will likely lead to higher uptake, particularly as electronic devices become central to everyday life.
- The shift towards online purchasing will spur further growth in extended warranties, as e-commerce platforms often offer these services as add-ons.
- Extended warranty providers are expected to broaden their coverage options to include accidental damage and theft, making these plans more appealing to consumers.
- Companies will increasingly integrate their offerings with tech support services, enhancing the overall value proposition of their warranty plans.
- The market will see the entrance of new competitors, which will stimulate innovation and potentially drive down prices through increased competition.
- Changes in consumer protection laws and regulations could shape the scope and features of warranty services, impacting market dynamics.
- Enhanced customer service and streamlined claims processes will become crucial competitive differentiators for companies in the market.
- Strategic partnerships between electronics manufacturers and warranty providers are likely to increase, providing consumers with more integrated and seamless warranty offerings.
- There will be a growing emphasis on sustainability, with warranty providers potentially offering services that emphasize device longevity and eco-friendly repair options.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the North America Consumer Electronics Extended Warranty Market by 2032?
Why are extended warranties becoming increasingly popular in North America?
What are the primary drivers of the extended warranty market in North America?
Which country holds the largest share in the North America Consumer Electronics Extended Warranty Market?
What trends are shaping the extended warranty market currently?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 North America Consumer Electronics Extended Warranty Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global North America Consumer Electronics Extended Warranty Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 55,467.31 million → 2032: USD 111,527.89 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 North America Consumer Electronics Extended Warranty Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. North America Consumer Electronics Extended Warranty Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 North America Consumer Electronics Extended Warranty Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 North America Consumer Electronics Extended Warranty Market Drivers
- 3.3 North America Consumer Electronics Extended Warranty Market Restraints & Challenges
- 3.4 North America Consumer Electronics Extended Warranty Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 North America Consumer Electronics Extended Warranty Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 North America Consumer Electronics Extended Warranty Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, North America Consumer Electronics Extended Warranty category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 North America Consumer Electronics Extended Warranty Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. North America Consumer Electronics Extended Warranty Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the North America Consumer Electronics Extended Warranty market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 North America Consumer Electronics Extended Warranty Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 North America Consumer Electronics Extended Warranty Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 North America Consumer Electronics Extended Warranty Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in North America Consumer Electronics Extended Warranty (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New North America Consumer Electronics Extended Warranty Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global North America Consumer Electronics Extended Warranty Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America North America Consumer Electronics Extended Warranty Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe North America Consumer Electronics Extended Warranty Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific North America Consumer Electronics Extended Warranty Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America North America Consumer Electronics Extended Warranty Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East North America Consumer Electronics Extended Warranty Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa North America Consumer Electronics Extended Warranty Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. North America Consumer Electronics Extended Warranty Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
