
What are the diagnosis and treatment options commonly available in Persistent Corneal Epithelial Defects (PCEDs)?
The failure of fast re-epithelialization and closure within 10-14 days following corneal damage, even with routine supportive therapy, results in persistent corneal epithelial defects (PEDs or PCEDs). PED awareness has risen recently due to expanded research efforts across the ophthalmology spectrum. However, while the exact prevalence of PED is unknown, several studies have estimated it based on its causal occurrence in conjunction with underlying diseases.
Loss of corneal epithelial cells, delayed epithelialization post-injury, non-healing epithelial defect, and others are some of the symptoms of PEDs, which can be caused by epithelial/limbal, inflammatory, neurotrophic, mechanical, and other reasons.
In addition, infection, stromal ulceration, perforation, scarring, and impaired visual acuity can all result from disruptions in this epithelial layer. According to DelveInsight, the total number of Persistent Corneal Epithelial Defects incident cases in the 7MM in 2020 was estimated to be 241,452.
PCED affects males more than females. Fluorescein instillation is used to monitor the extent, location, and depth of a persistent corneal epithelial defect throughout the evaluation. It takes longer for fluorescein to absorb into the epithelium and stroma in deeper persistent corneal epithelial abnormalities.
A comprehensive physical examination should disclose signs such as anterior chamber inflammation, eyelid anomalies, or diminished corneal sensibility, as in the case of neurotrophic persistent corneal epithelial defects. Moreover, persistent corneal epithelial defects are currently managed using a sequential approach, beginning with conservative measures and advancing to medicinal or surgical therapies if they are recalcitrant.
Lubrication, bandaging soft contact lenses, punctal plugs, debridement, and tarsorrhaphy are all included. Initially, the eye is lubricated aggressively every 1-2 hours with preservative-free artificial tears and ocular ointments. Persistent corneal epithelial abnormalities are also treated with tetracyclines, prophylactic Neurotrophic Keratitis (N.K.) antibiotics, and steroids. Inflammatory Disease tetracyclines have been proven to be beneficial in mending persistent corneal epithelial abnormalities within weeks due to their anticollagenolytic activity, which inhibits MMPs produced by inflammation mediators.
What is the Market Size of Persistent Corneal Epithelial Defects (PCEDs) in terms of value?
The global Persistent Corneal Epithelial Defects (PCEDs) Market is projected to increase at a significant CAGR of 18.50 % in the coming years. In 2021, the global Persistent Corneal Epithelial Defects (PCEDs) market was valued at USD XX million and is anticipated to reach the value of USD XX million by 2028. The demand for Persistent Corneal Epithelial Defects (PCEDs) is projected to increase substantially in the coming years and is presumed to generate revenue opportunities for the key industry players worth USD XX million during the forecast period.
What is the key emerging drug for Persistent Corneal Epithelial Defects (PCEDs)? Nexagon: OcuNexus Therapeutics, Eyevance Pharmaceuticals
It's a first-in-class natural antisense treatment that inhibits connexin43, a cell membrane hemichannel-forming protein (Cx43). Targeting gap junctions may help to minimize immune system reactions that might lead to an inflammatory cascade and enhance corneal epithelial microvasculature and regeneration. Nexagon has a competitive advantage in the United States because it was designated as an orphan medicine by the Food and Drug Clinical Causes.
Interesting Facts about Persistent Corneal Epithelial Defects (PCEDs) Industry
- The increased prevalence of chronic corneal epithelial defect formation is propelling the market forward.
- The market will be fuelled by an aging population that is predisposed to PCED.
- Increased knowledge of disease diagnosis and treatment will create new opportunities for the persistent corneal epithelial defects market to grow.
- Novel techniques for treating/improving disease symptoms are at the heart of developing medicines.
- The development of PED medicines involves a number of significant actors.
- North America region had a significant share in terms of volume as well as value in the global Persistent Corneal Epithelial Defects (PCEDs) market in 2021 and is projected to continue its dominance over the forecast period.
- Aggressive lubrication, punctal occlusion, bandage soft contact lenses, pressure patching, tetracyclines, prophylactic Neurotrophic Keratitis (N.K.) antibiotics, and steroids have a monopoly on the persistent corneal epithelial defects market.
- The market for Persistent Corneal Epithelial Defects (PCEDs) is moderately competitive, with many prominent players.
- Few big players currently dominate the market in terms of market share. The demand for innovative medicines, combined with the lack of significant actors, resulted in increased R&D from the academic-industry cooperation, promoting open innovation and emphasizing PED targeting. Novel medicines are showing promise in the treatment of non-healing corneal epithelium.
Who are the Top 10 players/companies in the Persistent Corneal Epithelial Defects (PCEDs) market in terms of value?
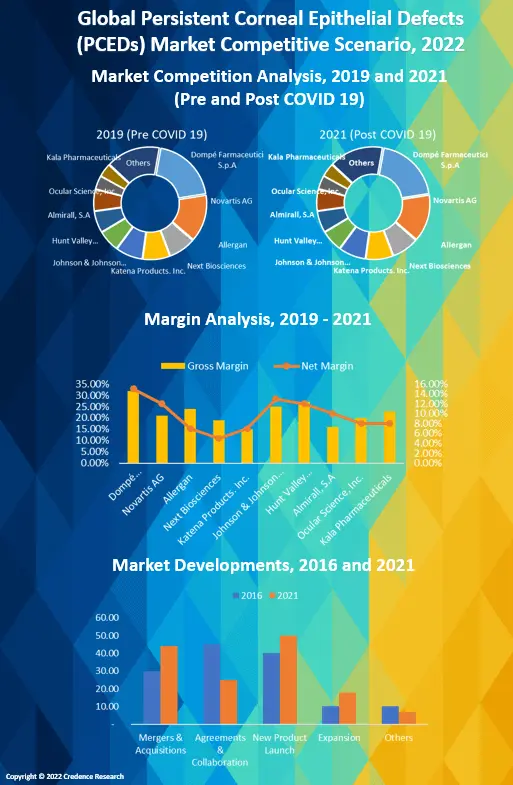
The key players in the global Persistent Corneal Epithelial Defects (PCEDs) market in terms of value includes Dompé Faraceutici S.p.A, Novartis AG, Allergan, Next Biosciences, Katena Products. Inc., Johnson & Johnson Services, Inc., Hunt Valley PhmarmaLAB, Almirall, S.A., Ocular Science, Inc., Kala Pharmaceuticals, Bausch Health, Integra LifeSciences Corporation, Laboratoires THEA S.A.S, Skye Biologics Inc., I-MED Pharma inc., and BioTissue, among other.
These key players are concentrating on new product developments as well as technological innovation to enhance their production in Persistent Corneal Epithelial Defects (PCEDs) to gain competitive market share at a global level. For instance, in April 2019, in the United States, Bausch Health launched LOTEMAX SM (Loteprednol Etabonate Ophthalmic Gel) at 0.38 percent. It's used to alleviate postoperative inflammation and pain after eye surgery.
This launch will aid in the company's expansion into the postoperative ocular inflammation/pain sector. On the other hand, in March 2019, ACUVUE OASYS with Transitions Light Intelligent Technology is now available in the United States, according to Johnson & Johnson Vision Care, Inc. As the product is a first-of-its-kind photochromic contact lens, the new TRANSITIONS in ACUVUE OASYS will help the company grow its market share.
Who are the Top 10 Countries in the Persistent Corneal Epithelial Defects (PCEDs) Market?
In the global Persistent Corneal Epithelial Defects (PCEDs) market, the major countries are the US, Canada, China, Japan, India, Germany, France, Italy, Spain, and the U.K. The largest market share is in the United States.
In the United States, the annual incidence of PED ranges from 25 to 38 cases per 100,000 people. The increased R&D from the academic-industry relationship in this region has resulted in the encouragement of open innovation and prioritizing the targeting of PED due to the desire for novel medicines in the absence of important stakeholders.
In the treatment of persistent corneal epithelium, several medicines that have lately been researched are beginning to show promise. According to studies based on the aetiology of the disease, the annual incidence of PED in the United States is less than 200,000 cases, making it a relatively rare disorder. Ocular herpes simplex can cause PED, epithelial and stromal keratitis, scarring, tissue damage, neovascularization, and glaucoma. The prevalence of ocular herpes simplex in the United States is estimated to be 20.7 per 100,000 person-years. Furthermore, PED after a corneal transplant is estimated to be around 7,558 instances per year in the United States, while PED after a diabetic vitrectomy is estimated to be around 2,480-5,257 cases per year.
Which is the Key end-user segment in the Persistent Corneal Epithelial Defects (PCEDs) Market?
The hospital segment is anticipated to dominate the persistent corneal epithelial defects (PCEDs) over the forecast period. Hospitals are an essential component of the healthcare industry, as well as a significant revenue source for the overall industry, which fuels research and innovation in the field. Various healthcare product manufacturers make remarkable investments in terms of marketing strategies as well as revenue to boost their products and services among hospitals.
As a result, strategic decisions made in the hospital sector have a significant impact on the other industries involved in the healthcare steam. Private hospitals and clinics are experiencing a decrease in inpatient footfalls as a result of the nationwide lockdown, as well as several other factors, which are leading to inadequate utilization of healthcare services by patients and a decrease in medical service volumes, resulting in an acute economic crisis.
What are the Driving Factors for the Persistent Corneal Epithelial Defects (PCEDs) Market?
The rising prevalence of persistent corneal epithelial defect production is propelling the market forward. The market will also be driven by an aging population that is predisposed to PCED. Increasing awareness about disease diagnosis and treatment will create new opportunities that will impact the growth of the persistent corneal epithelial defects treatment market during the forecast period.
Companies and academics are collaborating to assess challenges and identify opportunities for Persistent Epithelial Defect (PED) R&D. The therapies in development are centered on novel approaches to treating/improving disease symptoms. Major players are involved in the development of PED therapies. The introduction of new therapies will have a significant impact on the Persistent Epithelial Defect (PED) market.
What are the Major Restraints for Persistent Corneal Epithelial Defects (PCEDs) Market?
The poor response rate and varied adverse effects of the existing treatment options may limit the growth of the Persistent Corneal Epithelial Defects Market.
In addition, the market for persistent epithelial defects treatments is hampered by onerous regulatory procedures imposed by regulatory bodies on medications and devices. On the other hand, the high expense of treating persistent corneal epithelial abnormalities is projected to stymie market expansion. Furthermore, the persistent corneal epithelial defect market's growth is hampered by a lack of public awareness about the condition.
Which Region Dominated the World Persistent Corneal Epithelial Defects (PCEDs) Market?
In 2021, North America dominated the persistent corneal epithelial defects market due to its well-established healthcare infrastructure and the growing number of medication approvals. One of the primary factors driving the growth of the persistent corneal epithelial defect treatment market is the rising number of people suffering from corneal epithelial defects all over the world.
The rise in the prevalence of dry eye syndrome, as well as the advent of new technology development offering solutions for treating various difficulties induced by the disorder, has accelerated market expansion. The market is likely to rise at a high rate over the forecast period, owing to an increase in mechanical trauma cases.
Moreover, Asia Pacific is expanding at a rapid pace, owing to an increase in the number of geriatrics, rising healthcare costs, and, as a result, an increase in PCED cases hence, driving the growth of the persistent corneal epithelial defects market over the forecast period. In all investigations, the frequency of persistent corneal epithelial defects in the Japanese population and the rising number of elderly people in Japan were shown to be relatively high when compared to reports from other nations. The cost of healthcare per patient in Japan is estimated to be USD 323 million.
Segmentation of Global Persistent Corneal Epithelial Defects (PCEDs) Market-
Global Persistent Corneal Epithelial Defects (PCEDs) Market – By Clinical Causes
- Inflammatory Disease
- Neurotrophic Keratitis (NK)
- Epithelial/Limbal Stem Cell Deficiency
- Others
Global Persistent Corneal Epithelial Defects (PCEDs) Market – By Type
- Device
- Medication
Global Persistent Corneal Epithelial Defects (PCEDs) Market – By Distribution Channel
- Hospital Pharmacies
- Online Pharmacies
- Retail Pharmacies
Global Persistent Corneal Epithelial Defects (PCEDs) Market – By End User
- Hospitals
- Home-care
- Specialty Clinics
- Others

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Corneal Epithelial Defects
The increasing incidence of chronic corneal epithelial defects, particularly among aging populations and those with underlying ocular or systemic diseases, is driving demand for effective PCED treatments.
Advancements in Diagnosis and Treatment Awareness
Expanded research efforts and greater awareness among healthcare professionals and patients are leading to earlier diagnosis and more aggressive management of PCEDs, fueling market growth.
Development of Novel Therapeutics and Technologies
The introduction of innovative therapies such as antisense treatments (e.g., Nexagon) and advanced devices is expanding the range of available options, attracting investment and accelerating market expansion.
Strong Hospital Sector Demand
Hospitals remain the primary end users for PCED treatments due to the complexity of care required, and their strategic investments in new technologies and therapies are significantly boosting market growth.
Increased R&D and Academic-Industry Collaboration
Collaborative efforts between academic institutions and industry players are fostering open innovation, leading to the development of new medicines and devices specifically targeting persistent corneal epithelial defects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How does COVID-19 Impact the global Persistent Corneal Epithelial Defects (PCEDs) market?
Which is the leading market for Persistent Corneal Epithelial Defects (PCEDs)?
What are the key drivers for the growth of the Persistent Corneal Epithelial Defects (PCEDs) market?
Which is the major segment in Persistent Corneal Epithelial Defects (PCEDs) Market by Treatment?
Which is the major segment in Persistent Corneal Epithelial Defects (PCEDs) Market by distribution channel?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Device
- 1.2.2 Medication
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Home-care
- 1.3.3 Specialty Clinics
- 1.3.4 Others
- 1.4 By Clinical Causes
- 1.4.1 Inflammatory Disease
- 1.4.2 Neurotrophic Keratitis (NK)
- 1.4.3 Epithelial/Limbal Stem Cell Deficiency
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 Base year: USD 2,380.47 million → Forecast year: USD 4,510.60 million
- 2.6 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Persistent Corneal Epithelial Defects (PCEDs) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Persistent Corneal Epithelial Defects (PCEDs) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Persistent Corneal Epithelial Defects (PCEDs) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Persistent Corneal Epithelial Defects (PCEDs) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Persistent Corneal Epithelial Defects (PCEDs) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Persistent Corneal Epithelial Defects (PCEDs) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Persistent Corneal Epithelial Defects (PCEDs) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Persistent Corneal Epithelial Defects (PCEDs) Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: Base year: USD 2,380.47 million → Forecast year: USD 4,510.60 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Persistent Corneal Epithelial Defects (PCEDs) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Device
- 12.3.7.2 Medication
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Home-care
- 12.4.7.3 Specialty Clinics
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Clinical Causes - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inflammatory Disease
- 12.5.7.2 Neurotrophic Keratitis (NK)
- 12.5.7.3 Epithelial/Limbal Stem Cell Deficiency
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Persistent Corneal Epithelial Defects (PCEDs) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Persistent Corneal Epithelial Defects (PCEDs) Geographic Market Outlook
- 14.1 Regional Market Size and Share
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Persistent Corneal Epithelial Defects (PCEDs) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Persistent Corneal Epithelial Defects (PCEDs) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dompé Farmaceutici S.p.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novartis AG
- 18.4 Allergan
- 18.5 Johnson & Johnson Services, Inc.
- 18.6 Bausch Health
- 18.7 Kala Pharmaceuticals
- 18.8 Almirall S.A.
- 18.9 Katena Products Inc.
- 18.10 BioTissue
- 18.11 Ocular Science Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

