
Plant-made vaccine revenue rebuilds after Medicago's exit
The plant-based vaccines market was valued at USD 36.4 million in 2025 and is projected to increase from USD 43.5 million in 2026 to USD 216.1 million by 2035, registering a CAGR of 19.50% during 2025–2035. Demand rests on the speed of leaf-based antigen production, government funding for pandemic-ready capacity and licensed animal vaccines, led by a plant-derived classical swine fever vaccine in South Korea. Asia Pacific held the largest regional share, 36.8% in 2025, on Korean swine vaccine sales and contract work in Thailand. The main commercial change is a reset, because no plant-made human vaccine was on sale in 2025 after Medicago closed in 2023, and the field now waits on a 728-participant Phase 1/2 seasonal flu trial that Aramis Biotechnologies began in February 2026.
What counts as a plant-based vaccine and who pays for it
The market counts money paid for vaccines and vaccine antigens produced in whole plants or plant cell cultures, for people or animals. It includes licensed product sales, today almost entirely veterinary; fees paid to plant-platform service providers to express, purify and supply antigens; and government and partner payments for specific vaccine programs, the largest single pool in 2025.
It excludes plant-made antibodies, enzymes and other therapeutic proteins, vaccines made in yeast, insect, bacterial or mammalian cells, plant-derived adjuvants sold to conventional vaccine makers and basic research grants that buy no services.
Plant-Based Vaccines Market Insights
- The plant-based vaccines market is projected to grow from an estimated USD 43.5 million in 2026 to USD 216.1 million by 2035, a 19.50% CAGR, if a plant-made human vaccine reaches the market.
- Asia Pacific held 36.8% of 2025 value, the largest regional share, on licensed swine fever vaccine sales in South Korea and contract work in Thailand.
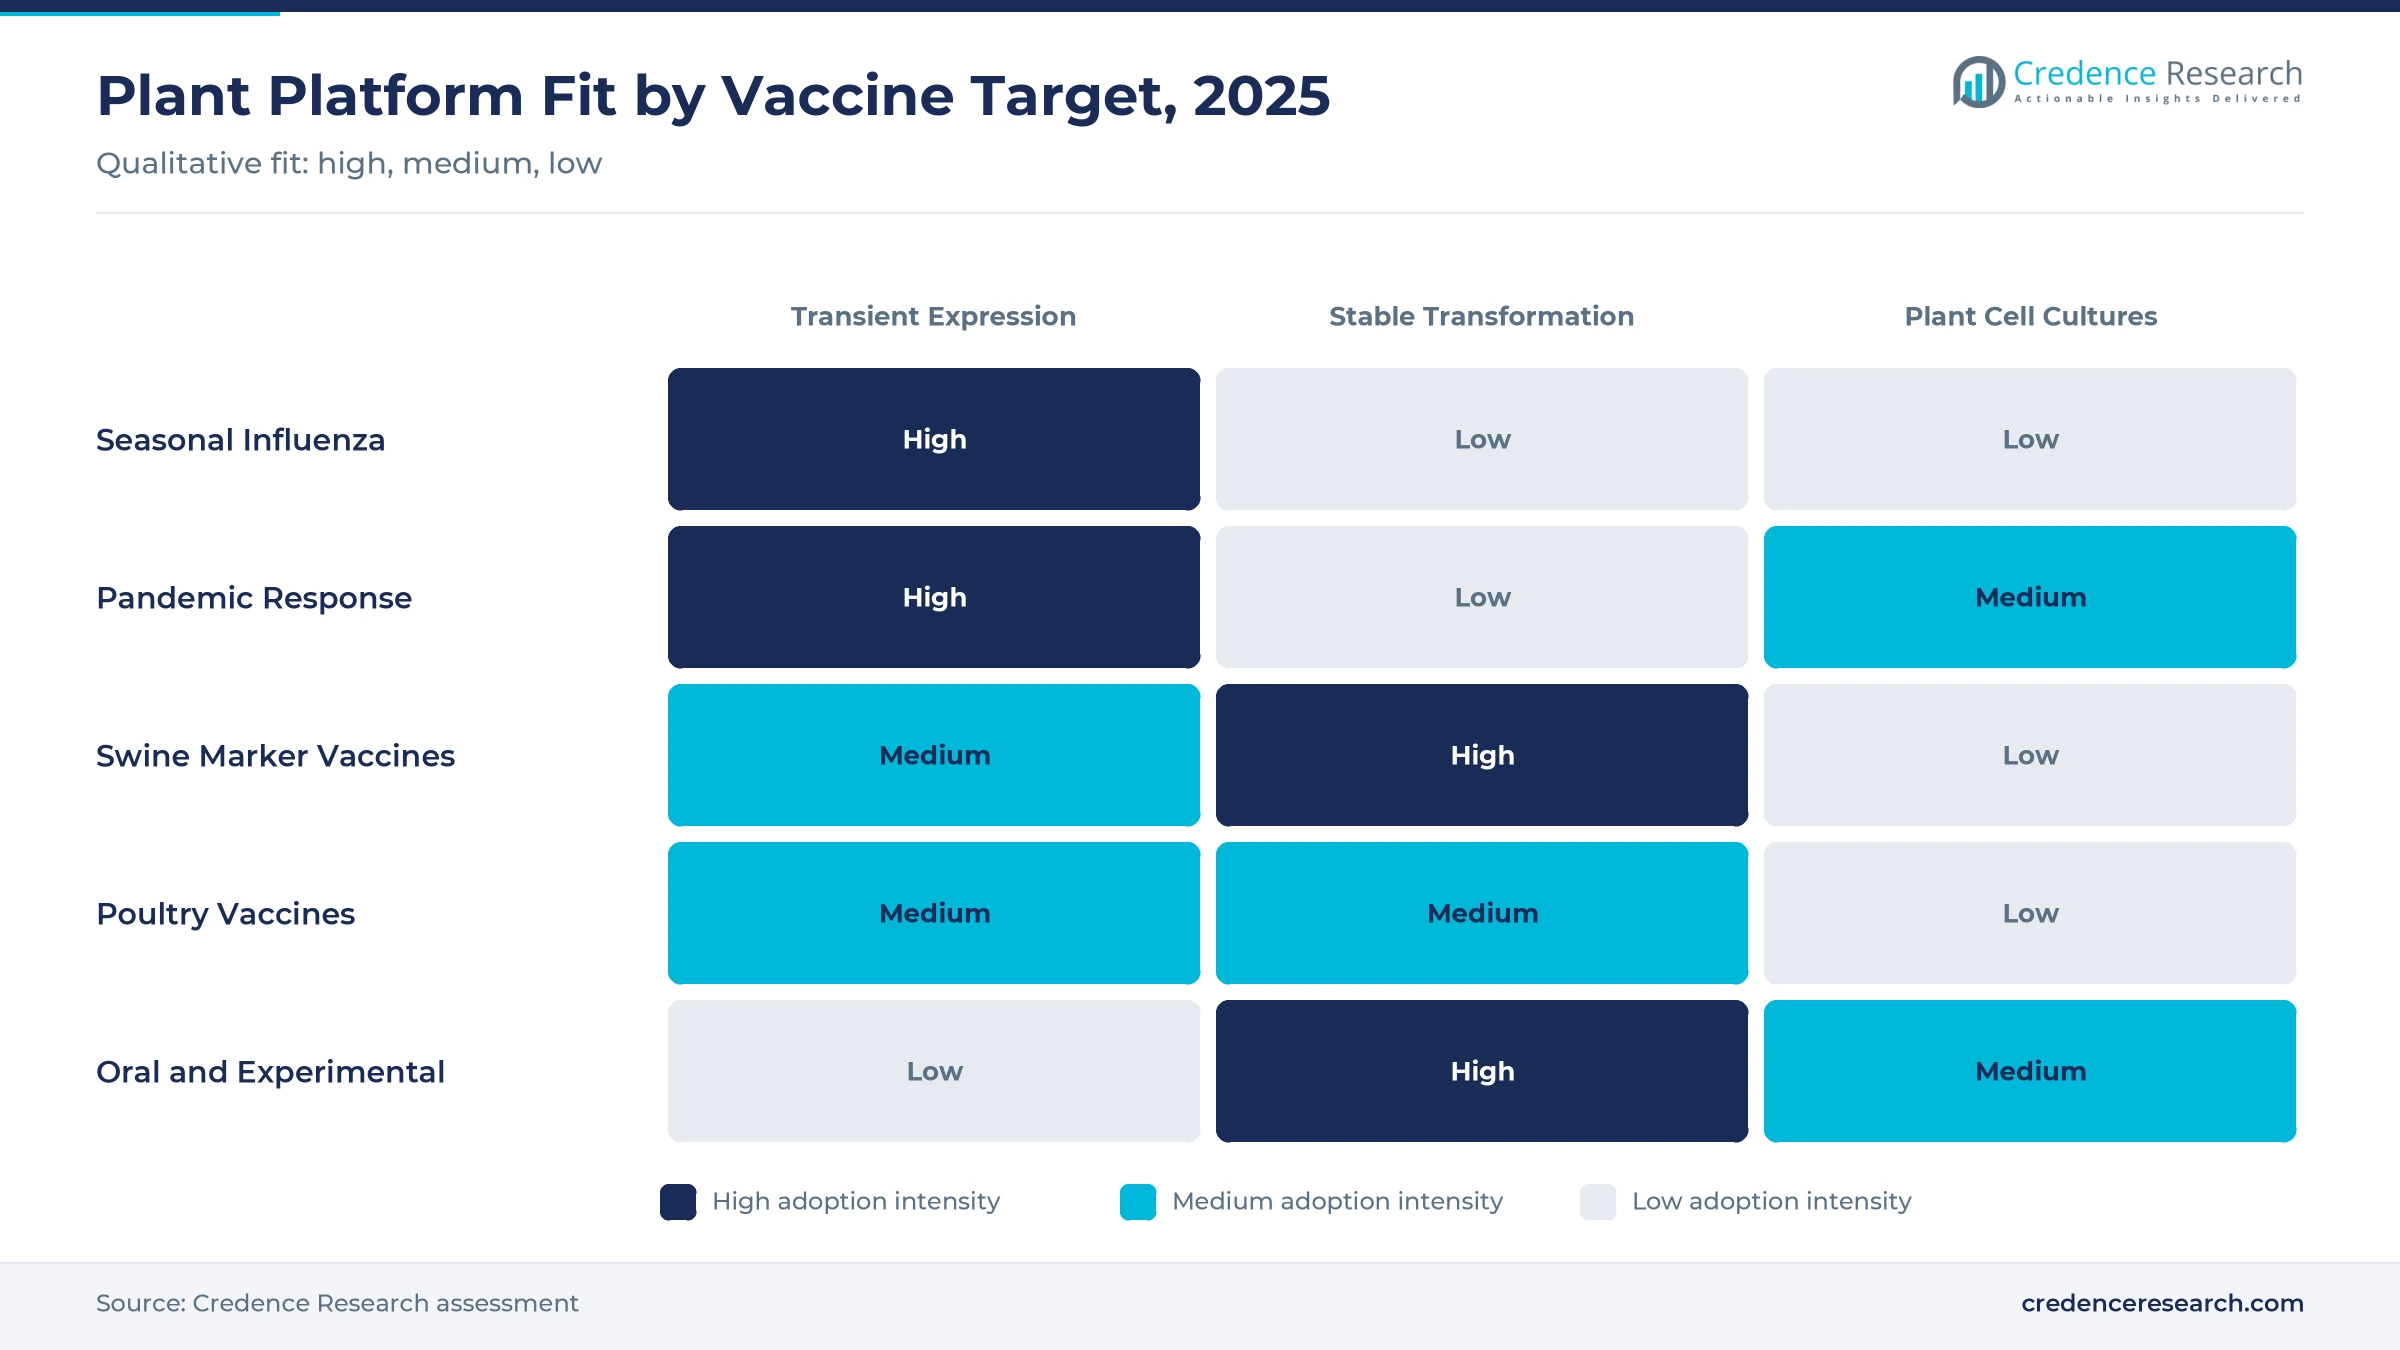
- Transient expression systems accounted for 70.3% of 2025 value, the largest technology, because leaves can make a new antigen within days without a new plant line.
- No plant-made human vaccine was on sale in 2025 after Medicago's 2023 closure, so revenue came from animal vaccines, contract services and funded development.
- Canada announced a Strategic Innovation Fund investment in Aramis in December 2024, and Aramis began a 728-participant Phase 1/2 flu trial in February 2026.
Leaf expression, drug developers and swine subunits lead
Transient expression leads the technology mix and grows fastest
Based on technology, the market is categorized into transient expression systems, stable transformation and plant cell cultures. Transient expression systems led with 70.3% of 2025 value, because the antigen gene is delivered into leaves for a single production run and a new strain needs only a new gene sequence. The same technology grows fastest at 21.01% a year, since Aramis, Leaf Expression Systems, Kentucky BioProcessing and Baiya Phytopharm all build their programs on it.
Drug developers pay the most among end users and increase spending fastest
Based on end-user, the market is categorized into pharmaceutical and biotechnology companies, government agencies, animal health companies and academic and research institutions. Pharmaceutical and biotechnology companies led with 41.2% of 2025 value, paying for antigen development, clinical supply and outsourced sterile steps. They also grow fastest at 23.22% a year as development spending moves toward late-stage trials, while public funding tends to arrive in waves after health emergencies.
Subunit vaccines lead product types while VLP vaccines grow fastest
Based on product type, the market is categorized into subunit vaccines, virus-like particle (VLP) vaccines and other plant-derived vaccines, including oral and experimental formats. Subunit vaccines led with 46.2% of 2025 value, driven by licensed swine fever marker vaccine sales in South Korea. VLP vaccines grow fastest at 22.85% a year, mainly on the strength of the Aramis seasonal influenza program, which builds on the former Medicago VLP platform.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Technology | Transient Expression Systems | 70.3% | Transient Expression Systems | 21.01% |
| By End-User | Pharmaceutical & Biotechnology Companies | 41.2% | Pharmaceutical & Biotechnology Companies | 23.22% |
| By Product Type | Subunit Vaccines | 46.2% | Virus-Like Particle (VLP) Vaccines | 22.85% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fast antigen output, pandemic funding and swine demand
Leaf expression produces a new antigen within days
In a transient expression system, a gene for the target antigen is delivered into leaves of a fast-growing tobacco relative, and the plant makes the protein within days. No virus is grown in eggs or cell tanks, and a new influenza strain needs only a new gene sequence. Leaf Expression Systems licenses its Hypertrans system from the John Innes Centre for vaccines, antibodies and enzymes, and Aramis, Kentucky BioProcessing and Baiya Phytopharm build their own programs on the same method for seasonal flu and outbreak response. That speed is why transient expression grows fastest among technologies through 2035.
Governments fund plant platforms as pandemic insurance
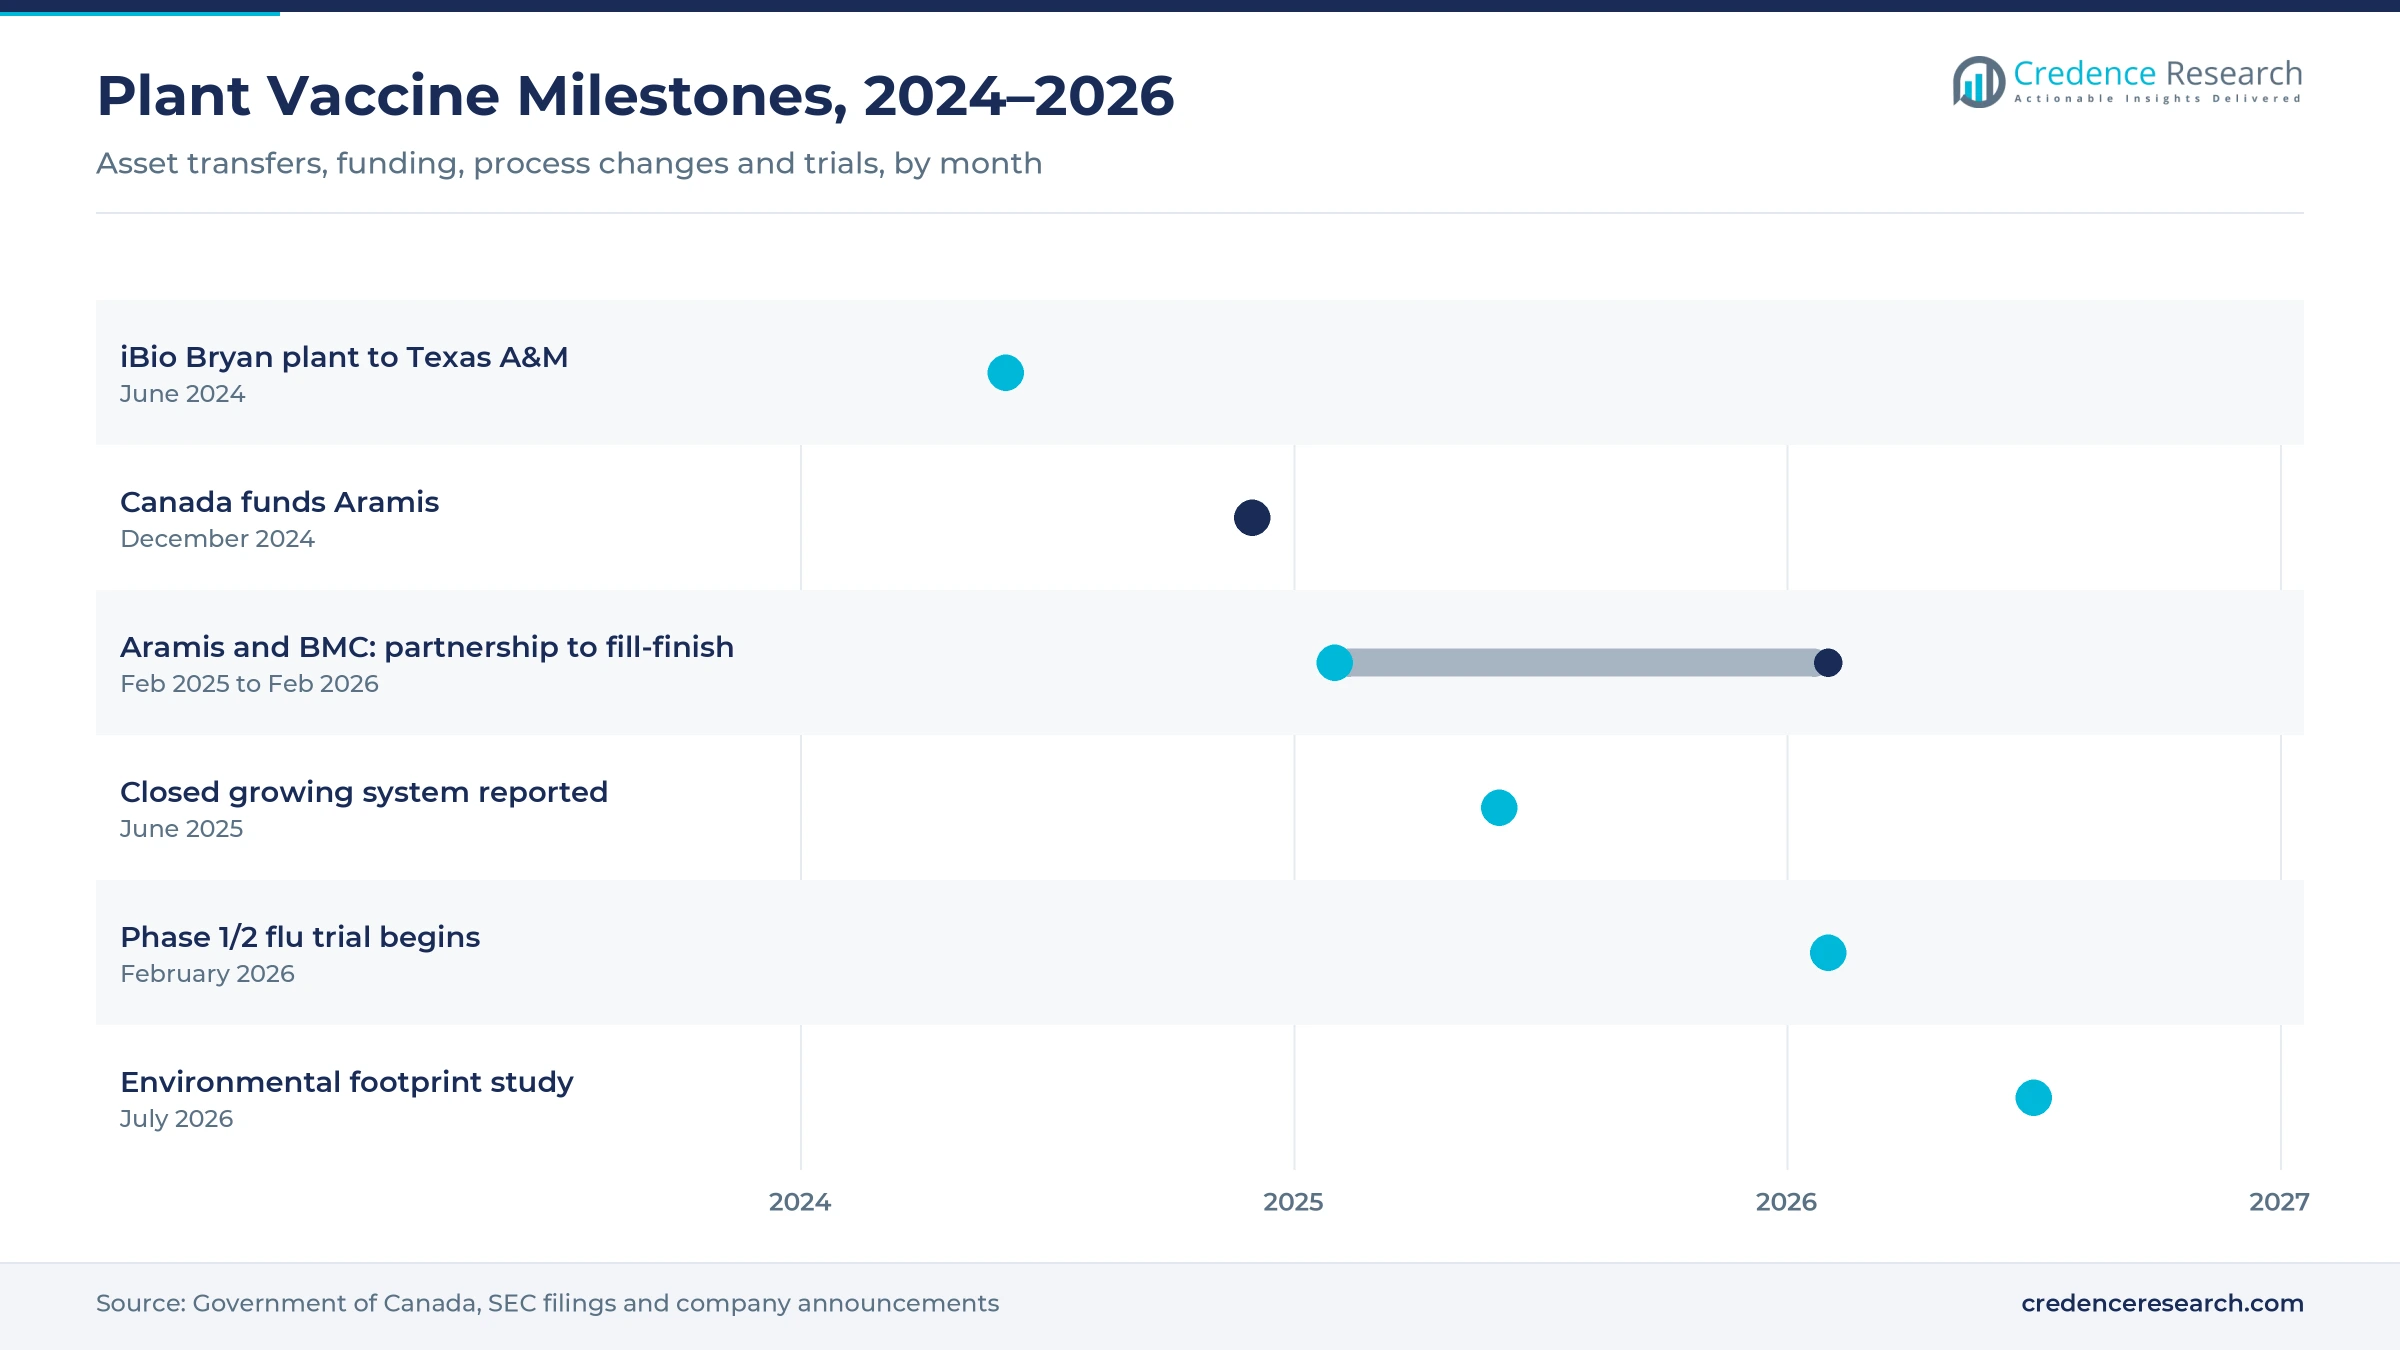
Governments see plant platforms as capacity that can switch to a new antigen without a new factory. On Dec. 5, 2024, the Government of Canada announced a Strategic Innovation Fund investment in Aramis Biotechnologies to optimize its plant-based manufacturing process and take a next-generation seasonal flu vaccine through Phase 2. Public money of this kind is the largest single revenue pool today and helps make North America the fastest-growing region.
Swine marker vaccines give plant platforms a commercial foothold
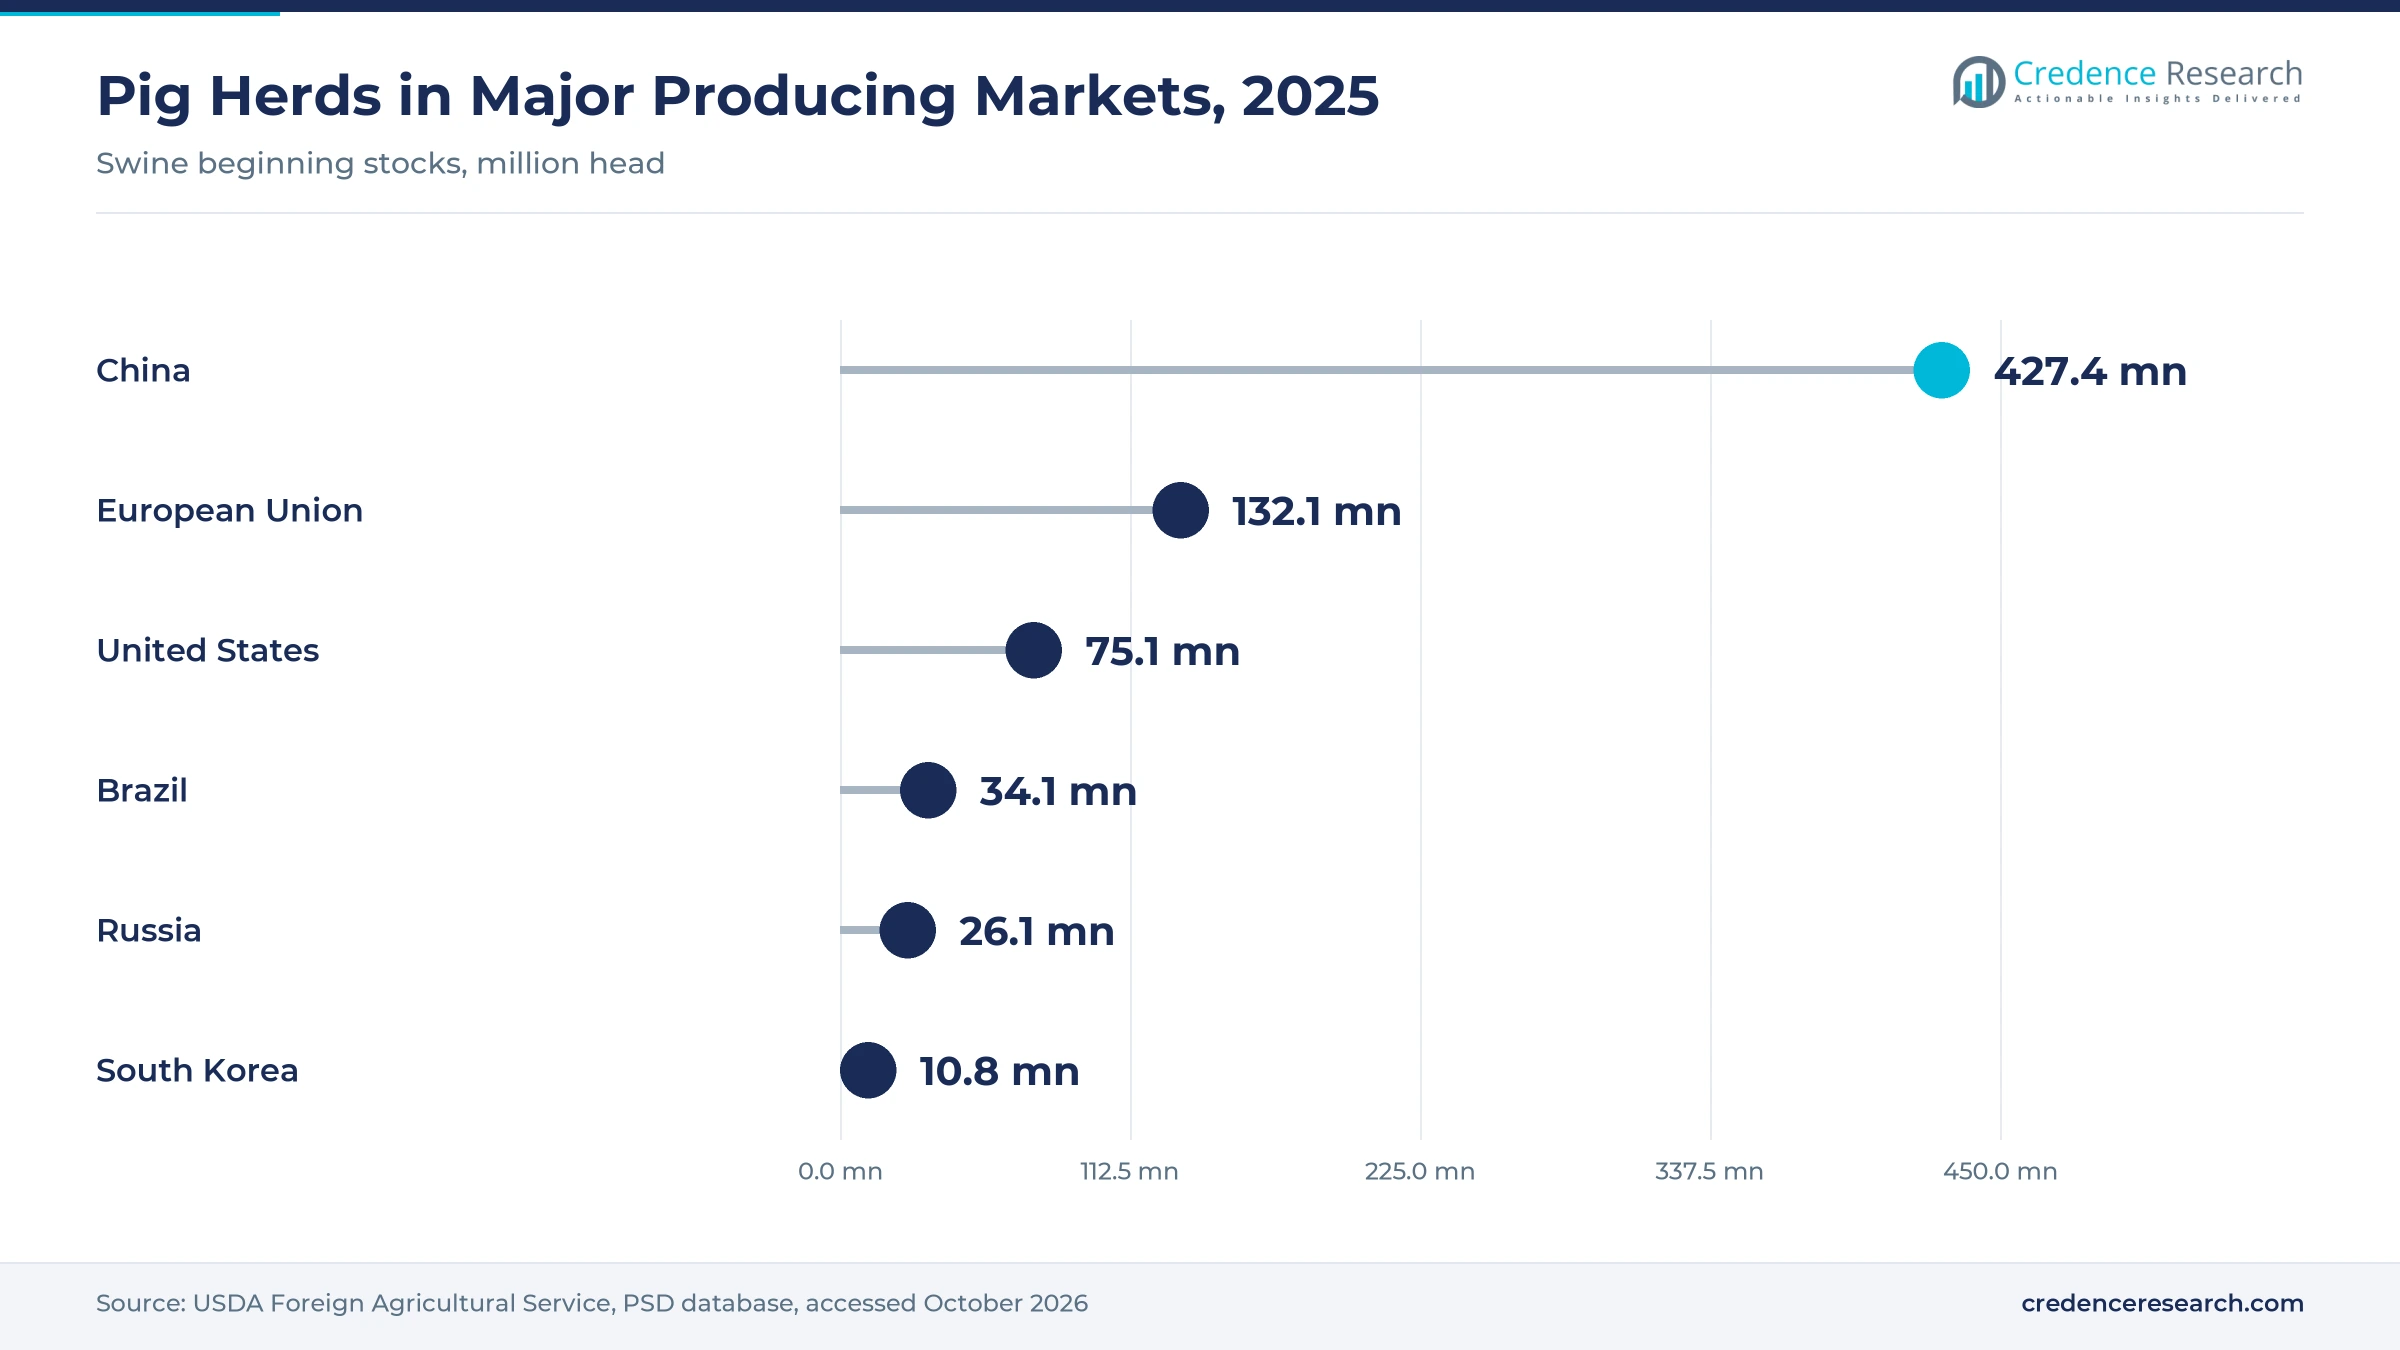
BioApp of Pohang, South Korea, received approval in April 2019 for HERBAVAC CSF Green Marker, described by pig333 as the first plant-derived recombinant subunit vaccine against classical swine fever. It carries the E2 antigen but not the Erns antigen of field virus, so vets can tell vaccinated pigs from infected ones. South Korea began 2025 with about 10.8 million pigs, according to USDA data. That herd underpins licensed product sales, which is why subunit vaccines led product types and why Korean swine sales put Asia Pacific ahead of North America in 2025.
Contract capacity is being rebuilt in Norwich, Bangkok and Texas
Leaf Expression Systems runs a purpose-built plant on Norwich Research Park with growing rooms and protein purification. In Bangkok, Baiya Phytopharm runs what it calls the first cGMP plant-based facility in Asia and sells contract services through Molecular Pharming Solution. In June 2024, the Texas A&M University System acquired iBio's former plant in Bryan, Texas, according to an SEC filing. Contract and development spending bridges the gap to product revenue.
Closed growing rooms and outsourced fill-finish emerge
Production shifts from greenhouses to closed growing rooms
In June 2025, Aramis said it had replaced traditional greenhouses with a proprietary closed, controlled-environment production system and achieved a multifold rise in plant protein productivity. Consistent biomass is the hardest part of plant manufacturing to prove to a regulator, so Credence Research expects closed systems to become the norm for human vaccine work by 2030. In July 2026, Aramis also launched a study with CIRAIG, Premier Tech and CRIBIQ on the environmental footprint of plant bioproduction.
Plant developers outsource sterile fill-finish
Small developers keep antigen expression in-house and buy the sterile steps. Aramis announced a partnership with the non-profit Biologics Manufacturing Centre in February 2025, and on Feb. 10, 2026, the two completed formulation, aseptic fill-finish and clinical packaging of the flu candidate, according to BIOTECanada. The same split is common across vaccine contract manufacturing, and it lets plant developers reach the clinic without building their own sterile lines.
A plant-made flu vaccine for adults 65 and over offers an opportunity
Aramis Biotechnologies began a randomized Phase 1/2 trial of its trivalent, plant-made seasonal influenza vaccine on Feb. 26, 2026, enrolling 728 healthy volunteers at seven sites across Canada and comparing it with commercial vaccines for adults aged 18 to 64 and 65 and over. Older-adult flu shots are a large, repeat purchase, so VLP vaccines stand to grow fastest among product types if the data hold.
Marker subunit vaccines for the largest pig herds open an opportunity
Marker vaccines that tell infection from vaccination support eradication programs and export status, which live attenuated vaccines cannot. USDA data show China began 2025 with about 427.4 million pigs, the European Union 132.1 million, the United States 75.1 million and Brazil 34.1 million. Plant-made subunits face a shorter, cheaper approval path than human vaccines, so swine and poultry antigens offer near-term product revenue for platform owners while human programs mature.
Medicago's exit, batch consistency and a thin pipeline
Medicago's closure showed an authorized vaccine is not a business
Medicago's Covifenz became the first COVID-19 vaccine using plant-based protein technology when the Health Canada authorized it on Feb. 24, 2022, for adults aged 18 to 64, after trials showed 71% efficacy against symptomatic infection. In February 2023, Mitsubishi Chemical Group began winding Medicago down, citing reduced demand for COVID-19 vaccines and scale-up challenges. Investors now ask who buys and whether supply is reliable, so developers target repeat-purchase vaccines such as seasonal flu.
Batch consistency remains the main scale-up risk
Plant biomass varies with light, temperature and handling, and each batch has to match the last for regulators. Aramis says its clinical-scale, GMP-compliant process is already enough for a commercial launch without further scale-up. Credence Research treats that as a claim to be proven in Phase 3 and commercial supply, not a settled fact. Closed growing rooms, tighter process controls and outsourced sterile steps are the main ways developers reduce the risk before filing.
A second human approval is unlikely before 2030
The only active human program Credence Research tracks toward late-stage development is a Phase 1/2 flu trial that began in 2026. Allowing for Phase 3 and regulatory review, Credence Research does not expect a plant-made human vaccine on sale before 2030, so product revenue stays small for half of the forecast period. Developers bridge the gap with contract work, animal vaccines and public funding, but each delay pushes revenue and investor patience further out.
Platform owners divert plant capacity to antibodies and other proteins
iBio's sale of its Bryan plant completed a shift toward antibody discovery, Kentucky BioProcessing describes a pipeline of antibodies and vaccines, and Baiya sells growth factors through BGF Plantrix. That diversification keeps facilities busy but thins the vaccine pipeline. History also adds caution, because the USDA approved a Dow AgroSciences plant-cell vaccine production system in 2006, yet no large plant-cell vaccine line followed. Clear late-stage data and dedicated vaccine funding are the main remedy.
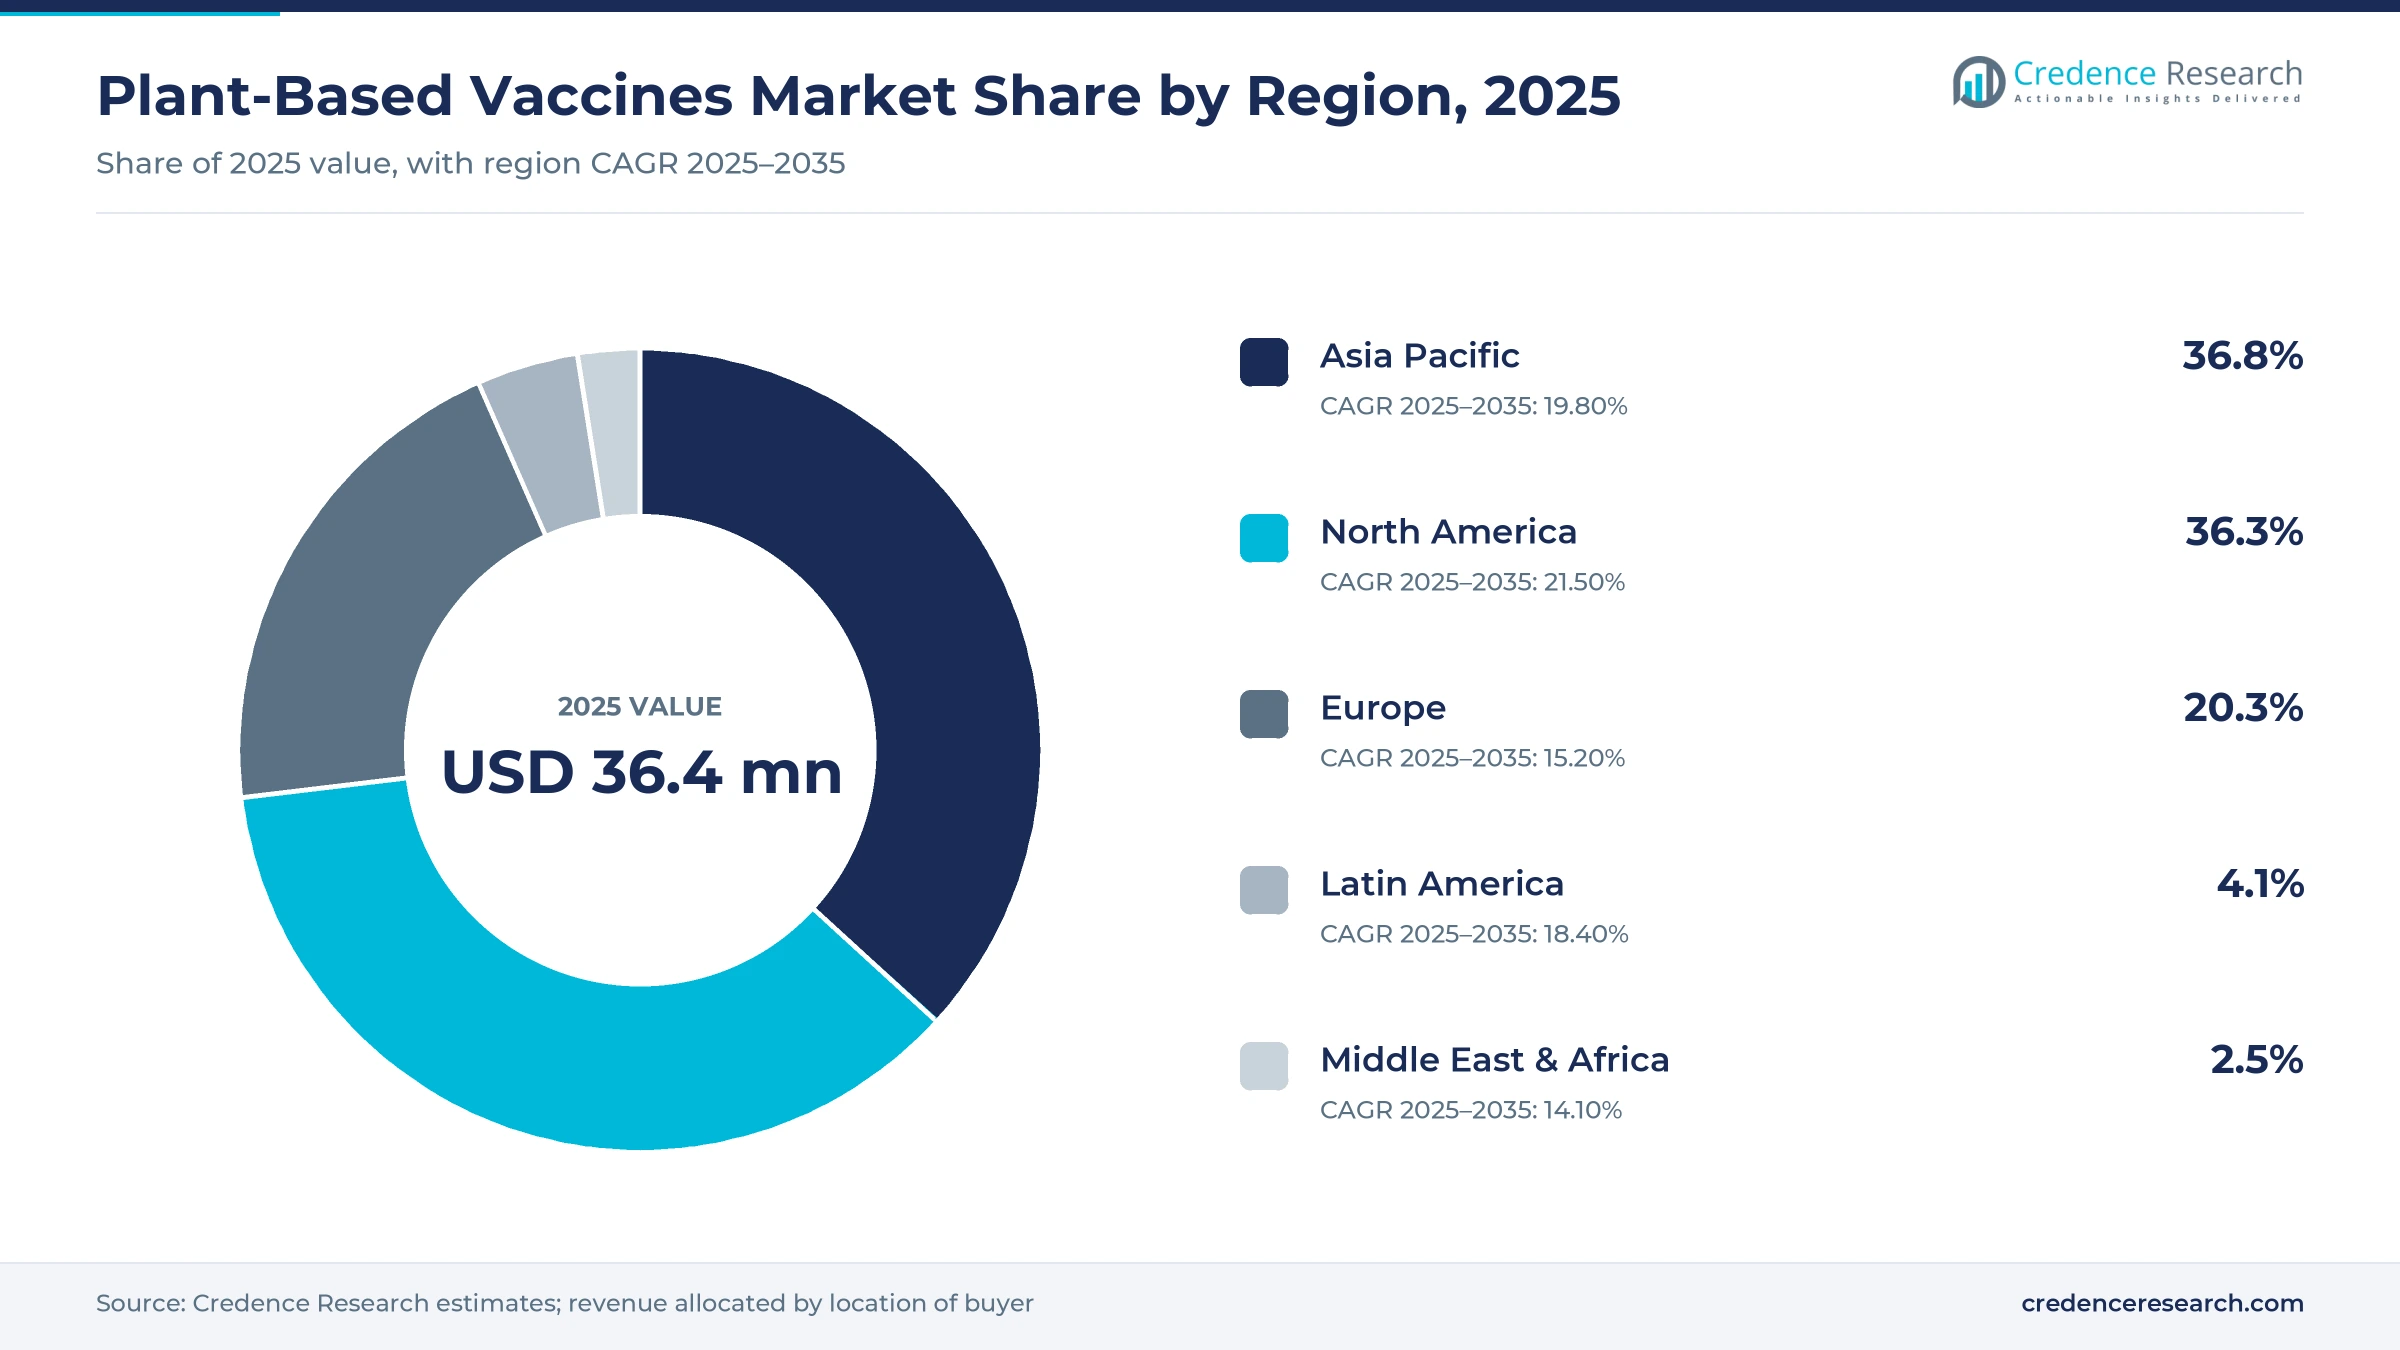
Korean swine sales edge Asia Pacific past North America
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Asia Pacific | 36.8% | 19.80% |
| North America | 36.3% | 21.50% |
| Europe | 20.3% | 15.20% |
| Latin America | 4.1% | 18.40% |
| Middle East & Africa | 2.5% | 14.10% |
Asia Pacific leads on Korean swine vaccine sales and Thai contract services
Asia Pacific held 36.8% of 2025 value and grows at 19.80% a year. Licensed swine fever vaccine sales by BioApp in South Korea and contract and development work at Baiya Phytopharm in Thailand make up most of it. Baiya signed a memorandum of understanding with Japan's KAICO on protein expression services in October 2025. Its PIC/S-compliant site gives regional governments a route to domestic vaccine capacity without a large mammalian-cell plant.
North America relies on Canada for the human vaccine pipeline
North America held 36.3% of 2025 value and is the fastest-growing region at 21.50% a year. Canada carries the human vaccine pipeline through Aramis, which launched in December 2023 with Medicago's research assets and pilot facility in Quebec City. The United States hosts Kentucky BioProcessing and the former iBio plant now owned by Texas A&M. A first approval of a plant-made flu vaccine would most likely land in this region first.
Europe earns from contract expression rather than product sales
Europe held 20.3% of 2025 value and grows at 15.20% a year. The United Kingdom's Leaf Expression Systems is the main contract provider, backed by plant science at the John Innes Centre. Credence Research sees little human vaccine product revenue in the region before 2035. Large pig herds in the European Union offer a later opening for plant-made marker vaccines once developers secure veterinary registrations country by country across the bloc.
Latin America has large pig and poultry sectors that await registrations
Latin America held 4.1% of 2025 value and grows at 18.40% a year. Large pig and poultry sectors in Brazil, Mexico and Argentina make the region a natural market for plant-made animal vaccines once local registrations clear.
Middle East & Africa builds research partnerships and long-run manufacturing plans
The Middle East & Africa held 2.5% of 2025 value and grows at 14.10% a year. Demand today is limited to research partnerships, while regional vaccine-manufacturing plans give plant platforms a long-run opening.
A Canadian flu trial, public funding and asset transfers
| Development | Status and market relevance |
|---|---|
| In July 2026, Aramis launched a study with CIRAIG, Premier Tech and CRIBIQ on the environmental footprint of plant-based bioproduction. | Under way. Could add a sustainability case to speed in public tenders. |
| In February 2026, Aramis began a randomized Phase 1/2 trial of its plant-made trivalent seasonal flu vaccine in 728 volunteers at 7 Canadian sites. | Enrolling. The only active human trial of a plant-made vaccine Credence Research tracks. |
| In October 2025, Baiya Phytopharm signed a memorandum of understanding with KAICO of Japan on protein expression services. | Signed. Widens Baiya's contract service reach in Asia. |
| In December 2024, the Government of Canada announced a Strategic Innovation Fund investment in Aramis Biotechnologies. | Announced. Public money backs Canada's plant vaccine platform through Phase 2. |
| In June 2024, the Texas A&M University System acquired iBio's Bryan, Texas, manufacturing facility. | Completed. Ended iBio's role in plant-based contract manufacturing. |
Leaf expression, controlled growing and marker antigens
- Transient expression delivers genes into leaves of a tobacco relative and yields antigen within days, suited to seasonal flu and outbreak response.
- Controlled growing in closed, controlled-environment rooms replaces greenhouses to keep biomass and antigen yield consistent from batch to batch.
- VLP antigens are plant-made virus-like particles that mimic a virus shell without genetic material, the basis of the former Medicago platform and the Aramis flu candidate.
- Marker subunits, subunit antigens such as E2 without Erns, let vets separate vaccinated from infected animals, supporting eradication and trade.
- Outsourced sterile steps such as formulation and aseptic fill-finish at partners like the Biologics Manufacturing Centre cut capital needs for small developers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Few platform developers and contract providers compete
Few companies compete in plant-based vaccines, and most are small. Developers with their own programs include Aramis Biotechnologies, which runs the only active human trial Credence Research tracks, Kentucky BioProcessing and Baiya Phytopharm, which has a plant-made COVID-19 candidate in Phase 1. Contract providers include Leaf Expression Systems, which holds rights to sublicense the Hypertrans system, and Baiya's Molecular Pharming Solution. The Biologics Manufacturing Centre is not a plant platform but performs sterile fill-finish for plant-made candidates. BioApp owns the clearest licensed product, while Medicago, iBio and Dow AgroSciences have left vaccine production. Credence Research estimates that the 5 largest participants hold well over half of 2025 value, because the cost of running GMP plant facilities without product revenue keeps entrants out.
Plant vaccine developers, service providers and former players
| Company | Type | Role in the market |
|---|---|---|
| Aramis Biotechnologies | Platform developer | Plant-made VLP seasonal flu vaccine in Phase 1/2; Medicago assets since December 2023 |
| Kentucky BioProcessing | Platform developer | Plant-based pipeline of antibodies and vaccines for rare and infectious diseases |
| Baiya Phytopharm | Developer and contract provider | Plant-made COVID-19 candidate in Phase 1; contract services via Molecular Pharming Solution |
| Leaf Expression Systems | Contract provider | Hypertrans transient expression; contract development and manufacturing in Norwich |
| BioApp | Product owner | HERBAVAC CSF Green Marker swine fever vaccine approved in South Korea in 2019 |
| Biologics Manufacturing Centre | Fill-finish partner | Sterile fill-finish for the Aramis flu candidate; not a plant platform |
| iBio | Former contract provider | Sold its Bryan, Texas, plant in 2024 and shifted to antibody discovery |
| Medicago | Former developer | Developed Covifenz; wound down from February 2023 |
| Mitsubishi Chemical Group | Former owner | Owned Medicago and ended its operations |
| Dow AgroSciences | Former entrant | USDA-approved plant-cell vaccine system in 2006; no large vaccine line followed |
One approved flu vaccine would reset the plant business
Credence Research's view is that plant-based vaccines remain a platform waiting for its second approved human product, and that a successful plant-made flu vaccine for older adults would reset investor interest more than any funding round. Until then, licensed swine marker vaccines, contract services and public programs carry the market. The main risk is another commercial failure after approval, as happened with Medicago. Investors should watch the Aramis Phase 1/2 readout, batch consistency data and new veterinary registrations in Asia and Latin America.
Revenue pools and filings behind the plant vaccine estimate
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from separate estimates of product sales, contract service fees and funded program spending for each active plant platform, and checked against securities filings, Government of Canada notices and company announcements. Segment and regional splits are Credence Research estimates, while livestock context uses USDA Foreign Agricultural Service herd data.
Flu data and animal marker vaccines set the pace to 2035
Through 2035, plant-based vaccines will shift from development funding toward product revenue, but only if plant-made flu data hold and supply proves reliable. Credence Research expects VLP flu vaccines to drive most human revenue after 2030, while marker subunit vaccines expand in pig and poultry markets across Asia Pacific and Latin America. North America will grow fastest on the strength of the Canadian pipeline. The pace will depend on trial results, regulatory review and whether governments keep funding pandemic-ready plant capacity after 2030.
Frequently Asked Questions
What was the size of the plant-based vaccines market in 2025?
What is the forecast value and CAGR of the plant-based vaccines market?
Is any plant-made human vaccine on sale today?
Which technology leads the plant-based vaccines market?
Which region holds the largest share of the plant-based vaccines market?
Who are the major companies in the plant-based vaccines market?
What is the most important upcoming event for plant-based vaccines?
What challenges could slow the plant-based vaccines market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Transient Expression Systems
- 1.2.2 Stable Transformation
- 1.2.3 Plant Cell Cultures
- 1.3 By End-User
- 1.3.1 Pharmaceutical & Biotechnology Companies
- 1.3.2 Government Agencies
- 1.3.3 Animal Health Companies
- 1.3.4 Academic & Research Institutions
- 1.4 By Product Type
- 1.4.1 Subunit Vaccines
- 1.4.2 Virus-Like Particle (VLP) Vaccines
- 1.4.3 Other Plant-Derived Vaccines
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 36.4 million → 2035: USD 216.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plant-Based Vaccines Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plant-Based Vaccines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plant-Based Vaccines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plant-Based Vaccines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plant-Based Vaccines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plant-Based Vaccines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plant-Based Vaccines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plant-Based Vaccines Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 36.4 million → 2035: USD 216.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plant-Based Vaccines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Transient Expression Systems
- 12.3.7.2 Stable Transformation
- 12.3.7.3 Plant Cell Cultures
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceutical & Biotechnology Companies
- 12.4.7.2 Government Agencies
- 12.4.7.3 Animal Health Companies
- 12.4.7.4 Academic & Research Institutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Subunit Vaccines
- 12.5.7.2 Virus-Like Particle (VLP) Vaccines
- 12.5.7.3 Other Plant-Derived Vaccines
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plant-Based Vaccines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Plant-Based Vaccines Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Plant-Based Vaccines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Plant-Based Vaccines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aramis Biotechnologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kentucky BioProcessing
- 18.4 Baiya Phytopharm
- 18.5 Leaf Expression Systems
- 18.6 BioApp
- 18.7 Biologics Manufacturing Centre
- 18.8 iBio
- 18.9 Medicago
- 18.10 Mitsubishi Chemical Group
- 18.11 Dow AgroSciences
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

