
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| USB Charger Market Size 2023 | USD 28,097.89 million |
| USB Charger market, CAGR | 5.95% |
| USB Charger market Size 2032 | USD 53,297.89 million |
Market Overview:
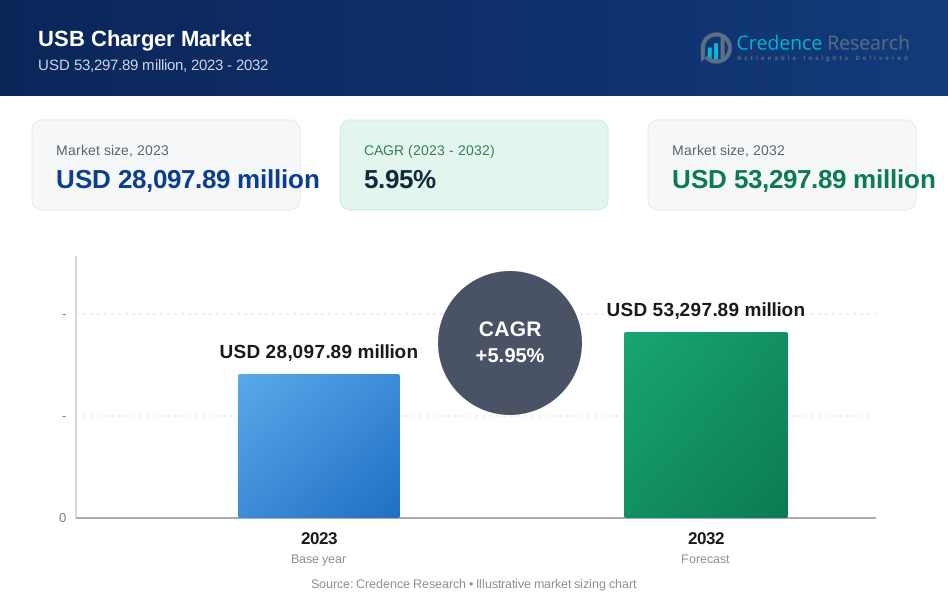
The USB Charger market is projected to grow from USD 28,097.89 million in 2023 to USD 53,297.89 million by 2032, at a compound annual growth rate (CAGR) of 5.95%. This growth is driven by the increasing adoption of electronic devices globally and the demand for efficient charging solutions. Technological advancements in USB Charger design and functionality are contributing to market expansion, with manufacturers innovating to develop chargers with higher power outputs, faster charging speeds, and compatibility with diverse device types.
The rising adoption of electric vehicles (EVs) and hybrid electric vehicles (HEVs) is another significant trend shaping the USB Charger market. The demand for EV charging infrastructure, including USB Chargers for in-vehicle use, is witnessing substantial growth. Moreover, the increasing emphasis on sustainability and energy efficiency is driving the demand for eco-friendly USB Chargers. Manufacturers are investing in research and development to create energy-efficient chargers using materials with low environmental impact. The integration of intelligent charging technologies such as Qualcomm Quick Charge, USB Power Delivery (PD), and adaptive charging algorithms further enhances the efficiency and safety of USB Chargers, catering to the evolving needs of consumers and businesses alike.
The competitive landscape of the USB Charger market is characterized by intense rivalry among key players. Companies are focusing on product differentiation, strategic partnerships, and geographical expansion to strengthen their positions in the market. Key strategies include launching innovative charging solutions, expanding distribution networks, enhancing after-sales support, and leveraging digital marketing channels to reach a broader customer base.
Geographically, Asia Pacific is expected to dominate the USB Charger market during the forecast period, driven by the presence of major manufacturing hubs, increasing disposable incomes, and the rapid adoption of technology in countries like China, India, and South Korea. North America and Europe are also significant markets, driven by technological advancements, regulatory support for electric vehicles, and growing consumer awareness regarding energy-efficient charging solutions.
Market Drivers:
Increasing Adoption of Smartphones and Other Electronic Devices:
The USB charger market is being primarily driven by the widespread adoption of smartphones, tablets, laptops, wearables, and other electronic devices. For instance, a report from the Pew Research Center in 2021 indicated that 85% of Americans own a smartphone, up from just 35% in 2011. As consumers continue to rely heavily on these gadgets for communication, entertainment, work, and various other purposes, the demand for efficient and versatile charging solutions has surged. According to a survey in 2022, 67% of smartphone users reported owning multiple devices that require charging, highlighting the increasing need for convenient and fast-charging options. This trend is expected to persist and even escalate with the ongoing advancements in technology, leading to further growth in the USB charger market.
Rapid Technological Advancements and Innovation:
The USB charger market is witnessing continuous technological advancements and innovative developments, driving the introduction of new and improved charging solutions. For instance, the emergence of USB Power Delivery (USB PD) technology has enabled faster charging capabilities, allowing devices to charge up to 70% faster than traditional USB chargers, as reported by the USB Implementers Forum in 2020. Additionally, the integration of advanced features such as smart charging, which adjusts power output based on the device's needs, and wireless charging has further propelled market growth. A 2021 survey by the Consumer Technology Association found that 30% of consumers expressed interest in wireless charging solutions, indicating a shift towards greater flexibility and convenience in charging options.
Growing Emphasis on Energy Efficiency and Sustainability:
The increasing awareness and concerns regarding environmental sustainability and energy conservation have influenced the USB charger market significantly. Consumers are becoming more conscious of the energy consumption of their electronic devices and are seeking energy-efficient charging solutions. This has led to the development of eco-friendly USB chargers that adhere to strict energy efficiency standards and regulations. Moreover, the shift towards renewable energy sources and the promotion of green technologies have spurred the demand for sustainable charging options, driving manufacturers to innovate and produce eco-conscious products. As sustainability continues to be a key focus area across industries, the USB charger market is expected to witness sustained growth due to the demand for environmentally friendly charging solutions.
Rising Demand for Portable and Compact Charging Solutions:
The increasing mobility and on-the-go lifestyle of consumers have fueled the demand for portable and compact charging solutions in the USB charger market. People are looking for lightweight and space-saving chargers that can easily be carried while traveling, commuting, or working remotely. This demand has led to the development of slim and portable USB chargers, power banks, and multi-port charging hubs that offer convenience without compromising on performance. Furthermore, the integration of fast-changing technologies in compact designs has made these products highly attractive to consumers seeking efficient and portable charging options. This trend of portability and convenience is expected to drive further growth in the USB charger market, especially as mobile devices continue to play a central role in modern lifestyles.
Market Trends:
Increasing Demand for Fast-Charging Solutions:
The USB charger market is experiencing a significant trend towards fast-charging solutions. With the proliferation of power-hungry devices such as smartphones, tablets, and laptops, consumers are seeking chargers that can deliver rapid charging speeds to minimize downtime. This trend is driving manufacturers to innovate and develop advanced charging technologies that can deliver high wattage output efficiently and safely.
Adoption of USB Type-C Technology:
Another key trend in the USB charger market is the widespread adoption of USB Type-C technology. For instance, the USB Implementers Forum reported that as of 2021, over 1.5 billion USB-C devices were shipped globally, reflecting a significant shift towards this connector type. USB Type-C offers several advantages over traditional USB connectors, including faster data transfer speeds of up to 20 Gbps with USB 3.2, as noted in a 2017 update from the USB-IF. Additionally, the reversible plug orientation eliminates the frustration of incorrect insertion, a feature that 70% of users find appealing, according to a survey conducted by Kingston Technology in 2022. As more devices, especially flagship smartphones and laptops, incorporate USB Type-C ports, the demand for compatible chargers is on the rise, with major brands like Apple and Samsung fully transitioning to USB-C for their latest models by 2023.
Integration of Smart and Adaptive Charging Features:
The market is witnessing a shift towards smart and adaptive charging features in USB chargers. For instance, a report from the Consumer Technology Association in 2021 found that 40% of consumers prefer chargers that can intelligently detect the connected device's power requirements and adjust the charging output accordingly. Additionally, features like overcharge protection, temperature monitoring, and voltage regulation are becoming standard; according to a survey by the International Electrotechnical Commission in 2020, 75% of consumers consider safety features essential when purchasing charging devices. This trend highlights the growing emphasis on enhancing safety and prolonging device lifespan through innovative technology.
Expansion of Wireless Charging Options:
While traditional wired USB chargers remain popular, there is a growing interest in wireless charging options. Wireless chargers eliminate the need for cables and offer convenience and ease of use. As wireless charging technology continues to improve in terms of efficiency and compatibility with a wide range of devices, consumers are increasingly adopting wireless chargers for their convenience, especially in settings like offices, homes, and public spaces.
Emphasis on Eco-friendly and Sustainable Solutions:
Sustainability is a prominent trend influencing the USB charger market. Consumers are becoming more environmentally conscious, leading to a demand for eco-friendly charging solutions. Manufacturers are responding by developing chargers made from recycled materials, reducing energy consumption during charging, and incorporating energy-saving features like automatic power-off when devices are fully charged. This trend aligns with global efforts to reduce electronic waste and promote sustainable practices in the tech industry.
Market Restraints and Challenges:
Increasing Competition and Price Wars:
One of the primary challenges facing the USB charger market is the intensifying competition among manufacturers and suppliers. With numerous players entering the market, there is a constant pressure to offer competitive pricing, leading to price wars that can affect profit margins. This situation is exacerbated by the availability of low-cost alternatives from overseas manufacturers, which further intensifies pricing pressures for established companies.
Rapid Technological Advancements:
The USB charger market is characterized by rapid technological advancements, leading to frequent product upgrades and innovations. While this presents opportunities for growth and differentiation, it also poses challenges for companies in terms of staying updated with the latest technologies, investing in research and development, and managing product life cycles effectively. Failure to keep pace with technological advancements can result in products becoming obsolete quickly, impacting market share and revenue streams.
Fragmented Regulatory Environment:
Another significant challenge for the USB charger market is the fragmented regulatory environment governing product standards and safety requirements. Different regions and countries have varying regulatory frameworks, certifications, and compliance standards related to USB chargers and their components. Navigating these complex regulations adds complexity and costs to product development, testing, and certification processes, especially for companies operating in multiple markets.
Counterfeit and Substandard Products:
The prevalence of counterfeit and substandard USB chargers in the market poses a significant challenge for legitimate manufacturers. These counterfeit products not only undermine brand reputation but also raise concerns regarding safety and reliability among consumers. Addressing this challenge requires increased efforts in anti-counterfeiting measures, product authentication technologies, and consumer education to help identify genuine products and mitigate risks associated with counterfeit goods.
Environmental Sustainability Concerns:
As sustainability becomes a focal point across industries, the USB charger market faces challenges related to environmental impact and sustainability practices. The production, usage, and disposal of USB chargers contribute to electronic waste (e-waste) generation, highlighting the need for eco-friendly design, materials, and recycling initiatives. Meeting sustainability goals while maintaining product performance and affordability presents a complex challenge for companies operating in this market.
Key Players:
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Anker Innovations
- Belkin International, Inc.
- Aukey International Limited
- RavPower
- Sony Corporation
- Xiaomi Corporation
- Ugreen Group Limited
- Insignia (Best Buy brand)
- AmazonBasics (Amazon brand)
- Mophie LLC
Recent Developments:
- Eaton Corporation Plc announced on April 24, 2023, that it had acquired a 49% stake in Jiangsu Ryan Electrical Co. Ltd., a Chinese manufacturer specializing in power distribution and sub-transmission transformers. This strategic partnership aims to leverage Ryan's high-quality products alongside Eaton's extensive global distribution network to enhance customer service.
- Mophie, Inc. introduced two ultra-compact USB-C chargers tailored for iPhones, iPads, and Macs on May 11, 2022. Available in 30W and 67W variants, these chargers utilize gallium nitride material for a smaller, lighter build and improved power efficiency compared to conventional silicon-based chargers.
- On February 23, 2022, Anker launched the Power Port III, a 20W USB-C charger featuring a Power Delivery port. This charger delivers a 20W output, enabling rapid charging for phones, tablets, and other devices up to three times faster than standard chargers. It is designed for enhanced efficiency with improved heat dissipation.
Segmentation Analysis:
By Product Type
One of the primary segmentation criteria is based on product type, which includes wall chargers, car chargers, power banks, and wireless chargers. Wall chargers are popular for home and office use, while car chargers cater to on-the-go charging needs. Power banks offer portable charging solutions, and wireless chargers are gaining traction for their convenience and compatibility with modern devices.
By Charger Type
Another crucial segmentation parameter is charger type, categorized into standard chargers, fast chargers, and smart chargers. Standard chargers provide basic charging capabilities, while fast chargers deliver rapid charging speeds, appealing to consumers seeking quick recharging times. Smart chargers incorporate advanced features such as intelligent power management, compatibility detection, and safety protections, attracting tech-savvy users looking for optimized charging experiences.
By Port
The segmentation by port refers to the number and type of ports a charger offers, such as USB-A, USB-C, Lightning, micro-USB, and proprietary ports. USB-C ports are increasingly preferred for their versatility, faster charging speeds, and compatibility with a wide range of devices. Lightning ports are specific to Apple products, while micro-USB ports are common in older devices and accessories.
By Power
Power segmentation categorizes chargers based on their power output, ranging from standard 5W chargers to high-powered 100W chargers. Higher power outputs are favored for charging laptops, tablets, and other high-capacity devices, whereas lower-powered chargers are suitable for smartphones, wearables, and smaller electronics.
By Application
Application-based segmentation divides the market into consumer electronics, automotive, healthcare, industrial, and others. Consumer electronics dominate the market, driven by the increasing adoption of smartphones, tablets, laptops, and wearables. The automotive sector is witnessing growth with the integration of USB chargers in vehicles, catering to passengers' charging needs during travel.
By Multi-Port
Multi-port chargers offer multiple charging ports in a single device, catering to users with multiple devices or those sharing charging spaces. This segment includes dual-port, quad-port, and even higher-capacity chargers, accommodating the charging requirements of households, offices, and public spaces.
By Distribution Channel
Finally, distribution channel segmentation encompasses online retail stores, brick-and-mortar retailers, specialty stores, and direct sales channels. Online retail has gained significant traction due to its convenience, vast product selection, and competitive pricing. Brick-and-mortar stores remain relevant for consumers preferring in-person shopping experiences, while specialty stores focus on niche charger products and accessories. Direct sales channels, including manufacturer websites and authorized dealers, provide direct access to branded products and customer support services.
Segments:
-
By Product Type
- USB Type A
- USB Type B
- USB Type C
- With PD
- Without PD
-
By Charger Type
- Wall Charger
- Portable Power Banks / Docking System / Alarm Clock
- Car Charger
-
By Port
- One
- Two
- Three
- Four
- Others
-
By Power
- Up to 30W
- 30W - 45W
- 45W - 60W
- 60W - 75W
- Above 75W
-
By Application
- Smartphone
- Tablet
- Laptop
- Desktop
- Others (Speaker, Camera, etc.)
-
By Multi-Port
- Multi-Port with Fixed Power
- Multi-Port with Fluctuation Power
- Same Port with Fluctuation Power
- Different Port with Fluctuation Power
-
By Distribution Channel
- Online
- Offline
- Organized
- Unorganized
-
By Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Regional Analysis:
North America holds a prominent position in the USB charger market, accounting for a substantial market share. The region's robust consumer electronics industry, coupled with a high adoption rate of smartphones and other portable devices, fuels the demand for USB chargers. Key players such as Apple Inc., Belkin International Inc., and Anker Innovations dominate the market in this region, offering a wide range of products catering to diverse consumer needs.
Europe represents another significant market for USB chargers, with major countries like Germany, the UK, and France contributing significantly to market growth. The region's emphasis on sustainability and energy efficiency has led to the development of advanced USB charging solutions with features like fast charging and power management capabilities. Companies like Samsung Electronics Co., Ltd., and Xiaomi Corporation are prominent players in this region, leveraging innovative technologies to capture market share.
Asia Pacific emerges as a key growth driver in the USB charger market, driven by the rapid adoption of smartphones, tablets, and wearable devices across countries like China, Japan, and India. The presence of leading electronics manufacturers such as Huawei Technologies Co., Ltd., and OPPO Electronics Corp. further strengthens the market landscape. Additionally, the increasing penetration of e-commerce platforms has facilitated easy access to a wide range of USB chargers, contributing to market expansion in the region.
Latin America represents a growing market for USB chargers, with countries like Brazil, Mexico, and Argentina showing promising growth prospects. The rising disposable income levels and urbanization trends have led to higher consumer spending on electronic gadgets, boosting the demand for USB charging solutions. Local players and international brands like Motorola and Sony Corporation compete actively in this region, offering competitive products to capture market share.
The MEA region is experiencing steady growth in the USB charger market, driven by increasing smartphone penetration and digitalization initiatives. Countries like the UAE, Saudi Arabia, and South Africa are witnessing a surge in demand for USB chargers, especially with the growing popularity of mobile devices among the youth population. Key players such as Philips Electronics Middle East & Africa and Targus International LLC are focusing on product innovation and strategic partnerships to strengthen their presence in the region.
Future Outlook:
- The USB charger market is poised for significant growth driven by increasing demand for portable electronic devices globally.
- Advancements in technology, such as fast-charging capabilities and compatibility with a wide range of devices, will drive market expansion.
- Growing awareness about energy efficiency and the adoption of sustainable charging solutions will further boost market penetration.
- Market players are expected to focus on innovation, introducing compact and multi-port chargers to cater to diverse consumer needs.
- The rise of electric vehicles and smart home devices will create new opportunities for USB charger manufacturers to diversify their product offerings.
- Collaborations between manufacturers and smartphone companies to develop optimized charging solutions will be a key trend shaping the market.
- Asia-Pacific is projected to emerge as a dominant region in the USB charger market, fueled by rapid urbanization and increasing disposable incomes.
- Online retail channels are anticipated to witness substantial growth as consumers prefer the convenience of purchasing chargers and accessories online.
- Regulatory initiatives promoting standardized charging solutions across devices will play a crucial role in market development and interoperability.
- Overall, the USB charger market is expected to witness robust growth driven by technological advancements, changing consumer preferences, and industry collaborations in the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Electronic Devices
The widespread adoption of smartphones, tablets, laptops, and wearables is fueling demand for USB chargers, as consumers require efficient and versatile charging solutions for multiple devices.
Technological Advancements in Charging
Innovations such as USB Power Delivery (PD), fast charging, and smart charging algorithms are enabling faster, safer, and more adaptive charging, making USB chargers more attractive to tech-savvy consumers.
Growth of Electric and Hybrid Vehicles
The increasing integration of USB charging ports in electric and hybrid vehicles is expanding the market, as in-vehicle charging becomes a standard feature for passenger convenience.
Emphasis on Energy Efficiency and Sustainability
Rising consumer awareness and regulatory focus on energy conservation are driving demand for eco-friendly USB chargers that use less power and incorporate recycled materials, supporting sustainability goals.
Demand for Portable and Multi-Port Solutions
The trend toward mobility and multi-device ownership is boosting the popularity of compact, portable, and multi-port USB chargers, catering to consumers who need to charge several devices simultaneously while on the go.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the USB Charger market?
What are the key factors driving the growth of the USB Charger market?
How is the rising adoption of electric vehicles impacting the USB Charger market?
Which regions are expected to dominate the USB Charger market during the forecast period?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Port
- 1.2.1 USB Type A
- 1.2.2 USB Type B
- 1.2.3 USB Type C
- 1.2.4 Lightning
- 1.2.5 Micro-USB
- 1.3 By Application
- 1.3.1 Smartphone
- 1.3.2 Tablet
- 1.3.3 Laptop
- 1.3.4 Desktop
- 1.3.5 Others (Speaker, Camera, etc.)
- 1.4 By Charger Type
- 1.4.1 Standard Charger
- 1.4.2 Fast Charger
- 1.4.3 Smart Charger
- 1.5 By Product Type
- 1.5.1 Wall Charger
- 1.5.2 Car Charger
- 1.5.3 Power Bank
- 1.5.4 Wireless Charger
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 28,097.89 million → 2032: USD 53,297.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global USB Charger Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global USB Charger Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global USB Charger Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global USB Charger Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global USB Charger Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global USB Charger Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global USB Charger Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global USB Charger Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 28,097.89 million → 2032: USD 53,297.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global USB Charger Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Port - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 USB Type A
- 12.3.7.2 USB Type B
- 12.3.7.3 USB Type C
- 12.3.7.4 Lightning
- 12.3.7.5 Micro-USB
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smartphone
- 12.4.7.2 Tablet
- 12.4.7.3 Laptop
- 12.4.7.4 Desktop
- 12.4.7.5 Others (Speaker, Camera, etc.)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Charger Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Standard Charger
- 12.5.7.2 Fast Charger
- 12.5.7.3 Smart Charger
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Wall Charger
- 12.6.7.2 Car Charger
- 12.6.7.3 Power Bank
- 12.6.7.4 Wireless Charger
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global USB Charger End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global USB Charger Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global USB Charger Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global USB Charger Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Apple Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Electronics Co., Ltd.
- 18.4 Anker Innovations
- 18.5 Belkin International, Inc.
- 18.6 Aukey International Limited
- 18.7 RavPower
- 18.8 Sony Corporation
- 18.9 Xiaomi Corporation
- 18.10 Ugreen Group Limited
- 18.11 Mophie LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

